
 US Esters Market | 2026-2036
US Esters Market Size, Share, and Industry Trends Forecast 2026-2036
US Esters Market Intelligence
Buyer concentration in the US esters market is shifting as large chemical manufacturers consolidate procurement while mid-sized cosmetic brands fragment demand across specialty suppliers. Eastman Chemical Company leverages its integrated Kingsport, Tennessee manufacturing complex to dominate high-purity alkyl ester output for coatings and personal care. Stepan Company anchors the Midwest with surfactant-linked ester production serving household and industrial cleaning end users. Dow Chemical Company extends its Gulf Coast petrochemical position into plasticizer-grade esters for construction and automotive compounds.
Esters are organic compounds formed by condensation of an acid and an alcohol, typically characterized by boiling points between 50°C and 300°C and solubility profiles tunable through carbon chain length modification; they function primarily as solvents, plasticizers, lubricity agents, and emollients across industrial and consumer formulations. Fatty acid esters command the largest volume pool in personal care applications where bio-derived feedstocks support premium positioning. Glycol esters represent the fastest-expanding structural category as water-based coating formulations displace solvent-borne systems under volatile organic compound restrictions. Alkyl esters remain mature in lubricant basestocks, with margin concentration shifting toward Group V synthetics for electric vehicle thermal management fluids.
The EPA regulates ester solvents under the Toxic Substances Control Act, while the FDA governs food-contact and cosmetic-grade esters through 21 CFR specifications, and OSHA sets permissible exposure limits for manufacturing environments; together these frameworks elevate compliance costs for imported material and favor domestic producers with established testing protocols. State-level California Proposition 65 labeling requirements add another layer of formulation scrutiny for consumer-facing applications. Stakeholders must monitor feedstock volatility between petroleum-derived and plant-based alcohols as carbon intensity accounting reshapes procurement criteria.
Market Dynamics
Feedstock bifurcation between petroleum-derived and plant-based alcohols is fragmenting procurement strategies as carbon accounting reshapes supplier selection criteria across personal care and industrial coatings.
Growth Catalysts
- EPA Safer Choice program:Formulators seeking preferred chemical status are accelerating bio-based ester substitution in household cleaning products, expanding volume pull through retail channels.
- Water-borne coating systems:Architectural and automotive refinish sectors are absorbing glycol ester plasticizers as VOC restrictions tighten in California and Northeast corridor states.
- Texas-Louisiana petrochemical corridor:Integrated oleochemical processing clusters are capturing margin expansion from domestic feedstock security and reduced import dependency.
Market Restraints
- Palm and coconut oil price volatility:Fatty acid ester producers face margin compression when tropical feedstock harvests disrupt plant-based alcohol supply chains.
- FDA 21 CFR compliance burden:Food-contact and cosmetic-grade certification timelines extend 18-24 months, freezing new entrants from rapid market penetration.
- Polyether polyol substitution:Polyurethane foam manufacturers are partially displacing ester polyols in insulation applications during crude oil price troughs.
Strategic Opportunities
- Electric vehicle thermal management fluids:Group V synthetic ester basestocks are capturing formulation trials as OEMs redesign battery cooling architectures.
- Mid-Atlantic cosmetic brand clusters:Specialty alkyl ester suppliers are establishing direct technical service relationships with indie personal care formulators in New Jersey and Pennsylvania.
- USDA BioPreferred procurement mandates:Federal purchasing preferences are creating guaranteed offtake channels for certified bio-based emollients and solvents.
Industry Challenges
- Process analytical chemistry talent scarcity:Gulf Coast producers struggle to hire spectroscopy and chromatography specialists for real-time quality control of high-purity ester streams.
- Legacy batch reactor retrofit costs:Continuous flow chemistry transitions demand $15-40 million per site for Midwest and Southeast manufacturers with aging infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Esters Market |
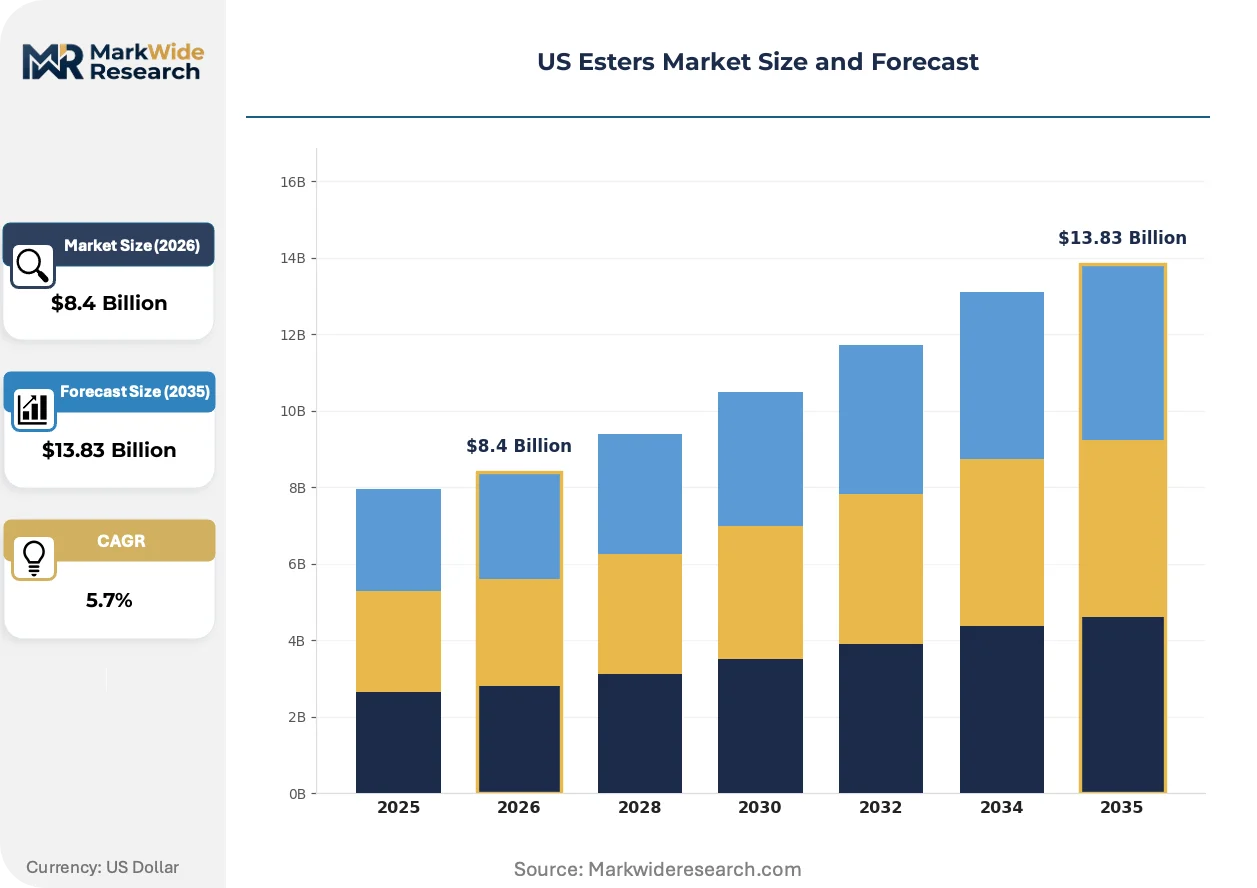
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Esters, Fatty Acid Esters, Glycol Esters, Plasticizers Application: Cosmetics, Coatings, Lubricants, Food Additives End User: Chemical Manufacturers, Pharmaceutical Companies, Food Producers, Cosmetic Brands Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Eastman Chemical Company, Evonik Industries AG, BASF SE, Procter & Gamble, Archer Daniels Midland Company, Sasol Limited, Stepan Company, PCC Chemax Inc., Dow Chemical Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Esters Market Strategic Shifts & Innovations
Bio-fermentation pathways for branched alcohol precursors are collapsing the traditional oleochemical value chain, enabling domestic producers to bypass tropical feedstock dependencies entirely.
Enzymatic transesterification is decentralizing ester production scale economics. Specialty chemical houses in Ohio and North Carolina are deploying immobilized lipase reactors for small-batch, high-molecular-weight esters serving pharmaceutical and fragrance end uses. This distributed manufacturing model is compressing minimum efficient scale thresholds and enabling regional suppliers to challenge Gulf Coast volume producers on lead time and customization.
California Proposition 65 warning label requirements are forcing reformulation transparency across personal care supply chains. Brands selling into the state must disclose trace contaminant profiles, pushing ester suppliers to invest in supercritical fluid purification and expanded substance testing protocols. The compliance burden is accelerating supplier consolidation as smaller compounders lack analytical capabilities.
Direct raw material sourcing by cosmetic formulators is shortening traditional distributor channels. Indie brands in Brooklyn and Los Angeles are contracting directly with fatty acid ester manufacturers for custom carbon chain distributions, bypassing regional chemical distributors. This disintermediation is compressing margin pools for mid-tier traders while rewarding producers with technical service capabilities.
US Esters Market Segmentation
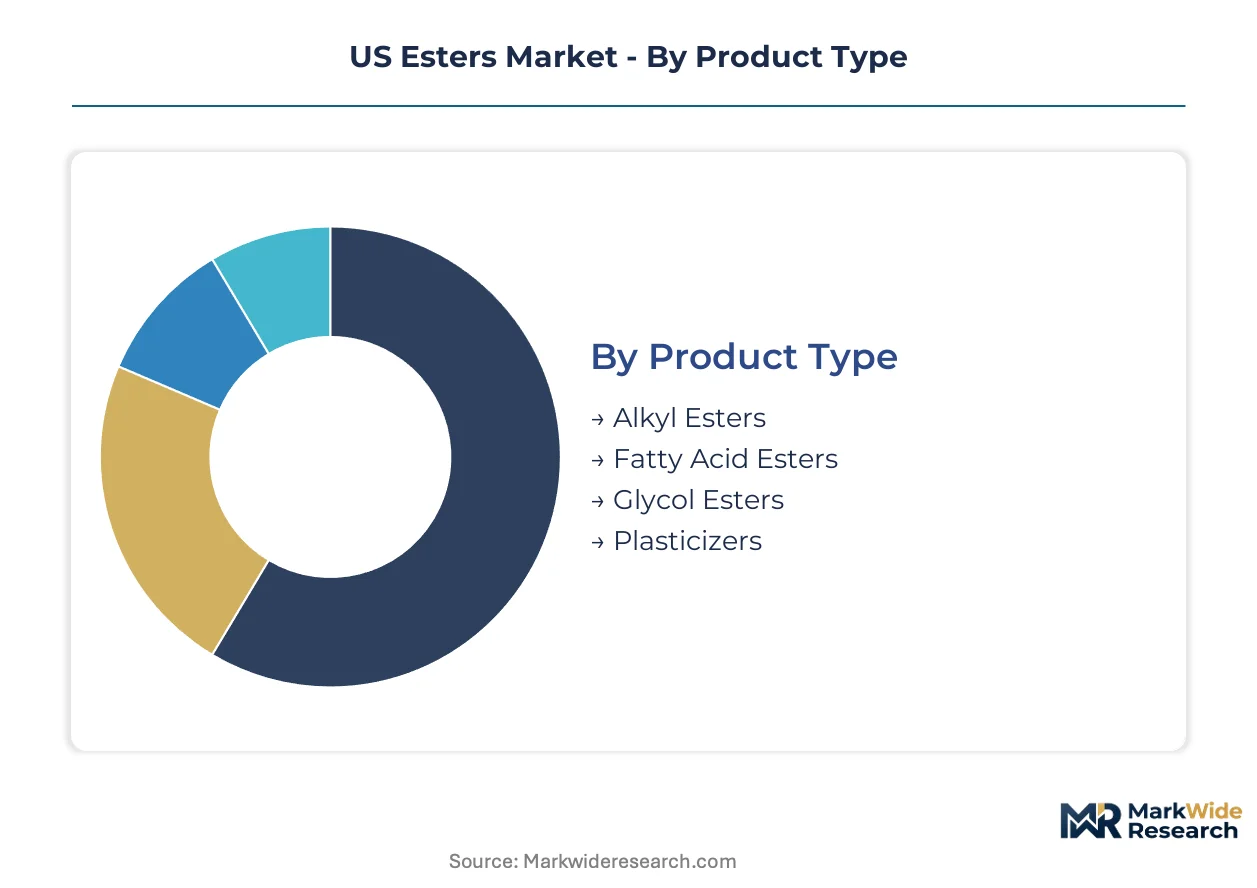
Ester segmentation in the US market reflects divergent margin profiles between commodity plasticizers and specialty cosmetic-grade materials. Procurement patterns split between Gulf Coast volume producers and regional specialty houses serving formulation-sensitive end users.
Product Type:
Volume concentrates in plasticizer-grade materials while premium positioning clusters around bio-derived cosmetic emollients.
- Fatty Acid Esters:Derived from palm, coconut, and tallow feedstocks through transesterification, these esters offer tunable melting points and oxidative stability. Demand concentrates in New Jersey and Pennsylvania cosmetic manufacturing clusters where indie brands specify custom carbon chain distributions for skin-feel optimization. FDA 21 CFR food-contact certification requirements elevate domestic producer advantages.
- Glycol Esters:Ethylene and propylene glycol esters function as coalescing agents and viscosity modifiers in water-borne architectural coatings. California and Northeast corridor states absorb volume as VOC restrictions tighten, displacing solvent-borne alternatives in automotive refinish and industrial maintenance applications.
- Alkyl Esters:High-purity C12-C18 alkyl esters serve lubricant basestock and personal care solvent applications. Eastman Chemical's Kingsport complex dominates domestic output.
- Plasticizers:Phthalate and non-phthalate ester plasticizers compound into PVC for construction and automotive wire insulation. Texas-Louisiana petrochemical corridors supply feedstock security.
Mature deployment sits with plasticizers in construction and automotive wire applications. Newer deployment is concentrated in fatty acid esters serving bio-based cosmetic formulations.
Application:
Cosmetic and coating end uses command formulation premiums while lubricant and food additive segments operate on volume-based procurement.
- Cosmetics:Emollient esters function as skin-conditioning agents, solubilizers, and texture modifiers in skincare and color cosmetics. Brooklyn and Los Angeles indie brands are contracting directly with manufacturers, bypassing traditional distributor channels and compressing margin pools for mid-tier traders.
- Coatings:Glycol ester coalescents enable low-VOC film formation in architectural paints and industrial finishes. Water-borne system conversion in California drives fastest segment expansion.
- Lubricants:Group V synthetic ester basestocks deliver thermal stability for electric vehicle battery cooling fluids. OEM formulation trials are redesigning thermal management architectures.
- Food Additives:Citric and lactic acid esters function as emulsifiers and preservatives in processed foods. FDA compliance timelines extend 18-24 months for new entrants.
Established demand patterns dominate lubricant and food additive procurement. Segment expansion is climbing the fastest in coatings as regulatory pressure accelerates solvent displacement.
End User:
Chemical manufacturers consolidate procurement volumes while cosmetic brands fragment demand across specialty suppliers.
- Chemical Manufacturers:Integrated producers like Dow and Eastman consume ester intermediates for downstream derivative production. Gulf Coast proximity determines supplier selection.
- Cosmetic Brands:Indie and multinational formulators specify carbon chain distributions for sensorial properties. Direct manufacturer relationships are shortening traditional distribution channels.
- Pharmaceutical Companies:High-purity esters serve as excipients and active pharmaceutical ingredient solvents. Enzymatic transesterification enables small-batch production in Ohio and North Carolina.
- Food Producers:Emulsifier and coating applications demand FDA-certified food-grade esters with full contaminant traceability.
Procurement standardization is most advanced among chemical manufacturers. Customization requirements are expanding most quickly with cosmetic brands seeking differentiated formulation inputs.
Distribution Channel:
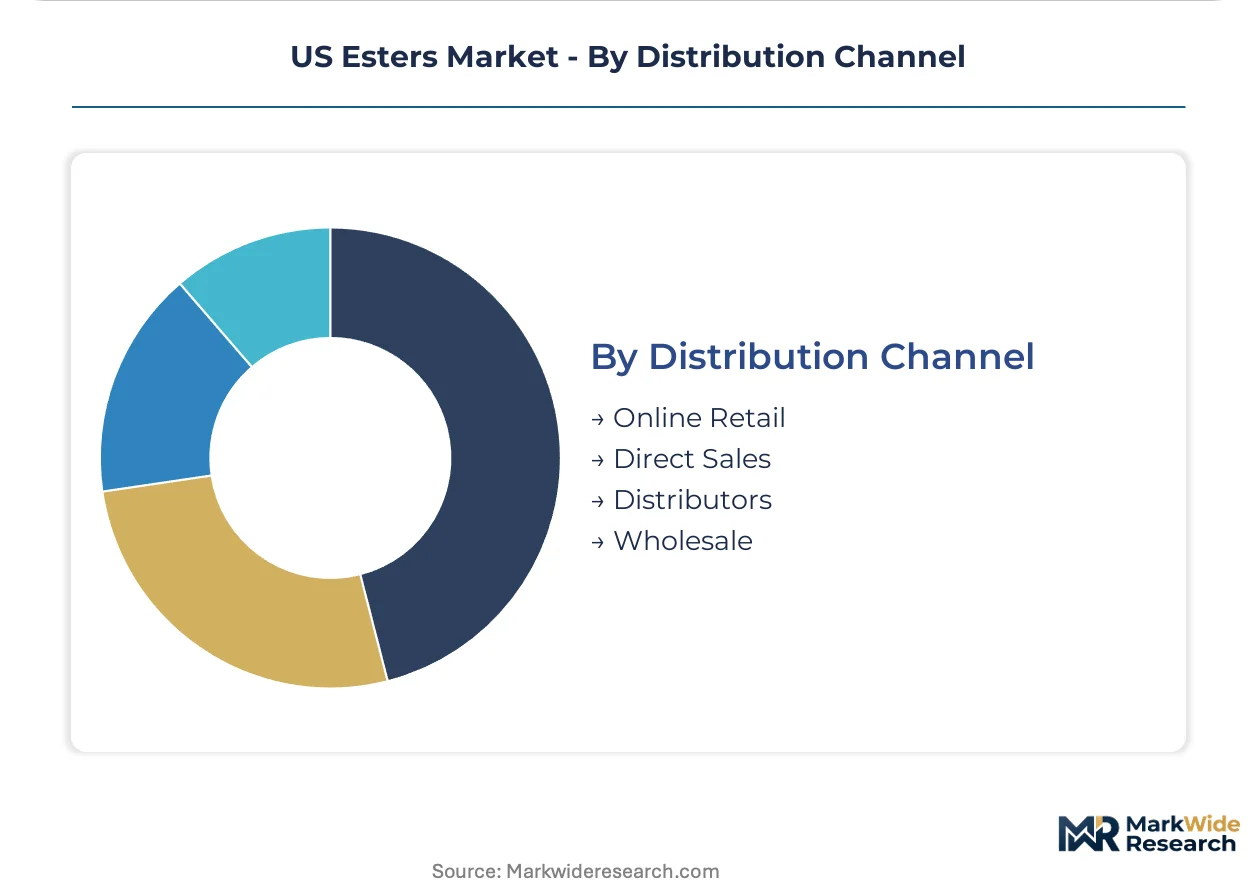
Direct sales capture premium formulation relationships while distributors retain commodity volume flows.
- Direct Sales:Technical service-intensive ester grades move through manufacturer-direct relationships with cosmetic and pharmaceutical formulators. Custom carbon chain distributions and joint development agreements characterize this channel.
- Distributors:Regional chemical distributors handle standard-grade plasticizers and lubricant basestocks for mid-sized compounders. Margin compression from disintermediation is forcing consolidation.
- Wholesale:Volume plasticizer grades flow through bulk terminal networks serving construction and automotive OEMs.
- Online Retail:Specialty esters in drum and pail quantities serve small cosmetic manufacturers and research laboratories.
Channel maturity rests with wholesale and distributor networks for commodity grades. Channel innovation is gaining share fastest in direct sales as cosmetic brands prioritize technical collaboration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for esters concentrates in the Texas-Louisiana petrochemical corridor, where integrated oleochemical processing clusters dominate domestic production. Formulator procurement patterns split between Gulf Coast volume suppliers and regional specialty houses serving cosmetic and pharmaceutical end users.
Texas
The Texas Gulf Coast anchors domestic ester production through integrated petrochemical complexes serving plasticizer and lubricant basestock markets. EPA regional enforcement of VOC standards under the Clean Air Act pressures Houston-area coating formulators toward water-borne glycol ester systems. The Houston Ship Channel corridor captures margin expansion from captive feedstock security and reduced import dependency for fatty alcohol precursors.
Louisiana
Louisiana's Mississippi River chemical corridor processes palm and coconut-derived feedstocks into personal care-grade fatty acid esters. State environmental regulations under the Louisiana Department of Environmental Quality align with federal TSCA compliance timelines, extending certification burdens for new market entrants. Baton Rouge and Lake Charles processing clusters supply cosmetic manufacturers in New Jersey and Pennsylvania through established distributor networks.
California
California absorbs the fastest-expanding volume of glycol ester coalescents as architectural and automotive refinish sectors convert to low-VOC water-borne formulations. Proposition 65 warning label requirements force reformulation transparency across personal care supply chains, pushing ester suppliers toward supercritical fluid purification investments. Los Angeles and Bay Area cosmetic brands are contracting directly with manufacturers, bypassing traditional distributor channels.
New Jersey
New Jersey's pharmaceutical and personal care manufacturing corridor drives demand for high-purity alkyl esters serving excipient and emollient applications. FDA's New Jersey district office enforces 21 CFR food-contact and cosmetic-grade certification standards, freezing rapid market penetration for uncertified imports. The state's indie cosmetic formulators in Brooklyn-adjacent clusters specify custom carbon chain distributions for sensorial differentiation.
Tennessee
Tennessee's Kingsport manufacturing complex dominates domestic output of high-purity alkyl esters for coatings and personal care end uses. State-level workforce development initiatives address process analytical chemistry talent scarcity for spectroscopy and chromatography specialists. The Appalachian region's position between Gulf Coast feedstocks and Midwest formulation centers enables competitive logistics positioning.
US Esters Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue enzymatic transesterification and distributed manufacturing models. The US esters market structures around three distinct player tiers: integrated petrochemical conglomerates with captive alcohol supply, regional specialty houses serving formulation-sensitive end users, and bio-fermentation startups collapsing traditional oleochemical value chains. Dominant competitive moves include backward integration into fatty alcohol production and capacity expansion for Group V synthetic ester basestocks.
Among integrated chemical producers, Eastman Chemical Company, Dow Chemical Company, and Stepan Company exemplify contrasting geographic and application archetypes. Eastman Chemical's Tennessee-based complex represents the integrated manufacturing model with captive feedstock processing. Dow Chemical occupies the Gulf Coast petrochemical position extending into plasticizer-grade esters. Stepan Company anchors Midwest surfactant-linked production serving household and industrial cleaning formulators.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Evonik Industries AG |
| BASF SE |
| Procter & Gamble |
| Archer Daniels Midland Company |
| Sasol Limited |
| Stepan Company |
| PCC Chemax Inc. |
| Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Cosmetic brand procurement consolidation around bio-based emollients is compressing margin pools for mid-tier distributors while rewarding Gulf Coast volume producers with captive feedstock security. Contract-based long-term offtake agreements dominate high-purity alkyl ester transactions, whereas commodity plasticizer grades trade on spot-indexed petrochemical feedstock formulas.
Pricing Analysis
Volume concentrates in plasticizer-grade esters trading on thin margins tethered to crude oil derivatives, while premium fatty acid esters for personal care command three-tier pricing structure across premium, standard, and economy levels based on carbon chain specificity and FDA 21 CFR certification status. Cost compression in standard-grade materials is intensifying because polyether polyol substitution threatens ester polyol demand during crude oil price troughs. Chemical manufacturers show least price sensitivity due to backward integration into alcohol feedstocks, whereas indie cosmetic brands exhibit highest sensitivity to lot-to-lot variability surcharges.
Supply Chain Analysis
Dual-sourcing requirements from California and New Jersey cosmetic formulators mandate multi-supplier qualification for fatty acid esters, fragmenting procurement across Louisiana palm-derived and Tennessee tallow-based producers. Raw material dependencies center on tropical palm and coconut oils from Southeast Asia, petroleum-derived ethylene from Texas crackers, and domestic tallow rendering operations. Single-source vulnerability concentrates in Southeast Asian oleochemical feedstocks subject to harvest volatility and maritime logistics chokepoints. Distribution runs through regional chemical distributors for standard grades, while direct manufacturer relationships capture formulation-intensive cosmetic and pharmaceutical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR compliance timelines erect an 18-24 month barrier-to-entry moat that freezes uncertified imports and rewards domestic producers with established testing protocols. This cost-of-compliance dynamic favors incumbents with sunk regulatory investments.
For Market Incumbents: Extend analytical chemistry capabilities into supercritical fluid purification to meet California Proposition 65 trace contaminant disclosure requirements. Add continuous flow chemistry capacity at Gulf Coast sites to capture margin expansion from reduced batch cycle times. Enzymatic transesterification startups in Ohio threaten small-batch specialty positions; defend through technical service embedding with Brooklyn and Los Angeles indie cosmetic brands. For New Entrants and Emerging Players: The gap between premium bio-fermentation esters and economy petroleum-derived grades offers white-space positioning for mid-tier suppliers with USDA BioPreferred certification. Target pharmaceutical excipient applications in New Jersey where FDA district enforcement elevates domestic sourcing preferences. Pursue enzymatic transesterification partnerships with Ohio and North Carolina research clusters to bypass Gulf Coast scale disadvantages. For Investors and Strategic Acquirers: The window for entry favors specialty houses with captive bio-fermentation pathways and established cosmetic brand technical relationships over commodity plasticizer exposure. Acquisition targets should demonstrate Group V synthetic ester qualification with electric vehicle OEM thermal management programs. Watch battery cooling fluid formulation trials as the inflection signal for Group V synthetic ester demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Production | Captive supply of palm and tallow precursors insulates margin from tropical feedstock volatility. |
| Continuous Flow Chemistry Retrofit | $15-40 million site investments reduce batch cycle times and improve real-time quality control. |
| USDA BioPreferred Certification | Federal procurement mandates create guaranteed offtake channels for certified bio-based emollients. |
| Direct Technical Service Relationships | Joint development agreements with Brooklyn and Los Angeles indie brands compress distributor margins. |
| Group V Synthetic Ester Capacity Expansion | OEM battery cooling architecture redesigns pull formulation trials toward thermal stability basestocks. |
Research Approach
Multi-period observation of EPA Safer Choice program certifications, FDA 21 CFR approval timelines, and palm oil futures volatility anchored the trend analysis, supplemented by interviews with plant managers at Gulf Coast petrochemical complexes, procurement leads at New Jersey cosmetic manufacturers, distribution channel partners in the Texas-Louisiana corridor, and technical R&D directors specializing in enzymatic transesterification. Secondary validation drew from EPA TSCA filings, FDA 21 CFR substance databases, American Chemistry Council sector reports, and customs trade data on fatty alcohol imports. Bottom-up volume builds across end-use segments triangulated against top-down petrochemical capacity assessments.
Input-output matrix framing connected feedstock availability scenarios to end-use demand elasticity across the projection horizon. Segmentation dimensions modeled include product type tier, application sensitivity, end-user procurement consolidation level, and regional production hub proximity. CAGRs derived from slope consistency checks against historical petrochemical demand cycles and regulatory phase-in schedules. Electric vehicle thermal fluid adoption curves and water-borne coating conversion rates served as industry-specific demand drivers.
Inputs from EPA enforcement actions and FDA district office inspection records were available through the study window; gaps in real-time enzymatic transesterification production data introduce uncertainty bands around specialty segment growth trajectories. Forecasts reflect assumptions regarding sustained palm oil price volatility and California VOC restriction tightening. Deviation in federal bio-preferred procurement mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Europe Wax Market
Oleochemicals
Paraffin Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Squalane Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Caprylic/Capric Triglyceride Market