
 Cryolite Market | 2026-2036
Cryolite Market Size, Share, and Industry Trends Forecast 2026-2036
Cryolite Market Intelligence
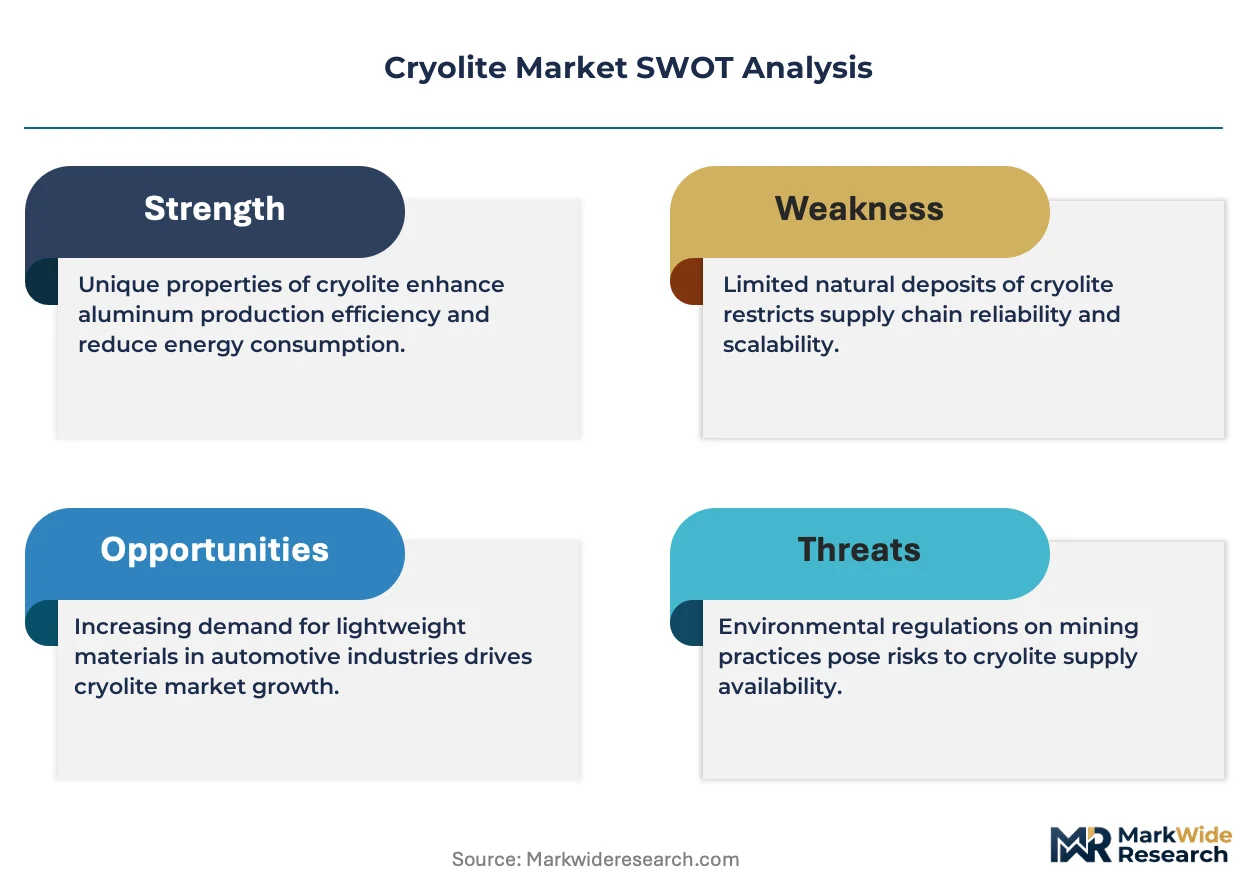
High-purity synthetic cryolite, essential for modern aluminum smelting, is reorganizing the competitive landscape. Global chemical producers like Solvay leverage extensive R&D to meet stringent purity requirements for electrolysis. Navin Fluorine International Limited differentiates through integrated manufacturing of fluorine-based chemicals, ensuring consistent feedstock. DO-FLUORIDE NEW ENERGY TECHNOLOGY CO.LTD competes on production scale to serve large-volume aluminum producers in China and other parts of Asia.
Cryolite is a sodium hexafluoroaluminate (Na3AlF6) mineral used primarily as a flux in electrometallurgy. Its main function is to dissolve alumina, allowing for efficient electrolytic reduction into aluminum metal at lower temperatures. Synthetic cryolite overwhelmingly dominates the product landscape due to the depletion of natural ore deposits, with powdered and granular forms offered. While aluminum electrolysis constitutes the largest application, demand from metal surface treatment and abrasives provides niche, higher-margin opportunities for specialized producers.
Regulatory frameworks, including the EU's REACH and standards from the US EPA, govern the handling of fluoride compounds and emissions from aluminum smelters. In China, MEE regulations on industrial pollutants and solid waste disposal influence the quality of cryolite required for cleaner production. Consequently, producers must navigate evolving environmental health and safety standards across key global markets. The critical decision for suppliers involves balancing investment in purity upgrades against cost pressures from the primary metals industry.
Market Dynamics
The structural pivot from scarce natural ore to scalable synthetic production defines the cryolite market. This shift stabilizes supply for the dominant aluminum industry, with demand heavily weighted toward China's massive smelting capacity, creating a market dynamic tied directly to primary metal output and energy costs.
Growth Catalysts
- Aluminum Sector Expansion:Sustained output in the global aluminum industry, particularly for automotive lightweighting and construction in Asia, directly stimulates consumption of cryolite as an essential fluxing agent in electrolysis.
- Synthetic Production Stability:The widespread adoption of synthetic manufacturing processes provides a reliable and consistent supply of high-purity cryolite, removing the volatility associated with depleted natural deposits and supporting industrial planning.
- Niche Application Growth:Demand from specialized sectors, including the manufacturing of abrasives, welding agents, and enamels, creates higher-margin opportunities for producers capable of meeting specific particle size and purity requirements.
Market Restraints
- Raw Material Price Volatility:The production cost of synthetic cryolite is directly linked to the fluctuating prices of key feedstocks like hydrofluoric acid and aluminum hydroxide, which can compress manufacturer margins.
- Stringent Environmental Regulations:Compliance with emissions standards for fluoride compounds, such as those enforced by the US EPA and China's MEE, necessitates significant investment in pollution control technology, raising operational costs.
- Energy Cost Dependency:The manufacturing process for synthetic cryolite is energy-intensive, making producers highly susceptible to regional fluctuations in electricity and natural gas prices, which can impact global competitiveness.
Strategic Opportunities
- High-Purity Grade Development:Innovating new cryolite formulations with exceptionally low impurity levels opens pathways into advanced applications like specialty alloys, optical materials, and next-generation battery electrolytes.
- Emerging Smelter Hubs:Targeting new aluminum production projects in the Middle East and Southeast Asia provides an opportunity to establish early supply agreements in regions with growing primary metal capacity.
- Circular Economy Integration:Developing technologies to efficiently recover and reuse cryolite from spent pot lining (SPL), a hazardous waste from aluminum smelters, aligns with sustainability goals and creates a secondary resource stream.
Industry Challenges
- High Capital Investment:Constructing new synthetic cryolite plants or upgrading existing ones to meet stringent purity and environmental standards requires substantial capital outlay, creating a high barrier to entry for new players.
- Navigating Global Compliance:Managing a patchwork of chemical safety regulations, including the EU's REACH framework and various national standards, complicates international trade and increases administrative overhead for suppliers.
- Logistical Complexity:Ensuring the safe and cost-effective transportation of cryolite, a fine powder that requires specialized handling to prevent moisture contamination and dust exposure, poses logistical hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryolite Market |
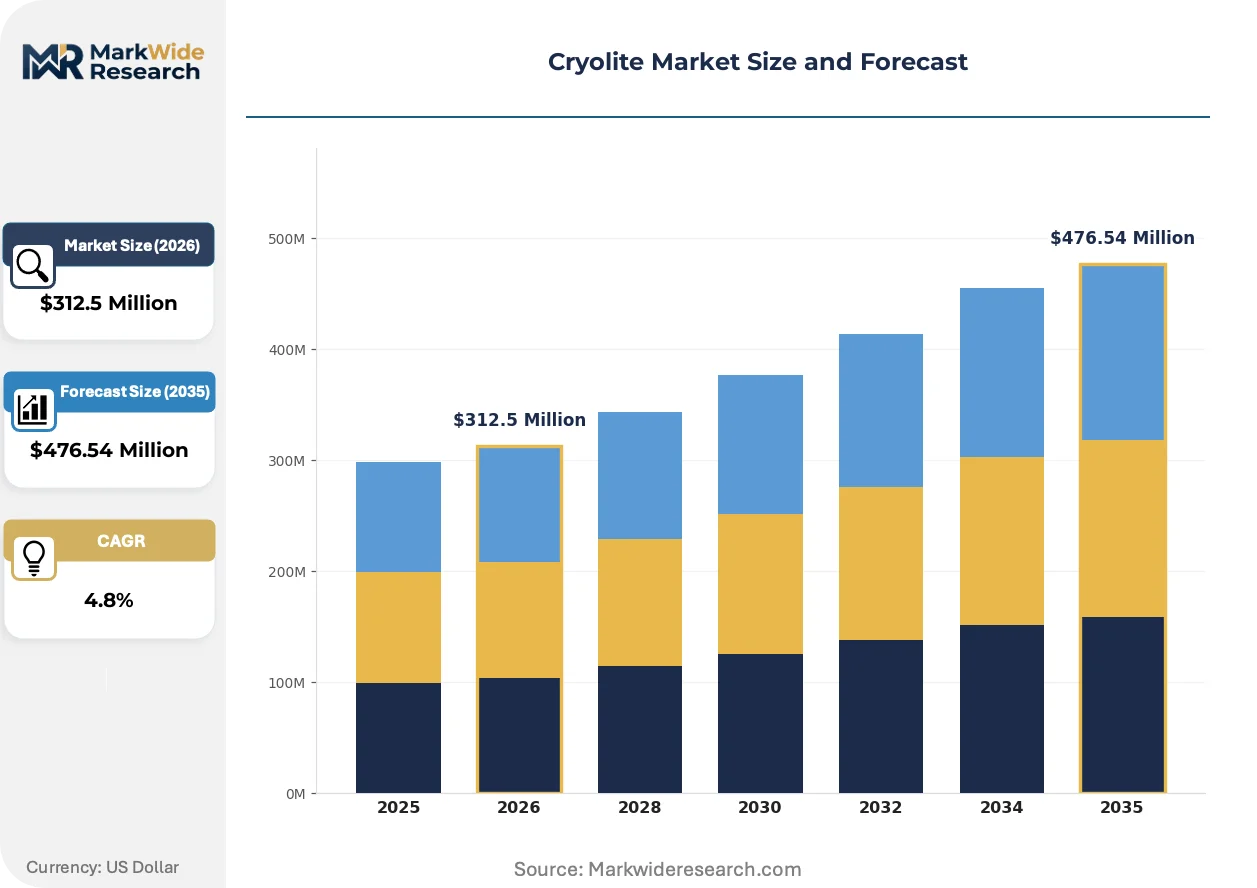
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Cryolite, Natural Cryolite, Granular Form, Powdered Form Application: Aluminum Electrolysis, Metal Surface Treatment, Fire Retardants, Glass Production, Flux in Welding End User Industry: Metal Casting Foundries, Chemical Manufacturing, Electronics Fabrication, Construction Materials, Ceramics Production Packaging Type: Bulk Bags, Cardboard Drums, Plastic Containers, Valve Bags |
| Companies Covered | DO-FLUORIDE NEW ENERGY TECHNOLOGY CO.LTD, Navin Fluorine International Limited, Solvay, Skyline Chemical Corporation, Harshil Industries, Fluorsid, Dupré Minerals Limited, Purex Global, S.B. Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryolite Market Strategic Shifts & Innovations
Process efficiency and environmental stewardship are the primary forces guiding innovation. The market is advancing toward cryolite formulations that lower energy consumption in electrolysis while simultaneously adapting production to meet tightening global regulations on fluoride emissions and solid waste disposal, particularly within the aluminum industry.
Advanced low-temperature electrolysis techniques utilize modified cryolite-alumina melts to reduce the energy required for smelting. Primary aluminum producers are cautiously adopting these methods in pilot projects and plant upgrades to lower operational expenditures. This development is decomposing the traditional, energy-intensive cost structure of aluminum production, making smelters in high-cost energy markets more competitive.
China's "dual carbon" goals and associated MEE regulations are imposing stricter limits on industrial pollutants from metallurgical facilities. This policy directly impacts aluminum smelters, forcing them to demand higher-purity cryolite that generates fewer harmful emissions during electrolysis. Cryolite producers supplying the Chinese market must therefore enhance product quality and provide documentation of environmental performance to remain competitive.
A notable behavioral shift involves major metal purchasers prioritizing suppliers who can verify a low-carbon footprint for their materials. This disrupts procurement models based solely on cost and technical specifications, creating a preference for cryolite producers using renewable energy or demonstrating superior energy efficiency. The trend is most pronounced in the European automotive and aerospace sectors.
Cryolite Market Segmentation
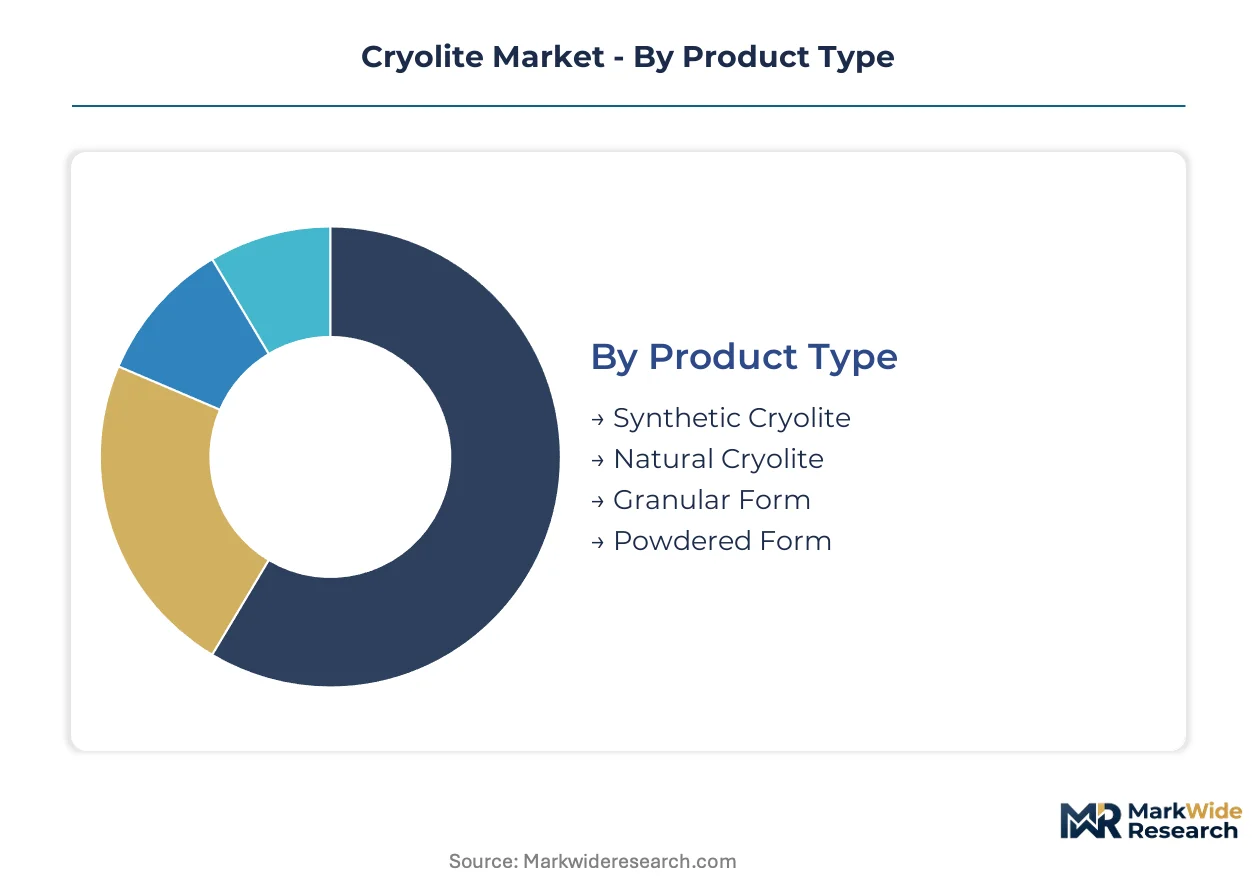
The Cryolite market's segmentation reflects diverse product forms, applications, end-user requirements, and logistical considerations. Understanding these distinct segments allows producers to tailor offerings and target specific industrial needs. This detailed breakdown highlights established demand and emerging growth opportunities.
Product Type:
Cryolite product types exhibit varying geographic concentration. Synthetic forms dominate industrial output in major aluminum-producing nations, while specialized forms serve localized markets.
- Synthetic Cryolite:This chemically manufactured sodium hexafluoroaluminate (Na3AlF6) provides consistent purity, crucial for modern industrial processes. Demand concentrates in China, which relies on synthetic production to fuel its vast aluminum smelting capacity.
- Powdered Form:Fine particle size offers high surface area for rapid dissolution and uniform mixing. Demand stems from global aluminum electrolysis operations, integrating into molten salt baths, optimizing energy consumption.
- Natural Cryolite:This naturally occurring mineral is now virtually depleted, making its commercial availability extremely limited for industrial use.
- Granular Form:Comprising larger, uniform particles, this form reduces dust generation and applies in specific flux formulations and abrasive manufacturing.
Synthetic Cryolite commands the established base. The steepest expansion runs through Powdered Form.
Application:
The cryolite market's application segments are differentiated by volume requirements, ranging from high-tonnage industrial processes to specialized, lower-volume chemical treatments.
- Aluminum Electrolysis:Cryolite serves as a solvent for alumina in the Hall-Héroult process, lowering the melting point for efficient electrolytic reduction. Global aluminum smelters, particularly in China, drive vast demand for this indispensable primary metal production material.
- Metal Surface Treatment:This application involves cryolite in pickling pastes and flux agents for cleaning and preparing metal surfaces. Demand arises from specialized industrial fabrication sectors seeking enhanced surface quality and corrosion resistance.
- Fire Retardants:Cryolite acts as a non-toxic flame retardant additive in various materials, including plastics and textiles, enhancing fire resistance.
- Glass Production:In glass manufacturing, cryolite functions as an opacifier and fluxing agent, reducing melting temperatures and improving specialty glass optical properties.
- Flux in Welding:Cryolite is incorporated into welding electrode coatings and flux powders, improving arc stability and slag removal during various welding processes.
Aluminum electrolysis remains the predominant application, while metal surface treatment applications demonstrate significant growth potential for specialized cryolite formulations.
End User Industry:
End-user industries for cryolite vary significantly by operational scale and technical specifications, from large-scale primary metal producers to niche specialty manufacturers.
- Metal Casting Foundries:These facilities use cryolite as a flux in melting and refining processes for non-ferrous metals, primarily aluminum, to remove impurities and improve metal flow. Demand is driven by automotive and aerospace industries requiring high-integrity castings.
- Chemical Manufacturing:This sector utilizes cryolite as a raw material or catalyst in producing various fluorine compounds and other specialty chemicals. Its demand reflects broader growth in industrial chemical synthesis and fluoropolymer production across Europe and Asia.
- Electronics Fabrication:Cryolite finds specialized use in producing certain electronic components and for etching processes in semiconductor manufacturing.
- Construction Materials:In the construction sector, cryolite is used as an additive in certain insulation materials and specialized cements, contributing to fire resistance.
- Ceramics Production:Cryolite acts as a flux and opacifier in ceramic glazes and enamels, improving their adherence, durability, and aesthetic finish.
Metal casting foundries represent the largest consumer base for cryolite. Chemical manufacturing exhibits a steady expansion due to diverse synthesis requirements.
Packaging Type:
Cryolite packaging types are largely dictated by supply chain efficiency and user handling requirements, with bulk formats dominating high-volume industrial deliveries and specialized options for smaller consignments.
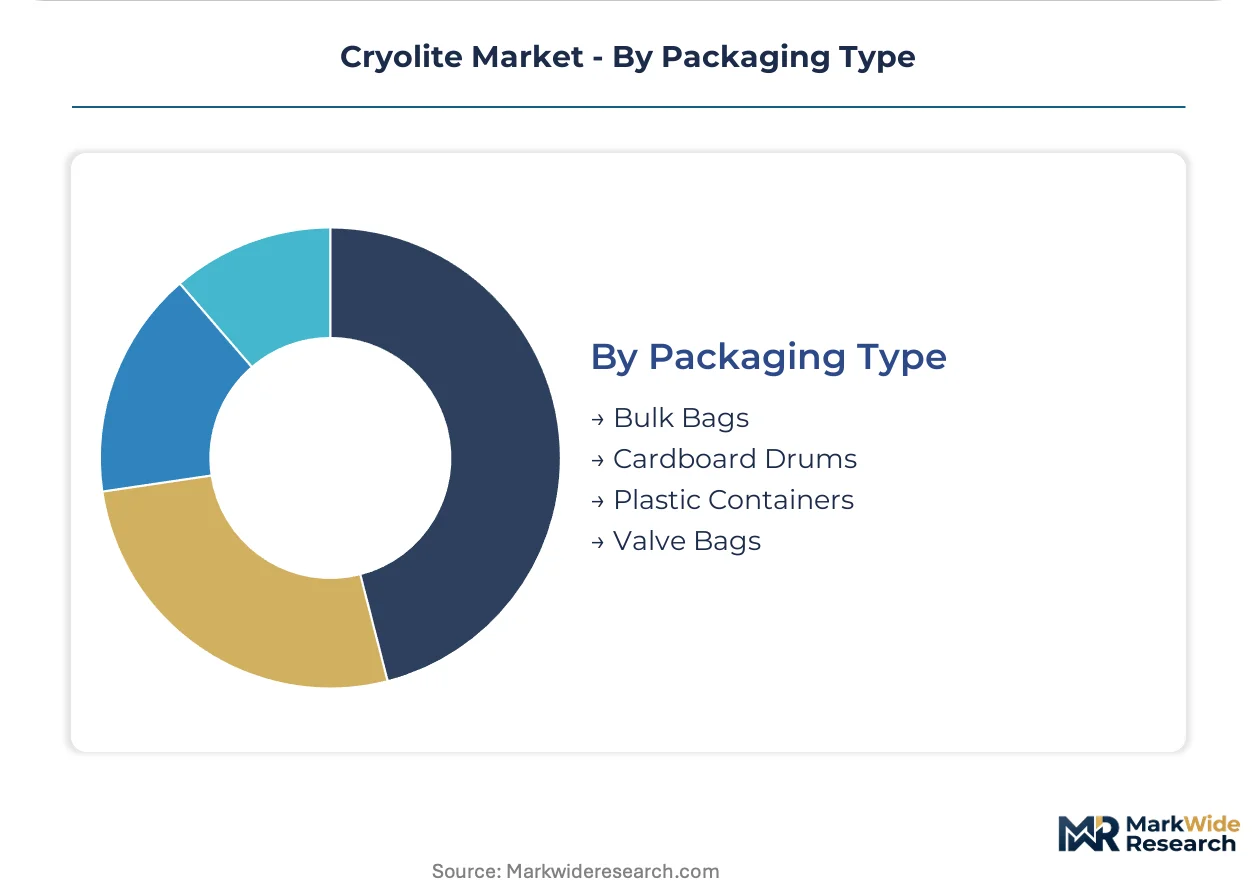
- Bulk Bags:These large, flexible containers (500 kg to 1,500 kg) are designed for efficient handling and transportation of high volumes of cryolite. Industrial aluminum smelters prefer bulk bags for cost-effective material delivery and reduced waste.
- Valve Bags:These bags feature a self-sealing valve for dust-free filling and precise dosing, common for smaller, controlled quantities of cryolite. Specialty chemical producers utilize valve bags for convenience and minimized product loss.
- Cardboard Drums:These rigid, cylindrical containers offer robust protection for cryolite, often used for smaller, specialized orders requiring enhanced moisture barrier.
- Plastic Containers:Plastic containers provide lightweight and moisture-resistant packaging for cryolite, suitable for smaller volumes and laboratory-grade materials.
Bulk bags are fundamental for large-scale industrial distribution. Valve bags cater effectively to niche applications requiring precise material handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration sits with major industrial nations driving aluminum production and specialty chemical manufacturing. These regions dictate demand patterns and influence global cryolite supply dynamics. Regulatory environments and technological advancements also shape regional market evolution.
China
Demand for cryolite in China stems from its dominant primary aluminum smelting capacity. MEE regulations on industrial pollutants impose stricter quality requirements for cryolite used in electrolysis. Major aluminum producers in regions like Xinjiang and Inner Mongolia drive substantial consumption.
India
The Indian market sees cryolite demand from growing aluminum production and chemical manufacturing sectors. India's PLI scheme for advanced chemistry cell batteries indirectly supports demand for specialty fluorine compounds. Chemical manufacturing clusters in Gujarat and Maharashtra utilize cryolite for various industrial applications.
United States
Cryolite consumption in the United States is driven by aluminum production, metal surface treatment, and abrasive manufacturing. US EPA regulations on fluoride emissions influence process and product quality standards for suppliers. Chemical processing facilities in Texas and Louisiana integrate cryolite into their operations.
Germany
Germany exhibits demand for high-purity synthetic cryolite, particularly for advanced aluminum applications and specialty chemicals. The EU's REACH framework governs the handling and environmental impact of fluoride compounds. Chemical parks in Rhineland-Palatinate and Bavaria are significant users and developers of cryolite formulations.
Saudi Arabia
Saudi Arabia represents an emerging demand center for cryolite due to significant investments in new aluminum smelter projects. The nation's Vision 2030 strategy aims to diversify industrial output, including primary metals. Industrial cities like Jubail and Yanbu are expanding their capacities for aluminum production, requiring cryolite.
Cryolite Market Key Industry Players
Concentration sits with established chemical producers and integrated fluorine specialists. The market structure exhibits a tiered approach, with global players offering high-purity grades and regional firms competing on scale. Strategic archetypes include large-scale commodity suppliers, integrated chemical manufacturers, and niche specialty producers. Dominant competitive moves involve investment in research and development for purity upgrades and capacity expansion to serve large industrial clients.
Global chemical producers like Solvay exemplify the focus on extensive research and development to meet stringent purity requirements for electrolysis. Navin Fluorine International Limited, an India-based firm, occupies a position in integrated manufacturing of fluorine-based chemicals, ensuring consistent feedstock supply. DO-FLUORIDE NEW ENERGY TECHNOLOGY CO.LTD, a Chinese entity, anchors the scale-driven end, competing on production volume to serve large aluminum producers across Asia.
| Leading Market Players |
|---|
| DO-FLUORIDE NEW ENERGY TECHNOLOGY CO.LTD |
| Navin Fluorine International Limited |
| Solvay |
| Skyline Chemical Corporation |
| Harshil Industries |
| Fluorsid |
| Dupré Minerals Limited |
| Purex Global |
| S.B. Chemicals |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for cryolite, common in the aluminum industry, lock in both supply access and price visibility for major smelters. These contracts mitigate feedstock price volatility for high-volume consumers.
Pricing Analysis
MEE regulations in China dictate the pricing tier structure for cryolite, influencing quality requirements and production costs. Pricing stratifies across premium, standard, and economy tiers based on purity levels and particle size specifications. Pricing softness stems from cost pressures within the primary metals industry, particularly for high-volume orders. Large aluminum producers exhibit the most price sensitivity, while specialty chemical manufacturers prioritize purity over cost.
Supply Chain Analysis
Inventory management for cryolite involves balancing just-in-time delivery for large users with strategic stockpiling against feedstock fluctuations. Supply concentrates heavily in China, drawing from raw materials like hydrofluoric acid and aluminum hydroxide. Commodity price volatility for these feedstocks presents a structural risk to manufacturer margins. Distribution runs through bulk deliveries to industrial users, primarily aluminum smelters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryolite market offers fragmentation opportunities as demand for high-purity grades in advanced applications creates distinct niches.
For Market Incumbents:
Secure long-term supply agreements with primary aluminum producers in emerging hubs like Saudi Arabia and Southeast Asia. Invest in R&D for low-energy electrolysis formulations to counter rising energy costs and stringent environmental regulations. Pursue integrated manufacturing capabilities to control feedstock costs against raw material price volatility.
For New Entrants and Emerging Players:
Certification fast-track pathways for specialized cryolite formulations open entry points into niche applications like advanced abrasives and optical materials. Target emerging smelter projects in the Middle East, which represent a penetrable segment for new supply partnerships. A go-to-market angle involves developing efficient cryolite recovery technologies from spent pot lining, aligning with circular economy goals.
For Investors and Strategic Acquirers:
Integrated fluorine chemical manufacturers with established high-purity cryolite production capabilities represent attractive acquisition targets. The market's long-term viability is anchored in the continuous demand from the global aluminum industry. The signal to watch is the widespread commercial adoption of advanced low-temperature electrolysis techniques, indicating a shift in product specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports China's dominant aluminum production and growing demand in Southeast Asia. |
| Green Manufacturing Transition | Addresses stricter MEE regulations and buyer preference for low-carbon footprint materials. |
| High-Purity Grade Development | Unlocks access to advanced applications like specialty alloys and battery electrolytes. |
| Circular Economy Integration | Mitigates hazardous waste disposal costs and creates secondary resource streams. |
| Long-term Supply Agreements | Ensures stable demand and price visibility for major aluminum industry clients. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and extensive secondary research. Primary research involved discussions with plant managers, procurement leads, R&D directors, and environmental compliance officers across the cryolite value chain. Secondary data sources included industry association reports, regulatory filings from the US EPA and China's MEE, company financial statements, and global trade databases. A bottom-up approach triangulated with top-down market sizing validated all data points.
The analysis window for this study extends from 2026 to 2035, integrating historical trends and future projections. Segmentation dimensions modeled included product type, application, end-user industry, packaging type, and purity grade. Compound annual growth rates (CAGRs) were derived from a synthesis of historical performance, expert consensus, and anticipated demand drivers. Key forecast inputs included primary aluminum output projections and feedstock price trends.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory environments and consistent technological adoption; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, acknowledging potential impacts from volatile energy costs or geopolitical shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market