
 Surface Treatment Chemicals Market | 2026-2036
Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Treatment Chemicals Market Intelligence
Technical support subscriptions for chemical management and application optimization is broadening the traditional product-centric sales model. Henkel AG & Co. KGaA leverages its deep integration with automotive OEMs to secure long-term contracts. PPG Industries specializes in high-performance coatings for the demanding aerospace sector. BASF differentiates through its R&D in sustainable, bio-based chemical alternatives.
Surface treatment chemicals are formulations designed to modify the outermost layer of a substrate. These compounds, often acidic or alkaline in nature, enhance properties such as corrosion resistance, paint adhesion, and wear protection. Conversion coatings represent a critical product segment, essential for preparing metal surfaces in automotive and industrial applications. Demand from the electronics sector for high-purity acidic and alkaline cleaners to prepare semiconductors and circuit boards is also a significant value driver.
Regulatory frameworks from Europe's ECHA, under REACH, and the United States' EPA, which limits volatile organic compounds (VOCs), mandate stricter chemical compositions. China's Ministry of Ecology and Environment (MEE) imposes similar stringent standards on industrial effluents and emissions. Chemical manufacturers must continually innovate to develop compliant, high-performance formulations without compromising cost-effectiveness for end-users.
Market Dynamics
The market's central tension is the demand for higher performance from automotive and electronics against tightening environmental regulations. Mandates from Europe's ECHA and the US EPA are forcing a fundamental reformulation of core chemical portfolios.
Growth Catalysts
- Automotive Lightweighting:The automotive shift to lightweighting requires specialized pretreatments for aluminum and composites to ensure corrosion resistance and paint adhesion.
- EU Regulation:EU's REACH regulation drives R&D into compliant, less-toxic formulations like bio-based systems, creating new product categories.
- Manufacturing Relocation:Manufacturing concentration in Southeast Asia, particularly Vietnam and Thailand, creates localized demand for high-purity cleaners and conversion coatings.
Market Restraints
- Input Cost Volatility:Price volatility of inputs like acids and specialty solvents, tied to the petrochemical market, complicates cost management.
- Effluent Standards:Stringent effluent standards from bodies like China's MEE require costly wastewater treatment, slowing adoption of certain processes.
- Material Substitution:Development of self-passivating alloys and advanced composites that require no surface treatment poses a long-term substitution threat.
Strategic Opportunities
- Sustainable Formulations:Developing high-performance, biodegradable, or bio-derived cleaners meets both regulatory mandates and corporate sustainability goals, representing a key growth area.
- Digital Services:Subscription-based software for process optimization and compliance tracking creates recurring revenue streams beyond traditional product sales.
- Aerospace Expansion:The expanding aerospace MRO sector in markets like India and Brazil is an underpenetrated segment for high-specification coatings.
Industry Challenges
- Formulation Complexity:Formulating products compliant with diverse global regulations like REACH and EPA VOC limits, without sacrificing performance, is a major R&D hurdle.
- Talent Scarcity:A shortage of field application engineers with expertise in chemistry and end-user processes, like semiconductor fabrication, hinders effective technical support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Treatment Chemicals Market |
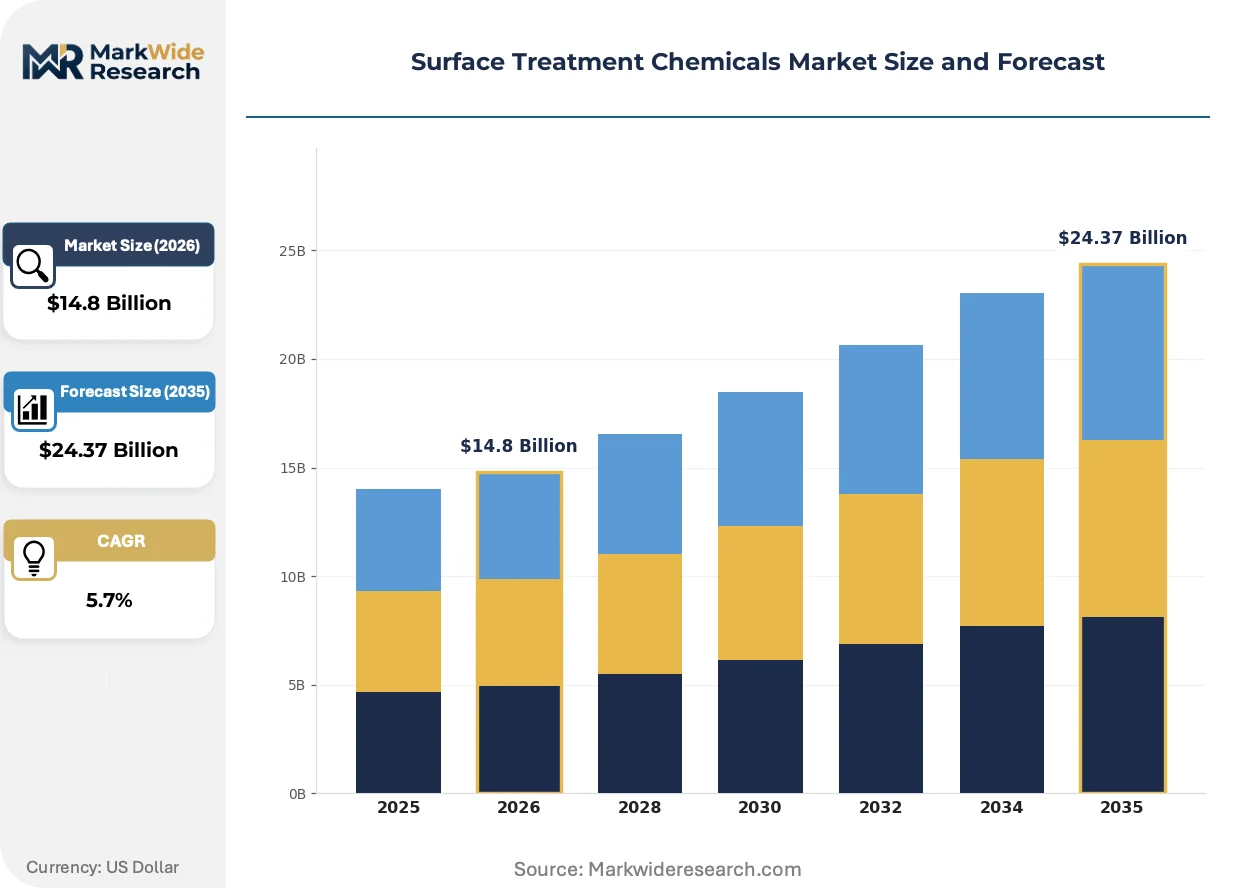
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acidic Cleaners, Alkaline Cleaners, Degreasers, Conversion Coatings Application: Aerospace, Automotive, Electronics, Industrial Technology: Electroplating, Anodizing, Coating, Passivation End User: Manufacturers, Tier-1 Suppliers, Service Providers, OEMs |
| Companies Covered | Nippon Paint Holdings, Nihon Parkerizing, BASF, Solvay, Element Solutions, Henkel AG & Co. KGaA, MKS Atotech, The Sherwin-Williams Company, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Treatment Chemicals Market Strategic Shifts & Innovations
The industry shifts from a product-centric model to a service-oriented one, driven by regulatory complexity and demands for process efficiency. This evolution prioritizes data-driven optimization and sustainable chemistry as core differentiators.
"Smart" chemical baths use embedded sensors to automatically monitor and adjust parameters like pH and concentration. Automotive and aerospace manufacturers are adopting these systems to ensure process consistency and reduce waste. This integration of digital controls with chemical processes is electrifying the factory floor, transforming static lines into data-generating assets.
Harmonization of chemical safety standards, driven by OECD guidelines and the Globally Harmonized System (GHS), creates a de facto global rulebook. This simplifies cross-border trade for multinationals but raises compliance costs for regional formulators. The industrial cleaners segment is most affected, requiring extensive safety data sheets consistent across jurisdictions.
End-users are increasingly outsourcing the entire chemical management function, from inventory to waste disposal, to their suppliers. This unbundles the sale of chemicals from the service of managing them, creating a new role for suppliers as on-site partners. This trend is most prominent in North America within the metal finishing sector.
Surface Treatment Chemicals Market Segmentation
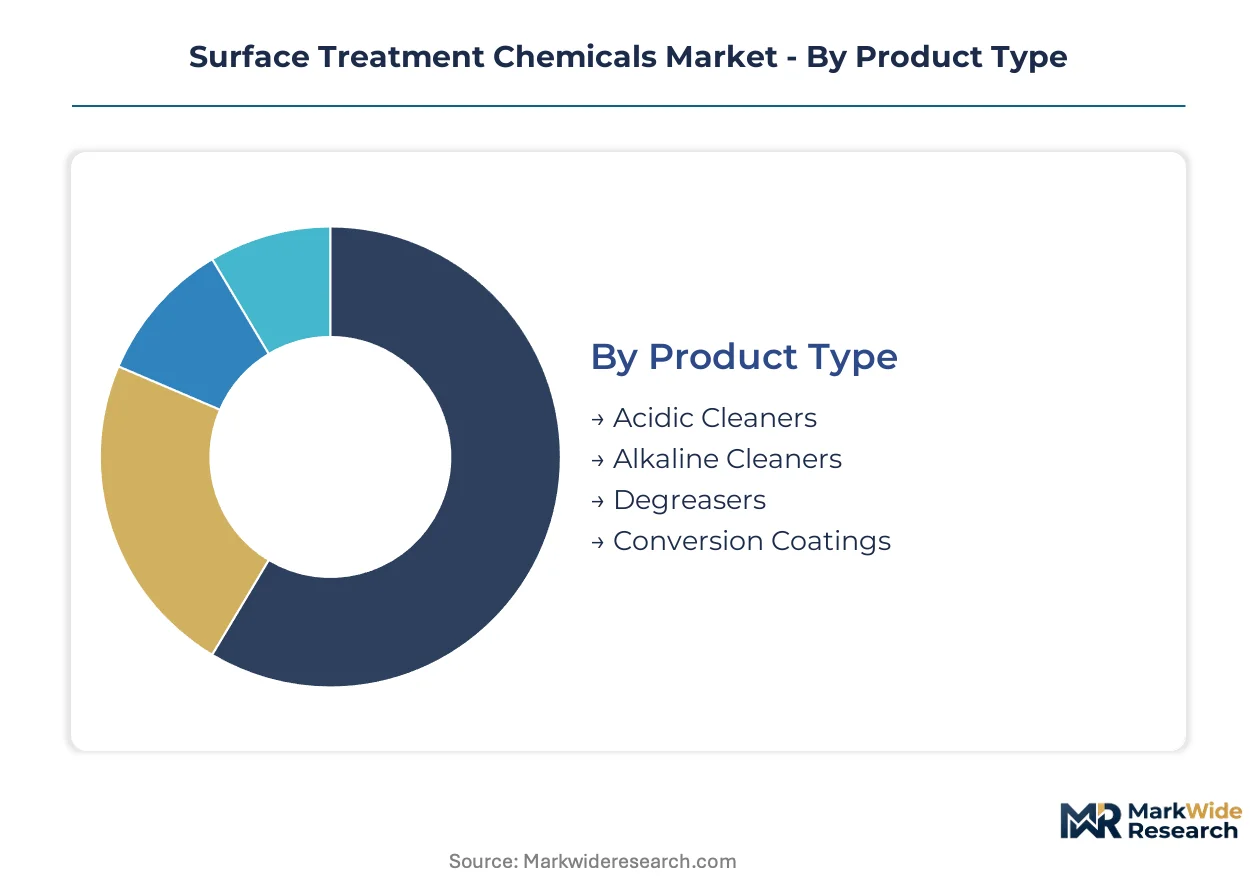
The Surface Treatment Chemicals Market segments across diverse product types, applications, technologies, and end-users. Understanding these divisions reveals the specific chemical formulations and technical expertise required for different industrial processes. This granular view highlights where innovation and demand concentration are occurring across the value chain.
Product Type:
Buyer differentiation in surface treatment chemicals often hinges on the specific substrate and desired outcome, driving demand for distinct chemical compositions.
- Conversion Coatings:These chemical formulations create an insoluble protective layer on metal surfaces, enhancing corrosion resistance and paint adhesion. Demand concentrates heavily in the automotive sector for vehicle body protection and in industrial applications for equipment durability.
- Alkaline Cleaners:Composed of strong bases and surfactants, these solutions effectively remove oils, greases, and other organic contaminants from metal surfaces. The electronics sector utilizes high-purity alkaline cleaners for preparing semiconductor wafers and circuit boards.
- Acidic Cleaners:These formulations, containing strong acids, remove rust, scale, and inorganic residues from various metal substrates.
- Degreasers:Solvent-based or aqueous solutions used to eliminate heavy oils and lubricants from industrial components before further treatment.
Volume sits with Alkaline Cleaners; growth tilts toward Conversion Coatings.
Application:
The end-use application dictates the performance requirements and regulatory compliance standards for surface treatment chemicals.
- Automotive:This sector demands specialized pretreatments for lightweight materials like aluminum and composites to ensure corrosion resistance and paint adhesion. Tightening environmental regulations in Europe and North America shape formulation development for automotive OEMs.
- Electronics:High-purity acidic and alkaline cleaners are critical for preparing semiconductors and circuit boards, ensuring device reliability and performance. Demand is strong in manufacturing hubs across China and Southeast Asia.
- Aerospace:High-performance coatings and pretreatments are essential for aircraft components, requiring extreme durability and corrosion protection.
- Industrial:Diverse industrial processes utilize surface treatments for machinery, infrastructure, and general manufacturing to enhance longevity.
Specific applications demand specialized chemical formulations for optimal performance and regulatory compliance.
Technology:
The choice of surface treatment technology fundamentally alters the required chemical processes and material interaction.
- Coating:This technology involves applying a protective or functional layer onto a substrate, enhancing properties like wear resistance, aesthetics, and corrosion protection. Paint adhesion in automotive manufacturing heavily relies on advanced coating pretreatments.
- Electroplating:An electrochemical process depositing a thin metal layer onto a conductive surface, primarily for decorative, protective, or functional purposes. The electronics industry uses electroplating for precise contact and circuit formation.
- Anodizing:An electrolytic passivation process forming a thick, protective oxide layer on metal surfaces, particularly aluminum, for durability.
- Passivation:A chemical process creating a passive layer on metal surfaces, typically stainless steel, to prevent corrosion and enhance cleanliness.
Each technology requires precise chemical control to achieve desired surface characteristics and material integrity.
End User:
Different end-user types exhibit distinct purchasing patterns and technical support needs for surface treatment chemicals.
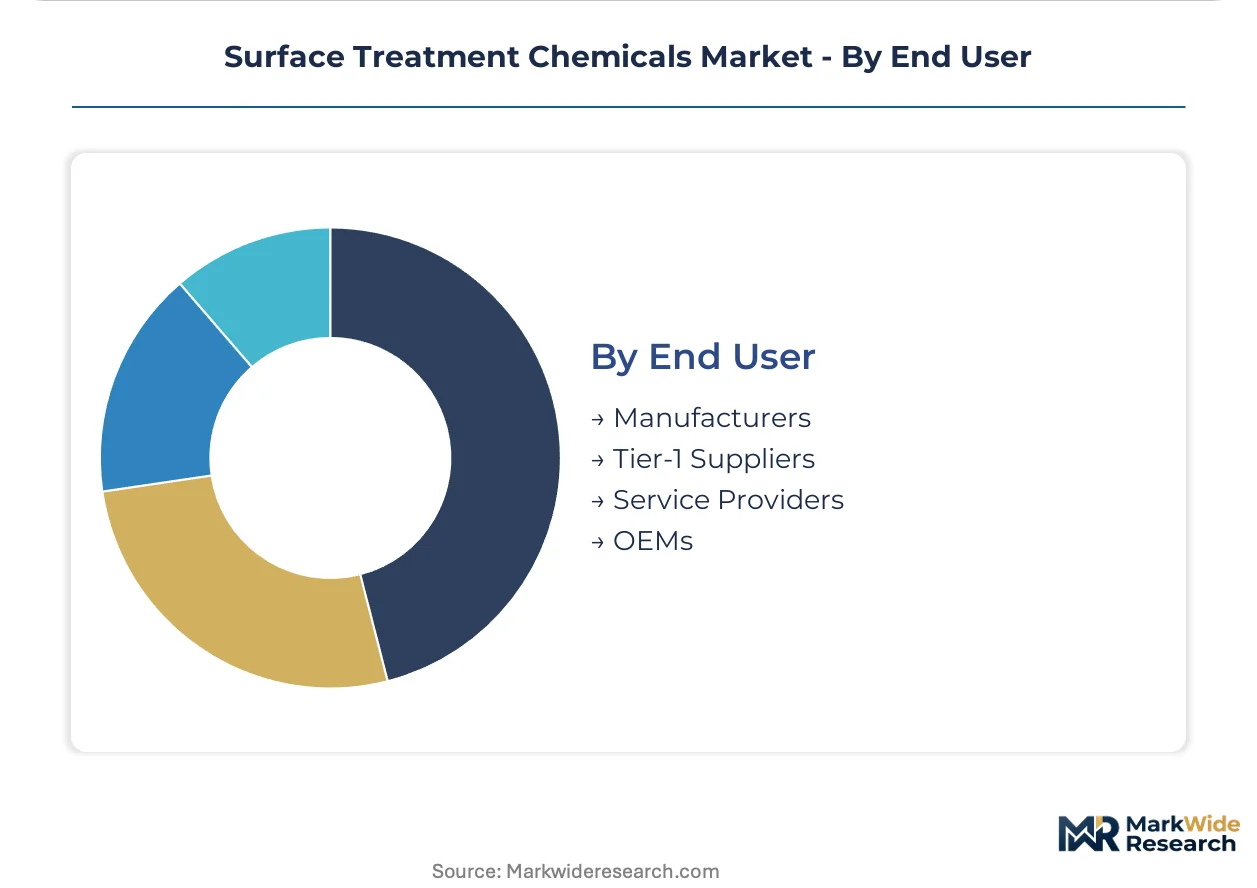
- Manufacturers:This broad segment encompasses diverse industries utilizing surface treatment chemicals for their production lines, from heavy machinery to consumer goods. Their chemical procurement often focuses on cost-effectiveness and process integration.
- OEMs:Original Equipment Manufacturers, particularly in automotive and aerospace, drive demand for highly specialized and certified chemical solutions. They often seek long-term contracts and deep technical partnerships with suppliers.
- Tier-1 Suppliers:These suppliers integrate components for OEMs, requiring surface treatment chemicals that meet stringent specifications and production volumes.
- Service Providers:Companies offering surface treatment services to multiple clients demand versatile chemical solutions and robust technical assistance.
The diverse needs of these end-user segments necessitate tailored chemical solutions and comprehensive technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of surface treatment chemicals is increasingly concentrating in manufacturing hubs, while consumption remains widespread across industrial sectors globally. This creates a complex supply chain dynamic where raw material availability and regulatory compliance vary significantly by region. End-users in diverse industries demand tailored formulations for their specific operational needs.
China
Demand for conversion coatings and high-purity cleaners is strong in China's automotive and electronics manufacturing sectors. The Ministry of Ecology and Environment (MEE) imposes stringent standards on industrial effluents, forcing chemical innovation. Manufacturing clusters in the Yangtze River Delta drive significant consumption for both domestic and export-oriented production.
Germany
Germany's automotive and industrial machinery sectors require advanced surface treatments for corrosion protection and paint adhesion. The EU's REACH regulation mandates the development of environmentally benign and compliant chemical formulations. The Rhine-Ruhr region, a traditional industrial heartland, sees sustained demand from diverse manufacturing operations.
United States
The United States aerospace and automotive industries drive demand for high-performance coatings and specialized pretreatments. The Environmental Protection Agency (EPA) limits volatile organic compounds (VOCs), influencing chemical composition. Manufacturing hubs in the Midwest, particularly around Detroit, utilize surface treatment chemicals for vehicle production.
Japan
Japan's precision electronics and automotive sectors require high-purity acidic and alkaline cleaners for critical applications. METI guidelines encourage sustainable manufacturing practices and resource efficiency in chemical production. Industrial zones in the Kanto region, including Tokyo, support robust demand for advanced surface treatment solutions.
India
India's expanding automotive and aerospace MRO sectors generate demand for specialized coatings and conversion treatments. The national PLI scheme supports domestic manufacturing, increasing the need for local chemical supply. Industrial corridors near Chennai and Pune are hubs for vehicle production, driving significant surface treatment chemical consumption.
Surface Treatment Chemicals Market Key Industry Players
Top-tier vendors anchor the premium segment, while a diverse array of regional and specialized formulators address niche applications. The market structure exhibits a tiered consolidation, with major players holding significant shares in core segments. Strategic archetypes include global chemical conglomerates focusing on R&D, and specialized providers delivering tailored solutions for specific industries. Competitive moves often involve strategic partnerships to meet regulatory requirements and portfolio diversification into sustainable formulations.
Among global chemical conglomerates, Henkel AG & Co. KGaA and BASF exemplify companies leveraging extensive R&D capabilities for sustainable alternatives and integrated technical support. PPG Industries represents a specialist in high-performance coatings, particularly for demanding sectors like aerospace, focusing on product reliability and application expertise. Solvay, another prominent player, occupies a position emphasizing advanced material science for complex industrial applications. These firms increasingly broaden their offerings beyond product sales, providing chemical management and application optimization services aligned with evolving regulatory landscapes.
| Leading Market Players |
|---|
| Nippon Paint Holdings |
| Nihon Parkerizing |
| BASF |
| Solvay |
| Element Solutions |
| Henkel AG & Co. KGaA |
| MKS Atotech |
| The Sherwin-Williams Company |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
The shift towards sustainable, bio-based chemical alternatives fundamentally reshapes cost economics for surface treatment chemicals, simultaneously concentrating supply among R&D-intensive manufacturers. This transition influences both raw material sourcing and end-product pricing strategies.
Pricing Analysis
Margin tightening in the industrial chemicals segment reflects intense competition and input cost volatility tied to petrochemical markets. The dominant pricing model combines contract-based long-term offtake for OEMs with per-unit transactional sales for smaller manufacturers. Price differentiation stems from product certification levels, particularly for aerospace applications, and comprehensive after-sales technical support. Manufacturers of consumer goods often exhibit higher price sensitivity compared to aerospace and automotive OEMs, who prioritize performance and reliability.
Supply Chain Analysis
Certification and qualification requirements for high-performance surface treatment chemicals gate market entry and influence supply chain structure. Production concentrates in China, Germany, and the United States, drawing heavily from specialty solvents and acid inputs. A structural risk involves commodity price volatility for petrochemical-derived raw materials. Distribution runs through a hybrid model, combining direct sales to large OEMs with regional distributors serving diverse industrial manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surface treatment chemicals market is increasingly defined by a vertical-integration race, as players pursue deep integration with automotive OEMs to secure long-term contracts. This strategy aims to capture greater value across the application lifecycle.
For Market Incumbents: To counter the threat of material substitution by self-passivating alloys, incumbents must invest heavily in R&D for advanced pretreatment solutions compatible with new substrates. Deepen existing technical partnerships with automotive and aerospace OEMs to reinforce long-term contract positions. Further, strategic acquisitions of specialized formulators can expand product portfolios into high-growth sustainable chemistry segments. Certification investment in new bio-based systems provides a critical lever against regulatory shifts.
For New Entrants and Emerging Players: Regional distributors represent a key channel for new entrants to access the fragmented industrial segment. Focus on developing high-performance, biodegradable cleaners for the electronics manufacturing hubs in Southeast Asia, a highly penetrable application. Offering subscription-based digital services for process optimization and compliance tracking provides a differentiated go-to-market angle. This approach targets smaller manufacturers seeking cost-effective, compliant solutions without significant upfront investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized chemical formulators with proprietary sustainable technologies or deep integration into niche high-growth applications like aerospace MRO. The long-term viability of this market over a five-to-ten-year window hinges on continuous innovation and regulatory compliance. Target mid-cap companies demonstrating strong R&D in bio-based alternatives and offering robust digital service platforms. A signal to watch is the adoption rate of "smart" chemical baths across diverse industrial sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports localized demand from electronics manufacturing hubs in Vietnam and Thailand. |
| Green Manufacturing Transition | Addresses stringent EU REACH regulations and corporate sustainability goals for chemical production. |
| Long-term Supply Agreements with Automotive OEMs | Secures stable revenue streams and deepens integration with major vehicle manufacturers. |
| Investment in Digital Service Platforms | Creates recurring revenue streams beyond product sales through application optimization software. |
| R&D in Bio-based Formulations | Develops compliant, less-toxic alternatives for diverse industrial and consumer applications. |
Research Approach
Multi-period observation of regulatory shifts, material science advancements, and end-user procurement patterns anchored the trend analysis, supplemented by interviews with plant managers, technical R&D directors, and procurement leads at automotive OEMs. Secondary validation drew from chemical industry association reports, SEC 10-K filings, and customs trade data. This approach ensured robust bottom-up and top-down triangulation of market insights.
An input-output matrix framework analyzed market dynamics across the analysis window, modeling segmentation by product type, application, technology, and regional production hub. Compound Annual Growth Rates were derived from historical data and projected demand drivers. Key forecast inputs included automotive production forecasts and electronics manufacturing output projections.
Caveats apply where unforeseen geopolitical events or rapid technological breakthroughs in material science could materially shift the outlook. Forecasts reflect assumptions documented regarding regulatory stability and raw material availability. A model refresh is warranted upon material change in global manufacturing relocation trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Cobalt Acetate Solution Market