
 Diisobutylaluminum Chloride Market | 2026-2036
Diisobutylaluminum Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Diisobutylaluminum Chloride Market Analytics
Drum-to-tank packaging conversion among bulk buyers is consolidating procurement patterns across the aluminum alkyl supply base. BASF SE leverages integrated C1 chemistry platforms to sustain captive diisobutylaluminum chloride output for polymerization catalyst bundles. Solvay S.A. anchors European supply through backward integration into aluminum metal and olefin feedstocks. Nouryon competes on specification-grade liquid formulations tailored to fluidized-bed polyethylene reactor lines.
Diisobutylaluminum chloride is a pyrophoric organoaluminum compound with empirical formula C8H18AlCl, manufactured via direct synthesis from aluminum powder, hydrogen, and isobutylene followed by chlorination; it serves primarily as a co-catalyst and reducing agent in Ziegler-Natta polymerization systems. Liquid product types dominate volume flows due to ease of metered injection into continuous reactor trains, while concentrated grades capture margin pools from pharmaceutical manufacturers requiring anhydrous conditions. Catalysis applications lead absolute consumption, though pharmaceutical manufacturing represents the fastest-expanding end-use segment as contract development organizations adopt aluminum alkyl-mediated carbonyl chemistry.
EPA regulates diisobutylaluminum chloride under TSCA Section 5 premanufacture notification requirements, while REACH mandates registration and downstream exposure documentation for EU importers; China's MEE enforces hazardous chemical storage standards under GB 15603 that constrain inland distribution logistics. OSHA process safety management rules and NFPA 704 flammability classifications further shape facility siting and capital deployment decisions for producers and users. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect fluoropolymer demand toward polyethylene systems dependent on aluminum alkyl catalysts.
Market Dynamics
Drum-to-tank packaging conversion among bulk polyethylene producers is consolidating procurement volumes and squeezing spot-market liquidity for diisobutylaluminum chloride spot cargoes.
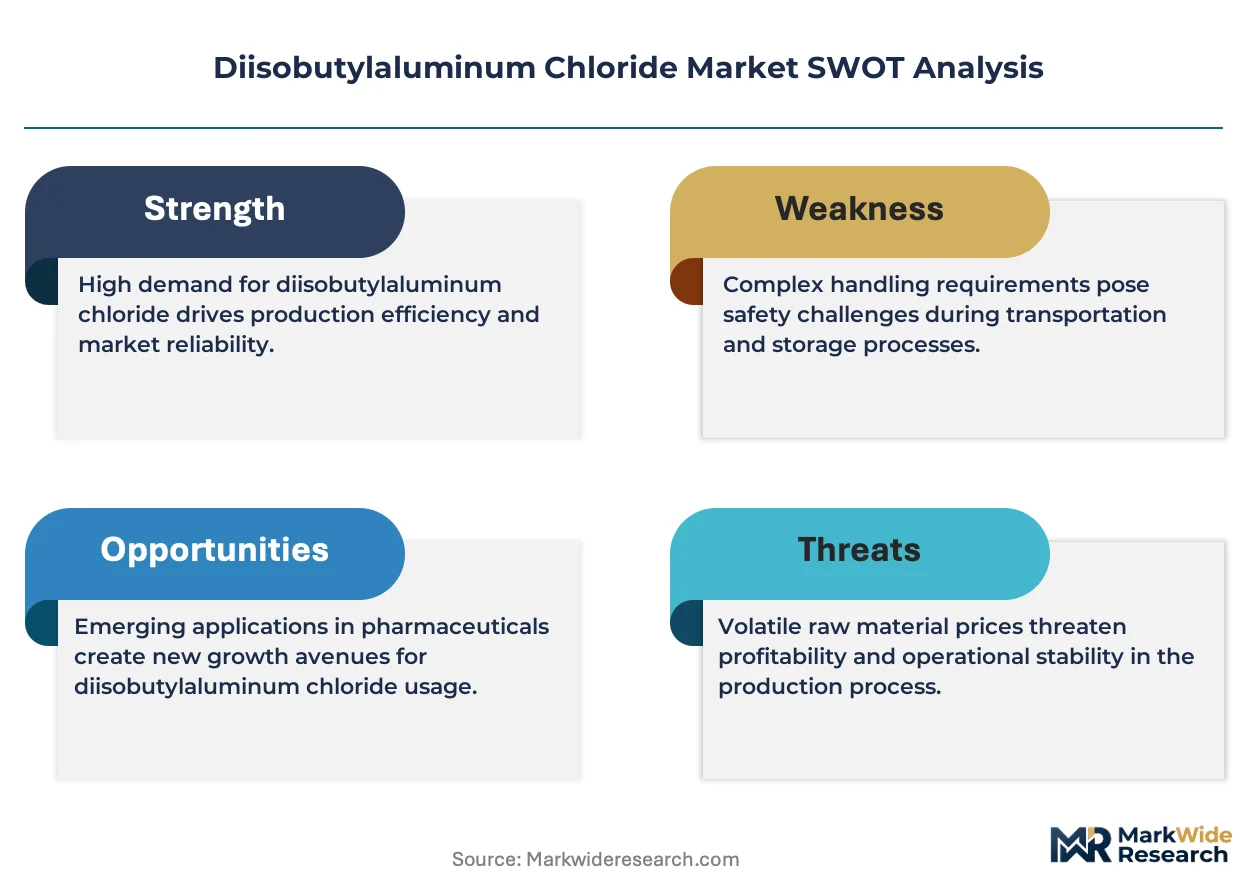
Growth Catalysts
- REACH registration mandates:European importers now document downstream exposure pathways, favoring specification-grade suppliers with established dossiers over opportunistic traders.
- Coal-to-chemical expansion:China's ethylene cracker buildout consumes Ziegler-Natta co-catalyst bundles at scale, pulling diisobutylaluminum chloride volumes eastward.
- Metallocene catalyst adoption:Refiners seeking higher alpha-olefin yields specify aluminum alkyl co-catalysts for single-site polymerization systems.
Market Restraints
- Aluminum metal price volatility:Feedstock cost swings compress margins for non-integrated producers lacking captive aluminum powder supply.
- Pyrophoric handling requirements:NFPA 704 flammability classifications and OSHA process safety management rules inflate facility siting costs and limit greenfield entrants.
- Fluoropolymer substitution risk:Per- and polyfluoroalkyl substance restrictions could redirect demand toward polyethylene systems, though this diverts rather than expands aluminum alkyl consumption.
Strategic Opportunities
- Pharmaceutical CDMO penetration:Contract development organizations adopt aluminum alkyl-mediated carbonyl chemistry for anhydrous synthesis routes.
- India's specialty chemical incentives:PLI scheme benefits and import substitution policies attract catalyst manufacturers to establish local blending operations.
- Fluidized-bed reactor compatibility:Specification-grade liquid formulations tailored to continuous polyethylene trains command premium positioning over drum-packaged alternatives.
Industry Challenges
- Organometallic chemist scarcity:Qualified process safety engineers with pyrophoric materials experience command compensation premiums that inflate operating costs.
- GB 15603 storage compliance:China's hazardous chemical warehousing standards constrain inland distribution logistics and extend order-to-delivery cycles for interior provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diisobutylaluminum Chloride Market |
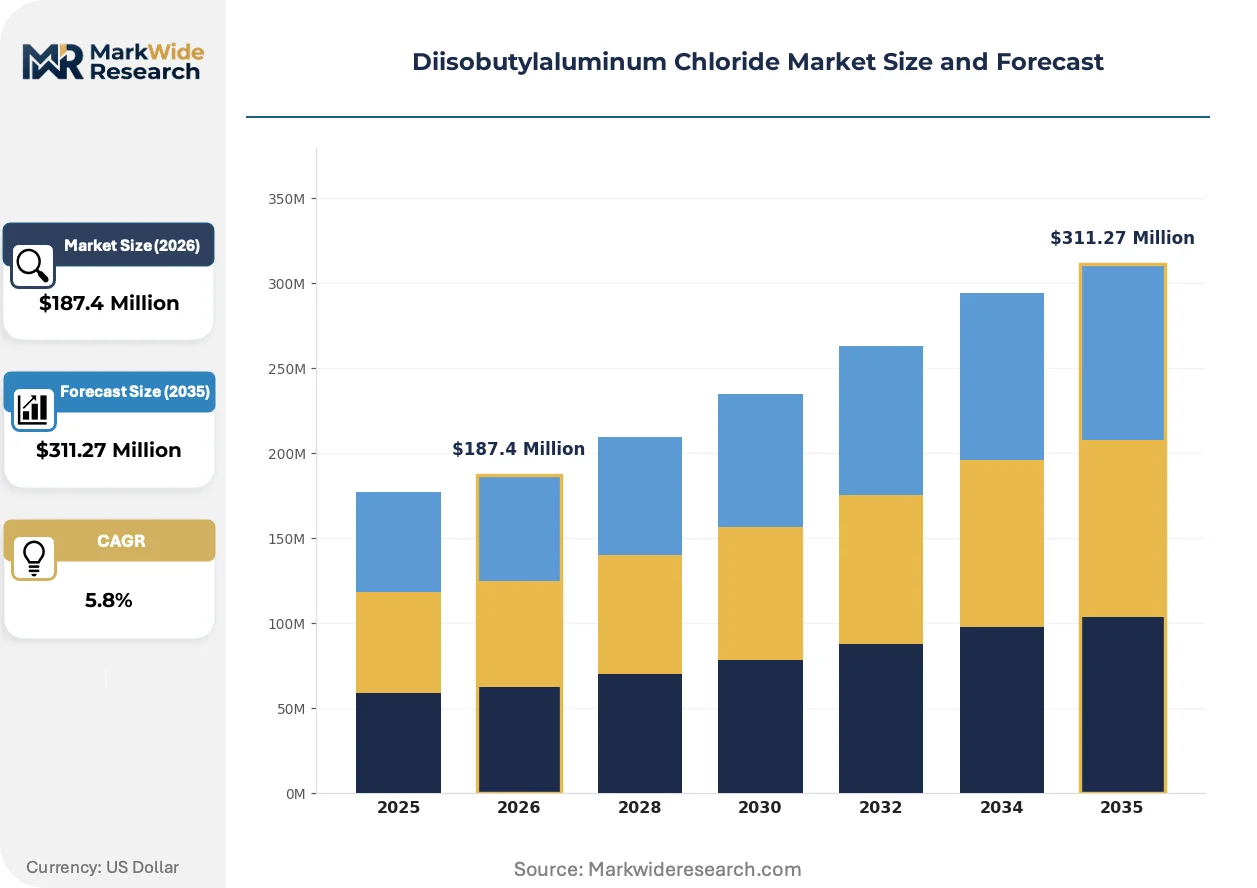
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Polymerization, Chemical Synthesis, Catalysis, Pharmaceutical Manufacturing Product Type: Liquid, Solid, Concentrated, Diluted End User: Chemical Industry, Pharmaceutical Sector, Research Institutions, Academic Labs Packaging Type: Drum, Bottle, Tank, Bulk |
| Companies Covered | BASF SE, Solvay S.A., Gulbrandsen, Aditya Birla Chemicals, Gujarat Alkalies and Chemicals Limited, Nippon Light Metal Company Ltd., Nippon Soda Co. Ltd., Kemira Oyj, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diisobutylaluminum Chloride Market Evolving Landscape
Packaging standardization and regulatory disclosure requirements are compressing supplier fragmentation while opening margin pools for specification-grade formulations.
Metallocene-based single-site catalyst systems is rewriting competitive positioning in polyethylene production. Polymer producers in the US Gulf Coast and Rotterdam-Antwerp corridor are retrofitting reactor trains to accept aluminum alkyl co-catalysts at higher molar ratios. This technology is compressing demand for conventional Ziegler-Natta systems while expanding absolute volumes for high-purity diisobutylaluminum chloride grades.
Evolving EPA toxics thresholds under TSCA Section 5 are tightening purity specifications for aluminum alkyl imports into US polymerization facilities. The industrial consequence is a bifurcation between specification-grade suppliers with premanufacture notification clearances and traders facing extended review timelines. Pharmaceutical manufacturers requiring anhydrous conditions are most affected, responding by consolidating qualified supplier lists to three or fewer approved vendors.
Buyer concentration among integrated polyethylene producers is compressing spot-market liquidity and extending contract durations. Large ethylene crackers in Texas, Louisiana, and Zhejiang province now negotiate three-year supply agreements with fixed-volume, indexed-pricing structures. This pattern is most visible in China, where coal-to-chemical complexes consume co-catalyst bundles at scales that dwarf historical spot-market transactions.
Diisobutylaluminum Chloride Market Segmentation
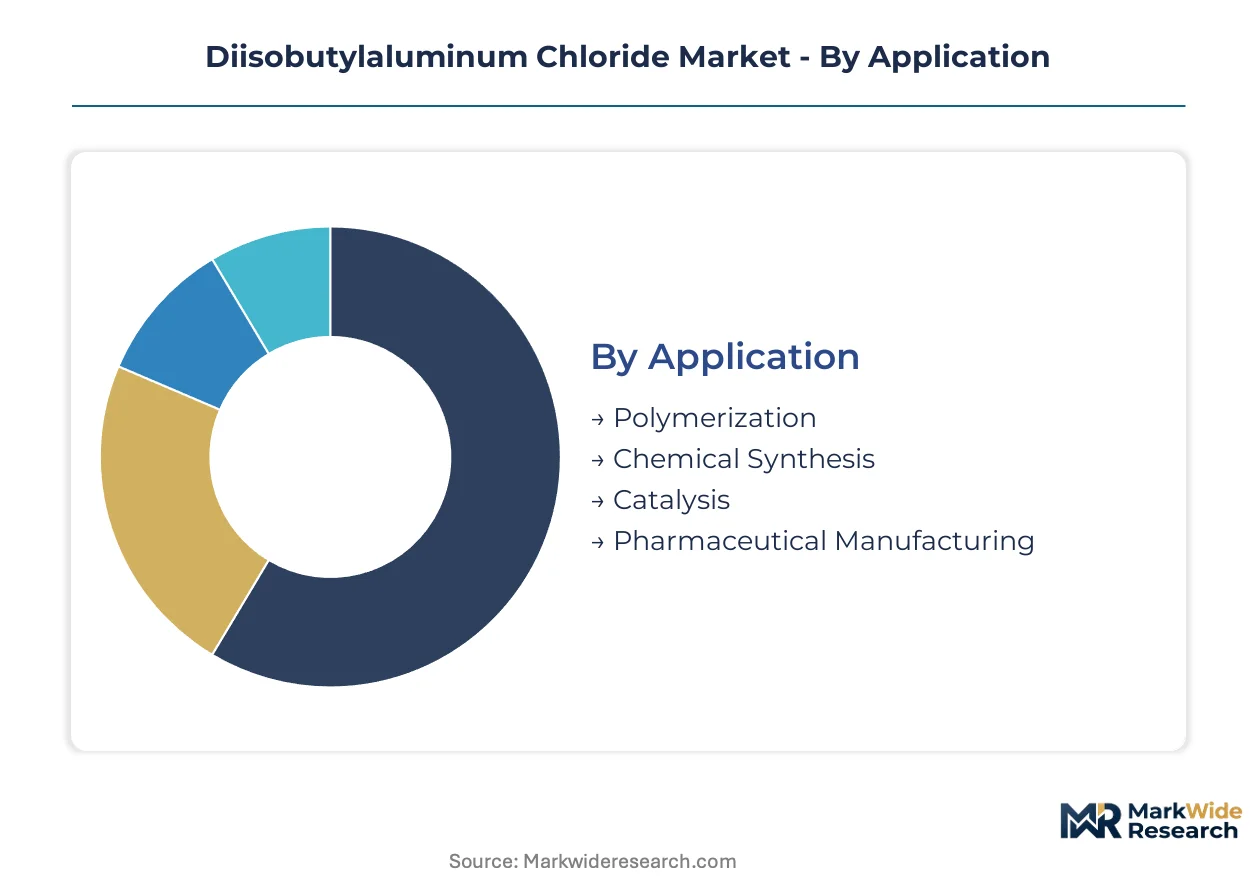
Diisobutylaluminum chloride procurement patterns diverge sharply across application intensity and handling protocols. Buyers with continuous reactor trains favor specification-grade liquid formulations in bulk packaging, while batch pharmaceutical manufacturers tolerate drum-packaged concentrated grades despite higher per-unit costs.
Application:
Upgrade cycles in polyethylene production are displacing legacy Ziegler-Natta systems with metallocene-based alternatives that demand higher-purity aluminum alkyl co-catalysts.
- Polymerization:Ziegler-Natta and metallocene catalyst systems consume diisobutylaluminum chloride as a co-catalyst for alpha-olefin polymerization. Ethylene crackers in Texas, Louisiana, and Zhejiang province specify this grade for continuous reactor injection, with metallocene retrofitting driving purity upgrades across installed capacity.
- Catalysis:Refinery alkylation and oligomerization units employ aluminum alkyls as Lewis acid catalysts for olefin transformation. Demand concentrates in fluidized-bed reactor lines requiring metered liquid injection, where specification-grade formulations command premium positioning over commodity alternatives.
- Chemical Synthesis:Carbonyl chemistry applications in fine chemical manufacturing utilize the compound as a reducing agent for selective transformations.
- Pharmaceutical Manufacturing:Contract development organizations adopt anhydrous aluminum alkyl-mediated routes for active pharmaceutical ingredient synthesis, representing the steepest expansion trajectory as CDMOs consolidate qualified supplier lists.
Polymerization sits at the top of the volume ranking, with Pharmaceutical Manufacturing climbing the fastest.
Product Type:
Cost tiering separates specification-grade liquids from solid and diluted alternatives, with purity premiums widening as EPA toxics thresholds tighten import specifications.
- Liquid:Standard industrial grade with 15-20% concentration in hydrocarbon solvent enables metered injection into continuous reactor trains. BASF SE and Solvay S.A. dominate supply of specification-grade liquids for fluidized-bed polyethylene systems, with drum-to-tank packaging conversion consolidating procurement among integrated producers.
- Concentrated:Anhydrous grades exceeding 90% purity serve pharmaceutical manufacturers requiring moisture-free conditions for carbonyl chemistry. REACH registration mandates and TSCA Section 5 premanufacture notification requirements constrain qualified supplier counts to three or fewer approved vendors in major markets.
- Solid:Crystalline or powder forms for specialized research applications with extended shelf stability.
- Diluted:Lower-concentration solutions for academic and small-scale industrial users with limited handling infrastructure.
Liquid formulations dominate absolute consumption, with Concentrated grades gaining share fastest on pharmaceutical demand.
End User:
Customer type determines packaging scale and safety infrastructure requirements, with chemical industry buyers driving bulk tank adoption while research institutions remain locked in drum procurement.
- Chemical Industry:Integrated polyethylene producers and coal-to-chemical complexes in China consume co-catalyst bundles at scales that compress spot-market liquidity. Three-year supply agreements with fixed-volume, indexed-pricing structures now predominate among ethylene cracker operators.
- Pharmaceutical Sector:Multinational drug manufacturers and contract development organizations specify anhydrous concentrated grades for GMP-compliant synthesis routes. OSHA process safety management rules and NFPA 704 flammability classifications inflate facility siting costs, limiting approved vendor pools.
- Research Institutions:National laboratories and industrial research centers employ aluminum alkyls for organometallic chemistry development.
- Academic Labs:University chemistry departments utilize small-volume drum packaging for undergraduate and graduate research training.
Chemical Industry sits at the top of the volume ranking, with Pharmaceutical Sector expanding most quickly on CDMO outsourcing trends.
Packaging Type:
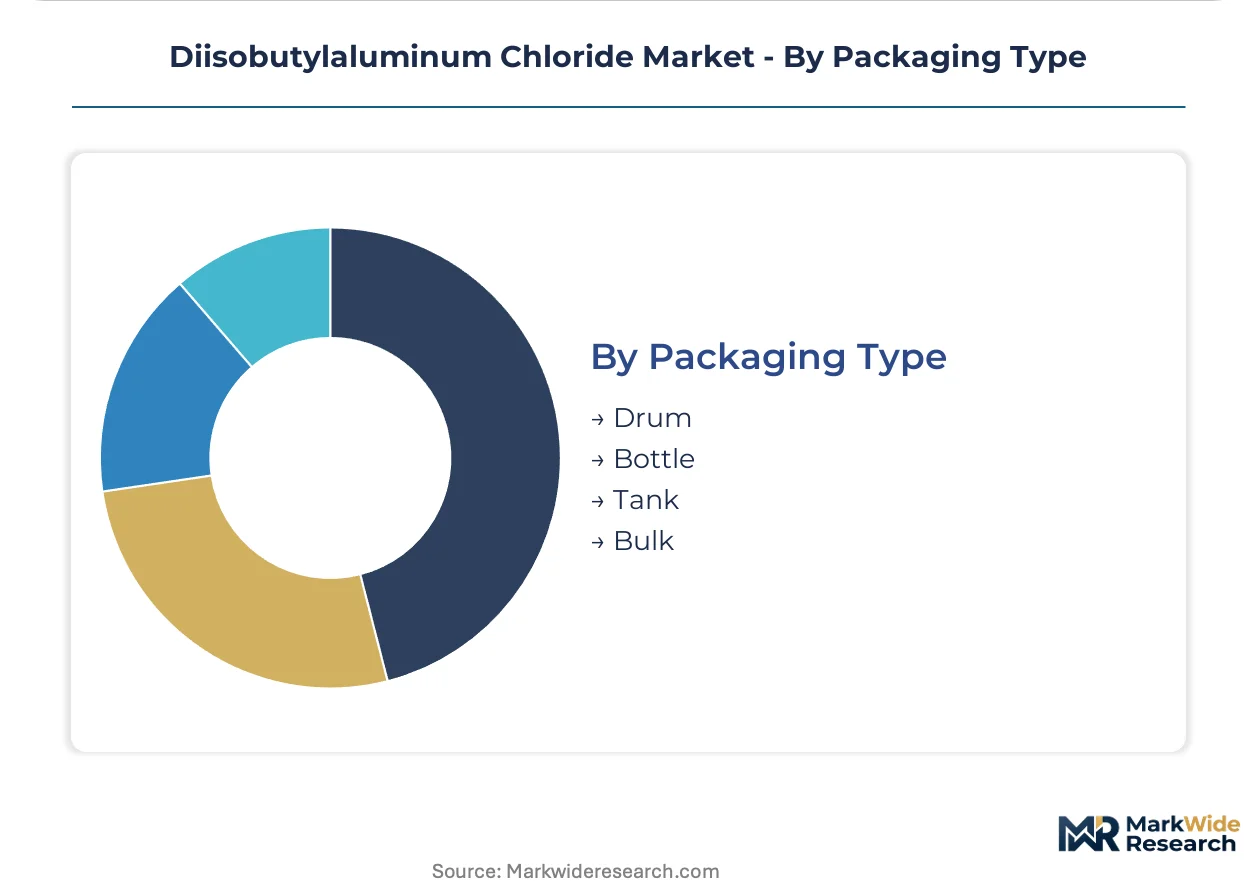
Supply concentration among bulk buyers is eliminating spot-market liquidity for drum-packaged spot cargoes while extending contract durations for tank-based delivery systems.
- Tank:Dedicated tanker or iso-tank delivery for continuous reactor trains at ethylene crackers and coal-to-chemical complexes. China's GB 15603 hazardous chemical storage standards constrain inland distribution logistics, favoring coastal production facilities with direct pipeline or tanker access.
- Bulk:Intermediate bulk containers and totes for mid-scale chemical manufacturers with periodic batch requirements.
- Drum:Standard 200-liter steel drums with nitrogen blanket for pyrophoric protection, serving spot-market buyers and smaller polymerization facilities. Drum-to-tank conversion among bulk polyethylene producers is squeezing spot-market availability and extending order-to-delivery cycles.
- Bottle:Small-volume glass or specialized containers for pharmaceutical and research applications requiring precise aliquoting.
Tank packaging sits at the top of the volume ranking, with Bottle formats gaining traction fastest on pharmaceutical precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale production of diisobutylaluminum chloride originated in Germany during the post-war expansion of Ziegler-Natta catalysis, with BASF SE establishing foundational manufacturing capacity along the Rhine chemical corridor. This heritage shaped subsequent geographic concentration patterns.
United States
Ethylene crackers along the Texas-Louisiana Gulf Coast consume specification-grade aluminum alkyl co-catalysts for metallocene retrofitting. EPA regulates imports under TSCA Section 5 premanufacture notification, tightening purity thresholds for polymerization facilities. Houston and Lake Charles host integrated polyethylene producers negotiating three-year supply agreements with indexed pricing.
Germany
BASF SE maintains captive production through integrated C1 chemistry platforms serving European polymerization catalyst demand. REACH mandates downstream exposure documentation, favoring established registrants over opportunistic traders. Ludwigshafen anchors supply chain coordination for fluidized-bed reactor formulations across the Rotterdam-Antwerp corridor.
China
Coal-to-chemical complexes in Zhejiang and Shandong provinces pull aluminum alkyl volumes eastward for ethylene cracker operations. MEE enforces GB 15603 hazardous chemical storage standards that constrain inland distribution logistics. Ningbo and Shanghai coastal facilities dominate procurement through direct tanker access, extending order-to-delivery cycles for interior provinces.
Japan
Nippon Light Metal and Nippon Soda anchor domestic supply for specialty polymerization applications requiring high-purity grades. METI industrial chemical regulations align with international handling protocols for pyrophoric organometallics. Chubu and Kansai industrial belts concentrate demand from precision polyethylene manufacturers serving automotive and electronics sectors.
India
Aditya Birla Chemicals and Gujarat Alkalies leverage domestic aluminum metal access for regional catalyst blending operations. PLI scheme incentives attract specialty chemical investments targeting import substitution in polymerization systems. Gujarat's chemical corridor hosts expanding capacity for Ziegler-Natta co-catalyst production serving South Asian polyethylene markets.
Diisobutylaluminum Chloride Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification-grade certification and pyrophoric handling infrastructure. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive aluminum supply, regional specialists with backward integration into metal feedstocks, and formulation blenders competing on liquid delivery logistics. Dominant competitive moves include capacity expansion adjacent to ethylene cracker clusters and strategic partnerships for pharmaceutical-grade certification.
Among European-based chemical conglomerates, BASF SE and Solvay S.A. occupy positions exemplifying integrated production archetypes, while Nouryon represents the specification-grade formulation specialist tier. These anchors reflect geographic concentration patterns where Rhine corridor heritage and Rotterdam-Antwerp logistics access determine competitive positioning. Gulbrandsen and Kemira Oyj illustrate North American and Nordic regional specialist models respectively, with company structures indicating diversified chemical portfolios rather than pure-play aluminum alkyl dependence.
| Leading Market Players |
|---|
| BASF SE |
| Solvay S.A. |
| Gulbrandsen |
| Aditya Birla Chemicals |
| Gujarat Alkalies and Chemicals Limited |
| Nippon Light Metal Company Ltd. |
| Nippon Soda Co. Ltd. |
| Kemira Oyj |
| Nouryon |
| Others |
Value Network & Pricing Analysis
Family-owned aluminum metal producers in Germany and Japan anchor upstream supply discipline, translating captive feedstock control into stable pricing for specification-grade co-catalyst bundles while spot-market traders absorb aluminum powder cost volatility.
Pricing Analysis
Three-tier pricing structure across specification-grade, industrial-grade, and research-grade levels separates pharmaceutical-certified anhydrous formulations from commodity polymerization liquids. Price differentiation rests on REACH registration status and TSCA Section 5 clearance tier, with unregistered traders facing extended review timelines that compress their viable pricing bands. Pricing pressure stems from aluminum metal cost swings that squeeze non-integrated blenders. Chemical industry buyers with three-year offtake contracts show lowest price sensitivity, while academic labs purchasing drum quantities face highest per-unit costs.
Supply Chain Analysis
Dual-sourcing mandates from polyethylene producers in Texas and Zhejiang province require qualified backup suppliers for pyrophoric co-catalyst delivery, constraining vendor pools to registrants with proven handling infrastructure. Geographic supply concentrates in Germany, China, and Japan, with BASF SE and Nippon Light Metal anchoring regional production clusters. Raw material flows draw from aluminum powder smelters, isobutylene crackers, and chlorination chemical processors. Single-source vulnerability runs through aluminum metal supply, where energy-intensive smelter economics tether pricing to electricity cost curves. Distribution runs through dedicated tanker fleets for bulk chemical buyers, with drum logistics serving residual spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on pharmaceutical-grade certification premiums offsetting aluminum feedstock volatility, as CDMO consolidation concentrates purchasing power among specification-grade vendors.
For Market Incumbents: Deploy backward integration into aluminum powder supply to defend margins against feedstock cost swings threatening non-integrated blenders. BASF SE's captive C1 chemistry platform exemplifies this lever, insulating polymerization catalyst bundles from spot metal markets. Incumbents should simultaneously deepen pharmaceutical-grade certification investments, as TSCA Section 5 and REACH dossier requirements constrain qualified supplier counts to three or fewer approved vendors in major markets. For New Entrants and Emerging Players: Fluidized-bed reactor compatibility formulations represent the most penetrable wedge for specification-grade market entry, targeting polyethylene producers retrofitting metallocene systems in the US Gulf Coast and Rotterdam-Antwerp corridor. India's PLI scheme incentives offer geographic white-space for catalyst blending operations serving South Asian import substitution. New entrants should pursue toll-manufacturing partnerships with established aluminum metal suppliers to bypass pyrophoric handling infrastructure capital barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with backward integration into aluminum feedstocks but lacking pharmaceutical-grade certification infrastructure. Long-term viability over the next decade depends on capturing CDMO outsourcing trends in anhydrous carbonyl chemistry. Investors should monitor REACH registration renewal timelines as inflection signals, where dossier expiration could disqualify incumbent suppliers and reopen vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Metal | Captive feedstock supply insulates margin from LME price volatility affecting non-integrated competitors. |
| Pharmaceutical-Grade Certification Investment | TSCA Section 5 and REACH dossiers constrain qualified suppliers to three or fewer approved vendors. |
| Fluidized-Bed Reactor Formulation Development | Metallocene retrofitting in Texas and Zhejiang drives premium positioning for specification-grade liquids. |
| Long-Term Supply Agreement Structuring | Three-year indexed contracts with ethylene crackers compress spot-market liquidity and stabilize revenue. |
| Joint Venture in India PLI Corridor | Gujarat chemical cluster offers import substitution positioning for South Asian polyethylene markets. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each region's chemical manufacturing clusters. The approach combines interviews with plant managers at ethylene cracker facilities, procurement leads at polymerization catalyst buyers, distribution channel partners handling pyrophoric logistics, and technical R&D directors at aluminum alkyl producers. Secondary validation draws from EPA TSCA filings, ECHA REACH registration databases, SEC 10-K disclosures from listed chemical conglomerates, and ACC industry production surveys. Bottom-up demand modeling from end-use applications triangulates against top-down supply capacity estimates from major production facilities.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. The framework models segmentation across grade tier (specification-grade liquid, concentrated anhydrous, solid, diluted), end-use industry (polymerization, pharmaceutical manufacturing, refinery catalysis, chemical synthesis), packaging format (tank, bulk, drum, bottle), and regional production hub. CAGRs derive from historical consumption patterns adjusted for technology substitution effects, specifically metallocene catalyst adoption displacing conventional Ziegler-Natta systems. Forecast inputs incorporate aluminum metal price elasticity, ethylene cracker capacity buildout schedules, and pharmaceutical CDMO outsourcing trajectories.
The model holds under stable regulatory clearance pathways for aluminum alkyl imports; deviation in TSCA Section 5 review timelines or REACH dossier renewal outcomes would shift supplier competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Chlorine Market