
 Continuous Reactors Market | 2026-2036
Continuous Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Reactors Market Insights
Stainless steel is repositioning product economics as advanced alloys replace carbon steel in high-pressure continuous reactor vessels, extending equipment lifespan and reducing maintenance downtime. BASF SE leverages its Ludwigshafen integrated site to sustain captive production of specialty chemicals via continuous stirred-tank and tubular systems. Corning Incorporated anchors the microreactor segment through its Advanced-Flow reactor technology, dominating laboratory-to-production scale transitions. Dow Chemical Company competes across petrochemical applications with loop reactor configurations for polyethylene production.
Continuous reactors are vessels designed for uninterrupted material flow where reactants enter and products exit simultaneously, typically operating at controlled temperatures between 150°C and 350°C and pressures up to 200 bar depending on the reaction chemistry. These systems enable precise residence time distribution, superior heat transfer coefficients, and higher throughput-to-footprint ratios than batch alternatives, serving primary purposes in chemical synthesis, polymerization, and pharmaceutical active ingredient manufacture. Tubular and plug flow reactor types command the largest installed base due to their simplicity and suitability for fast, exothermic reactions, while fluidized bed configurations represent the fastest-expanding category driven by catalytic cracking and biomass conversion applications. Microwave-assisted and photochemical technologies are gaining traction in pharmaceutical fine chemical production where selective activation reduces side-product formation and solvent consumption.
The EPA enforces Maximum Achievable Control Technology standards that favor continuous processes with lower fugitive emissions profiles, while OSHA's Process Safety Management regulations push refineries toward inherently safer continuous designs with reduced inventory volumes. REACH compliance in Europe mandates detailed substance registration that continuous manufacturers navigate through integrated analytical monitoring and real-time quality assurance systems. Stakeholders must monitor how the EU Green Deal's carbon border adjustment mechanism reshapes competitiveness for export-oriented continuous chemical producers in energy-intensive segments.
Market Dynamics
The EPA's Maximum Achievable Control Technology standards are compressing batch-to-continuous conversion timelines as processors face escalating compliance costs and emission permit restrictions.
Growth Catalysts
- REACH registration integration:European specialty chemical manufacturers deploy continuous systems with real-time analytical monitoring to streamline substance documentation and batch traceability.
- Heat transfer coefficient demands:Fast exothermic reactions in pharmaceutical active ingredient production favor tubular reactor geometries over conventional batch vessels.
- German integrated chemical parks:BASF's Ludwigshafen and Evonik's Marl sites demonstrate captive continuous processing infrastructure that locks in regional supply chain density.
Market Restraints
- High-alloy steel input volatility:Nickel and molybdenum price swings directly compress margins for pressure vessel fabricators serving 200-bar operating specifications.
- Specialized fabricator concentration:ASME-certified vessel construction capacity clusters in Germany, Japan, and the US Gulf Coast, creating 18-24 month delivery backlogs.
- Batch flexibility premium:Multi-product contract manufacturers retain stirred-tank assets for low-volume, high-margin custom synthesis where continuous economics fail.
Strategic Opportunities
- Biomass conversion catalytic cracking:Fluidized bed reactor deployments for lignocellulosic feedstock processing open addressable capacity in Nordic and Baltic markets.
- Photochemical-microwave convergence:Selective activation technologies reduce solvent consumption in fine chemical production, aligning with EU Green Deal carbon border adjustment positioning.
- Modular skid-mounted systems:Containerized continuous units enable distributed pharmaceutical manufacturing closer to point-of-care demand in mid-tier US and European hospital networks.
Industry Challenges
- Residence time distribution modeling:Computational fluid dynamics expertise scarcity extends pilot-to-production scale-up timelines for complex reaction chemistries.
- Legacy DCS integration:Brownfield continuous reactor installations face protocol incompatibility with existing distributed control systems from 1990s-vintage batch operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Reactors Market |
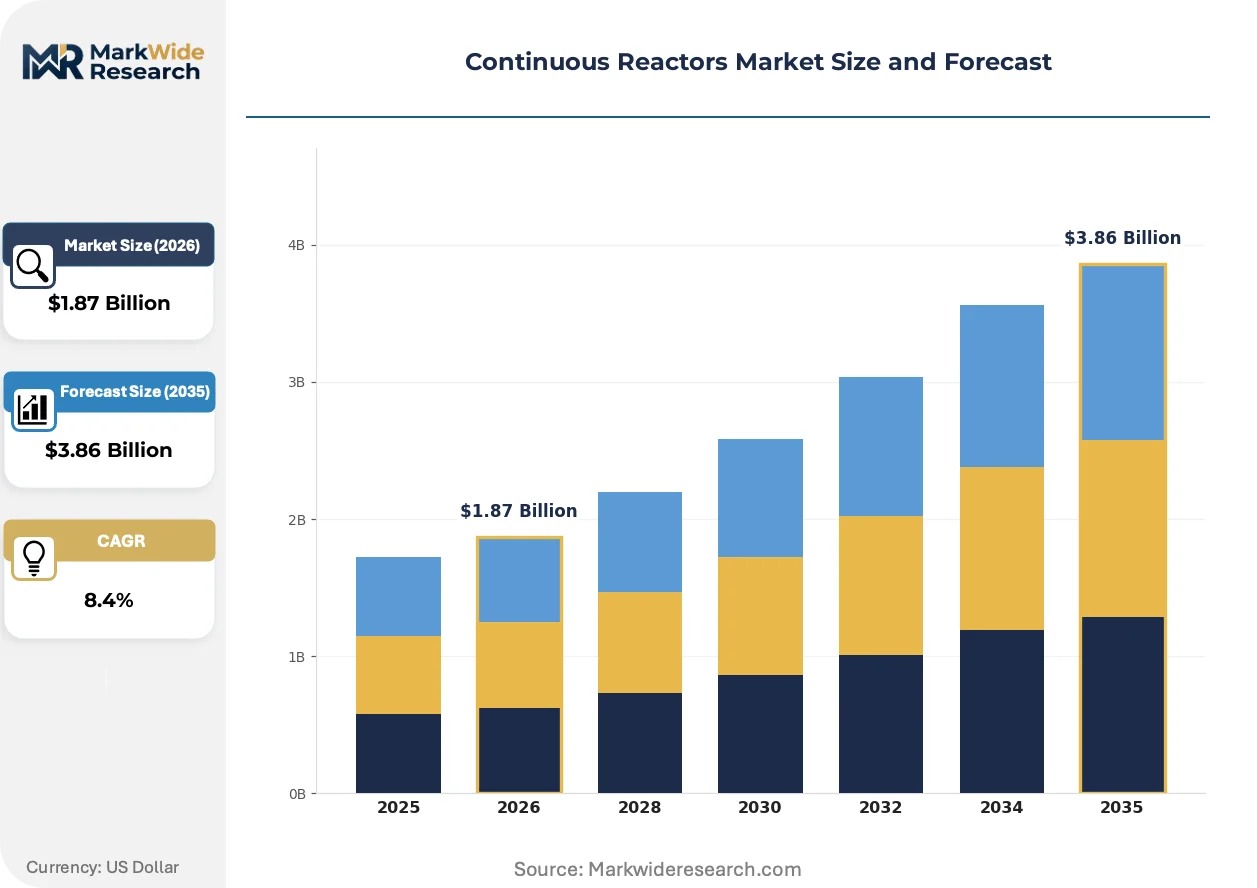
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.86 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Reactor Type: Plug Flow, Tubular, Stirred Tank, Packed Bed, Loop, Fluidized Bed Application: Chemical Synthesis, Polymer Production, Pharmaceuticals, Petrochemical Processing, Food Processing, Water Treatment Technology: Catalytic, Non-Catalytic, Microwave-Assisted, Ultrasonic, Photochemical, Electrochemical End User Industry: Refineries, Specialty Chemicals, Agrochemical Plants, Biotech Firms, Cosmetics Manufacturers, Food & Beverage Producers |
| Companies Covered | Evonik Industries AG, SABIC, BASF SE, LG Chem Ltd., Mitsubishi Chemical Corporation, Dow Chemical Company, LyondellBasell Industries N.V., Corning Incorporated, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Reactors Market Trends and Innovations
Process intensification architectures are compressing reactor footprints while elevating throughput density, fundamentally altering capital deployment patterns for greenfield chemical manufacturing investments.
Advanced stainless alloys with enhanced creep resistance are integrating into high-pressure tubular reactor designs, enabling sustained operation at 350°C and 200-bar conditions without scheduled downtime for vessel replacement. Pharmaceutical manufacturers in Switzerland and New Jersey are specifying these materials for multi-year campaigns of high-value active pharmaceutical ingredients. The technology is integrating predictive maintenance protocols that extend mean time between failures beyond traditional carbon steel depreciation cycles.
The EU Green Deal's carbon border adjustment mechanism is tightening emission accounting requirements for imported chemical products, compelling continuous reactor operators to document energy intensity per unit output. German and Dutch processors are retrofitting heat integration networks to capture exothermic reaction energy for upstream preheating. Petrochemical exporters in the US Gulf Coast and Middle East are responding with parallel continuous system investments to preserve European market access.
Specialty chemical buyers are consolidating supplier panels and demanding captive continuous processing commitments with guaranteed yield consistency specifications. Large agrichemical and coatings formulators in the US Midwest and Rhine-Ruhr corridor are awarding five-year sole-source contracts contingent on batch-to-batch variation below 2% coefficient of variation. This concentration is visible most acutely in pharmaceutical intermediates, where FDA quality agreements now mandate continuous manufacturing technology transfer for new molecular entity approvals.
Continuous Reactors Market Segmentation
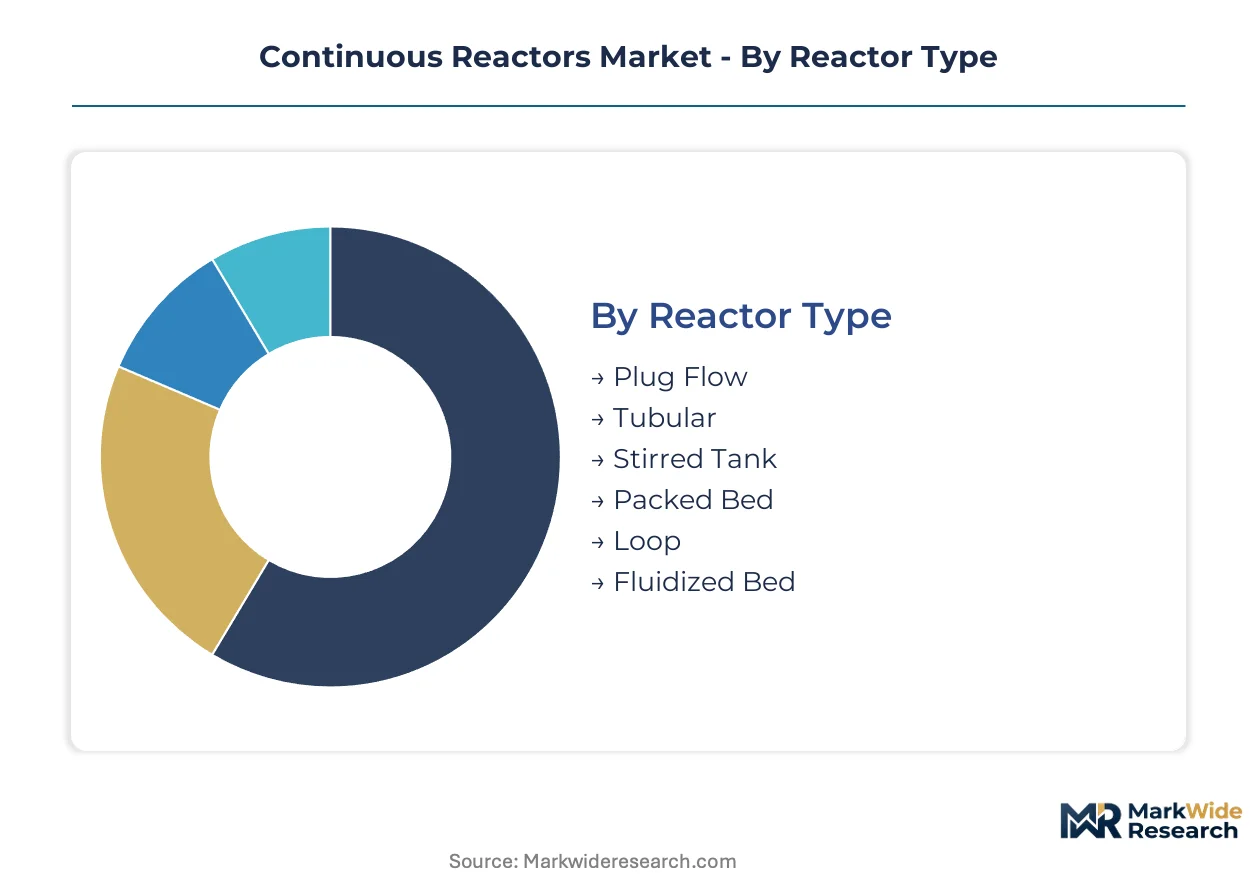
Continuous reactor selection hinges on reaction kinetics, heat management requirements, and regulatory compliance intensity. Each segmentation axis reveals distinct procurement patterns and technology migration paths across chemical processing industries.
Reactor Type:
Pressure containment geometry and residence time control define the technology hierarchy in this market.
- Tubular:Straight-through pipe configurations with minimal backmixing deliver precise residence time distribution for fast exothermic reactions. Pharmaceutical manufacturers in Switzerland and New Jersey specify these systems for high-value active pharmaceutical ingredient campaigns requiring tight thermal control.
- Fluidized Bed:Solid catalyst suspension enables superior heat transfer and continuous catalyst regeneration for catalytic cracking operations. Nordic biomass conversion facilities are deploying these configurations for lignocellulosic feedstock processing under EU Green Deal carbon accounting frameworks.
- Plug Flow:Ideal piston-flow characteristics suit polymerization reactions where molecular weight distribution control is critical.
- Stirred Tank:Backmixed operation provides flexibility for multi-product campaigns in specialty chemical contract manufacturing.
- Packed Bed:Fixed catalyst configurations dominate gas-phase petrochemical processing with established pressure drop correlations.
- Loop:Circulating slurry systems anchor polyethylene production for Dow Chemical and similar petrochemical operators.
Mature deployment sits with Tubular systems. Newer deployment is concentrated in Fluidized Bed configurations.
Application:
Process economics and regulatory scrutiny intensity shape demand concentration across end-use sectors.
- Chemical Synthesis:Continuous flow enables precise stoichiometric control for fine chemical production with reduced solvent inventory. German integrated chemical parks at Ludwigshafen and Marl leverage tubular and stirred-tank systems for captive specialty chemical output.
- Pharmaceuticals:FDA quality agreements now mandate continuous manufacturing technology transfer for new molecular entity approvals. Swiss and New Jersey facilities lead implementation of microwave-assisted and photochemical systems for selective activation.
- Polymer Production:Loop reactor configurations dominate polyethylene manufacturing with superior molecular weight control.
- Petrochemical Processing:Fluidized catalytic cracking units anchor refinery conversion capacity.
- Food Processing:Sanitary-design continuous systems support high-volume ingredient manufacture.
- Water Treatment:Advanced oxidation processes deploy photochemical and electrochemical reactor technologies.
Regulatory pressure is stiffest in Pharmaceuticals. Capital deployment is heaviest in Chemical Synthesis.
Technology:
Activation mechanism selection determines energy efficiency and selectivity profiles for target reaction pathways.
- Catalytic:Heterogeneous and homogeneous catalyst systems enable lower-temperature operation with improved atom economy. Refinery fluidized catalytic crackers and biomass conversion facilities represent the largest installed base.
- Photochemical:Selective wavelength activation reduces side-product formation in pharmaceutical fine chemical synthesis. EU Green Deal solvent reduction mandates accelerate adoption across Rhine-Ruhr corridor processors.
- Non-Catalytic:Thermal cracking and pyrolysis systems serve heavy hydrocarbon upgrading without catalyst deactivation concerns.
- Microwave-Assisted:Rapid volumetric heating shortens reaction times for laboratory-to-production scale transitions.
- Ultrasonic:Cavitation-enhanced mass transfer benefits multiphase reaction systems.
- Electrochemical:Direct electron transfer enables oxidation and reduction chemistry without stoichiometric reagent consumption.
Established capacity concentrates in Catalytic systems. Steepest expansion trajectory belongs to Photochemical technologies.
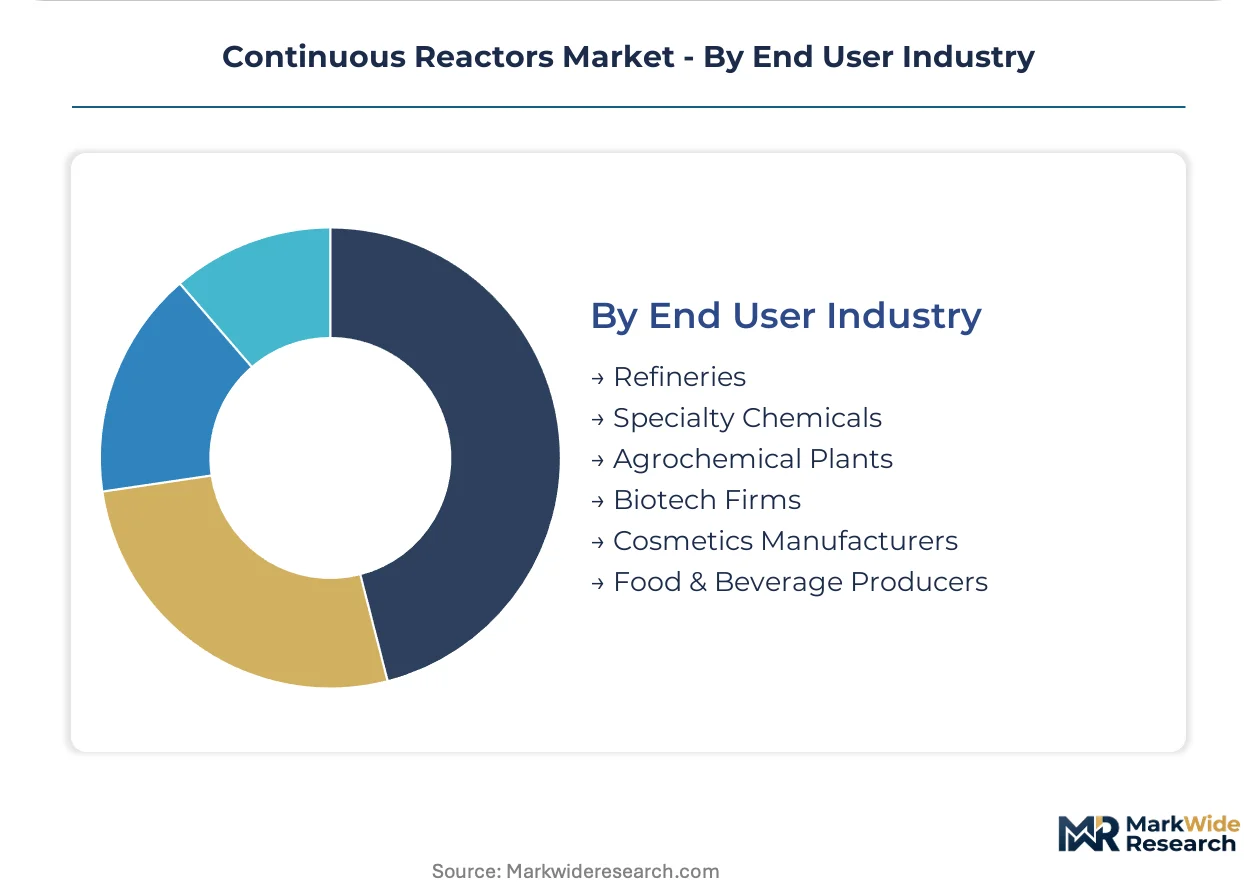
End User Industry:
Capital intensity and yield consistency requirements differentiate procurement behavior across customer segments.
- Specialty Chemicals:Multi-product flexibility demands drive hybrid continuous-batch configurations with integrated analytical monitoring for REACH compliance. BASF and Evonik operate extensive captive infrastructure at German integrated sites.
- Biotech Firms:Continuous fermentation and enzymatic processing require sterile-design systems with precise pH and dissolved oxygen control. Swiss pharmaceutical clusters specify advanced alloys for multi-year campaigns.
- Refineries:Fluidized catalytic crackers and hydroprocessing units represent the largest continuous reactor installed base by throughput volume.
- Agrochemical Plants:Herbicide and pesticide intermediate production favors plug flow systems for exothermic nitration chemistry.
- Cosmetics Manufacturers:Lower-pressure stirred-tank systems support emulsion and surfactant production.
- Food & Beverage Producers:Sanitary tubular reactors enable high-volume ingredient processing with clean-in-place protocols.
Technology leadership resides with Specialty Chemicals. Fastest capacity addition is occurring in Biotech Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical demand concentrates in Germany, where integrated chemical parks lock in regional supply chain density for continuous processing infrastructure. The United States and China follow as secondary centers, driven by petrochemical expansion and pharmaceutical manufacturing scale-up respectively.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts deploy continuous flow systems for FDA-mandated technology transfers of new molecular entities. EPA Maximum Achievable Control Technology standards compress batch-to-continuous conversion timelines for processors facing emission permit restrictions. The Gulf Coast petrochemical corridor anchors loop reactor deployments for polyethylene production.
Germany
BASF and Evonik operate captive continuous processing infrastructure at Ludwigshafen and Marl integrated sites, locking in regional specialty chemical supply chains. REACH compliance mandates real-time analytical monitoring systems that streamline substance documentation and batch traceability. The Rhine-Ruhr corridor leads EU Green Deal heat integration retrofits to capture exothermic reaction energy.
China
Petrochemical expansion along the Yangtze River Delta drives fluidized bed reactor installations for catalytic cracking capacity. National dual carbon goals pressure processors toward continuous systems with lower energy intensity per unit output. The Shandong Peninsula hosts concentrated pressure vessel fabrication serving domestic 200-bar specification demand.
Switzerland
Pharmaceutical clusters in Basel specify advanced stainless alloys for multi-year active pharmaceutical ingredient campaigns requiring tight thermal control. Swissmedic quality agreements align with FDA mandates for continuous manufacturing technology transfer. The region leads microwave-assisted and photochemical system adoption for selective activation in fine chemical synthesis.
Japan
Mitsubishi Chemical and domestic peers maintain loop reactor dominance in polyethylene and specialty polymer production. METI industrial policy supports process intensification architectures for brownfield chemical manufacturing investments. The Chubu region around Nagoya anchors ASME-certified vessel construction serving 18-24 month delivery cycles.
Continuous Reactors Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators respond to 18-24 month delivery backlogs for ASME-certified pressure vessels. The market structures around three tiers: diversified chemical conglomerates with captive reactor fleets, specialized vessel fabricators serving 200-bar specifications, and technology licensors providing modular skid-mounted systems. Strategic archetypes include integrated site operators, high-alloy steel specialists, and laboratory-to-production scale transition enablers. M&A activity and technology licensing partnerships represent the dominant competitive moves.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify integrated site operators with captive continuous processing infrastructure. Corning Incorporated occupies a position within the technology licensor archetype, anchoring the microreactor segment for laboratory-to-production transitions. Dow Chemical Company represents the petrochemical application specialist, competing across loop reactor configurations. These three companies span distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Evonik Industries AG |
| SABIC |
| BASF SE |
| LG Chem Ltd. |
| Mitsubishi Chemical Corporation |
| Dow Chemical Company |
| LyondellBasell Industries N.V. |
| Corning Incorporated |
| DuPont de Nemours, Inc. |
| Others |
Pricing and Supply Chain Analysis
EPA Maximum Achievable Control Technology standards gate qualified supply for continuous reactor fabricators, restricting premium-tier pricing access to ASME-certified vessel constructors with documented emission control integration. Buyers seeking REACH-compliant systems with real-time analytical monitoring face extended procurement cycles and elevated cost positions relative to standard batch equipment.
Pricing Analysis
Volume contracts anchor the lower-margin base while customization for 200-bar specifications captures premium returns. Three-tier pricing structure across premium, standard, and economy levels separates advanced alloy configurations from carbon steel alternatives, with certification grade and geographic delivery cost as primary differentiation levers. Cost compression in standard tubular systems is intensifying because of nickel and molybdenum price volatility. Specialty chemical producers show lowest price sensitivity given sole-source contract structures, whereas multi-product contract manufacturers retain batch flexibility despite continuous unit economics.
Supply Chain Analysis
ASME certification requirements concentrate qualified fabrication capacity in Germany, Japan, and the US Gulf Coast, creating structural bottlenecks for 200-bar specification demand. High-alloy steel plate, precision catalyst loading systems, and advanced control instrumentation anchor raw material dependencies. Single-source vulnerability runs through German integrated chemical park operators who dominate captive continuous processing infrastructure. Distribution feeds from specialized fabricators through engineering-procurement-construction contractors to end-use chemical and pharmaceutical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous reactors occupy a technology-transition phase as fluidized bed configurations displace legacy batch assets in biomass conversion and catalytic cracking applications. Microwave-assisted and photochemical activation systems are replacing conventional thermal routes in pharmaceutical fine chemical production.
For Market Incumbents: Deepen captive high-alloy steel supply arrangements to insulate margin positions from nickel and molybdenum volatility. Expand ASME-certified fabrication capacity in the US Gulf Coast to compress 18-24 month delivery backlogs. Lock in five-year sole-source contracts with specialty chemical buyers by guaranteeing sub-2% batch-to-batch variation coefficients.
For New Entrants and Emerging Players: Photochemical-microwave convergence technologies offer a technology-first wedge into Swiss and New Jersey pharmaceutical clusters seeking selective activation for solvent reduction. Target modular skid-mounted system deployments for distributed pharmaceutical manufacturing near mid-tier US and European hospital networks. Pursue technology licensing partnerships with established engineering-procurement-construction contractors rather than direct fabrication investment.
For Investors and Strategic Acquirers: FDA quality agreement mandates for continuous manufacturing technology transfer are the leading indicator that pharmaceutical application specialists will command acquisition premiums. Five-to-ten year viability favors ASME-certified fabricators with demonstrated 200-bar pressure vessel construction and integrated control system capabilities. Watch for EU Green Deal carbon border adjustment enforcement as the signal triggering accelerated retrofit demand for heat-integrated continuous systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Alloy Steel Supply | BASF and Evonik secure nickel and molybdenum access against price volatility compressing fabricator margins. |
| Modular Skid-Mounted System Launch | Corning's laboratory-to-production scale transitions enable distributed pharmaceutical manufacturing near point-of-care demand. |
| Photochemical Technology Licensing | Swiss and New Jersey facilities reduce solvent consumption to align with EU Green Deal carbon accounting requirements. |
| ASME-Certified Capacity Expansion | German and Japanese fabricators address 18-24 month delivery backlogs for 200-bar specification pressure vessels. |
| Heat Integration Network Retrofit | Rhine-Ruhr processors capture exothermic reaction energy to document energy intensity per unit output for carbon border compliance. |
Research Methodology
Document review covered SEC 10-K filings, ASME certification registries, and EPA emission compliance databases, complemented by interviews with plant managers at German integrated chemical parks, procurement leads at downstream specialty chemical formulators, and technical R&D directors at pressure vessel fabricators. Secondary validation drew from customs and trade data, Cefic sector reports, and FDA quality agreement documentation. Bottom-up unit deployment counts were triangulated against top-down chemical industry capital expenditure patterns.
Cross-referencing historical installation data with expert panel input on technology migration timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include reactor type, application sector, activation technology, and end-use industry concentration. CAGRs were derived from curve-fitting approaches applied to disclosed capacity expansion announcements and regulatory compliance-driven replacement schedules. Forecast inputs incorporated nickel and molybdenum price trajectory assumptions and EPA enforcement intensity projections.
Several conditions sit outside the modeled scope, including unannounced trade policy shifts affecting high-alloy steel tariffs and breakthrough batch reactor designs that reverse continuous adoption economics. Forecasts reflect assumptions about sustained REACH compliance complexity and FDA quality agreement enforcement without contingency for regulatory relaxation. A model refresh is warranted upon material change in EU Green Deal carbon border adjustment implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Kraft Lignin Products Market