
 Global Flame Retardants Market | 2026-2036
Global Flame Retardants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Retardants Market Analysis
The EU Green Deal is decoupling flame retardant procurement from legacy brominated chemistries across European construction and electronics supply chains. Albemarle Corporation leverages its bromine asset base in the US Gulf Coast to sustain integrated positions in tetrabromobisphenol A despite regulatory headwinds. ICL Group Ltd. anchors its growth strategy on phosphorus-based alternatives, while Clariant AG differentiates through halogen-free additive masterbatches tailored for polyamide and polyester compounds.
Flame retardants are functional additives that inhibit or suppress combustion through radical quenching, char formation, or endothermic decomposition, with loadings typically ranging from five to thirty percent by weight in polymer matrices to meet UL 94 V-0 or EN 13501-1 fire performance classifications. Their primary purpose is to extend escape times and reduce smoke toxicity in built environments and transportation interiors. Phosphorus-based flame retardants now lead volume growth as formulators substitute halogenated systems under tightening environmental protocols, while intumescent coatings command premium positions in steel protection for commercial construction. Brominated flame retardants retain scale in electrical connector housings and printed circuit boards where small additive loadings achieve stringent flammability thresholds.
REACH restrictions on persistent organic pollutants, the EU F-Gas Regulation on blowing agents in insulation foams, and EPA Significant New Use Rules under TSCA collectively reshape permissible chemistries and testing burdens for suppliers entering European and North American markets. China's GB standards on building fire safety and MEE enforcement of plastic waste import bans further fragment compliance requirements across production geographies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
REACH restrictions on halogenated compounds are forcing immediate formulation pivots across European supply chains, while Chinese GB standards on building fire safety create parallel compliance pressures that fragment global procurement strategies.
Growth Catalysts
- EU Green Deal implementation:The EU Green Deal mandates decarbonization across construction and electronics sectors, redirecting procurement toward phosphorus-based and halogen-free systems that reduce persistent organic pollutant exposure in built environments.
- China construction sector expansion:Chinese GB standards enforcement on high-rise fire safety drives volume procurement of intumescent coatings and non-halogenated additives for steel protection in commercial real estate developments.
- Electric vehicle battery enclosures:Thermal runaway protection requirements for lithium-ion battery packs in passenger vehicles create specification pull for ceramic- and phosphorus-based flame barriers that extend passenger escape times.
Market Restraints
- Bromine supply concentration:Brominated feedstock production concentrates in Dead Sea and Arkansas brine operations, exposing formulators to geopolitical risk and input cost volatility when regional extraction permits face environmental review.
- Phosphorus technical limitations:Phosphorus-based systems exhibit hydrolytic instability in polyamide compounds under elevated humidity, restricting their deployment in automotive under-hood applications where long-term performance validation is mandatory.
- REACH testing burden:ECHA registration requirements for novel chemistries impose six-figure toxicity dossier costs that deter mid-scale suppliers from commercializing alternative formulations.
Strategic Opportunities
- India building code modernization:Indian BIS adoption of EN 13501-1 equivalent classifications for commercial construction creates first-mover positioning for halogen-free masterbatch suppliers in Mumbai and Delhi NCR development corridors.
- Recycled polymer integration:Flame retardant systems compatible with post-consumer polyethylene and polypropylene streams address MEE enforcement of plastic waste circularity mandates in Chinese packaging and automotive sectors.
- 5G infrastructure deployment:Small cell housing and fiber optic cable specifications in Germany, South Korea, and the United States demand low-smoke zero-halogen compounds that command formulation premiums over legacy brominated grades.
Industry Challenges
- UL 94 V-0 certification timelines:Third-party testing protocols for polymeric compounds require 12-16 week validation cycles that delay product launches and freeze working capital in pre-certified inventory.
- Reformulation technical debt:Legacy brominated systems in automotive and appliance supply chains necessitate complete polymer matrix requalification, creating switching friction that extends sales cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Retardants Market |
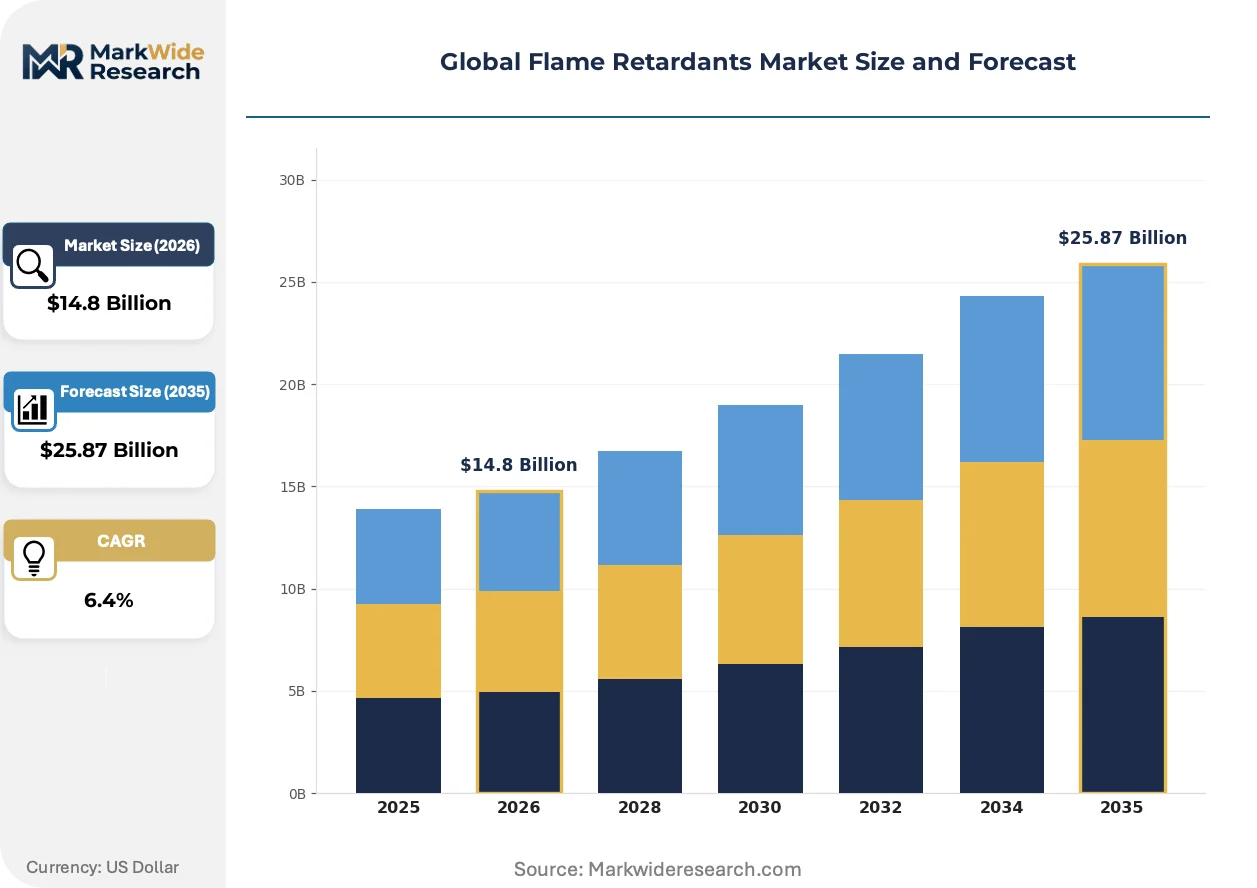
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brominated Flame Retardants, Phosphorus-Based Flame Retardants, Halogen-Free Flame Retardants, Intumescent Flame Retardants End Use Industry: Construction, Automotive, Electronics, Textiles Form: Liquid, Powder, Granules, Masterbatch Application: Coatings, Polymers, Composites, Adhesives |
| Companies Covered | Albemarle Corporation, BASF SE, LANXESS AG, ICL Group Ltd., Clariant AG, Dow Inc., Arkema, Syensqo, Nabaltec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Retardants Market Emerging Trajectories
Formulation chemistry is pivoting toward reactive and polymeric flame retardant architectures that bond covalently to polymer backbones, eliminating migration and leaching concerns that plague traditional additive approaches.
Phosphorus-nitrogen intumescent systems are absorbing specification share in European construction applications as ECHA restrictions on halogenated compounds accelerate. German facade manufacturers and French steel fabricators now specify these systems for EN 13501-1 Class A2-s1,d0 ratings. The technology is absorbing margin compression from higher raw material costs by reducing total additive loadings versus legacy brominated alternatives.
EPA Significant New Use Rules under TSCA are constraining the reintroduction of previously discontinued brominated chemistries into US commerce. Electrical connector and printed circuit board manufacturers face reformulation mandates when sourcing housings for NHTSA-regulated automotive and FAA-regulated aerospace applications. Suppliers are responding by accelerating phosphorus-based drop-in qualifications with tier-1 polymer compounders.
Automotive OEMs now bundle flame retardant specification with circularity mandates, requiring compatibility with mechanically recycled feedstocks. Tier suppliers in Stuttgart, Detroit, and Shanghai must validate performance across variable recycled content ratios. This specification bundling is most visible in electric vehicle battery enclosure contracts where thermal runaway protection and end-of-life recyclability carry equal weight in sourcing decisions.
Global Flame Retardants Market Segmentation
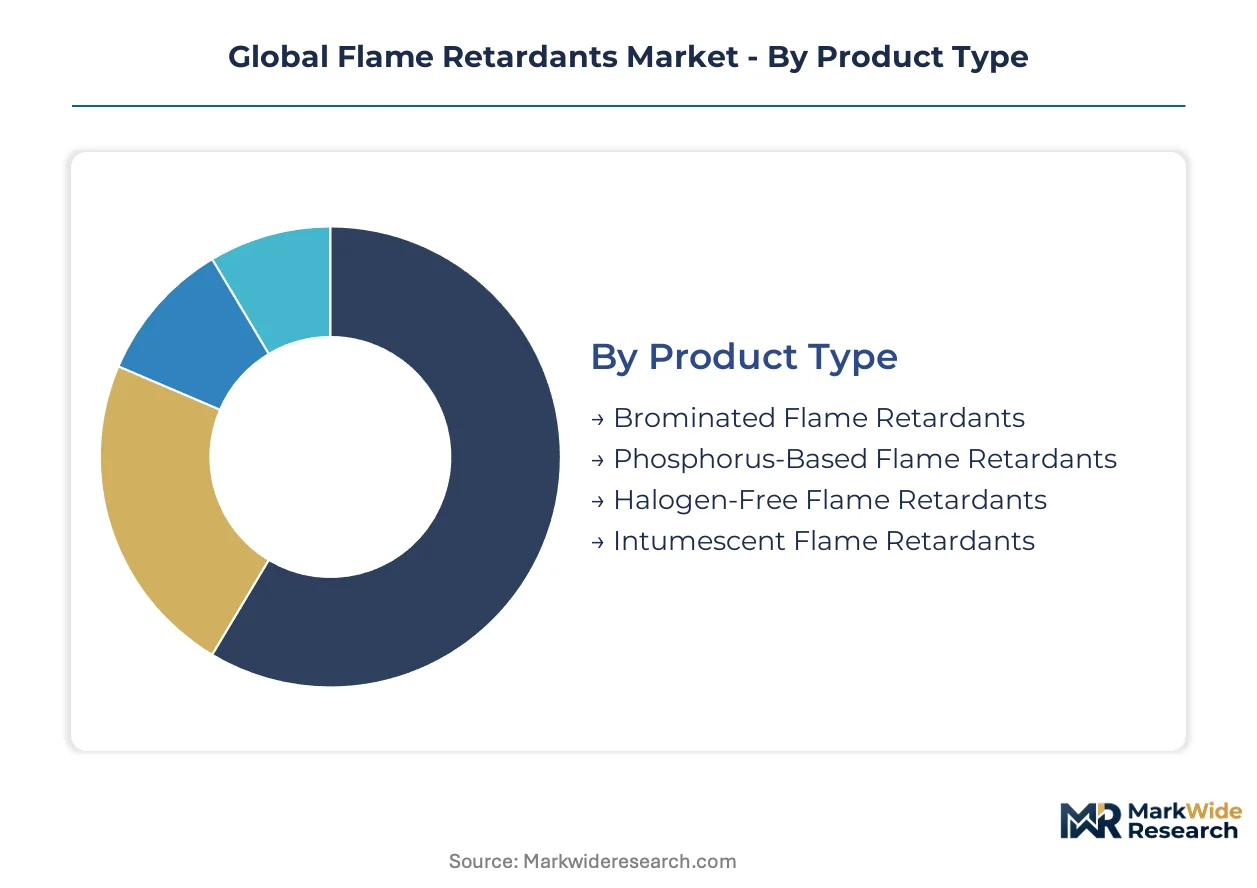
Flame retardant procurement diverges sharply across product chemistries and end-use specifications. Formulators must align additive selection with regulatory jurisdiction, polymer matrix compatibility, and fire performance classification requirements.
Product Type:
Technical performance and regulatory acceptance define competitive positioning across chemistries.
- Phosphorus-Based Flame Retardants:These systems operate through char formation and endothermic decomposition, achieving UL 94 V-0 ratings at lower loadings than mineral alternatives. German automotive suppliers and Chinese construction compounders now specify phosphorus-nitrogen intumescent grades for EN 13501-1 compliance under tightening EU REACH restrictions on halogenated alternatives.
- Brominated Flame Retardants:Radical quenching mechanisms deliver fire suppression at 5-15% loadings in polyolefins and styrenics, with tetrabromobisphenol A retaining specification in printed circuit boards and electrical connector housings where small additive fractions achieve stringent flammability thresholds despite regulatory headwinds.
- Halogen-Free Flame Retardants:Metal hydroxide and nitrogen-based systems serve low-smoke zero-halogen cable specifications in German 5G infrastructure and South Korean fiber optic deployments.
- Intumescent Flame Retardants:Phosphorus-nitrogen coatings expand under heat to form insulating char layers, commanding premium positions in Chinese high-rise steel protection and French facade applications.
Phosphorus-based systems lead on scale; halogen-free alternatives lead on momentum.
End Use Industry:
Application-specific fire codes and material performance requirements fragment demand patterns.
- Construction:EN 13501-1 and Chinese GB standards on high-rise fire safety drive volume procurement of intumescent coatings and non-halogenated additives for steel protection and facade insulation in commercial real estate developments across Germany, France, and China.
- Automotive:Thermal runaway protection requirements for lithium-ion battery packs in electric vehicles create specification pull for ceramic- and phosphorus-based flame barriers that extend passenger escape times, with Stuttgart and Shanghai OEMs bundling flame retardant selection with circularity mandates.
- Electronics:Low-smoke zero-halogen compounds for 5G small cell housings and fiber optic cables in Germany, South Korea, and the United States command formulation premiums over legacy brominated grades.
- Textiles:Phosphorus-based treatments for transportation upholstery and protective clothing face durability validation requirements under elevated humidity conditions.
Construction leads on scale; automotive leads on momentum.
Form:
Processing economics and dispersion requirements determine form factor selection.
- Masterbatch:Concentrated additive carriers enable precise dosing in continuous polymer extrusion, with halogen-free masterbatches tailored for polyamide and polyester compounds commanding premium positions in European automotive and electronics supply chains.
- Powder:Dry blending compatibility supports cost-sensitive construction applications and recycled polymer integration where dispersion uniformity is less critical.
- Liquid:Solution-processable systems serve coatings and adhesives applications requiring film-forming consistency.
- Granules:Dust-free handling properties suit automated dosing systems in high-volume compounding operations.
Masterbatch leads on scale; liquid formulations lead on momentum.
Application:
Substrate compatibility and fire testing protocols segment technical requirements.
- Polymers:Additive integration into polyethylene, polypropylene, polyamide, and polyester matrices represents the dominant consumption channel, with loadings of 5-30% by weight required to achieve UL 94 V-0 or equivalent classifications.
- Coatings:Intumescent and intumescent-ablative systems for steel protection in commercial construction command premium pricing based on EN 13381-8 and equivalent test certifications.
- Composites:Fiber-reinforced thermoset applications in aerospace and rail interiors require reactive flame retardant architectures that bond covalently to polymer backbones.
- Adhesives:Low-viscosity formulations for electronics assembly and transportation interior bonding face thermal stability constraints under continuous operating temperatures.
Polymers lead on scale; composites lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flame retardant manufacturing originated in German and US chemical corridors during the post-war plastics boom, with brominated and phosphorus-based chemistries scaling through integrated petrochemical complexes before dispersing to Asian production bases.
United States
Electric vehicle battery enclosure contracts and 5G infrastructure deployment drive specification pull for low-smoke zero-halogen compounds. EPA Significant New Use Rules under TSCA constrain reintroduction of discontinued brominated chemistries into US commerce. Houston-Gulf Coast chemical clusters sustain integrated bromine derivative production despite regulatory headwinds.
Germany
Facade manufacturers and steel fabricators specify phosphorus-nitrogen intumescent systems for EN 13501-1 Class A2-s1,d0 ratings in commercial construction. EU REACH restrictions on halogenated compounds accelerate formulation pivots across European supply chains. Stuttgart automotive OEMs bundle flame retardant selection with circularity mandates for battery enclosures.
China
High-rise commercial real estate development and electric vehicle production create volume demand for steel protection coatings and battery thermal barriers. GB standards enforcement on building fire safety drives procurement of intumescent and non-halogenated systems. Yangtze River Delta compounding operations concentrate phosphorus-based masterbatch production for construction and automotive sectors.
India
Mumbai and Delhi NCR development corridors generate specification pull as BIS adopts EN 13501-1 equivalent classifications for commercial construction. Building code modernization creates first-mover positioning opportunities for halogen-free masterbatch suppliers. Western India chemical manufacturing zones attract formulation investments targeting infrastructure growth.
South Korea
Fiber optic cable and 5G small cell housing specifications demand low-smoke zero-halogen compounds for telecommunications infrastructure. MFDS chemical safety protocols align with EU REACH restrictions, redirecting procurement toward phosphorus-based alternatives. Busan-Ulsan industrial corridors concentrate electronics materials compounding for export markets.
Global Flame Retardants Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capabilities and formulation integration depth. The vendor base organizes around three tiers: integrated bromine producers with captive feedstock access, phosphorus-based specialists with REACH-registered portfolios, and regional masterbatch compounders serving price-sensitive construction applications. Dominant competitive moves include backward integration into phosphorus and bromine feedstocks, plus strategic partnerships with tier-1 polymer compounders to accelerate qualification timelines.
Among integrated chemical producers, Albemarle Corporation anchors the brominated tier through US Gulf Coast brine operations, while ICL Group Ltd. exemplifies the phosphorus-based pivot with Dead Sea extraction assets repurposed toward intumescent and nitrogen-phosphorus formulations. Clariant AG occupies a specialist position in halogen-free additive masterbatches, representing the formulation-intensive archetype that differentiates through polymer-specific compounding expertise rather than feedstock scale.
| Leading Market Players |
|---|
| Albemarle Corporation |
| BASF SE |
| LANXESS AG |
| ICL Group Ltd. |
| Clariant AG |
| Dow Inc. |
| Arkema |
| Syensqo |
| Nabaltec AG |
| Others |
Supply Flow & Price Mechanics
Specialized formulation chemists concentrated in German industrial clusters and US Gulf Coast chemical corridors create labor-cost differentials that widen spreads between premium REACH-registered grades and economy-tier construction additives. This workforce geography directly shapes how phosphorus-based specialists capture margin premiums while regional masterbatch compounders compete on delivered cost.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered phosphorus formulations from commodity brominated grades and unregistered mineral alternatives. Price differentiation rests on ECHA registration status and UL 94 certification tier, with premium grades commanding substantial uplifts for automotive and electronics applications. Cost compression in economy-tier construction additives is intensifying because Chinese masterbatch producers are scaling phosphorus-nitrogen intumescent production. Tier-1 automotive OEMs exhibit lowest price sensitivity due to thermal runaway liability exposure, while regional construction distributors remain highly price-sensitive and switch readily between suppliers.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns that aggregate phosphorus derivatives from Chinese Yangtze River Delta production and brominated feedstocks from Arkansas brine operations. Raw material dependencies center on elemental phosphorus from China and Kazakhstan, bromine from the Dead Sea and Arkansas, and nitrogen intermediates from German chemical complexes. Single-source vulnerability concentrates in Dead Sea bromine extraction where environmental permit reviews periodically disrupt supply. Distribution runs through polymer compounder direct contracts for automotive and electronics sectors, with construction applications served via distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH restrictions on halogenated compounds and Chinese GB standards enforcement collectively redirect procurement toward phosphorus-based and halogen-free systems.
For Market Incumbents: Deploy backward integration into phosphorus feedstocks to secure supply continuity as Chinese environmental enforcement tightens extraction permits. Incumbent suppliers must accelerate ECHA registration for novel nitrogen-phosphorus architectures before mid-scale competitors recover from six-figure toxicity dossier costs. Capacity addition in Indian western chemical zones captures building code modernization demand before halogen-free masterbatch supply localizes. For New Entrants and Emerging Players: Enter via recycled polymer-compatible flame retardant formulations where Stuttgart and Shanghai OEMs bundle circularity mandates with thermal runaway specifications. White-space targets include India BIS-equivalent EN 13501-1 compliance for Mumbai commercial construction and 5G small cell housing compounds for South Korean fiber optic deployments. Go-to-market angle should emphasize rapid UL 94 V-0 qualification support to compress 12-16 week validation cycles. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing phosphorus asset bases are the most active acquirer in this space, seeking formulation expertise to complement feedstock positions. Long-term viability hinges on regulatory divergence management capabilities across REACH, TSCA, and Chinese GB frameworks. Acquisition target archetype: regional masterbatch compounders with established tier-1 automotive qualifications. Signal to watch is ECHA restriction expansion beyond halogenated compounds into organophosphate esters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Feedstocks | Captive supply of elemental phosphorus from Chinese or Kazakh sources insulates against export quota volatility. |
| REACH Registration Acceleration | Early ECHA dossier submission for novel chemistries blocks mid-scale competitors from market entry. |
| Recycled Polymer Compatibility Investment | Validation across variable post-consumer content ratios secures Stuttgart OEM battery enclosure contracts. |
| India Manufacturing Footprint Establishment | Western India chemical zones position suppliers ahead of BIS adoption of European fire classifications. |
| Long-term Supply Agreement with Tier-1 Compounders | Direct contracts with polymer compounders reduce working capital freeze in pre-certified inventory. |
Methodological Framework
Direct dialogue with plant managers at phosphorus derivative facilities, procurement leads at German automotive OEMs, distribution channel partners in Indian construction chemicals, and technical R&D directors at masterbatch compounders grounded qualitative assessment. Secondary validation drew from ECHA registration databases, Chinese customs trade data on phosphorus pentoxide imports, SEC 10-K filings of integrated chemical producers, and Cefic sector reports. Bottom-up demand modeling across end-use industries triangulated against top-down supply capacity estimates.
Segmented outputs across the analysis window reflect chemistry type, end-use industry, and regional regulatory cluster variations. The analytical framework modeled phosphorus-based, brominated, halogen-free, and intumescent product categories against construction, automotive, electronics, and textile applications. CAGRs were derived from elasticity-adjusted demand projections incorporating electric vehicle battery enclosure specification pull and 5G infrastructure deployment curves.
The model holds under stable REACH enforcement intensity and continued Chinese GB standards implementation; deviation in ECHA restriction scope or Dead Sea extraction permit moratoria would shift supply availability and pricing tier boundaries. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Ferrous Gluconate Market