
 Pyrethrin Market | 2026-2036
Pyrethrin Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrethrin Market Intelligence
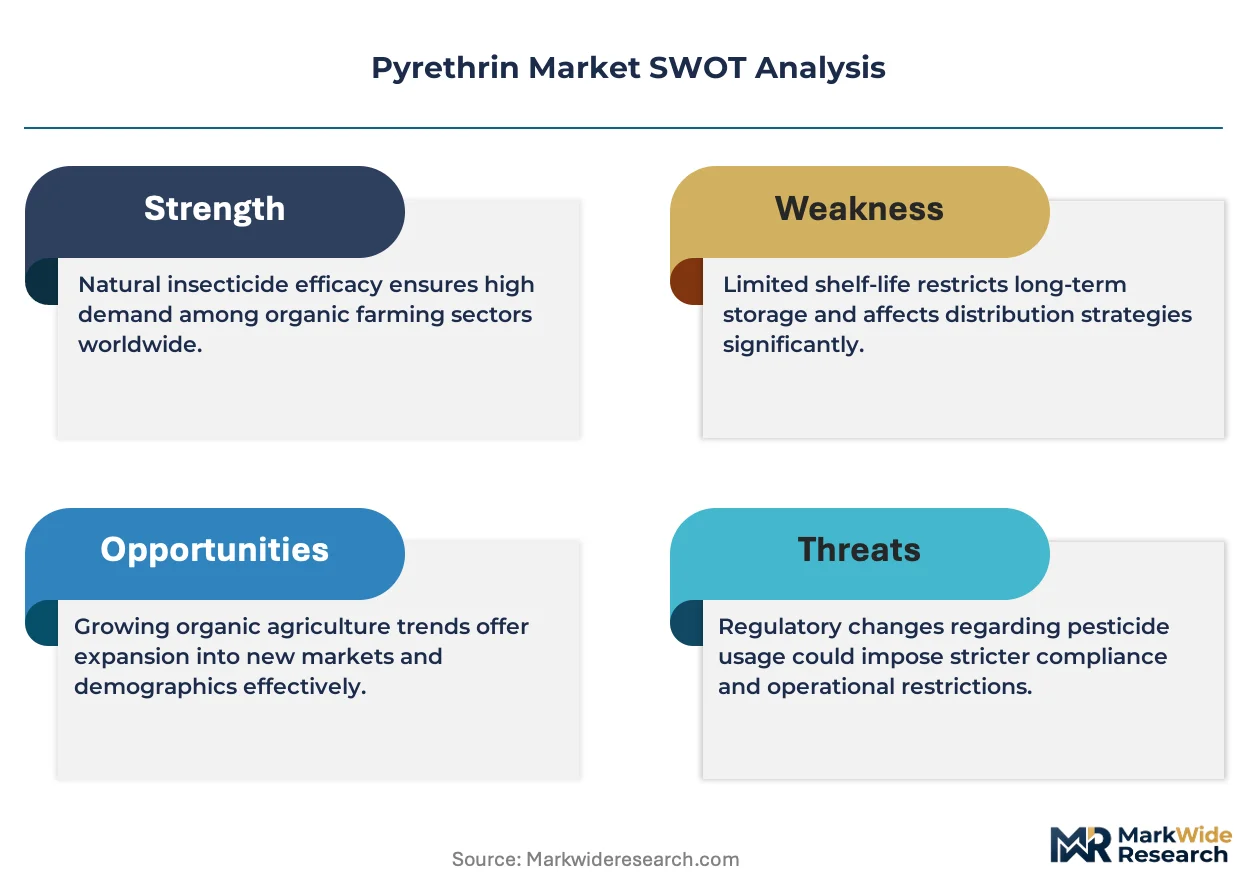
Organic certification under USDA NOP standards is unwinding competitive access for synthetic pyrethroid alternatives in premium crop segments. BASF SE leverages its formulation expertise to sustain leadership in microencapsulated delivery systems. Sumitomo Chemical anchors its position through backward integration into pyrethrum cultivation in East Africa. McLaughlin Gormley King Company specializes in technical-grade refinement for downstream botanical insecticide manufacturers.
Pyrethrin denotes a group of six ester insecticides extracted from Chrysanthemum cinerariifolium flowers, with pyrethrin I and pyrethrin II comprising the primary active constituents responsible for rapid knockdown and flush-out effects against arthropod pests. The compound functions commercially as a broad-spectrum botanical insecticide with low mammalian toxicity, applied across agricultural, residential, and public health vectors where synthetic chemical residues face restriction. Concentrate formulations command the deepest margin pools due to value-added blending services and custom dilution protocols for professional pest control operators. Agricultural crops applications lead volume consumption, though public health deployment for mosquito vector programs represents the fastest-expanding demand channel as resistance management protocols diversify active ingredient rotations.
EPA re-registration requirements under FIFRA mandate exhaustive residue chemistry and ecotoxicology datasets for pyrethrin product renewals, elevating compliance costs for smaller formulators. REACH registration obligations in Europe restrict import volumes of technical-grade material lacking full substance dossiers, redirecting supply toward jurisdictions with mutual recognition agreements. Stakeholders must monitor regulatory divergence between jurisdictions with streamlined botanical pathways and those applying synthetic-equivalent data requirements, as this bifurcation will determine which production clusters retain cost-competitive access to formulation-grade pyrethrum extract.
Market Dynamics
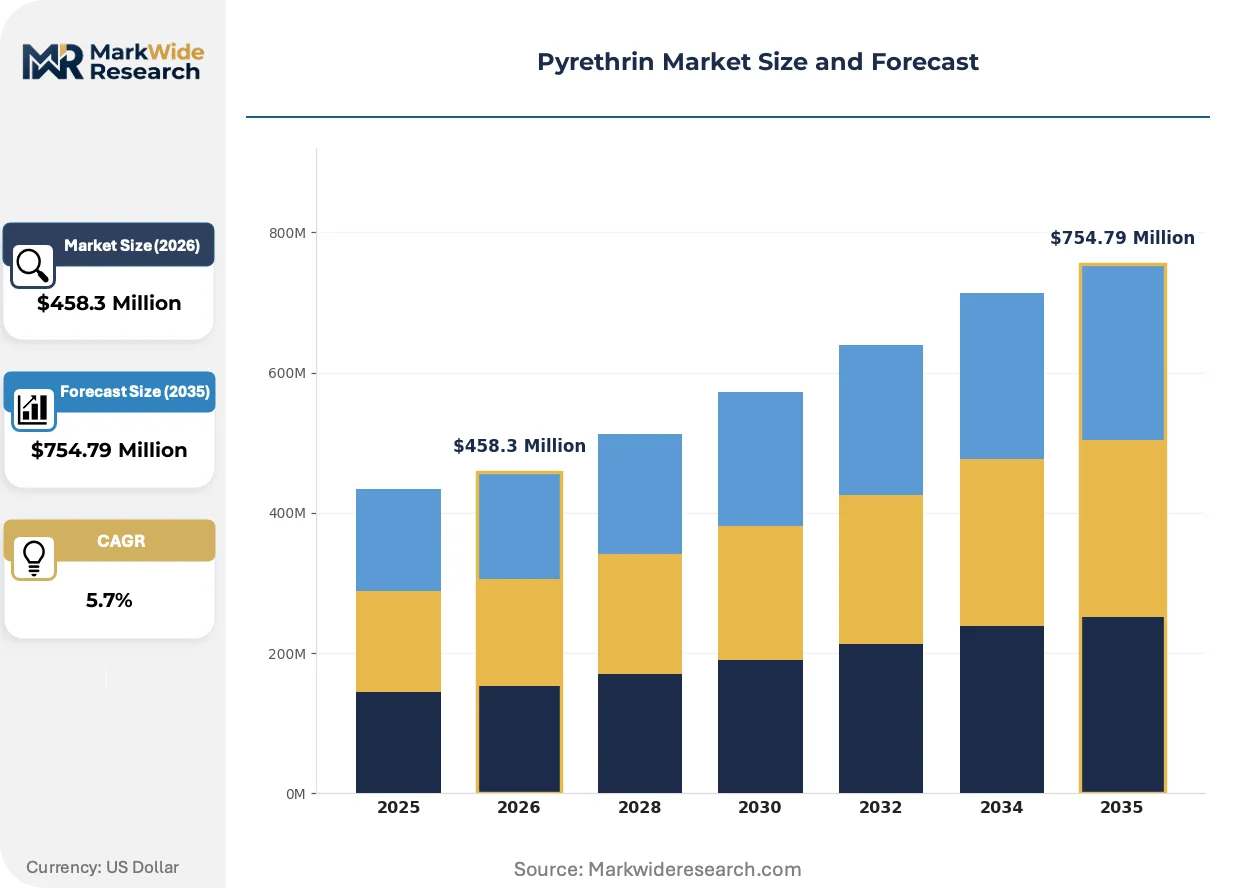
EPA's FIFRA re-registration review is compressing formulation timelines as pyrethrum extractors race to submit residue chemistry dossiers before 2027 deadlines, forcing consolidation among smaller technical-grade refiners unable to absorb compliance costs.
Growth Catalysts
- USDA NOP organic certification:Residue-sensitive export crops in California's Central Valley now require botanical insecticides, locking synthetic pyrethroids out of premium segments.
- Pyrethrum flower cultivation clusters:Kenya's Rift Valley supplies raw material to extraction facilities, anchoring backward-integrated supply security for major formulators.
- Microencapsulation technology:Controlled-release formulations extend field efficacy against resistant mosquito populations, opening public health vector programs as a demand channel.
Market Restraints
- Pyrethrum flower supply volatility:Kenyan smallholder harvests fluctuate with rainfall patterns, creating raw material price instability for extractors.
- REACH registration obligations:European ECHA substance dossier requirements block technical-grade imports lacking full ecotoxicology datasets, diverting supply to mutual-recognition jurisdictions.
- Synthetic pyrethroid substitution:Permethrin and cypermethrin alternatives offer lower unit costs for price-sensitive agricultural applications in developing markets.
Strategic Opportunities
- Public health vector rotation protocols:WHO resistance management guidelines now mandate pyrethrin inclusion in malaria control programs, creating institutional procurement mandates.
- Professional pest control channel expansion:Custom dilution services for licensed operators capture margin pools unavailable through retail concentrate sales.
- East African cultivation scaling:Rwanda and Tanzania present underdeveloped pyrethrum acreage with favorable altitude and labor cost structures for greenfield extraction investments.
Industry Challenges
- Ecotoxicology data generation:EPA FIFRA re-registration demands exhaustive non-target organism studies that smaller formulators cannot fund without partnership structures.
- Extraction technician scarcity:Technical-grade refinement requires specialized chromatographic separation skills concentrated among aging workforces in Kenya and Australia.
- Supply chain reconfiguration friction:REACH-redirected volumes strain logistics networks originally configured for European port distribution, elevating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrethrin Market |
| Market Size in 2026 | $458.3 Million |
| Market Size in 2035 | $754.79 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Concentrate, Emulsifiable Concentrate, Dust, Wettable Powder, Microencapsulated Application: Agricultural Crops, Residential Pest Control, Public Health, Veterinary, Commercial Landscaping, Aquaculture End User: Crop Growers, Pest Control Operators, Animal Husbandry, Landscape Contractors, Fish Farmers, Public Agencies Formulation Type: Liquid, Powder, Aerosol, Granules, Fogging Solutions, Ready-to-Use |
| Companies Covered | BASF SE, Sumitomo Chemical Co., Ltd., McLaughlin Gormley King Company, Botanical Resources Australia Pty Ltd, Endura S.p.A., Horizon Sopyrwa, KAPI Limited, The Pyrethrum Processing Company of Kenya Ltd, Valent BioSciences LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrethrin Market Strategic Shifts & Innovations
Formulation chemistry is diverging between residue-minimizing delivery systems for export agriculture and rapid-knockdown profiles for public health deployment, creating parallel R&D tracks with incompatible technical specifications.
Nano-emulsion carriers are fragmenting the concentrate segment as these systems enable water-based dilution without organic solvents. Professional pest control operators in Florida and Queensland are adopting nano-emulsion pyrethrins at accelerating rates for indoor residual spraying programs. This technology is fragmenting established margin pools by collapsing the distinction between technical-grade suppliers and finished-formulation brands.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are indirectly elevating pyrethrin attractiveness in stored-product protection, where fumigation alternatives face phase-down schedules. Warehouse operators in the Netherlands and Denmark are retrofitting aeration systems to accommodate botanical fogging protocols. Grain handling facilities in northern Europe now represent the fastest-adapting customer segment to this regulatory displacement.
Certification-driven procurement is restructuring buyer-supplier relationships as organic handlers demand chain-of-custody documentation from flower harvest through final formulation. California almond cooperatives and Kenyan tea outgrower associations now require third-party verified pyrethrum sourcing. This behavioral shift is most visible in contract negotiations for the 2026-2027 growing seasons, where traceability premiums are separating qualified from unqualified suppliers.
Pyrethrin Market Segmentation
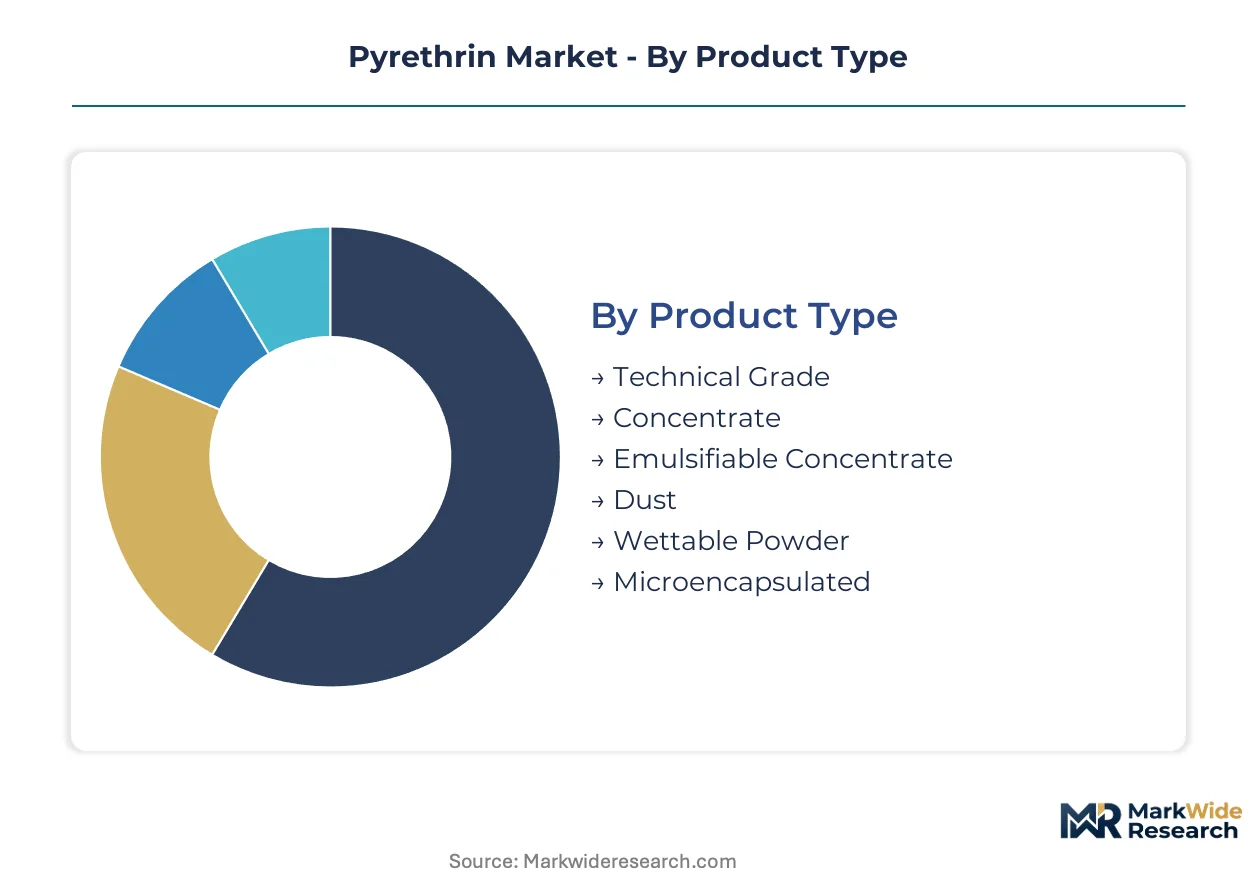
Pyrethrin segmentation reveals divergent supply chain configurations across product tiers. Technical-grade refinement clusters near Kenyan cultivation zones, while concentrate blending serves export markets with residue-sensitive certification requirements.
Product Type:
Technical-grade pyrethrin flows primarily to domestic formulation facilities in Kenya and Australia. Concentrate and microencapsulated variants drive export revenue through premium agricultural and public health channels.
- Technical Grade:Raw pyrethrin extract containing pyrethrin I and II esters at standardized purity levels. Kenyan extraction facilities in Nakuru County supply this material to formulators in the United States and Europe, though REACH dossier gaps redirect volumes toward mutual-recognition jurisdictions.
- Concentrate:Value-added formulations with custom dilution protocols for professional pest control operators. Demand concentrates in California's Central Valley for organic-certified almond and pistachio operations where residue limits exclude synthetic alternatives.
- Emulsifiable Concentrate:Oil-based carriers enabling field dilution for agricultural spraying.
- Dust:Dry formulations for stored-product protection in grain handling facilities.
- Wettable Powder:Suspension concentrates for high-volume agricultural applications.
- Microencapsulated:Controlled-release technology extending field efficacy against resistant mosquito populations in WHO vector programs.
Technical Grade commands the established base. The steepest expansion runs through Microencapsulated.
Application:
Application segmentation tracks regulatory divergence between residue-restricted export agriculture and resistance-management public health deployment. Cost tiers separate premium organic crop protection from commodity pest control.
- Agricultural Crops:Broad-spectrum arthropod control for residue-sensitive export commodities. California almond cooperatives and Kenyan tea outgrower associations now mandate third-party verified pyrethrum sourcing through contract negotiations.
- Public Health:Mosquito vector control programs under WHO resistance management guidelines. Institutional procurement mandates in malaria-endemic regions now require pyrethrin inclusion in active ingredient rotations, displacing single-chemical dependence.
- Residential Pest Control:Consumer formulations for household arthropod management.
- Veterinary:Livestock and companion animal ectoparasite treatments.
- Commercial Landscaping:Turf and ornamental applications for aesthetic pest management.
- Aquaculture:Fish farm parasite control with strict withdrawal period requirements.
Agricultural Crops anchors volume consumption. Public Health gains share fastest through institutional procurement mandates.
End User:
End user structure reflects customer maturity gradients, from price-sensitive smallholders to specification-driven public agencies. Procurement sophistication determines margin capture across the value chain.
- Crop Growers:Direct agricultural applications ranging from smallholder pyrethrum farmers to large-scale organic operations. California Central Valley growers pay traceability premiums for certified supply chains.
- Pest Control Operators:Licensed professionals purchasing custom dilution services. Florida and Queensland operators are adopting nano-emulsion systems for indoor residual spraying programs.
- Animal Husbandry:Livestock producers managing ectoparasite burdens.
- Landscape Contractors:Commercial turf and ornamental maintenance services.
- Fish Farmers:Aquaculture operations with veterinary oversight requirements.
- Public Agencies:Government vector control programs with institutional procurement protocols.
Pest Control Operators deliver the deepest margin pools. Public Agencies are expanding most quickly through WHO guideline adoption.
Formulation Type:
Formulation segmentation tracks technology substitution between solvent-based and water-based delivery systems. Nano-emulsion advances are collapsing traditional distinctions between concentrate suppliers and finished brands.
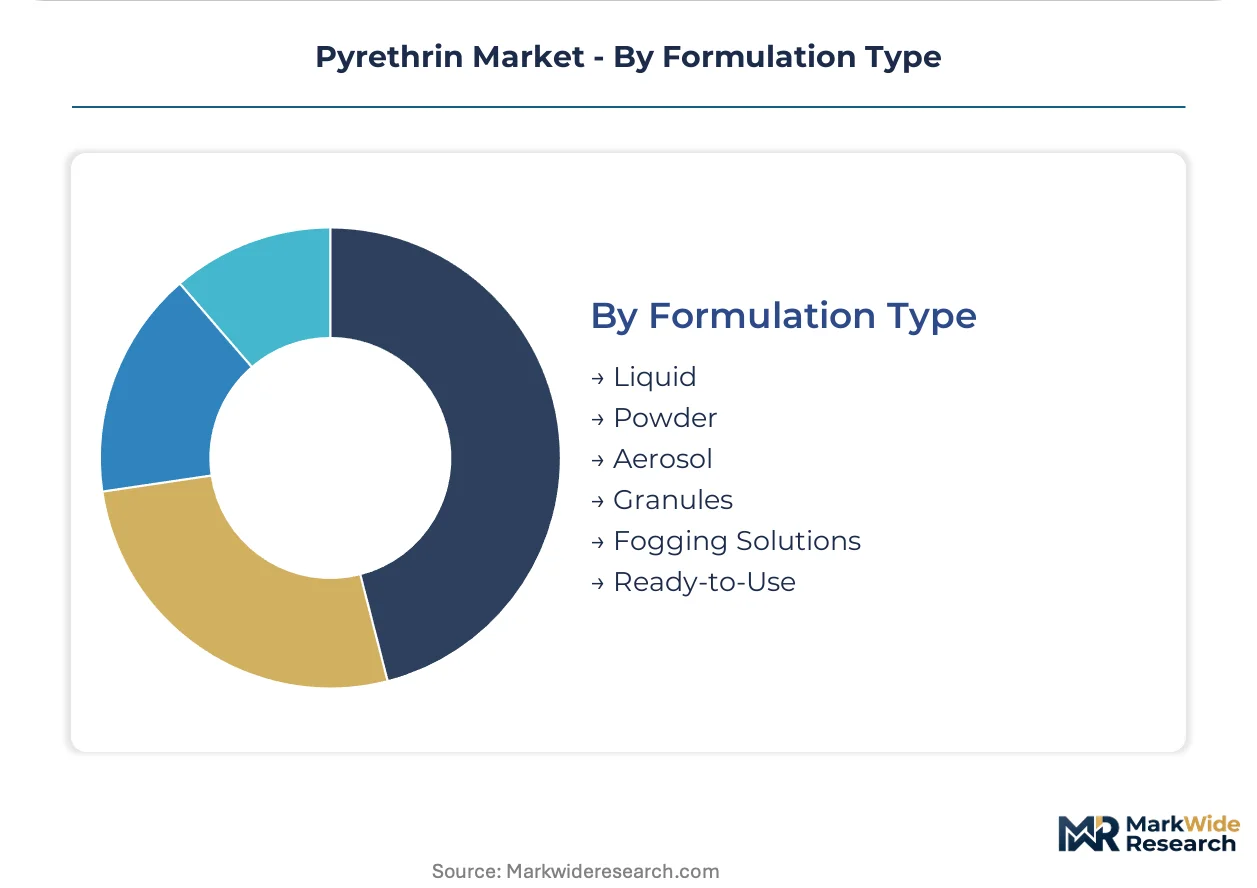
- Liquid:Solvent-based solutions for professional dilution and application. Established formulators in the United States maintain formulation expertise in this segment.
- Aerosol:Pressurized delivery systems for residential and commercial quick-kill applications. Queensland warehouse operators are retrofitting aeration systems for botanical fogging protocols under EU F-Gas Regulation displacement.
- Powder:Dry formulations for dusting and stored-product protection.
- Granules:Slow-release carriers for soil and turf applications.
- Fogging Solutions:Ultra-low volume formulations for space treatment.
- Ready-to-Use:Consumer pre-mixed products bypassing professional service channels.
Liquid formulations command the established base. Aerosol applications are climbing the fastest through regulatory displacement of fluorinated alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around residue-sensitive agricultural exporters, public health procurement agencies, and professional pest control operators. California almond growers, Dutch grain handlers, and Kenyan pyrethrum cultivators anchor distinct demand clusters. Regulatory divergence between streamlined botanical pathways and synthetic-equivalent data requirements determines which production regions retain formulation-grade access.
United States
California Central Valley organic operations drive concentrate demand for almond and pistachio protection. EPA FIFRA re-registration deadlines compress formulation timelines through 2027. Fresno County extraction facilities process Kenyan technical-grade material for domestic microencapsulated production.
Kenya
Rift Valley smallholder cultivation supplies raw pyrethrum flowers to Nakuru County extraction plants. National agricultural extension programs coordinate smallholder quality standards for export certification. Kericho and Nyandarua counties anchor backward-integrated supply security for major formulators.
Australia
Queensland pest control operators adopt nano-emulsion systems for indoor residual spraying programs. TGA registration requirements for agricultural chemicals shape import substitution patterns. Botanical Resources Australia maintains technical-grade refinement capacity near Tasmanian cultivation zones.
Netherlands
EU F-Gas Regulation phase-down elevates pyrethrin attractiveness for stored-product protection in Rotterdam grain terminals. ECHA REACH dossier gaps redirect technical-grade volumes toward mutual-recognition jurisdictions. Warehouse operators in Groningen retrofit aeration systems for botanical fogging protocols.
Germany
BASF SE leverages formulation expertise from Ludwigshafen headquarters for microencapsulated delivery systems. BfR residue monitoring programs enforce strict maximum residue limits for export-bound produce. Bavarian agricultural cooperatives specify third-party verified pyrethrum sourcing for organic certification compliance.
Pyrethrin Market Key Industry Players
Player mix skews toward backward-integrated agricultural chemical conglomerates and specialized botanical extraction firms. The structure concentrates around three strategic archetypes: multinational formulators with cultivation partnerships, regional extraction specialists with technical-grade refinement capabilities, and public health-focused delivery system innovators. Dominant competitive moves include backward integration into East African pyrethrum cultivation and nano-emulsion technology licensing for professional pest control channels.
Within the multinational formulator tier, BASF SE and Sumitomo Chemical Co., Ltd. exemplify backward-integrated positioning through captive supply arrangements with Kenyan cultivation clusters. McLaughlin Gormley King Company occupies a specialist role in technical-grade refinement for downstream botanical insecticide manufacturers. These three entities represent divergent scale vectors: BASF SE anchors global formulation capacity, Sumitomo Chemical secures raw material origination, and McLaughlin Gormley King concentrates on purity-standard supply to smaller formulators lacking in-house extraction capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Sumitomo Chemical Co., Ltd. |
| McLaughlin Gormley King Company |
| Botanical Resources Australia Pty Ltd |
| Endura S.p.A. |
| Horizon Sopyrwa |
| KAPI Limited |
| The Pyrethrum Processing Company of Kenya Ltd |
| Valent BioSciences LLC |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles at Kenyan extraction facilities tether working capital requirements to pyrethrum flower harvest seasonality, concentrating pricing power among backward-integrated formulators with strategic stockpile capacity. This lead-time structure rewards operators who pre-finance smallholder cultivation contracts, while spot-market buyers absorb raw material volatility.
Pricing Analysis
Cost-plus contracts indexed to Nairobi flower auction prices dominate technical-grade transactions, with premium pyrethrin I/II ratios commanding certification-grade markups for organic handlers. Three-tier pricing structure across certified-organic, standard-refined, and unverified technical levels separates California almond cooperatives from commodity pest control channels. Cost compression in standard-grade concentrate is intensifying because REACH-redirected volumes strain logistics networks originally configured for European port distribution. Smallholder outgrower associations in Kenya exhibit highest price sensitivity, while WHO procurement frameworks demonstrate lowest elasticity due to resistance-management mandates.
Supply Chain Analysis
Strategic stockpile preferences among major formulators contrast with just-in-time procurement patterns among regional blenders lacking cultivation partnerships. Supply concentrates in Kenya, Australia, and Tasmania, with Kenyan Rift Valley smallholders providing raw pyrethrum flowers, Tasmanian zones offering alternative cultivation, and Australian facilities maintaining chromatographic refinement capacity. Extraction draws from dried flower biomass, hexane solvent systems, and specialized chromatographic separation equipment. Single-source vulnerability runs through Kenyan rainfall-dependent harvests. Distribution runs through formulation facilities in the United States and Germany for microencapsulated finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Custom dilution services for licensed pest control operators represent a service-attach layer expanding faster than technical-grade commodity sales, as margin pools concentrate in formulation expertise rather than raw extraction.
For Market Incumbents: Consolidate cultivation partnerships in Rwanda and Tanzania before greenfield extraction investments anchor competitor supply security. Deepen backward integration into East African pyrethrum acreage to offset Kenyan rainfall volatility threatening raw material origination. Defend microencapsulated formulation margins through nano-emulsion licensing protocols that fragment concentrate segment profitability for non-integrated rivals. For New Entrants and Emerging Players: Custom traceability documentation for California organic handlers presents a service-layer gap where incumbents under-serve small-to-mid scale buyers lacking in-house certification teams. Target Dutch grain handling facilities retrofitting aeration systems for botanical fogging under EU F-Gas Regulation phase-down schedules. Pursue white-label technical-grade supply to regional formulators in mutual-recognition jurisdictions blocked from European REACH compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nano-emulsion R&D and chromatographic refinement capacity, favoring acquisition of specialized extraction technicians rather than greenfield facility construction. Five-to-ten year viability hinges on positioning within WHO vector program procurement frameworks as resistance-management protocols institutionalize pyrethrin inclusion. Watch for EPA FIFRA re-registration completion rates as inflection indicator for smaller formulator distress and consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive pyrethrum acreage in Kenya's Kericho County insulates formulators from rainfall-driven supply volatility. |
| Nano-Emulsion Technology Licensing | Water-based dilution protocols collapse solvent-dependent margin pools among established concentrate suppliers. |
| REACH Dossier Completion | Full ECHA substance registration restores European market access for technical-grade Kenyan extraction output. |
| Custom Traceability Services | Third-party verified chain-of-custody documentation commands premiums from California almond cooperatives. |
| Strategic Stockpile Financing | Pre-harvest cultivation contracts with Rift Valley smallholders secure preferential pyrethrin I/II ratio allocation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pyrethrum extraction facility managers, formulation chemists at agricultural chemical conglomerates, licensed pest control operators in Florida and Queensland, procurement officers at California almond cooperatives, and regulatory affairs specialists navigating EPA FIFRA re-registration. Secondary validation drew from EPA residue chemistry databases, ECHA REACH registration filings, Kenyan agricultural extension service reports, WHO vector control procurement guidelines, and USDA organic certification records. Bottom-up volume estimates from cultivation acreage and flower yield data triangulated against top-down formulation revenue analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product grade tier, end-use application, formulation technology, and regional regulatory cluster. CAGRs were derived from trend extrapolation of cultivation expansion rates, institutional procurement mandate adoption curves, and substitution elasticity between pyrethrin and synthetic pyrethroid alternatives. Industry-specific inputs incorporated pyrethrum flower yield volatility patterns, nano-emulsion adoption rates among professional pest control channels, and EU F-Gas Regulation displacement timelines for stored-product protection.
Forecasts assume regulatory continuity in EPA FIFRA re-registration, ECHA REACH enforcement, and WHO resistance-management guideline implementation; material policy shifts in botanical pesticide approval pathways or malaria vector control funding would require re-modeling. Revision becomes warranted when Kenyan rainfall indices fall below cultivation viability thresholds or when synthetic pyrethroid resistance patterns accelerate institutional procurement timeline shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Global Silicone Fluid Market
Industrial Chemicals
Aluminium Production Chemicals Market