
 Food Grade Grease Market | 2026-2036
Food Grade Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Grease Market Analysis
EU Green Deal food-system decarbonization mandates are broadening the addressable market for biodegradable and bio-based lubricant formulations. FUCHS leverages its specialty grease portfolio to dominate European food machinery applications. Klüber Lubrication anchors its position through intensive R&D in synthetic food-grade chemistries. Exxon Mobil Corporation extends its reach via integrated base oil supply chains that sustain cost competitiveness.
Food grade grease denotes lubricants formulated with base fluids and additives meeting NSF H1 or HX-1 registration for incidental food contact, typically incorporating white mineral oils, polyalphaolefins, or vegetable esters with dropping points above 150°C to withstand bake oven and fryer proximity. Its primary purpose is reducing friction and wear on processing equipment while eliminating contamination risk in packaged food streams. Conventional grease still occupies the largest volume share across mature markets, though biodegradable grease represents the fastest-expanding margin pool as sustainability procurement criteria harden. High-temperature grease leads in bakery manufacturing applications where oven conveyor chains demand thermal stability exceeding 200°C.
NSF International registration, REACH chemical authorization through ECHA, and EU F-Gas Regulation phase-down schedules collectively determine product eligibility and reformulation cycles across European food production. FDA 21 CFR 178.3570 compliance remains mandatory for any grease exported into United States food processing facilities. Stakeholders must monitor evolving national implementations of the EU AI Act for predictive maintenance systems that automatically trigger lubricant replenishment cycles.
Market Dynamics
EU Green Deal food-system decarbonization mandates are forcing simultaneous reformulation of base chemistries and procurement protocol upgrades across European food processing infrastructure. This regulatory compression is reshaping supplier qualification timelines and lubricant category management.
Growth Catalysts
- Biodegradable Formulation Mandates:EU Green Deal compliance requirements in Germany are expanding procurement budgets for vegetable ester-based greases that eliminate petrochemical contamination risk in packaged food streams.
- Dairy Equipment Maintenance Protocols:Italy's processing sector now mandates NSF H1-certified lubricants for homogenizers and separators, creating specification pull-through across Southern European equipment fleets.
- REACH Chemical Authorization:ECHA's tightening substance restrictions are accelerating replacement cycles for legacy mineral oil formulations in French baking and confectionery applications.
Market Restraints
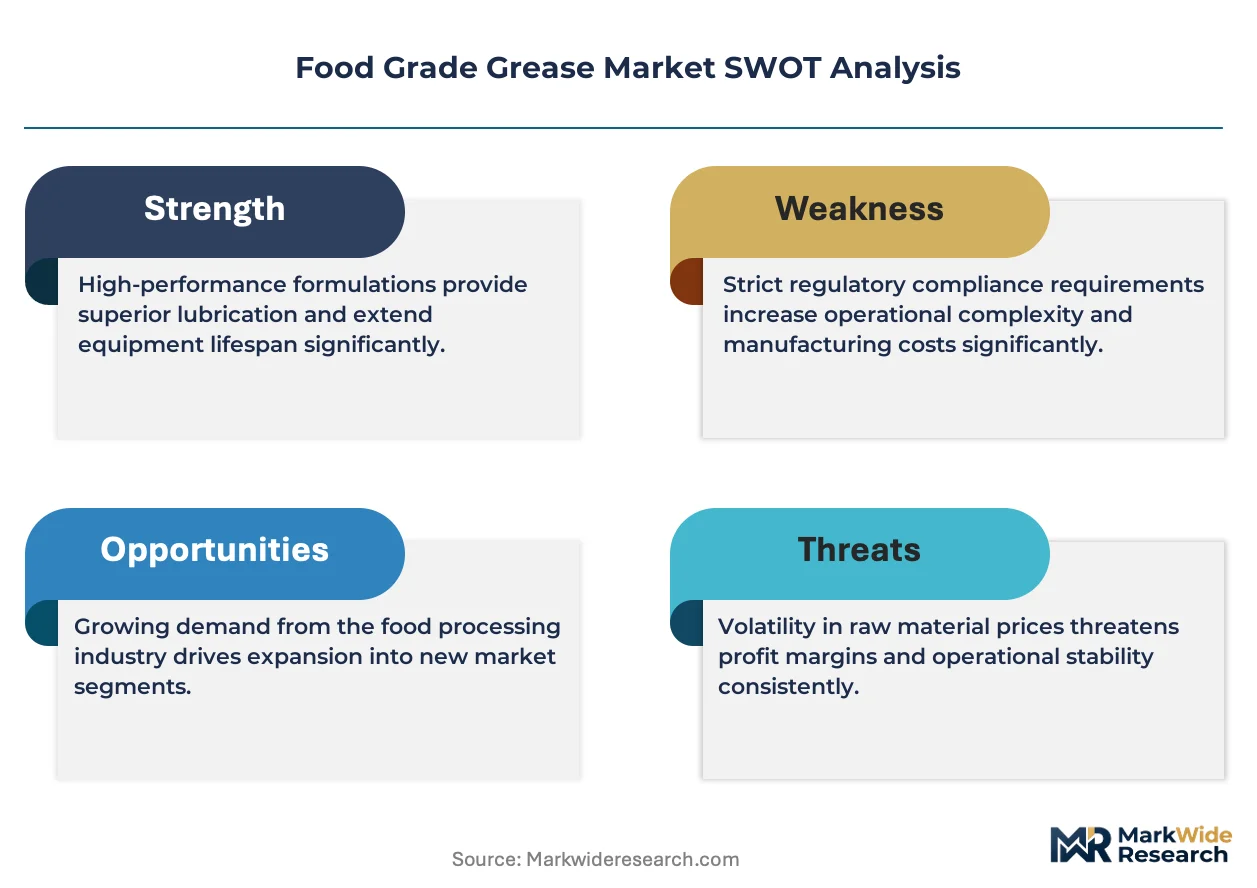
- Base Fluid Cost Volatility:White mineral oil and polyalphaolefin feedstock prices fluctuate with crude oil benchmarks, compressing margin stability for synthetic food-grade formulations.
- Specialty Additive Supply Concentration:High-performance thickeners and oxidation inhibitors for 200°C+ applications concentrate among a narrow supplier base in Western Europe.
- Reformulation Timeline Friction:ECHA REACH authorization procedures extend new chemistry validation to 18-24 months, delaying product commercialization against sustainability deadlines.
Strategic Opportunities
- Predictive Maintenance Integration:EU AI Act implementation for automated lubricant replenishment systems creates white space for sensor-enabled grease delivery in continuous processing lines.
- Bakery Conveyor Thermal Stability:High-temperature grease formulations exceeding 250°C dropping points address unmet demand in artisan bread and industrial pastry oven chains.
- Plant-Based Protein Processing:Extrusion equipment for meat analogues requires novel lubrication protocols that incumbent suppliers have not fully specified.
Industry Challenges
- NSF H1 Certification Bottlenecks:Third-party registration timelines stretch to 6-9 months, delaying product launches against tightening customer qualification windows.
- Legacy Equipment Compatibility:Synthetic grease conversion in older Italian and Spanish machinery requires seal material upgrades that processors resist funding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Grease Market |
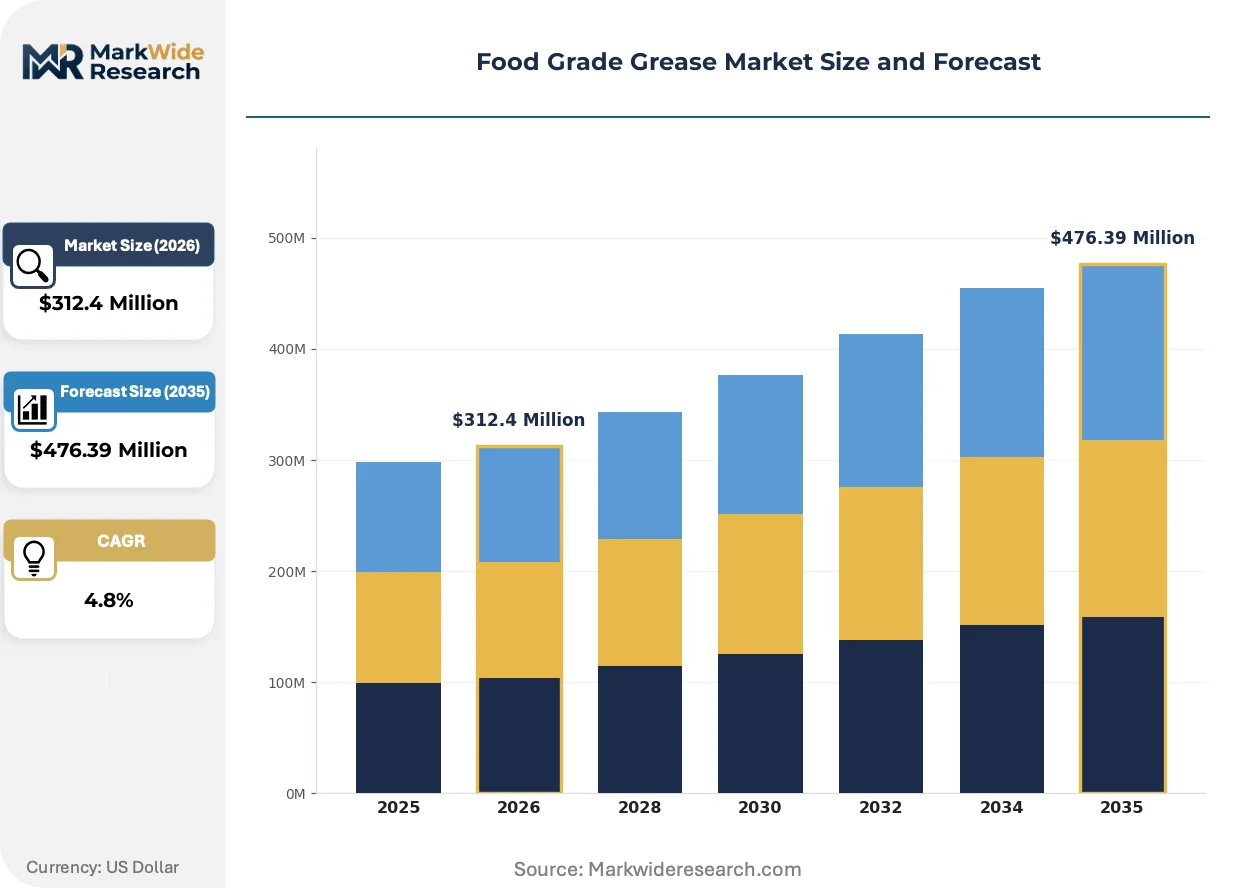
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Grease, Biodegradable Grease, High-Temperature Grease, Low-Temperature Grease End User: Food Processing, Beverage Production, Dairy Industry, Bakery Manufacturing Application: Lubrication, Maintenance, Assembly, Equipment Protection Packaging Type: Drums, Pails, Tubes, Cartridges |
| Companies Covered | Exxon Mobil Corporation, FUCHS, TotalEnergies, Shell plc, Chevron Corporation, Klüber Lubrication, Petro-Canada Lubricants, JAX Inc., Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Grease Market Emerging Trajectories
Synthetic base fluid technology is converging with digital monitoring systems to redefine equipment reliability metrics in continuous food processing. This convergence is compressing traditional maintenance intervals and recasting supplier value propositions.
Polyalphaolefin-vegetable ester hybrid formulations are converging with advanced thickener systems to deliver thermal stability above 220°C in bakery oven applications. German and Dutch industrial bakers are specifying these chemistries for 24-month re-greasing intervals. The technology is converging with total cost of ownership procurement models that displace price-per-kilogram evaluation.
ECHA's F-Gas Regulation phase-down schedules are accelerating elimination of fluorinated lubricants from freezer and cold-chain equipment across Nordic and Benelux processing facilities. Equipment OEMs are redesigning compressor architectures to accommodate non-fluorinated alternatives. Dairy and frozen dessert manufacturers in Denmark and Sweden face the most compressed compliance timelines.
Specification consolidation among multinational food processors is narrowing approved lubricant lists to 3-5 suppliers per facility. Category managers are unbundling grease supply from equipment maintenance contracts to capture direct procurement savings. This pattern is most pronounced in German and French meat and ready-meal processing plants with centralized technical purchasing functions.
Food Grade Grease Market Segmentation
Food grade grease procurement varies sharply by operational intensity and contamination risk exposure. Equipment thermal profiles and regulatory contact classifications dictate formulation selection across European processing infrastructure.
Product Type:
Capital deployment concentrates in synthetic and bio-based chemistries requiring dedicated blending equipment and NSF registration infrastructure.
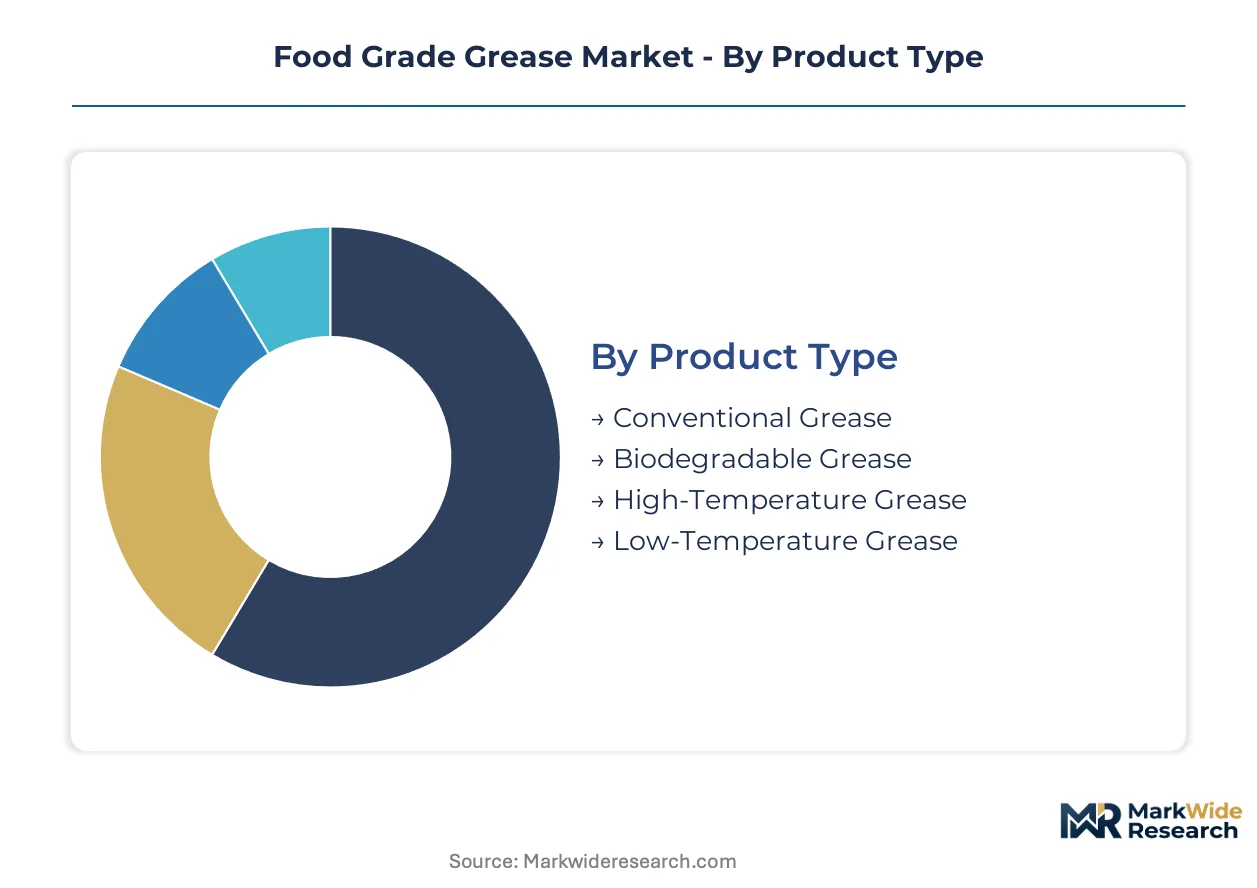
- Conventional Grease:White mineral oil and polyalphaolefin base stocks with aluminum complex or calcium sulfonate thickeners. German meat processors specify these formulations for ambient-temperature conveyor systems where thermal stability demands remain moderate. REACH compliance costs for legacy mineral oil supply chains are compressing margins in this segment.
- Biodegradable Grease:Vegetable ester and synthetic ester base fluids with biodegradable thickener systems. French baking equipment manufacturers specify these chemistries to meet EU Green Deal procurement mandates. ECHA substance authorization timelines stretch commercialization cycles to 18-24 months.
- High-Temperature Grease:Polyurea and complex soap thickeners with dropping points exceeding 250°C for oven proximity applications.
- Low-Temperature Grease:PAO-silicone hybrid formulations maintaining pumpability at -40°C for freezer and cold-chain equipment.
Most installed capacity flows through Conventional Grease. Expansion is steepest in Biodegradable Grease.
End User:
Volume concentration tracks dairy and meat processing automation intensity across Benelux and Alpine manufacturing corridors.
- Food Processing:General meat, poultry, and prepared meal manufacturing requiring NSF H1-certified lubricants for incidental contact scenarios. Dutch ready-meal facilities specify synthetic greases for automated portioning equipment. EU AI Act predictive maintenance integration is reshaping procurement protocols in this segment.
- Beverage Production:Bottling line conveyor lubrication and filler valve maintenance. Italian mineral water and soft drink bottlers favor cartridge-dispensed greases for rapid changeover compliance. Carbonated beverage CO2 compatibility constraints limit thickener selection.
- Dairy Industry:Homogenizer, separator, and pasteurizer lubrication with strict H1 contact protocols.
- Bakery Manufacturing:Oven chain and proofer equipment thermal stability requirements.
Procurement volume concentrates in Food Processing. Technology upgrade rates are climbing fastest in Dairy Industry.
Application:
Service intensity varies by equipment criticality and failure cost exposure in continuous production environments.
- Lubrication:Friction reduction on bearings, gears, and sliding surfaces in mixers, extruders, and conveyors. German sausage processing lines specify 24-month re-greasing intervals for PAO-vegetable ester hybrids. Thermal degradation monitoring is displacing calendar-based maintenance schedules.
- Maintenance:Scheduled equipment servicing and component replacement protocols. French dairy cooperatives bundle grease supply with OEM service contracts. Unbundling trends are shifting procurement toward direct supplier relationships.
- Assembly:Initial equipment build and commissioning lubrication.
- Equipment Protection:Corrosion prevention and seal conditioning during storage or seasonal shutdown.
Operational expenditure concentrates in Lubrication. Digital integration is advancing most quickly in Maintenance.
Packaging Type:
Distribution economics and contamination control protocols shape container selection across facility scales.
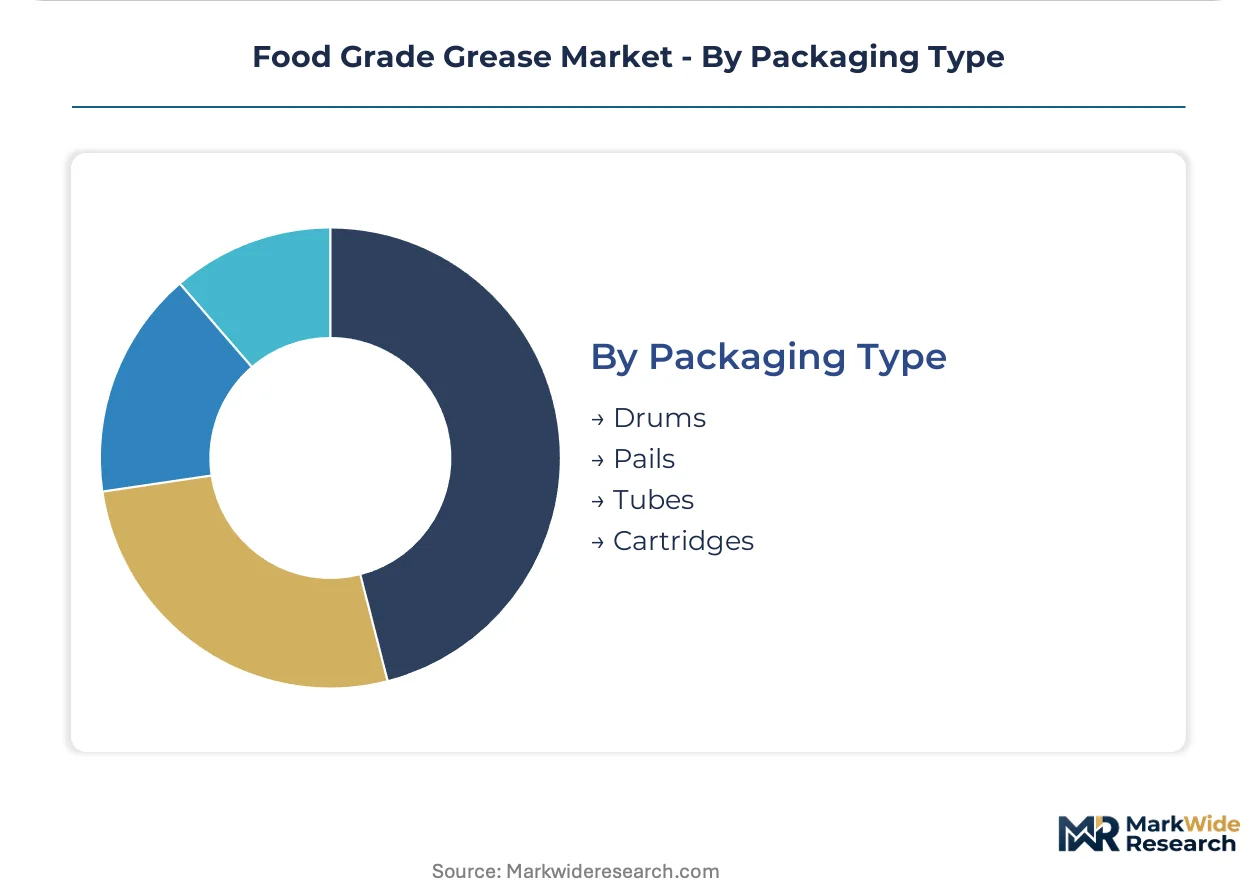
- Drums:Bulk supply for central lubricant storage and automated dispensing systems. Large German meat processing campuses specify 180kg steel drums with closed transfer systems. Drum return logistics and cleaning costs are prompting packaging format reevaluation.
- Pails:Intermediate volume for departmental distribution in mid-size facilities. Belgian chocolate manufacturers favor 15kg pails for enrober line maintenance. Pail handling ergonomics influence procurement specifications.
- Tubes:Precision application for small-component lubrication.
- Cartridges:Grease gun compatibility for rapid field maintenance.
Volume throughput concentrates in Drums. Format diversification is expanding most rapidly in Cartridges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial lubrication chemistry originated in German chemical engineering laboratories during the early twentieth century, establishing quality protocols that now govern food-grade formulation standards across European processing infrastructure.
Germany
Meat processing automation and bakery equipment manufacturing drive specification intensity for NSF H1-certified greases. EU Green Deal procurement mandates compel processors in Lower Saxony to source vegetable ester-based formulations. Munich-area equipment OEMs now bundle synthetic grease supply with maintenance service contracts for sausage production lines.
France
Baking and confectionery applications concentrate demand for high-temperature formulations exceeding 250°C thermal stability. REACH chemical authorization through ECHA accelerates replacement cycles for legacy mineral oil lubricants in Paris Basin industrial bakeries. Lyon-area dairy cooperatives unbundle grease procurement from OEM service agreements to capture direct sourcing savings.
Italy
Dairy equipment maintenance protocols mandate NSF H1 lubricants for homogenizers and separators across Emilia-Romagna processing clusters. Stricter contamination risk standards in Parmigiano-Reggiano production zones favor synthetic formulations with extended re-greasing intervals. Milan-based equipment distributors now stock PAO-vegetable ester hybrids for 24-month service cycles.
Netherlands
Ready-meal manufacturing and beverage bottling automation concentrate procurement volume for synthetic greases in cartridge-dispensed formats. EU AI Act predictive maintenance integration reshapes technical purchasing protocols at Rotterdam-area processing campuses. Eindhoven-region equipment OEMs redesign conveyor architectures to accommodate sensor-enabled lubricant replenishment systems.
United States
Export compliance requirements for FDA 21 CFR 178.3570 sustain demand for white mineral oil and polyalphaolefin base stocks in Midwest meat processing corridors. Chicago-area protein processors specify closed-transfer drum systems to eliminate contamination risk in high-volume production environments. Wisconsin dairy equipment manufacturers qualify synthetic formulations for homogenizer applications serving international markets.
Food Grade Grease Market Vendor Landscape
Capital-heavy producers with integrated base oil supply chains compete with asset-light specialty formulators focused on NSF registration and application engineering. The vendor base stratifies across three tiers: multinational petroleum majors with captive feedstock access, European specialty lubricant houses with deep formulation expertise, and regional blenders serving price-sensitive ambient-temperature applications. Two dominant competitive moves reshape positioning: backward integration into bio-based feedstock cultivation, and technology licensing agreements that accelerate synthetic chemistry commercialization.
Within the specialty formulator tier, FUCHS and Klüber Lubrication occupy positions anchored in European food machinery applications, while Exxon Mobil Corporation exemplifies the integrated petroleum major archetype with cost competitiveness sustained through captive base oil supply. These three entities represent distinct strategic approaches to the regulatory complexity and thermal performance demands now standard in bakery and dairy processing equipment specifications.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| FUCHS |
| TotalEnergies |
| Shell plc |
| Chevron Corporation |
| Klüber Lubrication |
| Petro-Canada Lubricants |
| JAX Inc. |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Specialized lubricant formulation chemists concentrated in Germany's Rhine-Ruhr industrial corridor create labor-cost differentials that widen pricing spreads between premium synthetic grades and economy mineral oil formulations. This workforce clustering allows established blenders to command margin premiums on NSF H1-certified products while regional competitors compete on ambient-temperature conventional grease pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with differentiation anchored in NSF H1 registration tier and thermal performance specification. Premium synthetic formulations with 250°C dropping points command substantial markups over conventional mineral oil grades. Cost compression in the economy tier intensifies because REACH compliance expenses erode margins on legacy formulations. Small-scale Italian dairy processors exhibit highest price sensitivity, while German meat processing conglomerates prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
NSF H1 certification gating restricts qualified supplier pools to blenders with dedicated registration infrastructure and analytical laboratory capabilities. Base fluid supply concentrates in Germany, the Netherlands, and Belgium, drawing from white mineral oil refineries and polyalphaolefin polymerization facilities. Thickener systems and oxidation inhibitor packages hinge on specialty chemical suppliers in Western Europe. Single-source vulnerability exists for high-performance polyurea thickeners used in 200°C+ bakery applications. Distribution runs through authorized industrial lubricant distributors with technical service capabilities, bypassing commodity chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Grade Grease Market functions as a regulatory compounder where EU Green Deal decarbonization mandates continuously expand demand for biodegradable and bio-based formulations. REACH authorization timelines and NSF registration requirements create durable competitive moats around incumbent positions.
For Market Incumbents: Acquire vegetable ester cultivation and refining assets to secure bio-based feedstock supply chains against price volatility. Expand blending capacity in Italy's Emilia-Romagna dairy processing corridor to capture specification pull-through from equipment OEMs. Defensive positioning requires preemptive investment in EU AI Act-compliant predictive maintenance system integration before customer qualification windows tighten further. For New Entrants and Emerging Players: The pricing gap between premium synthetic formulations and economy mineral oil grades offers entry points for mid-tier hybrid products with partial bio-based content. Target France's industrial bakery segment where REACH-driven replacement cycles create specification openness for new chemistries. A technical service partnership model with regional equipment distributors accelerates customer qualification without captive NSF registration infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders with established NSF H1 portfolios but limited geographic reach. Long-term viability over the coming decade favors assets with demonstrated ECHA regulatory navigation capabilities and synthetic formulation expertise. Watch for inflection signals in EU F-Gas Regulation compliance timelines that will force accelerated fluorinated lubricant replacement in Nordic cold-chain equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures vegetable ester supply chains against agricultural commodity volatility for EU Green Deal compliance. |
| NSF H1 Certification Infrastructure Investment | Compresses product launch timelines from 18-24 months to 6-9 months against tightening customer windows. |
| Predictive Maintenance System Partnerships | Positions grease formulations within EU AI Act-compliant automated replenishment architectures in Dutch processing facilities. |
| High-Temperature Formulation R&D Expansion | Addresses unmet 250°C+ thermal stability demand in French artisan and industrial bakery oven chains. |
| Geographic Expansion into Italian Dairy Corridor | Captures specification pull-through from homogenizer and separator OEMs mandating H1-certified lubricants. |
Methodological Framework
Direct dialogue with lubricant formulation chemists, food processing plant maintenance directors, equipment OEM procurement teams, and NSF International registration specialists grounded qualitative findings. Secondary validation drew from ECHA substance authorization databases, EU F-Gas Regulation implementation schedules, SEC filings of integrated petroleum majors, and trade flow data for white mineral oil and polyalphaolefin feedstocks. Bottom-up volume modeling across product types, end-user segments, and regional processing clusters was cross-checked against top-down market sizing from supply-side capacity analysis.
Output projections across the analysis window reflect segmented modeling of synthetic, biodegradable, high-temperature, and conventional grease categories by application intensity in dairy, bakery, meat processing, and beverage equipment. CAGRs were derived from regression analysis of historical procurement patterns against regulatory milestone timelines and equipment automation adoption curves. Forecast inputs incorporated ECHA REACH authorization velocity, EU AI Act implementation pace for predictive maintenance, and thermal performance specification evolution in oven chain applications.
Caveats apply where ECHA substance restriction expansions, EU Green Deal procurement mandate acceleration, or bio-based feedstock agricultural supply disruptions could materially shift the outlook. Deviation in NSF H1 registration timeline compression or synthetic base oil price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Global Bio Based Isoprene Market