
 Emulsion Explosive Market | 2026-2036
Emulsion Explosive Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsion Explosive Market Analysis
Electronic detonation integration is tilting emulsion explosive systems toward precision blasting protocols that cut vibration and improve fragmentation control. Orica Limited leverages its digital blasting platforms to anchor technology leadership across hard-rock mining contracts. Dyno Nobel sustains North American manufacturing scale through backward integration into ammonium nitrate supply. MAXAM competes on bulk delivery logistics across Latin American copper and gold operations.
Emulsion explosives consist of oxidizer salts—predominantly ammonium nitrate—dispersed in a continuous fuel oil phase, stabilized by emulsifiers to yield a water-resistant, high-velocity detonation product with densities typically ranging from 1.15 to 1.35 g/cm³; the formulation serves primarily to fracture rock in surface and underground excavation with reduced fume and improved safety profiles versus traditional dynamite. Water-resistant formulations lead product type demand where wet borehole conditions dominate underground and coastal mining. Bulk delivery mode captures the fastest expansion as open-pit operators abandon packaged products in favor of on-site mixing trucks that reduce inventory risk and labor exposure. Quarrying application remains the most mature segment with price-sensitive procurement and established supplier relationships.
OSHA and MSHA standards in the United States govern worker exposure limits and storage siting, while Australia's state-based explosives regulators enforce licensing regimes that favor suppliers with integrated technical services. The EU Explosives Directive harmonizes transport classification and stability testing across member states, creating compliance barriers for non-European exporters. Stakeholders must monitor how carbon accounting frameworks reshape explosives supply chain disclosure requirements without waiting for mandated reporting deadlines.
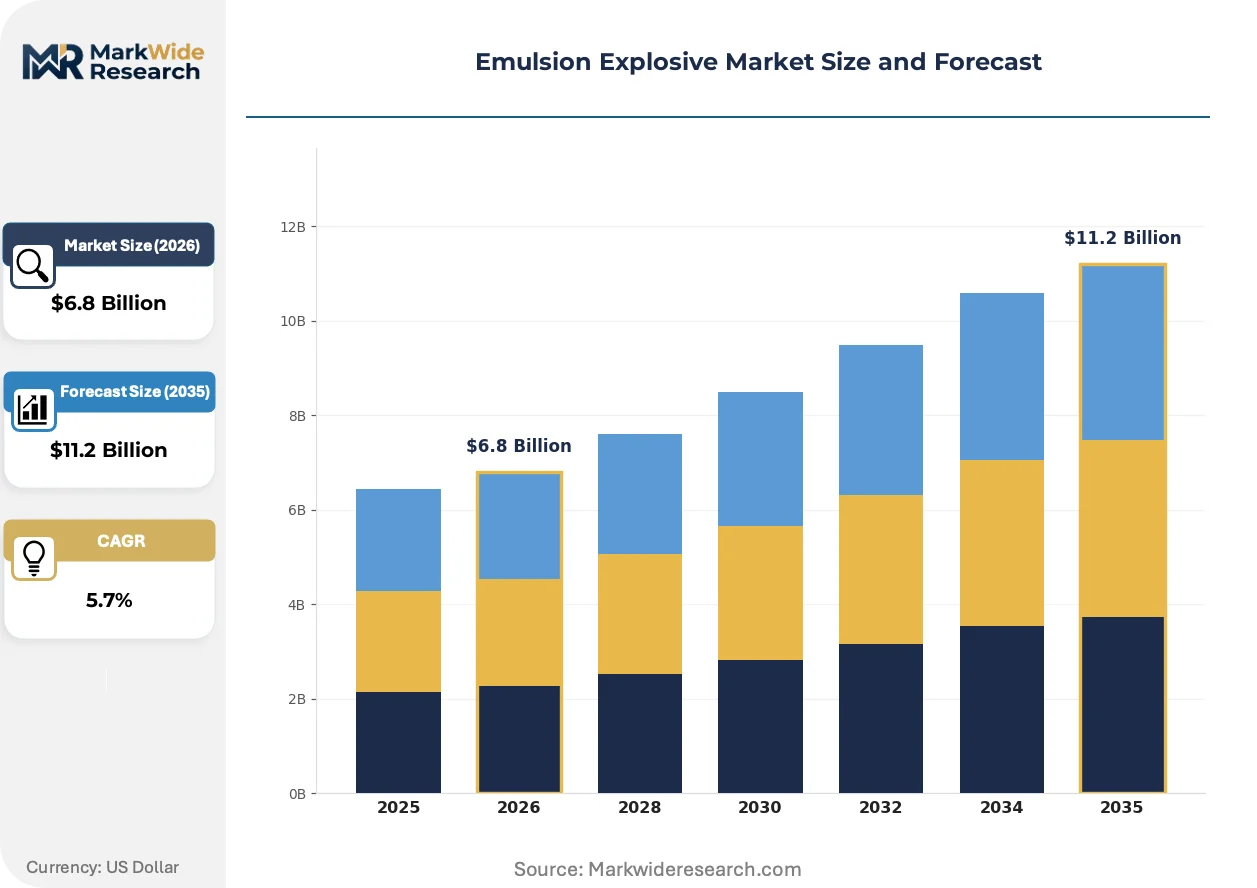
Market Dynamics
Electronic detonation integration is compressing the operational gap between blast design and fragmentation outcomes, forcing suppliers to bundle hardware with chemistry. This convergence is reconfiguring procurement from commodity purchasing toward integrated blasting services contracts.
Growth Catalysts
- Pilbara Iron Ore Expansion:Australia's Pilbara iron ore belt is driving bulk emulsion consumption as automated haulage systems demand precision fragmentation profiles that packaged explosives cannot deliver.
- EU Explosives Directive Reformulation Mandate:Stricter stability testing and transport classification rules under the EU Explosives Directive are accelerating formulation upgrades that improve shelf-life and reduce thermal sensitivity.
- Copper Corridor Deepening:Underground metal mining operations in Chile's copper corridors are expanding bulk emulsion deployment as ore grades decline and extraction moves below water tables.
Market Restraints
- Ammonium Nitrate Supply Concentration:Captive ammonium nitrate production is concentrated among vertically integrated suppliers, creating input cost volatility for independent blenders lacking backward integration.
- Underground Thermal Stability Limitations:Emulsion formulations face performance degradation above 40°C in deep South African gold mines, restricting application depth without costly cooling infrastructure.
- ANFO Substitution Threat:Ammonium nitrate-fuel oil mixtures retain cost advantage in dry surface quarries, pressuring emulsion pricing in price-sensitive procurement environments.
Strategic Opportunities
- Indonesian Nickel Belt Penetration:Laterite nickel mining in Sulawesi and Halmahera presents underdeveloped demand as open-pit operations transition from coal to critical mineral extraction.
- Carbon Accounting Disclosure Tailwinds:EU CSRD reporting requirements are creating preference for suppliers with verified supply chain emissions data, favoring early movers in Scope 3 tracking.
- Drone-Assisted Blast Monitoring Convergence:Integration of unmanned aerial systems with electronic initiation networks enables real-time muckpile analysis, opening service revenue streams beyond product sales.
Industry Challenges
- Shot Firer Skill Compression:Electronic blasting systems require technicians capable of programming delay sequences and interpreting vibration data, creating talent gaps in traditional explosives handling workforces.
- Legacy Initiation System Integration:Mining operations with mixed fleets face complexity harmonizing electronic detonators with existing non-electric inventory without full capital replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsion Explosive Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Resistant, High-Density, Oil-Based, Gelatinous Application: Mining, Construction, Demolition, Quarrying End User: Contractors, Miners, Oil & Gas Producers, Construction Firms Delivery Mode: Bulk Delivery, Packaged Explosives, Truck-mounted, Aerial Delivery |
| Companies Covered | Austin Powder Company, EPC Groupe, Orica Limited, Sasol, BME, Dyno Nobel, MAXAM, Enaex, AEL Mining Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsion Explosive Market Emerging Trajectories
Precision blasting protocols are displacing empirical drill-and-blast methods as sensor networks and initiation electronics merge with explosive chemistry. This convergence is compressing the feedback loop between blast design and excavation efficiency.
Microsphere-sensitized emulsion formulations are hybridizing density control with detonation velocity modulation. Underground metal miners in Canada and Australia are adopting these blends for wet borehole conditions where traditional gassing agents fail. The technology is hybridizing product differentiation strategies around fragmentation predictability rather than bulk energy content alone.
REACH chemical registration requirements are tightening emulsifier sourcing constraints across European manufacturing. Industrial consequence includes forced reformulation cycles and supplier qualification delays for non-EU additive producers. Bulk emulsion categories with complex surfactant packages face the steepest compliance cost escalation.
Buyer concentration among tier-one mining houses is compressing supplier negotiation leverage and extending payment terms. Integrated service contracts are displacing spot purchasing for ammonium nitrate and emulsion supply across Australian iron ore and Chilean copper operations. This pattern is most visible in Western Australia where three operators control over eighty percent of bulk explosive procurement volume.
Emulsion Explosive Market Segmentation
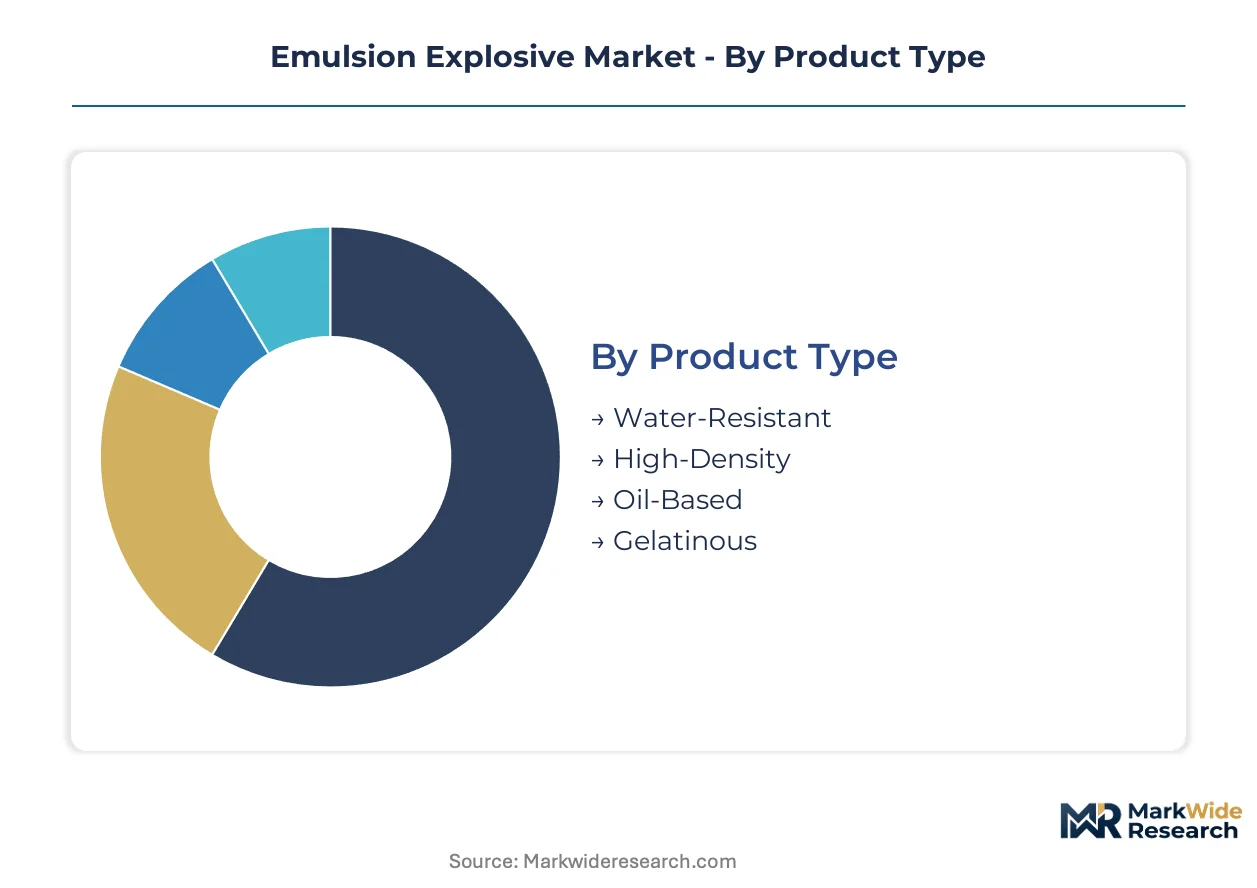
Emulsion explosive procurement patterns diver sharply across product formulations and delivery configurations. Mining operators select segments based on borehole conditions, fragmentation requirements, and inventory risk tolerance rather than price alone.
Product Type:
Water-resistant formulations turn inventory fastest in wet mining environments, while oil-based variants sit longer due to narrower application windows. High-density products command extended production cycles tied to specialized blasting contracts.
- Water-Resistant:Ammonium nitrate microspheres suspended in continuous fuel oil phase with specialized emulsifiers create hydrophobic stability for saturated boreholes. Australia's Pilbara iron ore operations specify these formulations exclusively for monsoon-season blasting where dry alternatives fail. The segment anchors procurement volumes across underground base metal mines in Canada and Chile.
- High-Density:Densities exceeding 1.30 g/cm³ achieve through microsphere loading or chemical gassing for hard-rock fragmentation in deep excavation. South African gold mines below 3,000 meters deploy these blends where confinement pressure demands elevated detonation velocity. Thermal stability limitations above 40°C restrict deployment depth without cooling infrastructure.
- Oil-Based:Continuous hydrocarbon phase formulations prioritize shelf stability over water resistance for arid surface operations.
- Gelatinous:Thixotropic consistency enables vertical borehole placement without segregation in irregular ground conditions.
Water-resistant formulations anchor the volume base while high-density products gain share at the steepest rate.
Application:
Cost tier separation runs deepest in this category, with quarrying operations squeezing suppliers on price while mining contracts absorb premium formulations for fragmentation control.
- Mining:Underground metal extraction in Australia's nickel sulfide deposits and Chile's porphyry copper systems consumes bulk emulsion for controlled wall stability and ore dilution management. Declining head grades force deeper extraction below water tables, expanding water-resistant formulation demand. Procurement concentrates among tier-one operators with integrated blasting service contracts.
- Quarrying:Surface aggregate producers in Germany's Bavarian limestone belt and France's Massif Central prioritize ANFO substitution only where wet conditions mandate emulsion chemistry. Price-sensitive spot purchasing dominates, with independent contractors sourcing packaged products through distributor networks rather than direct supplier relationships.
- Construction:Tunneling and infrastructure excavation specify emulsion for vibration control in urban proximity.
- Demolition:Controlled structure removal requires precision initiation compatibility with electronic detonator networks.
Mining commands the revenue concentration while construction applications expand most quickly through urban infrastructure mandates.
End User:
Customer type determines contract structure more than formulation selection, with miners demanding integrated service bundles and contractors accepting commodity terms.
- Miners:Integrated mining houses in Western Australia and northern Chile negotiate multi-year supply agreements bundling emulsion chemistry with electronic initiation systems and blast design software. Technical service integration locks in supplier relationships beyond price competition. Procurement leverage concentrates among three Pilbara operators controlling the majority of regional explosive volume.
- Contractors:Independent drilling and blasting contractors serving construction and quarry markets purchase packaged products through regional distributors with limited technical support attachment. Margin compression forces inventory minimization and just-in-time delivery demands.
- Oil & Gas Producers:Seismic exploration programs specify specialized low-velocity formulations for controlled energy release.
- Construction Firms:Infrastructure developers increasingly outsource blasting to specialized contractors rather than maintaining in-house explosive licenses.
Miners anchor the volume base while oil and gas producers gain share at the steepest rate through unconventional reservoir stimulation demand.
Delivery Mode:
Supply chain configuration separates bulk on-site mixing from packaged inventory risk, with truck-mounted systems collapsing lead times for remote operations.
- Bulk Delivery:Non-explosive precursor components—ammonium nitrate solution and fuel oil—transport separately to mixing trucks at blast sites, eliminating packaged inventory hazards. Australia's automated haulage iron ore mines mandate bulk systems for continuous operation compatibility. The model shifts liability from mine site to supplier while reducing labor exposure.
- Packaged Explosives:Cartridge and bagged products persist in small-scale quarrying and construction where blast frequency cannot justify on-site mixing infrastructure. Shelf-life constraints and storage licensing burdens push marginal users toward contractor outsourcing.
- Truck-mounted:Mobile mixing units service remote exploration camps and intermittent construction projects without fixed plant investment.
- Aerial Delivery:Helicopter transport reaches mountainous terrain inaccessible to ground logistics in Canadian cordillera operations.
Bulk delivery anchors the volume base while truck-mounted systems gain share at the steepest rate through exploration camp mobilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian bulk emulsion exports flow predominantly to Southeast Asian nickel and copper operations, establishing a trade corridor that shapes regional supply security calculations. Chilean producers serve Peruvian and Bolivian mining projects through overland bulk delivery networks. South African formulation specialists export across sub-Saharan Africa to gold and platinum belt operations.
Australia
Pilbara iron ore automation and Queensland coal seam gas drilling drive bulk emulsion procurement at scale. State-based explosives regulators in Western Australia and Queensland enforce licensing regimes favoring suppliers with integrated technical service capabilities. The Pilbara region hosts the densest concentration of on-site mixing infrastructure globally, with three operators controlling the majority of regional explosive volume.
Chile
Declining copper ore grades below water tables in the Atacama Desert expand water-resistant formulation demand for underground extraction. The national mining regulator SERNAGEOMIN mandates stability testing protocols that align with EU Explosives Directive benchmarks. The copper corridors between Antofagasta and Calama concentrate bulk delivery infrastructure serving Codelco and private mine operators.
South Africa
Deep-level gold mining below 3,000 meters generates demand for high-density formulations, though thermal degradation above 40°C restricts deployment without cooling systems. The Department of Mineral Resources and Energy enforces strict storage siting rules under the Explosives Act. The Witwatersrand Basin remains the primary consumption cluster, with suppliers maintaining dedicated mixing plants at individual mine sites.
Canada
Nickel sulfide mining in Sudbury and gold operations in Ontario's Abitibi belt adopt microsphere-sensitized blends for wet borehole conditions. Health Canada and provincial regulators harmonize transport classification with US OSHA and MSHA standards. The Canadian cordillera operations in British Columbia utilize helicopter aerial delivery to reach mountainous terrain inaccessible to ground logistics.
Indonesia
Laterite nickel mining in Sulawesi and Halmahera presents underdeveloped demand as open-pit operations transition from coal to critical mineral extraction. The Ministry of Energy and Mineral Resources oversees explosives licensing with evolving technical standards. The Sulawesi nickel belt is attracting bulk delivery infrastructure investment as Chinese and Australian mining houses expand processing capacity.
Emulsion Explosive Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Three to five vertically integrated suppliers dominate bulk emulsion supply to tier-one mining houses, while regional blenders serve quarrying and construction markets through distributor networks. Strategic archetypes separate integrated blasting service providers from standalone chemistry suppliers and niche formulation specialists. Competitive moves concentrate on backward integration into ammonium nitrate supply and geographic expansion through local blending plant acquisition.
Within the integrated service provider tier, Orica Limited and Dyno Nobel exemplify channel-controlling archetypes that bundle electronic initiation systems with bulk chemistry. MAXAM occupies a position representing European-based competitors with Latin American operational density. Among regional specialists, Austin Powder Company and AEL Mining Services sit within the independent blender category serving construction and quarry markets without full vertical integration.
| Leading Market Players |
|---|
| Austin Powder Company |
| EPC Groupe |
| Orica Limited |
| Sasol |
| BME |
| Dyno Nobel |
| MAXAM |
| Enaex |
| AEL Mining Services |
| Others |
Supply Flow & Price Mechanics
Ammonium nitrate supply concentration among vertically integrated producers determines both the premium-to-economy pricing spread across bulk and packaged segments and the geographic clustering of blending infrastructure near captive feedstock sources. This input dependency forces independent blenders into contract terms that compress margins while rewarding backward-integrated suppliers with pricing power in volatile feedstock cycles.
Pricing Analysis
Electronic initiation compatibility gaps separate current-generation precision blasting services from prior-generation commodity chemistry sales, with next-generation drone-integrated monitoring systems widening the premium tier. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by technical service bundling and electronic detonator integration rather than chemistry alone. Cost compression in quarrying-grade packaged products is intensifying because ANFO substitution threats squeeze spot-market emulsion pricing. Contractors serving construction and quarry markets exhibit the highest price sensitivity, while tier-one mining houses in Western Australia and Chile absorb premium formulations for fragmentation control.
Supply Chain Analysis
Tariff exposure between EU member states and non-European additive producers dominates supply chain risk as REACH chemical registration requirements tighten emulsifier sourcing constraints. Manufacturing concentration centers on Australia, Chile, and South Africa for bulk emulsion production serving regional mining belts. Raw material dependencies draw from ammonium nitrate solution, fuel oil, and specialized surfactant packages. Single-source vulnerability persists for microsphere sensitizers and complex emulsifier chemistries subject to regulatory qualification delays. Distribution runs through on-site mixing truck networks for bulk delivery, packaged product distributor channels for quarrying, and helicopter aerial logistics for remote Canadian cordillera operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three Pilbara operators controlling the majority of Western Australian bulk explosive procurement, forcing suppliers toward integrated service contracts that commoditize standalone chemistry.
For Market Incumbents: Build switching-cost moats through electronic initiation system lock-in that binds blast design software to emulsion supply contracts. Deepen captive ammonium nitrate production to insulate margin structures from feedstock volatility threatening independent blenders. Invest in cooling infrastructure partnerships for South African gold mines below 3,000 meters where thermal stability limitations restrict high-density formulation deployment. For New Entrants and Emerging Players: Indonesian laterite nickel operations in Sulawesi and Halmahera represent the most penetrable entry point as Chinese and Australian mining houses expand processing capacity without established explosive supplier relationships. Truck-mounted mobile mixing units for remote exploration camps offer asset-light service revenue without fixed plant investment. Target carbon accounting disclosure readiness as a go-to-market wedge, positioning early Scope 3 tracking capabilities ahead of EU CSRD reporting requirements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated blasting service providers over standalone chemistry suppliers. Long-term viability over the next decade hinges on digital blasting platform ownership rather than manufacturing scale alone. Acquisition target archetype: regional blenders with established distributor networks in Southeast Asian nickel belts or Latin American copper corridors. Watch for electronic detonator adoption rates as the inflection signal separating service-integrated winners from commodity-margin losers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonium Nitrate | Captive feedstock supply insulates margin structures from input cost volatility affecting independent competitors. |
| Electronic Initiation Platform Acquisition | Digital blasting system ownership locks in multi-year service contracts with tier-one mining houses. |
| Indonesian Blending Plant Expansion | Laterite nickel mining growth in Sulawesi creates first-mover advantage in underdeveloped explosive demand. |
| Carbon Accounting Certification Investment | Verified Scope 3 emissions data attracts EU CSRD-compliant procurement from sustainability-focused miners. |
| Drone-Assisted Blast Monitoring Development | Real-time muckpile analysis integration opens recurring service revenue beyond product-only sales models. |
Methodological Framework
Operator-level perspectives from mine site engineers, procurement managers at tier-one mining houses, explosives distribution channel partners, and blasting service technicians anchored the qualitative base for this study. Primary interviews combined with secondary validation from SEC filings of publicly traded suppliers, Australian state explosives regulator licensing databases, Chilean SERNAGEOMIN stability testing protocols, and EU Explosives Directive compliance records. Bottom-up volume estimates from individual mine site consumption patterns triangulated against top-down regional production capacity assessments.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation modeling across product formulation type, delivery mode configuration, application sector, and end-user contract structure. CAGRs derived from trend extrapolation of bulk delivery adoption rates, electronic initiation penetration curves, and water-resistant formulation demand in deepening underground extraction. Industry-specific forecast inputs incorporated Pilbara automation timelines, Chilean copper grade decline curves, and Indonesian nickel processing capacity buildouts.
Practitioners should monitor ammonium nitrate feedstock price volatility, EU REACH emulsifier registration delays, and South African deep-mine cooling infrastructure investment for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Plastic Contract Manufacturing Market