
 Phosphate Rock Market | 2026-2036
Phosphate Rock Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphate Rock Market Intelligence
High-purity, low-cadmium phosphate rock is redrawing competitive positioning among major producers. This shift prioritizes quality over sheer volume for access to premium agricultural markets. OCP Group leverages its extensive Moroccan reserves to supply a significant portion of the market. The Mosaic Company dominates production in North America, focusing on integrated fertilizer manufacturing. PhosAgro sustains its market presence through large-scale operations and logistical advantages in supplying European and Asian markets.
Phosphate rock is a naturally occurring sedimentary rock containing high concentrations of phosphate minerals, primarily apatite. Its commercial value is determined by the phosphorus pentoxide (P2O5) content, which is the essential raw material for producing phosphoric acid. Fertilizer production remains the dominant application, consuming the vast majority of mined output. Open-pit mining is the most prevalent mining method, reflecting the geological formation of most large-scale commercial deposits.
Regulatory frameworks increasingly govern the market, particularly concerning environmental impact and final product safety. The European Union's regulations on cadmium levels in fertilizers directly influence trade flows and beneficiation investments. In parallel, environmental agencies like the US EPA and China's MEE impose stringent rules on mining waste and water management. Producers must now balance investments in purification technologies against the cost of compliance in key export destinations.
Market Dynamics
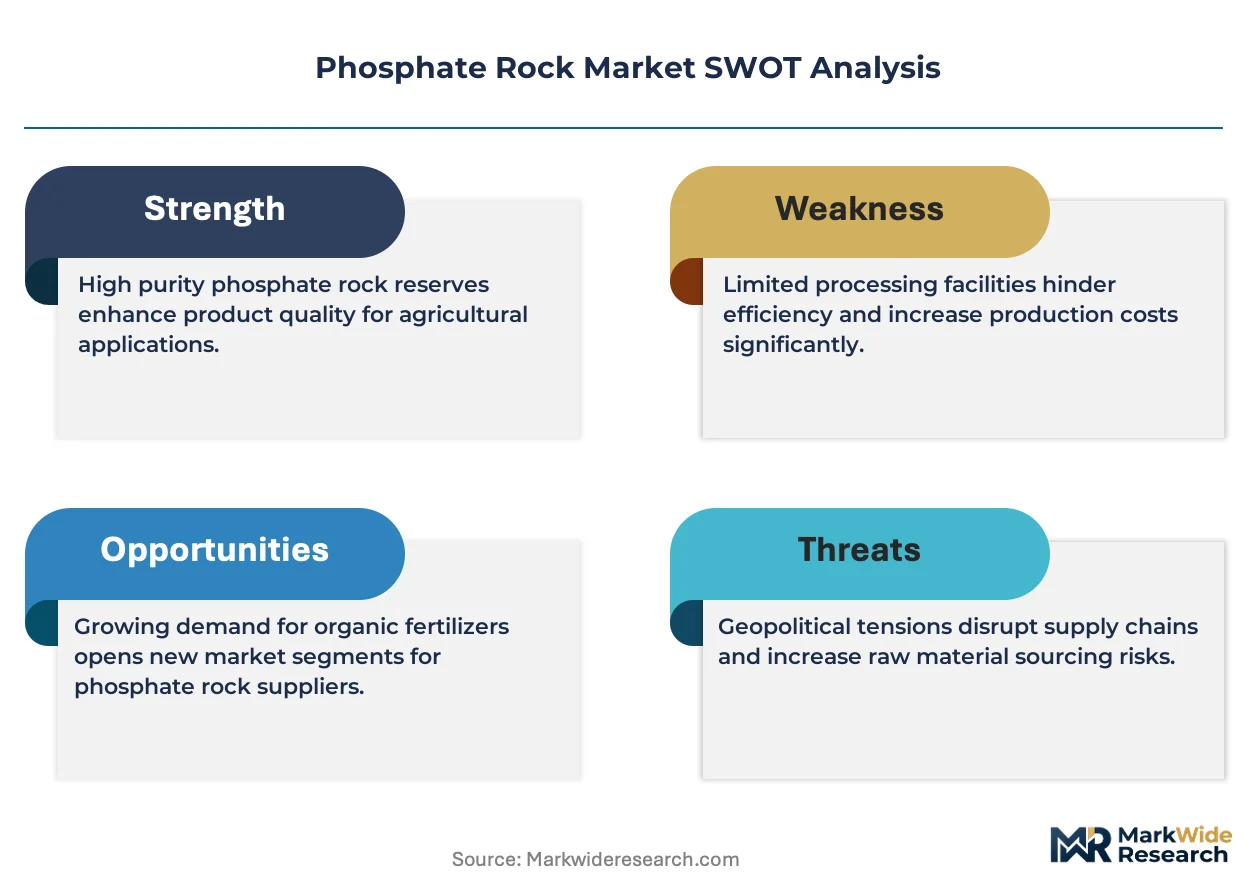
The central tension in the phosphate rock market is the divergence between high-volume, standard-grade supply and the growing premium for low-cadmium, high-purity material. This quality bifurcation, driven by stringent food safety regulations, is creating distinct value chains and competitive arenas.
Growth Catalysts
- Sustained Agricultural Demand:Persistent requirements for phosphate fertilizers to support crop yields in major agricultural economies, including Brazil and India, provide a foundational demand floor for the market.
- Advanced Beneficiation Technology:Innovations in flotation and purification processes enable the economic processing of lower-grade or complex ores, expanding the base of commercially viable reserves.
- National Food Security Policies:Government initiatives in numerous countries aimed at achieving agricultural self-sufficiency and boosting domestic food production directly stimulate fertilizer consumption and, consequently, phosphate rock demand.
Market Restraints
- High Input Costs:The mining and beneficiation of phosphate rock are highly energy- and water-intensive, exposing producers to significant cost volatility in commodity and utility markets.
- Geopolitical Supply Risk:A heavy concentration of high-grade, low-contaminant reserves within a limited number of countries, particularly in North Africa, creates supply chain vulnerabilities for importing nations.
- Stringent Environmental Regulations:Compliance with strict rules on tailings management, water usage, and land rehabilitation, such as those enforced by the US EPA, adds substantial operational costs and project delays.
Strategic Opportunities
- Battery Materials Application:The rapid expansion of the electric vehicle market creates a significant opportunity for purified phosphoric acid in the production of lithium iron phosphate (LFP) batteries.
- African Agricultural Development:Under-fertilized agricultural land across Sub-Saharan Africa represents a vast, long-term opportunity for market expansion as farming practices modernize and intensify.
- Circular Economy Integration:Developing technologies to recover and recycle phosphorus from waste streams, such as municipal wastewater and agricultural runoff, offers a path to a more sustainable supply.
Industry Challenges
- Capital-Intensive Projects:The development of new open-pit mines and associated processing infrastructure requires massive upfront capital investment, posing a high barrier to entry and expansion.
- Logistical Hurdles:Managing the bulk transportation of phosphate rock from often remote mining locations to processing plants and international ports presents significant and costly logistical complexities.
- Permitting and Social License:Securing the necessary environmental permits and gaining local community acceptance for new mining projects is a lengthy and increasingly contentious process globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphate Rock Market |
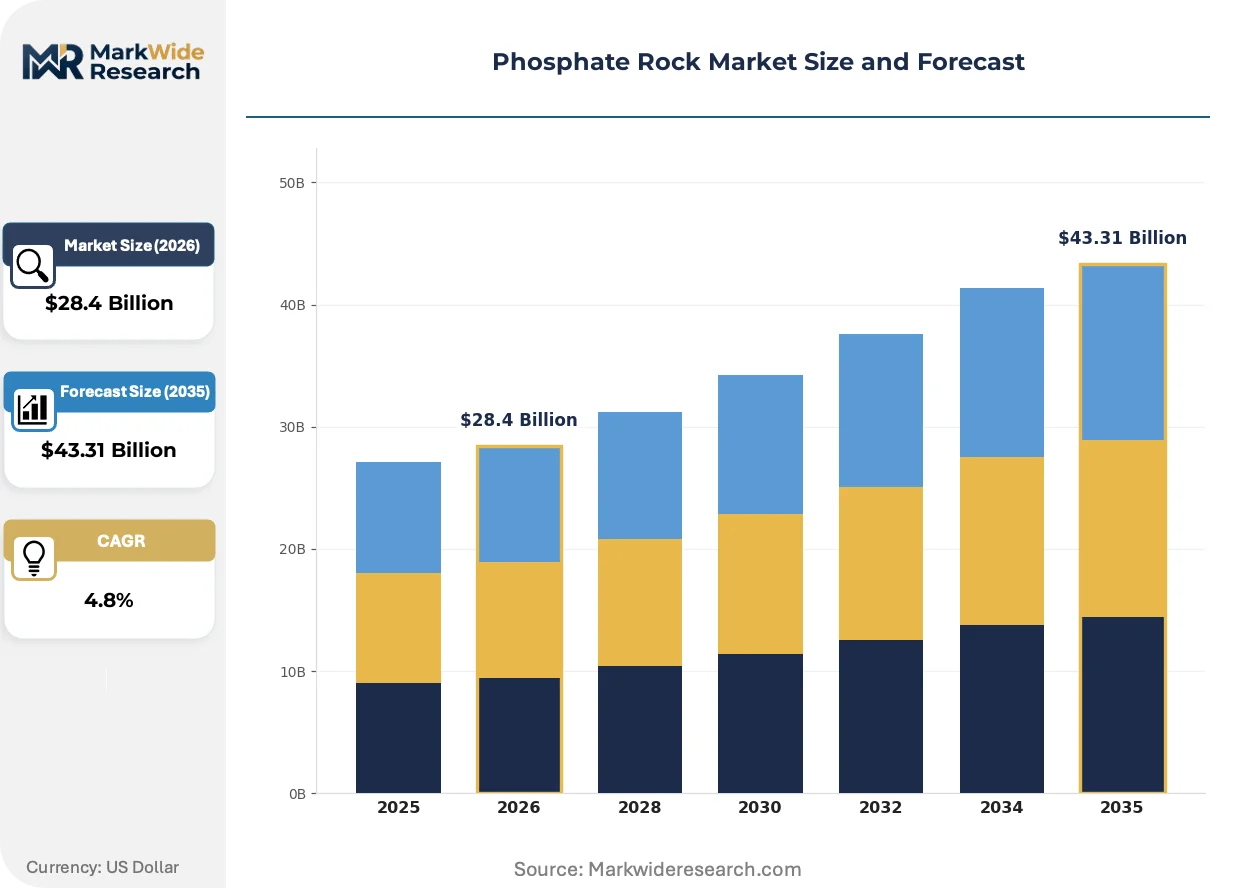
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Authigenic Phosphate, Biogenic Phosphate, Residual Phosphate, Volcanic Phosphate Application: Fertilizer Production, Animal Feed Supplements, Food Additives, Industrial Chemicals, Water Treatment Mining Method: Open-pit Mining, Underground Mining, Solution Mining, Dredging End User Industry: Chemical Manufacturing, Agriculture Cooperatives, Livestock Producers, Environmental Services |
| Companies Covered | PhosAgro, Itafos, The Mosaic Company, Hubei Xingfa Chemicals, Jordan Phosphate Mines Company, Nutrien Ltd, Ma'aden, Guizhou Kailin Holdings (Group) Co., Ltd., OCP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphate Rock Market Strategic Shifts & Innovations
The market is being reshaped by the dual pressures of environmental accountability and the emergence of high-value industrial applications beyond fertilizers. These forces are compelling producers to invest in purification technologies and explore new, non-agricultural value chains.
Advanced beneficiation methods are a key focus of process innovation. These techniques, including selective flotation and bio-leaching, are designed to remove heavy metal impurities like cadmium directly from the rock. Agricultural producers are adopting these higher-purity inputs to meet stringent food-grade standards. This technology is displacing older, less efficient purification processes that struggle to meet new regulatory thresholds.
The European Union's regulation limiting cadmium content in phosphatic fertilizers is a primary example of policy influencing global trade. This rule directly impacts market access and creates a clear price premium for rock sourced from low-cadmium deposits, such as those in Morocco or Russia. Producers with naturally high-cadmium ore must invest in costly beneficiation or risk being excluded from this key market.
A significant demand shift is occurring with the rise of the electric vehicle industry. The need for purified phosphoric acid as a precursor for lithium iron phosphate (LFP) battery cathodes is creating a new, non-agricultural buyer segment with distinct quality and purity requirements. This trend is most prominent in China, the global center for LFP battery manufacturing, altering traditional demand patterns.
Phosphate Rock Market Segmentation
The phosphate rock market exhibits diverse characteristics across its various segments, reflecting distinct geological origins, processing requirements, and end-use applications. Understanding these segment dynamics is crucial for producers to align their supply capabilities with evolving demand patterns and regulatory mandates across global agricultural and industrial sectors.
Product Type:
The phosphate rock market faces varying substitution pressures across its product types, with high-purity deposits offering significant advantages against alternatives or lower-grade materials. Producers prioritize specific rock types based on their P2O5 content and impurity levels to meet stringent market demands.
- Authigenic Phosphate:Formed through direct precipitation from seawater, these deposits are typically marine in origin and often contain higher P2O5 concentrations with fewer impurities. Demand concentrates in regions like North Africa, where these high-grade reserves are critical for premium fertilizer production for export markets.
- Biogenic Phosphate:Derived from the accumulation of organic remains, such as bones and shells, these deposits can vary widely in purity and composition. Brazil's agricultural sector drives significant demand for biogenic phosphates, supporting its vast crop cultivation needs.
- Residual Phosphate:These deposits result from the weathering of pre-existing phosphatic rocks, often leading to concentrated but sometimes impure material.
- Volcanic Phosphate:Associated with igneous activity, these deposits are less common commercially and often require specialized beneficiation processes.
Authigenic Phosphate retains volume leadership; Biogenic Phosphate holds the steepest expansion curve.
Application:
Application diversity drives distinct quality requirements and market values for phosphate rock, with each end-use demanding specific purity levels and processing characteristics. This differentiation impacts sourcing strategies and beneficiation investments for producers.
- Fertilizer Production:This remains the dominant application, consuming the vast majority of mined phosphate rock for manufacturing phosphoric acid and various phosphatic fertilizers. Global food security initiatives in India and China underpin sustained demand for this critical agricultural input.
- Animal Feed Supplements:Phosphate rock derivatives provide essential phosphorus for livestock nutrition, supporting animal growth and health. European regulations influence the quality standards for these supplements.
- Food Additives:Highly purified phosphoric acid and its salts serve as leavening agents, preservatives, and acidulants in the food and beverage industry.
- Industrial Chemicals:Purified phosphoric acid serves as a precursor for a wide range of industrial chemicals, including those used in detergents, metal treatment, and, increasingly, high-purity applications like lithium iron phosphate (LFP) batteries. This segment is experiencing significant growth due to the electric vehicle market.
- Water Treatment:Phosphate compounds are utilized in municipal and industrial water treatment to control corrosion and sequester heavy metals.
Fertilizer Production commands the largest market share, while Industrial Chemicals are expanding most quickly.
Mining Method:
The choice of mining method directly influences operational costs, environmental impact, and the economic viability of phosphate rock deposits. Geopolitical factors and local geological conditions heavily dictate the predominant extraction techniques in different regions.
- Open-pit Mining:This method is prevalent for large, shallow, and extensive phosphate deposits, allowing for high-volume extraction at relatively lower costs. Its widespread use in North America reflects the geological formation of key deposits.
- Underground Mining:Employed for deeper or more complex ore bodies, this method involves higher capital expenditure and operational complexities.
- Solution Mining:A less common method where chemical solutions are injected to dissolve and extract soluble phosphate minerals.
- Dredging:Used for extracting phosphate from underwater deposits, such as marine or lake beds, requiring specialized equipment and environmental considerations. This method is gaining traction in coastal regions with accessible marine resources.
Open-pit Mining remains the most widespread approach, while Dredging is seeing increased investment for specific resource types.
End User Industry:
End user industries dictate specific quality parameters and volume requirements for phosphate rock, influencing supply chain configurations and product specifications. This segmentation highlights the diverse commercial pathways for phosphate rock derivatives.
- Chemical Manufacturing:This industry segment consumes significant volumes of phosphate rock for conversion into phosphoric acid, a fundamental precursor for various downstream chemical products. Major chemical companies drive demand for consistent, high-purity feedstock.
- Agriculture Cooperatives:These organizations aggregate demand from numerous farmers, procuring phosphate fertilizers and related products for widespread agricultural use. Their purchasing power influences pricing and distribution channels across agricultural economies.
- Livestock Producers:Directly purchase phosphate-based feed supplements to enhance animal nutrition and productivity in the meat and dairy sectors.
- Environmental Services:Utilize phosphate compounds in wastewater treatment, soil remediation, and other environmental management applications.
Chemical Manufacturing represents the largest consumer segment, with Environmental Services showing consistent growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock supply heavily concentrates in specific geological formations globally. Key nations with significant reserves and processing capabilities dictate trade flows and market dynamics. This concentration influences pricing and availability for importing agricultural economies worldwide.
Morocco
Morocco maintains a dominant position, supplying premium, low-cadmium phosphate for global fertilizer markets. European Union regulations on cadmium levels directly influence the demand for Moroccan rock. The Safi region hosts extensive mining and processing operations, supporting OCP Group's significant global supply chain.
United States
The United States drives substantial demand for integrated fertilizer manufacturing and domestic agricultural applications. US EPA regulations on mining waste and water management impose significant compliance costs. Florida's Bone Valley region remains a primary hub for phosphate mining and processing, serving North American agricultural demand.
China
China's agricultural self-sufficiency policies and the expansion of LFP battery manufacturing fuel phosphate rock consumption. China's MEE imposes stringent rules on mining waste and water management. Yunnan province represents a key phosphate production area, supporting both fertilizer and industrial chemical sectors.
India
India's national food security initiatives and vast crop cultivation needs underpin consistent demand for phosphate fertilizers. Government subsidies directly support domestic fertilizer production and consumption. Rajasthan and Madhya Pradesh are significant regions for indigenous phosphate rock mining, crucial for national agricultural input requirements.
Brazil
Brazil's expansive agricultural sector requires substantial phosphate inputs to maintain high crop yields. ANVISA oversees agricultural input quality standards for domestic use. The Minas Gerais state features prominent phosphate mining operations, supplying inputs for the nation's extensive agricultural sector.
Phosphate Rock Market Key Industry Players
Concentration sits with vertically integrated mining and fertilizer producers, who control significant portions of the raw material supply chain. The market exhibits a tiered structure, distinguishing between large-scale, global suppliers and more regionally focused players. Strategic archetypes include state-backed enterprises, diversified agricultural input companies, and specialized industrial chemical manufacturers. Key competitive moves involve substantial capital investment in capacity expansion for low-cadmium reserves and the formation of strategic partnerships for purification technology adoption.
Within the global integrated producer archetype, OCP Group represents a significant player, leveraging its extensive Moroccan reserves for premium fertilizer production. The Mosaic Company, a prominent North American entity, exemplifies a major producer focusing on integrated fertilizer manufacturing across its expansive operations. PhosAgro, a Russian-based company, occupies a strong market position through large-scale operations and logistical advantages in supplying both European and Asian markets. These entities collectively anchor the market's supply dynamics, influencing global trade flows and setting quality standards for phosphatic products.
| Leading Market Players |
|---|
| PhosAgro |
| Itafos |
| The Mosaic Company |
| Hubei Xingfa Chemicals |
| Jordan Phosphate Mines Company |
| Nutrien Ltd |
| Ma'aden |
| Guizhou Kailin Holdings (Group) Co., Ltd. |
| OCP Group |
| Others |
Cost & Logistics Intelligence
European Union's cadmium regulations gate both supply qualification and price differentiation across the phosphate rock market.
Pricing Analysis
European Union's cadmium limits dictate the pricing tier structure for phosphate rock, creating a premium for low-cadmium material. The market operates on a hybrid model of commodity spot pricing for standard grades and long-term contract-based offtake for high-purity products. Price differentiation stems from P2O5 content and cadmium levels, alongside geographic delivery costs. Agricultural cooperatives purchasing standard fertilizers exhibit high price sensitivity, contrasting with the lower sensitivity of LFP battery manufacturers for purified phosphoric acid.
Supply Chain Analysis
The limited number of high-grade, low-contaminant reserves in North Africa underwrites the global phosphate rock supply chain. Supply concentrates heavily in Morocco, the United States, and China, drawing from high-grade phosphate ore and sulphuric acid for processing. This concentration creates geopolitical supply risk for importing nations. Vertically integrated producers like OCP Group and The Mosaic Company manage distribution through direct sales and regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phosphate rock market represents a defensive moat story, underpinned by significant regulatory entrenchment around environmental and purity standards.
For Market Incumbents: Compound market leadership by investing in advanced beneficiation technologies to meet evolving purity standards for industrial applications. Secure long-term offtake agreements with LFP battery manufacturers to diversify beyond fertilizer demand. This strategy mitigates the threat from increasingly stringent environmental regulations. OCP Group can leverage its low-cadmium reserves to achieve greater upstream control of purified phosphoric acid production.
For New Entrants and Emerging Players: Anchor in niche segments demanding specialized phosphate derivatives, focusing on regions with less established supply chains. Target circular economy integration by developing technologies for phosphorus recovery from waste streams. Sub-Saharan Africa's under-fertilized agricultural land represents a penetrable geography. Offer sustainable, locally sourced phosphate solutions to gain market entry.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier phosphate producers requiring capital for environmental compliance upgrades and beneficiation technology. The market offers long-term viability due to its essential role in global food security and the energy transition. Target regional producers with viable reserves but underinvested processing capabilities. Watch for increased M&A activity focused on securing access to low-cadmium deposits.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Beneficiation | This enhances the purity of phosphate rock, allowing producers to meet stringent EU cadmium regulations for premium agricultural markets. |
| Secure LFP Battery Offtake Agreements | Diversifying sales channels to lithium iron phosphate battery manufacturers reduces reliance on traditional fertilizer demand fluctuations. |
| Expand African Agricultural Initiatives | Targeting under-fertilized land in Sub-Saharan Africa establishes new, long-term demand centers for phosphate fertilizers. |
| Develop Phosphorus Recovery Technologies | Integrating circular economy principles creates sustainable supply sources and mitigates environmental impact from waste streams. |
| Acquire Low-Cadmium Reserves | Consolidating access to naturally low-cadmium deposits, such as those in Morocco, ensures compliance and market access. |
Research Approach
A spread of perspectives from mining executives, fertilizer manufacturers, agricultural economists, and LFP battery researchers converged on the working assumptions for this phosphate rock market analysis. Primary interviews with industry stakeholders were validated against extensive secondary research. Secondary sources included customs data, company annual reports, FAO agricultural statistics, and environmental agency reports. This approach employed both bottom-up market sizing and top-down validation.
Product type, application, mining method, end-user industry, and regional production hubs formed the segmentation dimensions modeled across the analysis window. Compound annual growth rates were derived through regression analysis on historical data and projected based on identified growth catalysts. Key forecast inputs included evolving P2O5 content requirements and global lithium iron phosphate battery production forecasts.
Decision-makers should treat outputs as directional under current regulatory stability and agricultural demand assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding geopolitical stability in major producing regions and sustained agricultural output. Practitioners should keep alternative scenarios live as global trade policies and LFP battery demand evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Coal Tar Pitch Market