
 General Industrial Oils Market | 2026-2036
General Industrial Oils Market Size, Share, and Industry Trends Forecast 2026-2036
General Industrial Oils Market Foresight
Bulk-to-tote packaging downsizing is shifting procurement patterns among mid-sized manufacturing plants. Exxon Mobil Corporation leverages its integrated base oil supply chain to sustain drum-and-tote flexibility across North American distribution. Shell plc anchors large-volume contracts with energy producers through dedicated bulk logistics networks. Fuchs Petrolub differentiates in metalworking fluids by controlling specialized additive blending capacity in European manufacturing hubs.
General industrial oils comprise refined mineral, synthetic, and bio-based base stocks formulated with performance additives to reduce friction, transfer heat, and prevent corrosion in mechanical systems. Viscosity grades typically span ISO VG 32 to 680, with oxidation stability and demulsibility determining service intervals in demanding environments. Hydraulic oil and compressor oil categories lead volume contribution due to universal deployment across stationary and mobile equipment fleets. Metalworking fluids represent the fastest-growing application segment as precision machining intensifies in automotive and aerospace component manufacturing. Rust prevention and sealing formulations command premium positioning where equipment downtime costs exceed lubricant expenditures by orders of magnitude.
EPA lubricant standards in the United States and REACH registration requirements in Europe are elevating formulation costs for conventional mineral oil products while accelerating qualified demand for synthetic and bio-based alternatives. China's SAMR enforces GB standards for industrial lubricant performance labeling that restrict market access for uncertified imports. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional blending assets offer superior compliance economics.
Market Dynamics
Factory automation intensification across East Asian manufacturing clusters is compressing service intervals and elevating specification requirements for hydraulic and heat transfer fluids. This structural force is reconfiguring procurement volumes and formulation priorities among industrial lubricant suppliers.
Growth Catalysts
- GB Standards Enforcement:China's SAMR certification mandates for industrial lubricant performance labeling restrict uncertified imports, creating qualified demand corridors for certified synthetic formulations in Shanghai and Pearl River Delta machinery clusters.
- Precision Machining Intensification:Automotive and aerospace component manufacturers are expanding metalworking fluid consumption as tolerances tighten and cutting speeds accelerate in high-volume production environments.
- Preventive Maintenance Programs:Manufacturing plants in India are formalizing scheduled lubricant analysis and replacement protocols, expanding addressable volume for condition-monitoring-compatible hydraulic oils.
Market Restraints
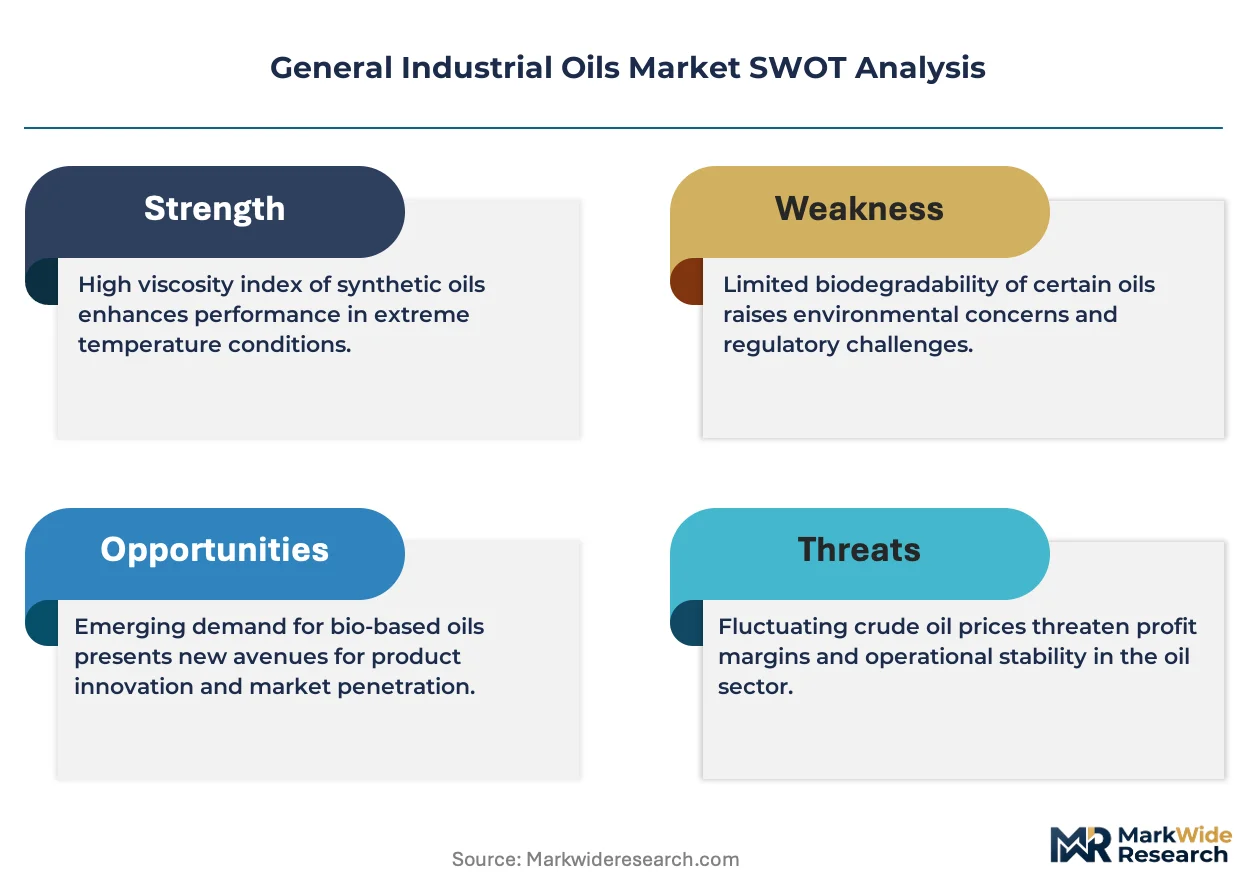
- Base Oil Supply Concentration:API Group II/III base stock production concentrates in Gulf Coast and Singapore refining complexes, exposing formulators to geographic concentration risk and freight cost volatility.
- REACH Registration Burden:ECHA requirements for novel additive chemistry elevate formulation costs and extend commercialization timelines for European-blended mineral oil products.
- Extended Drain Interval Technology:Synthetic lubricant durability advances compress total addressable volume by reducing replacement frequency in stationary equipment fleets.
Strategic Opportunities
- Bio-based Formulation Platforms:EPA lubricant standards for biodegradability and toxicity create qualified demand corridors for vegetable-derived base stocks in environmentally sensitive applications.
- Heat Transfer Fluid Expansion:Concentrated solar power and data center thermal management installations in India and China represent underpenetrated demand for specialized thermal stability formulations.
- Digital Fluid Monitoring Integration:IoT sensor deployment in German and Japanese manufacturing facilities enables predictive lubricant replenishment services as a recurring revenue model.
Industry Challenges
- Additive Chemist Scarcity:Formulation expertise in oxidation inhibitor and anti-wear chemistry concentrates among retiring specialists, constraining R&D throughput for next-generation products.
- Cross-Jurisdictional Compliance:Divergent EPA, REACH, and GB standard requirements force decisions between centralized formulation platforms and regional blending asset duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Industrial Oils Market |
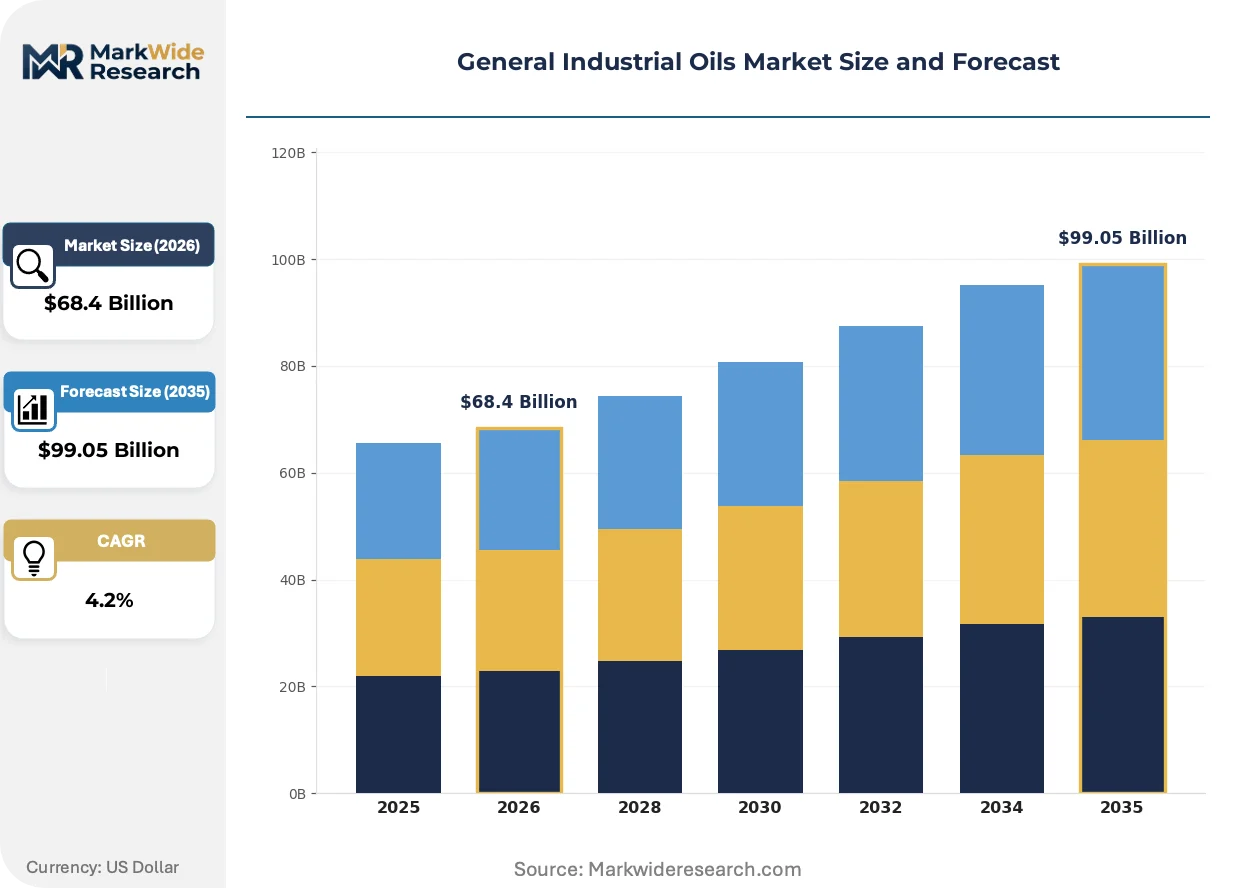
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $99.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricating Oil, Hydraulic Oil, Heat Transfer Oil, Compressor Oil, Turbine Oil, Quenching Oil Application: Machinery Lubrication, Metalworking Fluids, Power Transmission, Cooling Systems, Rust Prevention, Sealing End User: Manufacturing Plants, Mining Equipments, Construction Units, Energy Producers, Textile Operations, Chemical Facilities Packaging Type: Drums, Tins, Bulk Containers, Cans, Pails, Carboys |
| Companies Covered | Exxon Mobil Corporation, Shell plc, Chevron Corporation, BP p.l.c., TotalEnergies SE, China Petrochemical Corporation, Castrol Limited, Fuchs Petrolub, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Industrial Oils Market Shifts & Advancements
Synthetic base stock technology and digital distribution platforms are compressing traditional supply chain configurations while elevating performance specifications across industrial end-uses.
Polyalkylene glycol (PAG) synthetic lubricants are electrifying thermal management applications by delivering superior oxidative stability and water solubility compared to mineral alternatives. Data center operators and concentrated solar power developers in India and China are specifying PAG-based heat transfer fluids for 8,000+ hour service intervals. This chemistry shift is electrifying demand for specialized blending capacity and technical service support in high-growth industrial corridors.
REACH registration requirements under ECHA jurisdiction are elevating formulation transparency and substance safety documentation burdens for industrial lubricant suppliers. The regulation forces reformulation of conventional anti-wear additives containing zinc dialkyldithiophosphate complexes and accelerates substitution with ashless alternatives. European metalworking fluid manufacturers are responding by consolidating additive supplier relationships and pre-registering novel chemistry through SIEF consortia.
Direct procurement relationships between manufacturing plants and regional blenders are displacing traditional distributor intermediaries in mid-volume hydraulic oil segments. Automotive component suppliers in Germany and precision machinery builders in Japan are negotiating annual volume contracts with dedicated technical service support. This channel restructuring concentrates purchasing power among qualified regional formulators with ISO-certified blending assets and same-day delivery capabilities.
General Industrial Oils Market Segmentation
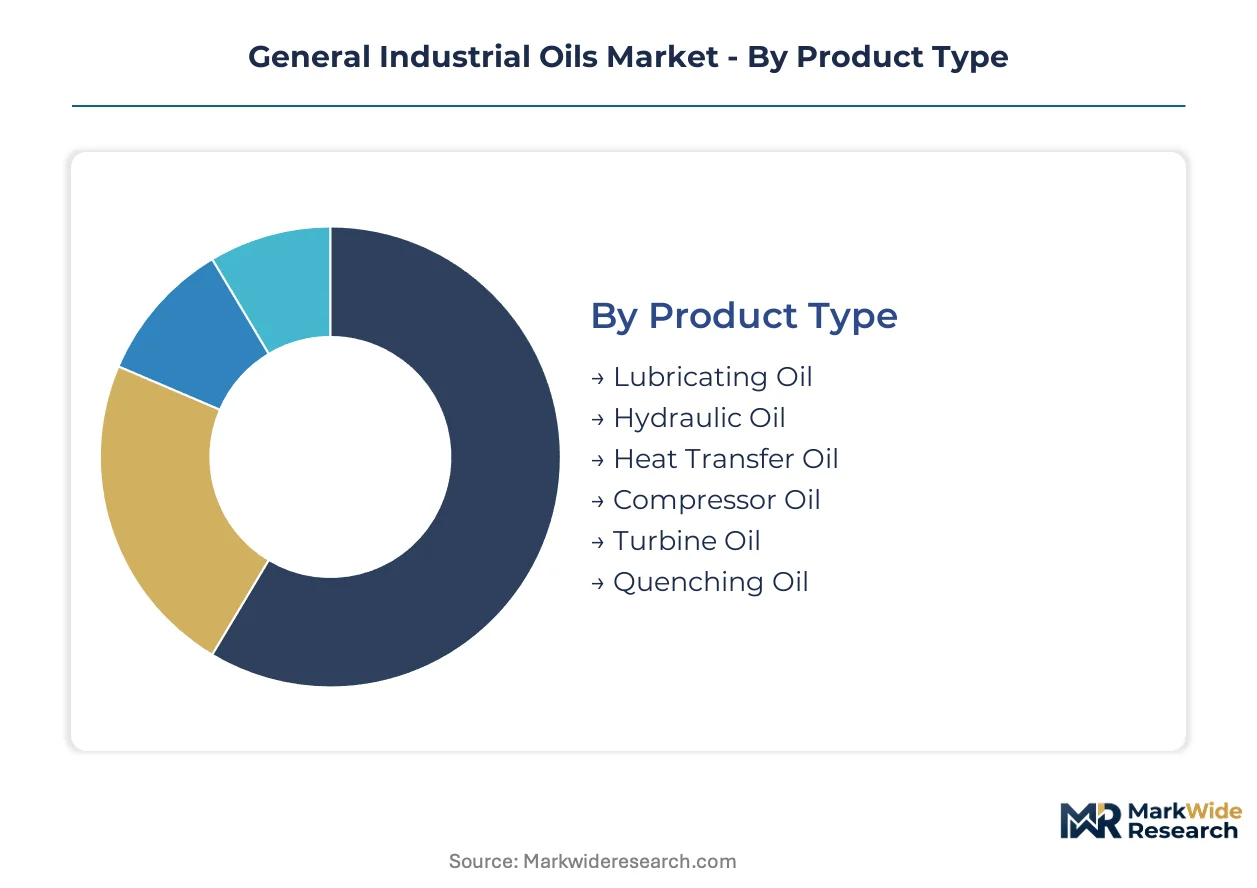
Segmentation in general industrial oils reveals distinct capital requirements, formulation complexity, and service intensity across product categories. Procurement patterns diverge sharply between high-volume hydraulic contracts and specialized metalworking formulations requiring technical support.
Product Type:
Capital intensity varies dramatically across product categories, with synthetic base stock production demanding multi-million dollar hydrogenation units while mineral oil blending requires modest tank farm investments.
- Hydraulic Oil:Formulated from Group II/III base stocks with anti-wear zinc additives and demulsibility packages for high-pressure fluid power systems. Demand concentrates in Shanghai and Pearl River Delta manufacturing clusters where factory automation intensifies preventive maintenance protocols. SAMR GB standards enforcement restricts uncertified imports, elevating certified synthetic formulations.
- Heat Transfer Oil:Synthetic aromatic or paraffinic fluids engineered for thermal stability across -40°C to 400°C operating ranges. Concentrated solar power installations in India and data center thermal management in China specify these formulations for extended service intervals exceeding 8,000 hours.
- Lubricating Oil:General-purpose mineral and synthetic blends for bearing and gear protection across ISO VG 32-680 viscosity grades.
- Compressor Oil:Oxidation-inhibited formulations for rotary screw and reciprocating air compression systems with varnish control additives.
- Turbine Oil:Refined base stocks with rust inhibitors and demulsifiers for steam and gas turbine lubrication in power generation.
- Quenching Oil:Specialized heat treatment fluids with controlled cooling rates for metallurgical hardening processes in automotive component manufacturing.
Most installed capacity flows through Hydraulic Oil. Expansion is steepest in Heat Transfer Oil.
Application:
Application segmentation tracks the divergence between commodity volume plays and premium-margin technical services, with metalworking fluids commanding formulation expertise premiums.
- Metalworking Fluids:Water-soluble emulsions and neat oils for cutting, grinding, and forming operations with biocide packages for sump life extension. Automotive and aerospace component manufacturers in Germany and Japan specify these as tolerances tighten and cutting speeds accelerate.
- Power Transmission:Insulating and lubricating formulations for electrical transformers and switchgear with dielectric strength requirements.
- Machinery Lubrication:General bearing and gear oils for stationary industrial equipment across manufacturing sectors.
- Cooling Systems:Heat transfer formulations for industrial process temperature control and thermal management applications.
- Rust Prevention:Protective coatings and dewatering fluids for interim corrosion protection of machined components and stored equipment.
- Sealing:Viscous lubricant formulations that simultaneously seal against dust ingress and reduce friction in mechanical assemblies.
Volume concentrates in Machinery Lubrication. Margin expansion is strongest in Metalworking Fluids.
End User:
End user segmentation exposes divergent procurement sophistication, with energy producers negotiating long-term bulk contracts while textile operations purchase through distributor intermediaries.
- Manufacturing Plants:Integrated hydraulic, compressor, and metalworking fluid demand from automotive, aerospace, and precision machinery producers with formal preventive maintenance programs.
- Energy Producers:Turbine oil and transformer fluid procurement by thermal, renewable, and grid operators with multi-year technical service agreements.
- Mining Equipments:Heavy-duty hydraulic and lubricating oil consumption for open-pit and underground extraction machinery operating in abrasive environments.
- Construction Units:Mobile equipment lubrication for earthmoving, lifting, and compaction machinery with seasonal demand patterns.
- Textile Operations:Spindle oils and heat transfer fluids for synthetic fiber production and fabric finishing processes.
- Chemical Facilities:Specialized lubricants for pumps, compressors, and reactors handling corrosive process streams.
Contract value peaks with Energy Producers. Procurement formalization is advancing fastest in Manufacturing Plants.
Packaging Type:
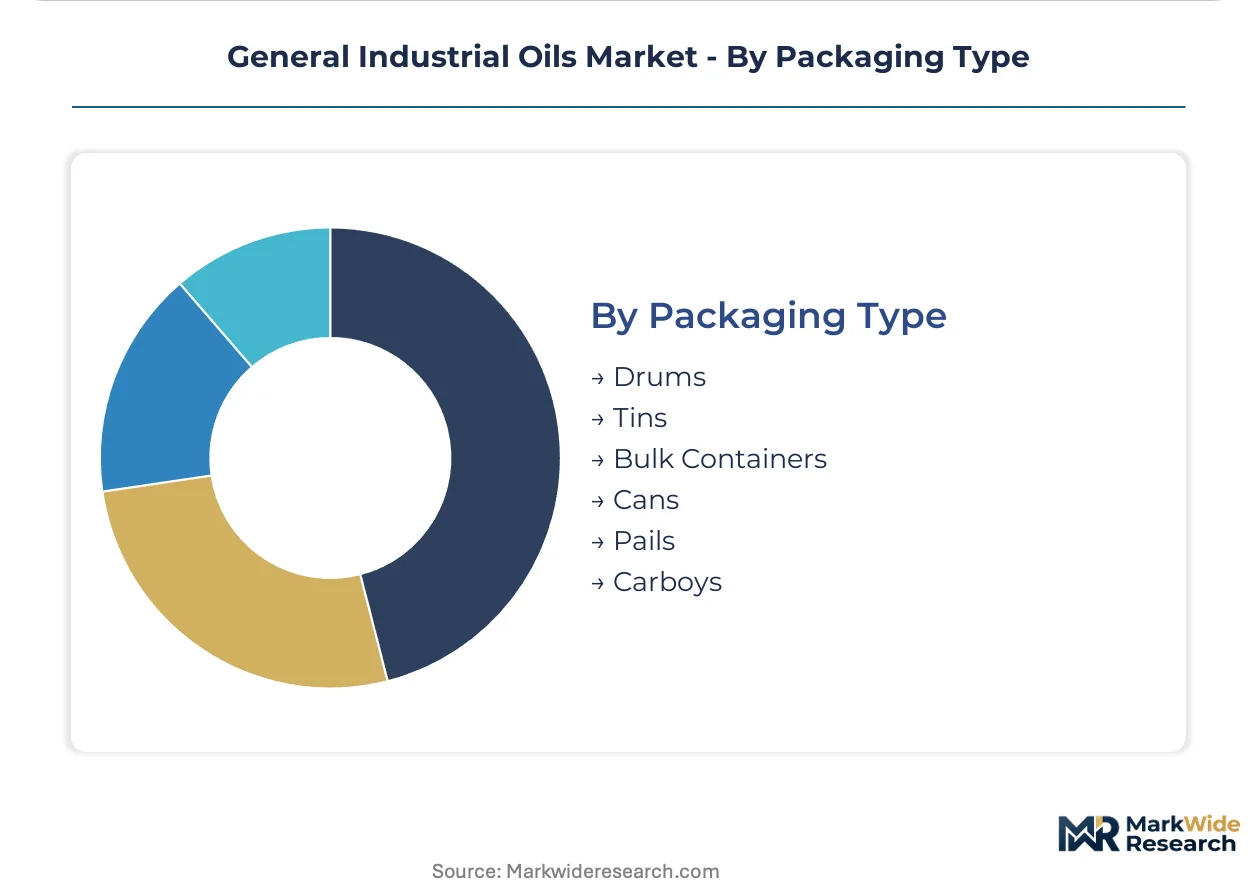
Packaging segmentation reflects supply chain configuration trade-offs between bulk delivery economics and inventory flexibility for mid-volume consumers.
- Bulk Containers:Tank truck and railcar deliveries to dedicated storage tanks at high-volume manufacturing and energy production sites with ISO-certified receiving infrastructure.
- Drums:55-gallon steel containers for mid-volume hydraulic and lubricating oil procurement with established handling equipment compatibility.
- Tins:Small metal containers for specialty formulations and sample quantities in metalworking fluid trials.
- Cans:Retail-scale packaging for maintenance departments and small equipment fleets with limited storage space.
- Pails:Five-gallon plastic containers for moderate-volume consumers transitioning between drum and bulk delivery thresholds.
- Carboys:Glass or plastic demijohns for laboratory-scale and precision application requirements in chemical and pharmaceutical manufacturing.
Volume flows predominantly through Bulk Containers. Drum-to-tote downsizing is shifting procurement patterns among mid-sized plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial lubricant formulation originated in the German Rhineland and Pennsylvania oilfields during the late nineteenth century, establishing the technical foundations that now govern global specification standards. Contemporary demand concentrates in manufacturing corridors where machinery density and regulatory enforcement have tightened in parallel.
United States
EPA lubricant standards for biodegradability and toxicity are elevating formulation costs for conventional mineral oil products. Gulf Coast refining complexes concentrate API Group II/III base stock production, exposing formulators to geographic concentration risk. Houston and Corpus Christi anchor hydrogenation capacity for synthetic base stock manufacturing.
China
SAMR enforces GB standards for industrial lubricant performance labeling that restrict market access for uncertified imports. Factory automation intensification across East Asian manufacturing clusters compresses service intervals for hydraulic fluids. Shanghai and Pearl River Delta machinery clusters specify certified synthetic formulations for preventive maintenance protocols.
Germany
ECHA REACH registration requirements elevate formulation transparency burdens for anti-wear additive chemistry. Metalworking fluid manufacturers consolidate additive supplier relationships through SIEF consortia. Stuttgart and Munich precision machinery builders negotiate direct procurement contracts with ISO-certified regional blenders.
India
Manufacturing plants formalize scheduled lubricant analysis and replacement protocols, expanding volume for condition-monitoring-compatible hydraulic oils. Concentrated solar power installations in Rajasthan and data center thermal management in Maharashtra specify PAG-based heat transfer fluids for extended service intervals.
Japan
METI industrial standards govern synthetic lubricant performance specifications for precision machinery applications. IoT sensor deployment in manufacturing facilities enables predictive lubricant replenishment services. Nagoya and Osaka automotive component suppliers demand technical service support from qualified regional formulators.
General Industrial Oils Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and technical service intensity, creating a tiered competitive structure. The vendor base spans integrated petroleum majors, specialized additive blenders, and regional formulators with ISO-certified assets. Three archetypes dominate: upstream-integrated suppliers with captive base oil supply, technical specialists controlling niche additive chemistry, and regional blenders with same-day delivery capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing dedicated logistics networks or pre-registering novel chemistry through regulatory consortia.
Within the integrated petroleum major tier, Exxon Mobil Corporation and Shell plc exemplify scale-driven positioning through drum-and-tote distribution flexibility and bulk logistics networks respectively. Fuchs Petrolub occupies a specialist position, representing the technical-formulation archetype through controlled additive blending capacity in European manufacturing hubs. These three entities anchor the competitive spectrum from commodity volume to premium-margin technical services.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP p.l.c. |
| TotalEnergies SE |
| China Petrochemical Corporation |
| Castrol Limited |
| Fuchs Petrolub |
| Phillips 66 |
| Others |
Supply & Pricing Matrix
GB standards enforcement by SAMR is compressing procurement options for uncertified mineral oil imports, forcing formulators to absorb certification costs or surrender volume to certified synthetic suppliers. This specification tightening elevates entry thresholds while fragmenting price competition across compliance tiers.
Pricing Analysis
Three-tier pricing structure across premium synthetic, certified mineral, and uncertified economy levels stratifies the market. Price differentiation hinges on REACH registration status and ISO-certified blending asset access, with German and Japanese buyers paying premiums for technical service bundling. Cost compression in economy mineral tiers is intensifying because Gulf Coast base oil concentration exposes blenders to freight volatility. Distributor-dependent textile operations exhibit highest price sensitivity, while energy producers negotiating multi-year turbine oil contracts demonstrate lowest.
Supply Chain Analysis
ISO certification and REACH pre-registration through SIEF consortia gate supply access for European metalworking fluid manufacturers. API Group II/III base stock production concentrates in United States Gulf Coast and Singapore refining complexes. Formulation draws from hydrogenated mineral feedstocks, zinc dialkyldithiophosphate anti-wear packages, and PAG synthetic chemistries. Single-source vulnerability concentrates in Singapore hydrogenation capacity. Distribution runs through dedicated bulk logistics networks for energy producers and drum-and-tote flexibility for mid-volume manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as precision machining tolerances tighten and preventive maintenance programs formalize across East Asian manufacturing clusters. Premium synthetic formulations are displacing commodity mineral volumes in contract negotiations.
For Market Incumbents: Anticipate additive chemist scarcity constraining R&D throughput by consolidating supplier relationships through SIEF consortia for REACH compliance. Defend position by securing dedicated bulk logistics networks around Shanghai and Pearl River Delta machinery clusters. Backward integration into API Group III base stock production anchors margin control against Gulf Coast concentration risk. For New Entrants and Emerging Players: Launch via direct procurement relationships with mid-sized automotive component suppliers in Germany seeking ISO-certified regional blenders with same-day delivery capabilities. Target heat transfer fluid demand from concentrated solar power installations in Rajasthan and data center thermal management in Maharashtra. White-space penetration runs through PAG-based synthetic formulations for 8,000+ hour service intervals. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulators controlling specialized additive blending capacity in European manufacturing hubs. Five-to-ten year viability favors technical specialists over commodity volume players as specification requirements intensify. Monitor IoT sensor deployment rates in Japanese manufacturing facilities as predictive replenishment service adoption signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Captive API Group III supply secures margin control against Singapore and Gulf Coast concentration risk. |
| REACH Pre-Registration through SIEF Consortia | Novel additive chemistry commercialization timelines compress for European-blended metalworking fluid manufacturers. |
| Digital Fluid Monitoring Integration | IoT sensor deployment in German and Japanese facilities enables predictive replenishment recurring revenue models. |
| Regional Blending Asset Expansion | ISO-certified capacity in Shanghai and Pearl River Delta clusters captures SAMR GB standards enforcement volume. |
| Bio-Based Formulation Platform Development | EPA biodegradability standards create qualified demand corridors for vegetable-derived base stocks in sensitive applications. |
Research Methodology
Direct dialogue with plant maintenance directors, procurement leads at automotive OEMs, lubricant distribution channel partners, and technical R&D directors at additive suppliers grounded qualitative findings. Secondary validation drew from ECHA REACH registration databases, SAMR GB standards filings, SEC 10-K disclosures from integrated petroleum majors, and customs trade data for base stock flows. Bottom-up volume estimates triangulated against top-down industrial machinery installation projections.
Bottom-up modeling segmented demand across hydraulic oil, heat transfer fluid, metalworking fluid, and compressor oil categories by viscosity grade, base stock type, and end-use intensity. Top-down validation referenced manufacturing machinery density indices and preventive maintenance program penetration rates across the analysis window. CAGRs derived from regression against industrial production indices and specification upgrade cycle assumptions.
Several conditions sit outside the modeled scope, including sudden base oil price shocks from refinery outages, accelerated synthetic substitution curves from unanticipated durability breakthroughs, and trade policy shifts affecting Singapore hydrogenation capacity access. A model refresh is warranted upon material change in SAMR enforcement intensity for GB standards certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
High Pressure Roll Compactor Market