
 Honing Oil Market | 2026-2036
Honing Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Honing Oil Market Intelligence
Market Context with Strategic Players
Distributor networks for honing oil is fragmenting as regional specialty lubricant suppliers and direct-to-factory digital platforms erode the traditional two-step wholesale model. Sunnen Products Company leverages its captive equipment-oil bundling to lock in precision-machining accounts across North America. Houghton International anchors global supply through its metalworking fluid heritage and technical service density in major manufacturing clusters. Eurol BV differentiates via synthetic formulations that meet tightening European chemical standards without sacrificing cutting performance.
Technical Definition and Structural Segments
Honing oil is a low-viscosity metalworking fluid engineered with extreme-pressure additives and lubricity agents to cool abrasive stones, flush swarf, and achieve sub-micron surface finishes during bore-sizing operations. Its formulation balances oiliness, detergency, and oxidation stability to prevent glazing of honing stones and dimensional drift in precision cylinders. Synthetic oil commands the fastest expansion as aerospace OEMs and Tier-1 suppliers mandate chlorine-free, low-mist chemistries for worker safety and environmental compliance. Biodegradable oil remains niche but gathers share in European job shops facing REACH registration burdens and discharge-limit enforcement. Mineral oil still dominates volume in cost-sensitive automotive powertrain honing where process approval cycles slow substitution.
Regulatory Frame and Forward-Looking Close
REACH in Europe, EPA reporting requirements in the United States, and Japan's METI chemical management framework collectively raise the compliance threshold for base-stock selection and additive packages in metalworking fluids. These regimes pressure formulators to document substance volumes, restrict chlorinated paraffins, and label products for safe handling in factory environments. Stakeholders must monitor how evolving substance restrictions in Germany, California, and Japan reshape formulation economics and determine which suppliers can absorb re-registration costs without passing full burden to end users.
Market Dynamics
REACH re-registration deadlines and EPA substance reporting are compressing formulation approval cycles, forcing honing oil suppliers to absorb compliance costs or cede share to synthetic specialists with pre-certified portfolios.
Growth Catalysts
- Tightening bore tolerances in aerospace:Aerospace OEMs now demand sub-micron surface finishes for fuel-efficient engine architectures, expanding consumption of chlorine-free synthetic honing fluids.
- EU Green Deal chemical phase-outs:The EU Green Deal accelerates biodegradable base-stock adoption as job shops preempt REACH restrictions on mineral oil discharge.
- Direct digital distribution:Specialty lubricant platforms now connect formulators directly to precision machining shops, bypassing traditional wholesale markups and accelerating product trials.
Market Restraints
- Base-stock supply concentration:Synthetic ester and polyalphaolefin supply concentrates among a handful of European and US chemical producers, exposing formulators to input volatility.
- Process approval inertia:Automotive powertrain honing lines require 18-24 month validation cycles for fluid substitutions, locking in mineral oil despite superior synthetic performance.
- Chlorinated paraffin substitution costs:REACH and EPA restrictions on short-chain chlorinated paraffins force reformulation investments that smaller job shops defer, slowing segment-wide transition.
Strategic Opportunities
- Japanese precision component manufacturing:METI chemical management frameworks favor low-mist synthetic formulations, opening share for suppliers with JIS-certified portfolios.
- Combined coolant-honing fluid systems:Integration of honing oil with minimum-quantity lubrication (MQL) delivery systems reduces waste and commands premium positioning in German machining clusters.
- California Safer Consumer Products mandates:The state's chemical prioritization process creates early-mover advantage for formulators with pre-registered biodegradable alternatives.
Industry Challenges
- Fluid analysis technician scarcity:Precision machining shops lack in-house chemists to interpret used-oil analysis data, delaying predictive maintenance adoption and extending fluid change intervals beyond optimal.
- Cross-border formulation harmonization:Suppliers serving both EU and US markets must maintain parallel additive packages to satisfy divergent EPA and ECHA substance lists, complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honing Oil Market |
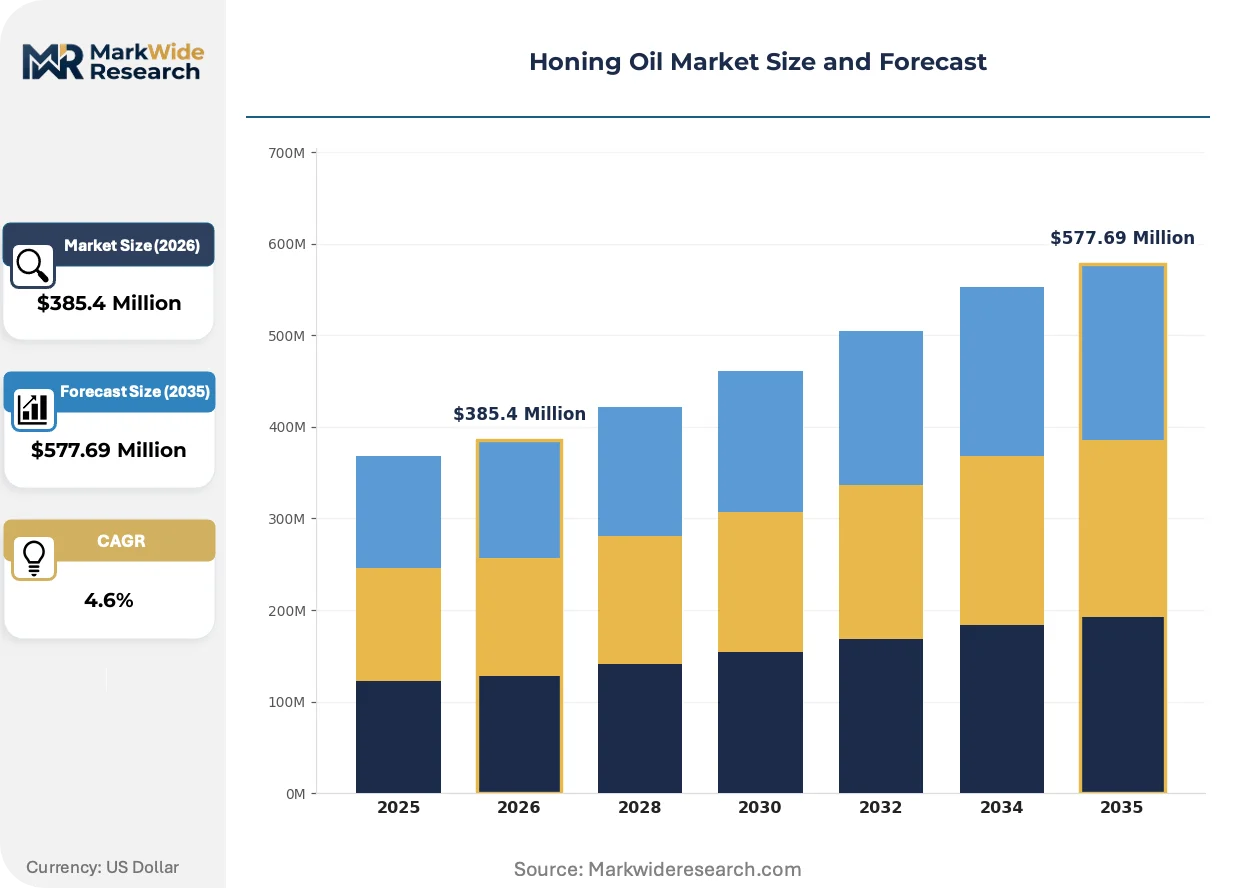
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $577.69 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Water-Soluble Oil, Biodegradable Oil Application: Metalworking, Aerospace, Automotive, Precision Machining End User: OEMs, Tier-1 Suppliers, Aftermarket Manufacturers, Job Shops Distribution Channel: Direct Sales, Online Retail, Distributor Networks, Resellers |
| Companies Covered | Growmark, Eurol BV, Sunnen Products Company, Houghton International, CC Jensen, Penrite Oil, Sunbelt Lubricants, Stahli USA, Lansky Sharpeners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honing Oil Market Strategic Shifts & Innovations
Formulation chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure and digital procurement reshape how precision machining shops source and consume metalworking fluids.
Synthetic ester-based honing oils with built-in extreme-pressure performance are rendering obsolete traditional mineral oil formulations dependent on chlorinated paraffin additives. Aerospace Tier-1 suppliers in Germany and Japan are adopting these chemistries ahead of regulatory deadlines to secure process approvals. The shift compresses margins for legacy mineral oil blenders while rewarding early synthetic specialists with multi-year supply agreements.
REACH substance volume reporting and the EU Green Deal's chemical restriction roadmap are forcing formulators to document additive packages down to 0.1% concentration thresholds. This regulatory burden favors larger suppliers with dedicated regulatory affairs teams capable of managing re-registration cycles. Smaller regional blenders in Italy and Spain are exiting the market or seeking white-label partnerships to avoid direct compliance costs.
Precision machining shops are consolidating fluid procurement through integrated supply contracts that bundle honing oil with filtration services and waste management. This vendor consolidation displaces spot purchasing through industrial distributors, particularly visible in US Midwest automotive supply chains. Shops now prioritize suppliers offering real-time inventory monitoring and automated replenishment over traditional price-per-gallon negotiations.
Honing Oil Market Segmentation
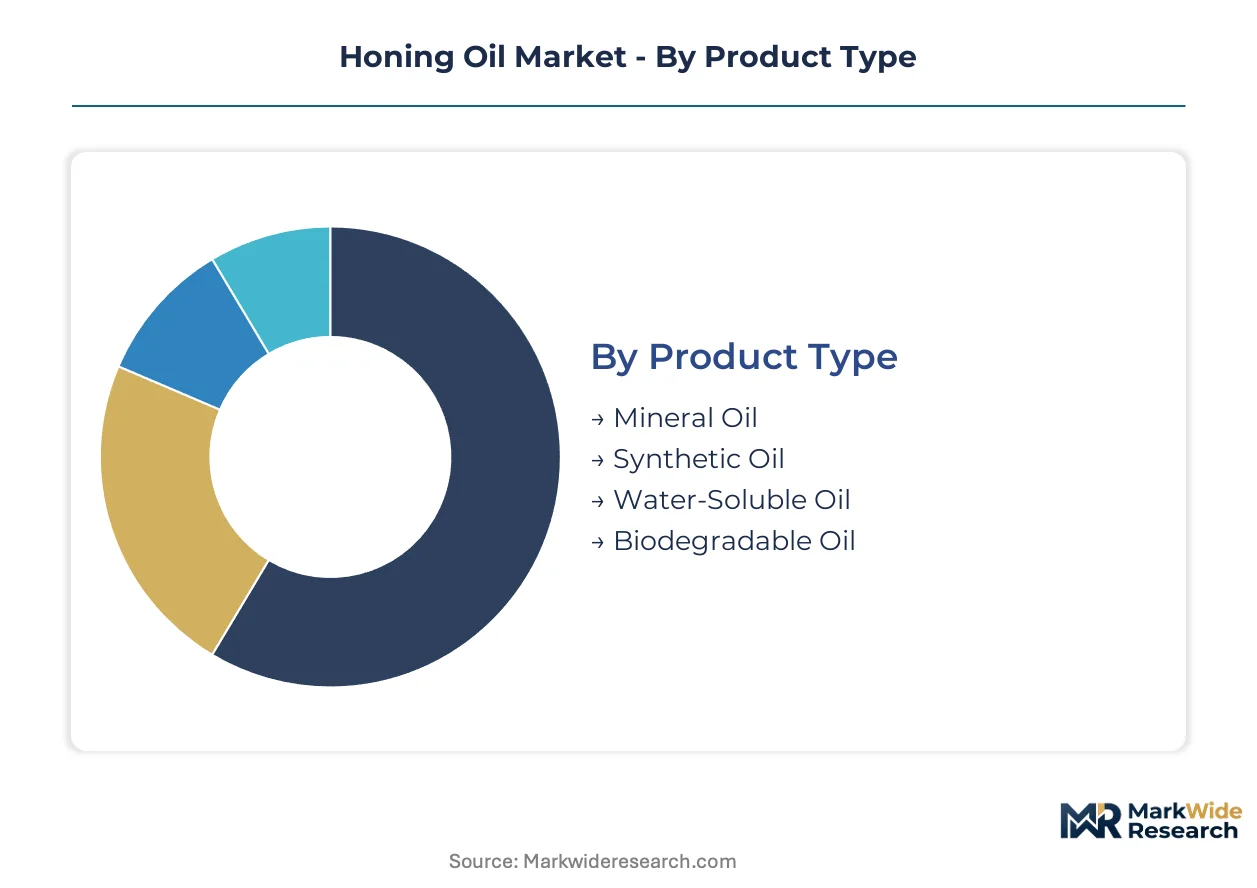
Honing oil segmentation reveals how formulation chemistry, end-use precision requirements, and procurement channels fragment addressable demand. Technical service intensity varies dramatically across these divides, reshaping supplier economics and customer retention strategies.
Product Type:
After-sales service intensity climbs with formulation complexity, as synthetic and biodegradable variants demand fluid analysis programs and re-certification support that mineral oil rarely requires.
- Synthetic Oil:Formulated from polyalphaolefin and ester base stocks with built-in extreme-pressure additives, eliminating chlorinated paraffins. Aerospace Tier-1 suppliers in Germany and Japan mandate these chemistries for sub-micron bore finishing, though 18-24 month process approvals slow adoption in automotive powertrain lines.
- Mineral Oil:Petroleum-derived formulations with conventional sulfur-phosphorus extreme-pressure packages dominate volume in cost-sensitive honing operations. REACH re-registration burdens and EPA substance reporting are compressing margins for legacy blenders without dedicated regulatory affairs teams.
- Biodegradable Oil:Vegetable-based esters with rapid aquatic biodegradability meet EU Green Deal discharge limits for European job shops facing enforcement.
- Water-Soluble Oil:Semi-synthetic emulsions dilute with water for high-volume flushing operations in large-diameter cylinder honing.
By volume, mineral oil leads. By growth pace, synthetic oil is climbing the fastest.
Application:
Cost tier stratification separates aerospace qualification-driven premiums from automotive scale economies, with precision machining occupying a contested middle ground.
- Aerospace:Fuel-efficient engine architectures demand sub-micron surface finishes on turbine discs and compressor cases. OEMs specify chlorine-free synthetic fluids with documented REACH compliance, locking in multi-year supply agreements with certified formulators.
- Automotive:Powertrain honing lines process millions of cylinder bores annually, favoring mineral oil formulations where process inertia and 18-24 month fluid substitution cycles resist premium synthetic migration despite superior stone life.
- Precision Machining:Independent job shops serving medical device and hydraulic component manufacturers value technical service density over per-gallon pricing, consolidating procurement around suppliers offering real-time inventory monitoring.
- Metalworking:General fabrication honing consumes standard-grade fluids through distributor spot purchasing, with limited supplier stickiness.
Aerospace commands the steepest expansion trajectory as surface-finish tolerances tighten. Automotive retains the largest absolute consumption base.
End User:
Customer type determines contract structure, with OEMs demanding integrated fluid-service bundles and job shops prioritizing flexibility.
- OEMs:Original equipment manufacturers in aerospace and automotive powertrain consolidate honing oil procurement with filtration services and waste management under multi-year integrated supply contracts. Real-time inventory monitoring and automated replenishment displace traditional price negotiations.
- Tier-1 Suppliers:Contract manufacturers serving Boeing, Airbus, and major automotive OEMs face downstream fluid specification mandates, accelerating synthetic adoption ahead of regulatory deadlines to secure process approvals.
- Job Shops:Small and mid-size precision machining operations in Italy and Spain lack in-house chemists to interpret used-oil analysis, delaying predictive maintenance adoption and extending fluid change intervals.
- Aftermarket Manufacturers:Independent cylinder reconditioning and repair operations purchase through industrial distributors with limited technical service attachment.
Tier-1 suppliers are gaining share fastest as outsourcing concentrates precision machining capacity. OEMs retain the most concentrated purchasing power.
Distribution Channel:
Supply concentration among synthetic base-stock producers is reshaping how formulators reach end users, with digital platforms eroding traditional two-step wholesale economics.
- Direct Sales:Specialty lubricant suppliers connect formulators directly to precision machining shops, bypassing wholesale markups and accelerating product trials through technical service teams embedded in German and US manufacturing clusters.
- Distributor Networks:Traditional two-step wholesale models fragment as regional specialty lubricant suppliers capture share, though automotive aftermarket channels retain relevance for high-volume mineral oil sales.
- Online Retail:Digital procurement platforms serve small job shops with standardized formulations, offering transparent pricing and rapid delivery for non-critical honing operations.
- Resellers:Independent agents white-label formulations for smaller regional blenders in Southern Europe exiting direct compliance with REACH substance volume reporting.
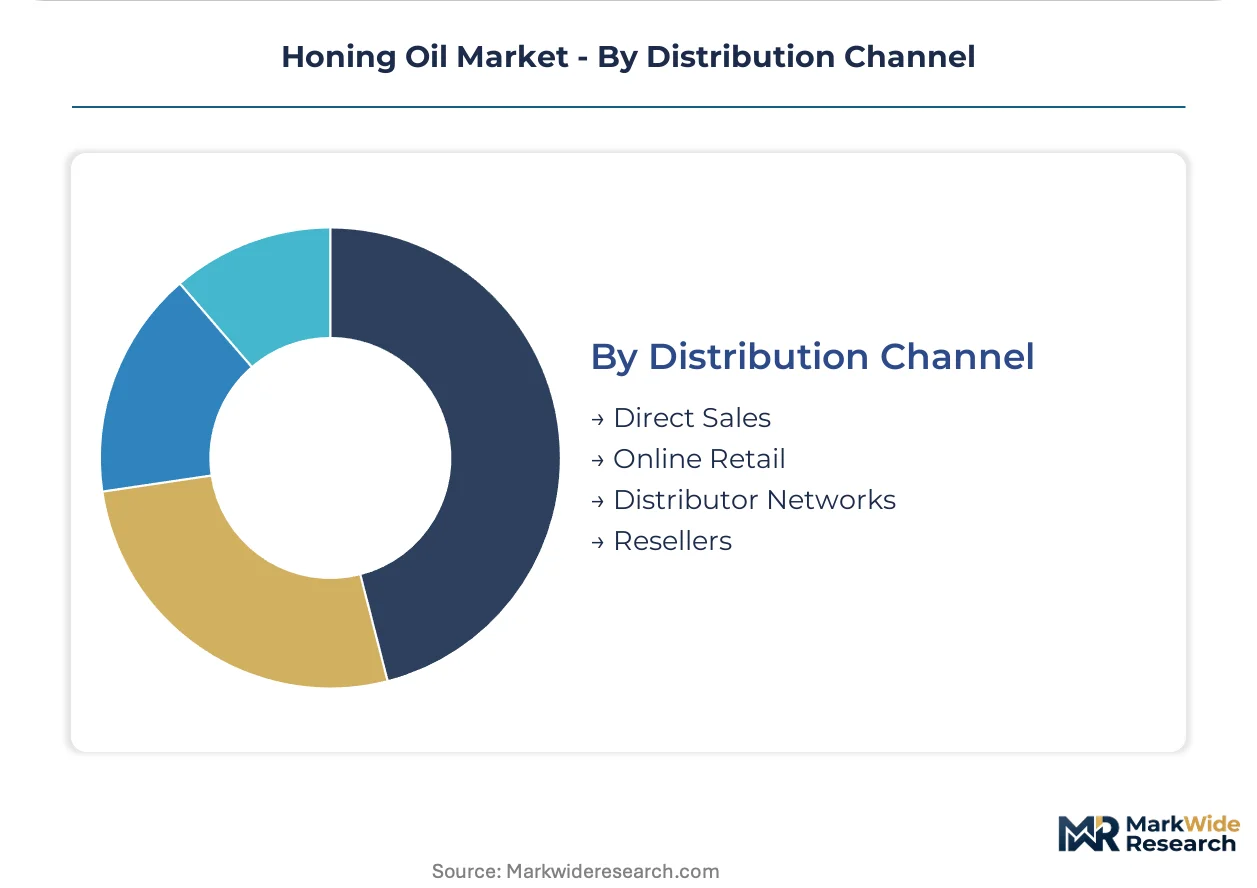
Direct sales channels are expanding most quickly as vendor consolidation displaces spot purchasing. Distributor networks still handle the largest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-machining clusters command premium pricing power for REACH-certified synthetic formulations, while US Midwest automotive powertrain operations extract volume discounts on mineral oil through consolidated procurement contracts.
United States
Aerospace OEMs in Connecticut and Washington State mandate chlorine-free synthetic honing fluids for turbine disc finishing, tightening surface-finish tolerances beyond mineral oil capabilities. EPA substance reporting under the Toxic Substances Control Act compresses formulation approval cycles for domestic blenders. The Detroit-Toledo corridor anchors automotive powertrain honing volume, where 18-24 month fluid validation cycles lock in mineral oil despite synthetic performance advantages.
Germany
Machine tool builders in Stuttgart and Munich specify integrated coolant-honing fluid systems for export equipment, bundling synthetic formulations with minimum-quantity lubrication delivery hardware. REACH re-registration deadlines force additive package documentation to 0.1% concentration thresholds, favoring formulators with dedicated regulatory affairs teams. The Ruhr Valley industrial cluster sees job shops consolidating procurement around suppliers offering real-time inventory monitoring and automated replenishment.
Japan
Precision component manufacturers in Aichi Prefecture adopt low-mist synthetic honing oils ahead of METI chemical management framework deadlines, securing JIS process certifications for aerospace Tier-1 supply chains. The Nagoya-Toyota industrial corridor concentrates captive honing operations at Toyota and its keiretsu suppliers, where equipment-oil bundling locks in long-term formulation agreements. Osaka-based independent job shops lack in-house chemists to interpret used-oil analysis, delaying predictive maintenance adoption.
China
Domestic machine tool builders in Shenyang and Dalian source standard-grade mineral honing oils through distributor networks for general fabrication, with limited technical service attachment. MIIT industrial upgrading programs accelerate synthetic adoption among state-owned aerospace enterprises in Xi'an and Chengdu, though process approval inertia slows substitution in automotive joint ventures. Yangtze River Delta precision machining clusters show early demand for combined coolant-honing fluid systems as foreign equipment OEMs establish local assembly.
India
Automotive component manufacturers in Pune and Chennai rely on imported synthetic formulations for export-facing powertrain honing lines, absorbing premium pricing to satisfy downstream OEM specifications. BIS standards for metalworking fluids remain less stringent than REACH or EPA frameworks, allowing regional mineral oil blenders to retain cost-sensitive job shop accounts. The Gujarat industrial corridor attracts honing oil distributors serving diesel engine remanufacturing operations with limited environmental enforcement.
Honing Oil Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in formulation supply. The honing oil market structures around three tiers: multinational lubricant houses with metalworking fluid heritage, regional synthetic specialists with regulatory pre-certification, and captive equipment manufacturers bundling oil with honing machinery. Consolidation pressures concentrate among mid-size blenders lacking dedicated regulatory affairs capacity. Dominant competitive moves include direct digital distribution bypassing wholesale markups and integrated supply contracts bundling fluid with filtration services.
Within the multinational lubricant tier, Houghton International anchors global supply through technical service density in major manufacturing clusters. Among equipment-integrated players, Sunnen Products Company exemplifies captive bundling strategies that lock in precision-machining accounts across North America. The European synthetic specialist tier includes Eurol BV, which occupies a position defined by REACH-compliant formulations that satisfy tightening chemical standards without sacrificing cutting performance.
| Leading Market Players |
|---|
| Growmark |
| Eurol BV |
| Sunnen Products Company |
| Houghton International |
| CC Jensen |
| Penrite Oil |
| Sunbelt Lubricants |
| Stahli USA |
| Lansky Sharpeners |
| Others |
Cost & Logistics Intelligence
The Ruhr Valley industrial cluster concentrates synthetic ester base-stock capacity for European formulators, and this geographic concentration grants incumbent blenders pricing power over precision machining shops lacking alternative certified suppliers. REACH re-registration deadlines compress approval cycles for additive packages, forcing smaller regional blenders to absorb compliance costs or exit, which tightens supply and sustains premium pricing for pre-certified synthetic formulations.
Pricing Analysis
The customization-premium spread separates configured-to-order synthetic formulations from standard mineral oil grades. Three-tier pricing structure across premium synthetic, standard mineral, and economy spot-purchase levels captures differentiation by certification grade and after-sales service bundling. Pricing pressure stems from REACH substance reporting burdens compressing margins for legacy mineral oil blenders without dedicated regulatory affairs teams. Automotive powertrain operations exhibit highest price sensitivity due to 18-24 month fluid validation cycles locking in volume discounts, while aerospace Tier-1 suppliers show lowest sensitivity as downstream OEM mandates override cost considerations.
Supply Chain Analysis
Export-control regimes on advanced synthetic base-stock technologies limit technology transfer to certain precision machining markets, constraining local formulation capacity in emerging manufacturing clusters. Supply concentrates among German, United States, and Japanese chemical producers for polyalphaolefin and ester base stocks. Raw material dependencies rest on petroleum feedstocks for mineral oil and vegetable oil derivatives for biodegradable variants. Single-source vulnerability from European synthetic ester producers exposes formulators to input volatility. Distribution runs through direct technical service teams embedded in manufacturing clusters, displacing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic formulation chemistry is disrupting mineral oil dominance as REACH and EPA restrictions on chlorinated paraffins force process re-qualification across aerospace and automotive supply chains.
For Market Incumbents: Insulate market position by deepening backward integration into synthetic ester base-stock supply and accelerating JIS certification investments for Japanese precision component manufacturing. Threat from emerging synthetic specialists with pre-certified REACH portfolios demands channel control through integrated fluid-service bundles combining honing oil with filtration and waste management.
For New Entrants and Emerging Players: Build out technical service density in precision machining job shops lacking in-house chemists to interpret used-oil analysis, targeting Italian and Spanish markets where regional blenders exit direct compliance. White-label partnerships with exiting regional formulators offer lowest-friction go-to-market path.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthetic specialists with regulatory pre-certification and captive equipment bundling capabilities. Long-term viability hinges on formulation chemistry transition completion rather than mineral oil scale. Acquisition targets should demonstrate REACH-compliant additive documentation and embedded technical service teams. Signal to watch is METI framework implementation pace in Japanese precision component manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stocks | Captures margin from polyalphaolefin supply concentration among European chemical producers. |
| REACH Pre-Certification Investment | Locks in aerospace Tier-1 supply agreements ahead of re-registration deadline compression. |
| Integrated Fluid-Service Bundling | Displaces spot purchasing through real-time inventory monitoring and automated replenishment. |
| JIS Certification for Japanese Market Entry | Opens share in Aichi Prefecture precision component manufacturing ahead of METI deadlines. |
| Direct Digital Distribution Platform | Bypasses wholesale markups and accelerates product trials with precision machining shops. |
Research Approach
Operator-level perspectives from plant engineers at precision machining shops, procurement leads at aerospace Tier-1 suppliers, technical R&D directors at lubricant formulators, and aftermarket service heads at machine tool OEMs anchored the qualitative base. Primary interviews combined with secondary validation from ECHA substance volume databases, EPA TSCA filings, customs and trade data on base-stock flows, and SEC filings from multinational lubricant houses. Bottom-up demand modeling across formulation chemistry tiers triangulated with top-down supply-side capacity assessments.
Scenario-bracketing framed demand trajectories across the analysis window, with segmentation dimensions including product type, application end-use, end user archetype, and distribution channel. CAGRs derived from curve-fitting historical consumption patterns against projected aerospace surface-finish tolerance tightening and automotive process approval inertia. Industry-specific inputs incorporated REACH re-registration timeline impacts and MIIT industrial upgrading program acceleration in Chinese state-owned aerospace enterprises.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by synthetic base-stock producers or accelerated chlorinated paraffin substitution subsidies would shift outcomes. Material shifts in EU Green Deal chemical restriction enforcement timelines or METI framework implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Commercial Electronic Detonator Market