
 Global Phosphate Esters Market | 2026-2036
Global Phosphate Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phosphate Esters Market Foresight
UL 94 flammability certification is bifurcating the competitive landscape into qualified suppliers and commodity producers. BASF SE leverages its integrated phosphorus chemistry platform to sustain premium positioning in aryl phosphate esters for engineered polymers. Lanxess AG anchors its European manufacturing base while competing aggressively in North American hydraulic fluid applications through specialized distribution networks.
Phosphate esters are organophosphorus compounds synthesized through phosphorylation of alcohols or phenols, yielding molecules with phosphorus-oxygen-carbon bonds that impart flame retardancy, lubricity, and surfactant functionality; industrial grades typically achieve phosphorus content between 4% and 12% by weight depending on molecular architecture. Aryl phosphate esters dominate margin pools in engineering thermoplastics due to their thermal stability above 300°C, while alkyl phosphate esters are gaining fastest in synthetic lubricants where hydrolytic stability requirements have intensified. The plasticizers segment remains mature in PVC applications but faces displacement pressures from bio-based alternatives in European consumer goods.
REACH registration under ECHA mandates comprehensive toxicological dossiers for aryl phosphate esters entering European polymer supply chains, while EPA TSCA Section 5 premanufacture notifications govern new chemical introductions in the United States. China's GB standards for flame-retardant materials, administered by SAMR, are converging with international norms but retain country-specific testing protocols that complicate cross-border formulation strategies. Stakeholders must monitor regulatory divergence between EU F-Gas restrictions and evolving U.S. state-level chemical disclosure laws to anticipate reformulation cycles and qualify alternative chemistries ahead of compliance deadlines.
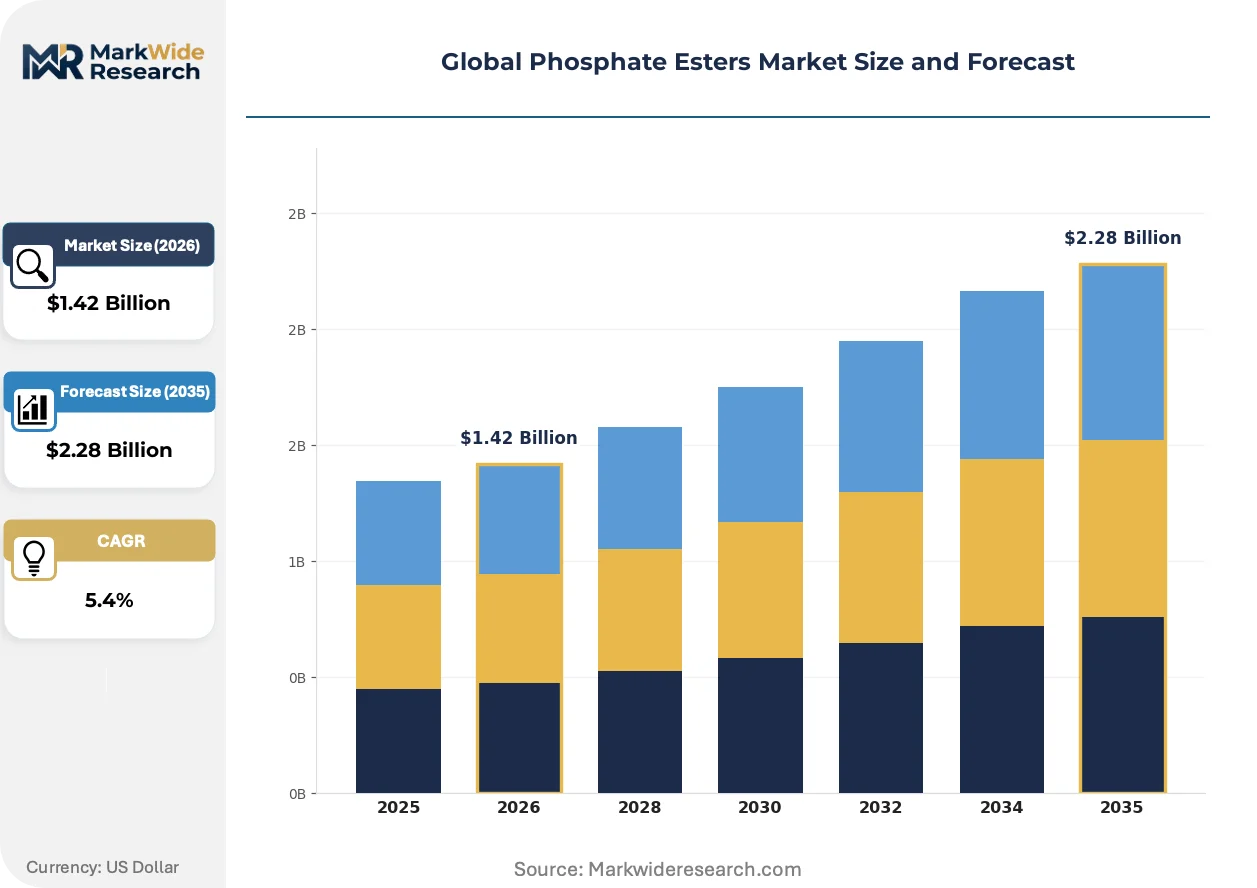
Market Dynamics
REACH registration deadlines and China's GB standard convergence are forcing simultaneous reformulation across European and Asian polymer supply chains, compressing product development cycles while elevating toxicological dossier requirements for aryl phosphate ester producers.
Growth Catalysts
- Automotive Interior Mandates:OEM procurement specifications for UL 94 V-0 certified materials are expanding flame-retardant loadings in electric vehicle battery housings and cabin components.
- REACH Annex XIV Authorization:Restrictions on halogenated alternatives are redirecting formulation priorities toward phosphorus-based chemistry in European consumer electronics and construction materials.
- Hydraulic Fluid Specifications:Industrial machinery operators in Germany and the United States are upgrading to fire-resistant hydraulic fluids for high-temperature metalworking and aviation ground support equipment.
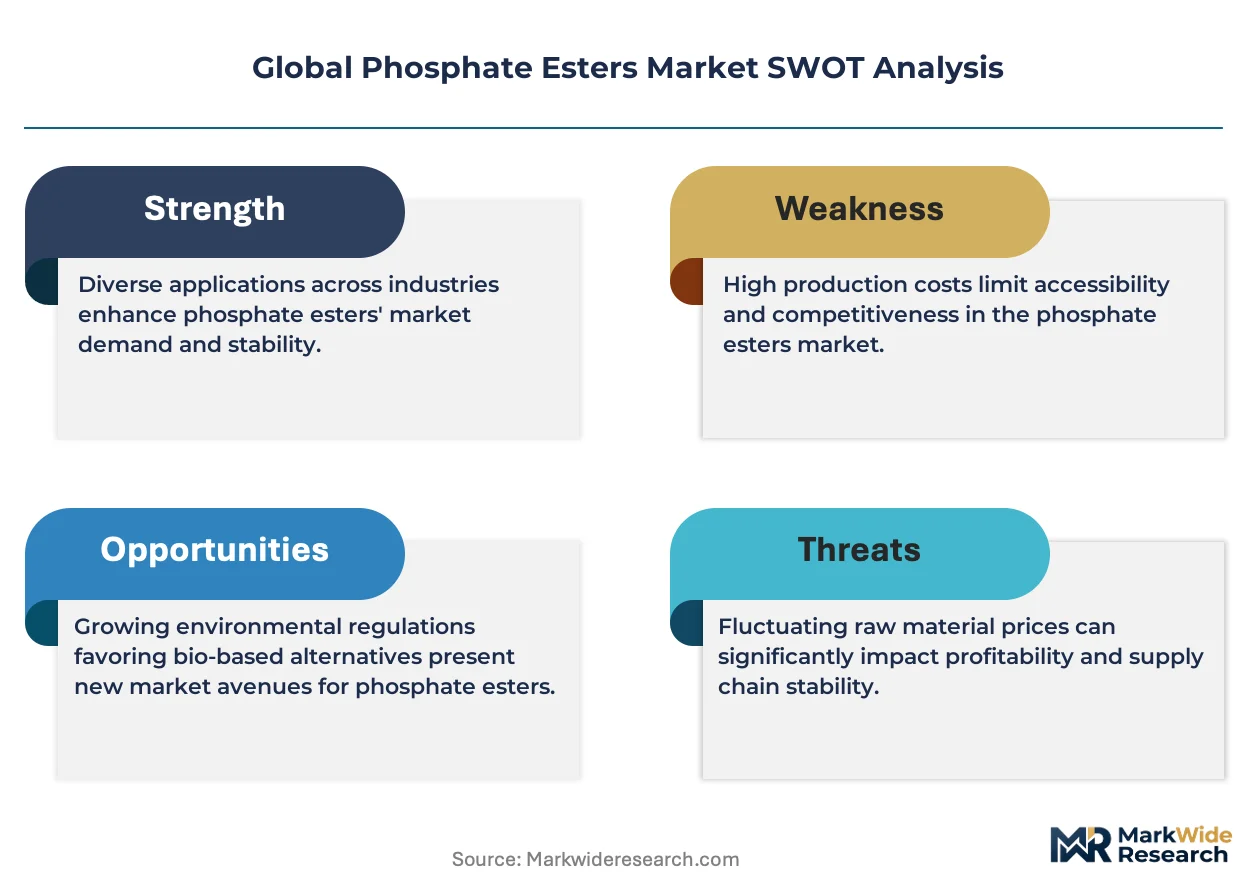
Market Restraints
- Phosphorus Feedstock Concentration:Yellow phosphorus production clusters in Yunnan and Guizhou provinces create geographic supply vulnerability for Western phosphate ester manufacturers.
- Hydrolytic Degradation Limits:Alkyl phosphate esters face performance ceilings in high-moisture lubricant applications, restricting penetration into marine and outdoor equipment segments.
- Bio-Based Plasticizer Substitution:European PVC compounders are piloting epoxidized soybean oil and citrate alternatives under pressure from retailer sustainability scorecards.
Strategic Opportunities
- India BIS Certification Gap:Domestic flame-retardant formulation capabilities lag behind polymer processing growth in Gujarat and Maharashtra, creating import substitution potential for qualified suppliers.
- Synthetic E-Fluid Convergence:Battery thermal management systems are merging dielectric coolant and flame-retardant functions, opening specification windows for customized phosphate ester blends.
- EU F-Gas Regulation Alignment:Refrigeration system manufacturers are requalifying compressor lubricants ahead of hydrofluorocarbon phase-down schedules, favoring compatible phosphate ester chemistries.
Industry Challenges
- Toxicological Dossier Compilation:ECHA data requirements for reproductive toxicity and environmental fate studies demand 18-24 month lead times, delaying market entry for novel molecular architectures.
- Cross-Border Standard Harmonization:Divergent flammability testing protocols between China's SAMR-administered GB standards and UL methodologies force redundant certification investments for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phosphate Esters Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Phosphate Esters, Aryl Phosphate Esters, Alcohol Phosphate Esters, Amino Phosphate Esters Application: Personal Care, Food Additives, Agricultural Chemicals, Plasticizers End User: Consumer Goods, Agriculture, Pharmaceuticals, Industrial Form: Liquid, Powder, Emulsion, Granular |
| Companies Covered | BASF SE, Lanxess AG, Dow Chemical Co., Croda International Plc, Evonik Industries AG, Stepan Co., Clariant International Ltd., Eastman Chemical Company, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phosphate Esters Market Shifts & Advancements
Phosphate ester chemistry is fragmenting into application-specific molecular designs as end-users abandon universal grades in favor of performance-optimized formulations tailored to thermal, hydrolytic, and compatibility constraints.
Reactor-integrated phosphorylation technology is miniaturizing batch sizes for specialty aryl phosphate esters, enabling toll manufacturers to serve engineered polymer compounders with 48-hour turnaround on customized phosphorus content specifications. Automotive Tier 1 suppliers in Stuttgart and Detroit are adopting these flexible supply arrangements to reduce working capital tied to flame-retardant inventory. The shift is compressing minimum viable production runs from 20-ton batches to sub-ton quantities, fragmenting volume concentration among regional blenders.
China's GB 8624-2012 standard revisions for building material flammability are tightening smoke density and toxicity requirements for interior finishes, accelerating substitution of brominated flame retardants in decorative laminates and insulation foams. Polymer processors in Jiangsu and Zhejiang provinces are requalifying phosphate ester formulations ahead of provincial enforcement inspections. The regulatory momentum is spilling into export-oriented manufacturing, as multinational buyers harmonize global specifications to Chinese baselines.
Specification-driven procurement is consolidating qualified supplier lists among polymer compounders, with technical service capabilities displacing price as the primary selection criterion for flame-retardant procurement teams. European automotive OEMs are reducing approved vendor pools from twelve to four phosphate ester sources, demanding dedicated regulatory affairs support and joint development agreements. The concentration is most pronounced in Bavaria and Baden-Württemberg, where integrated polymer processing clusters favor proximity-based technical collaboration over distant commodity supply.
Global Phosphate Esters Market Segmentation
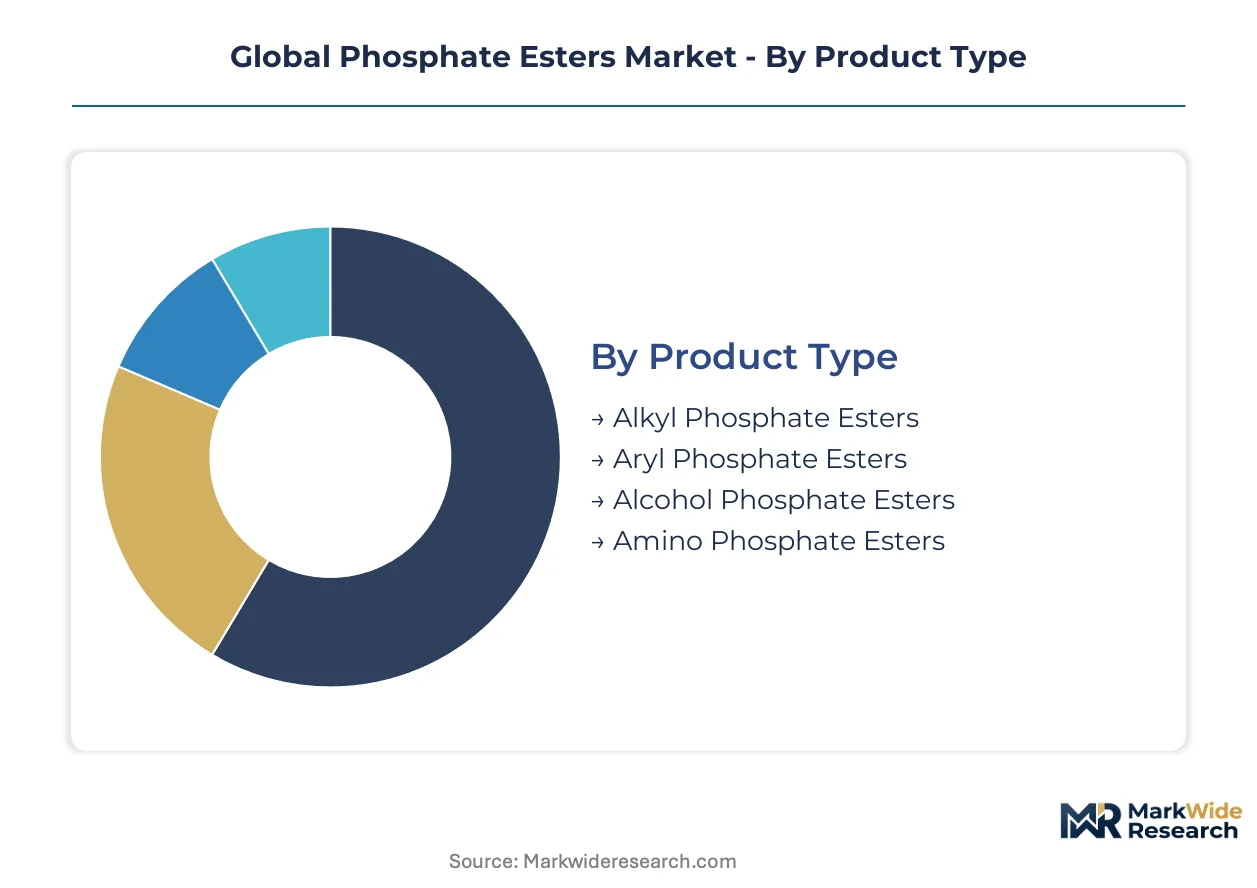
Phosphate ester formulation strategies diverge sharply across molecular architectures and end-use specifications, with substitution pressures from bio-based alternatives and halogen-free mandates fragmenting traditional volume concentration. Procurement teams now prioritize application-specific performance over commodity grades, forcing suppliers to align production with precise thermal stability, hydrolytic resistance, or surfactant functionality requirements.
Product Type:
Aryl phosphate esters face the most acute substitution pressure from emerging phosphorus-nitrogen synergists in European electronics, while alkyl variants confront bio-lubricant competition in metalworking fluids.
- Alkyl Phosphate Esters:These aliphatic organophosphorus compounds deliver superior hydrolytic stability in synthetic lubricant formulations, with phosphorus content typically ranging from 4% to 8% by weight. Demand concentrates in German automotive transmission fluids and United States aviation ground support equipment where fire-resistance specifications under FAA regulations have intensified. Hydrolytic degradation limits in high-moisture environments restrict penetration into marine applications.
- Aryl Phosphate Esters:Phenol-derived structures achieve thermal stability above 300°C, making them indispensable for engineering thermoplastics requiring UL 94 V-0 certification. European automotive OEMs in Stuttgart and Wolfsburg specify these grades for electric vehicle battery housings, though REACH Annex XIV authorization requirements for toxicological dossiers extend qualification timelines to 18-24 months.
- Alcohol Phosphate Esters:Intermediate molecular weights serve surfactant and emulsifier functions in industrial cleaning formulations, with demand clustering in United States metal finishing operations.
- Amino Phosphate Esters:Nitrogen-modified structures provide corrosion inhibition in specialized lubricant applications, finding niche adoption in German precision machining coolants.
Aryl phosphate esters anchors the volume base while alkyl phosphate esters gains share at the steepest rate.
Application:
Cost tier stratification separates specification-grade flame retardants from commodity plasticizers, with premium positioning concentrated in automotive and electronics certification chains.
- Personal Care:Mild surfactant properties drive incorporation into hair conditioning and skin cleansing formulations, with demand concentrating in French and German cosmetic manufacturing clusters under ECHA cosmetic ingredient scrutiny.
- Food Additives:Phosphoric acid esters function as emulsifiers and pH stabilizers in processed foods, with EFSA maximum residue limits governing European bakery and dairy applications.
- Agricultural Chemicals:Pesticide formulation adjuvants and fertilizer coating agents represent mature demand in United States Corn Belt operations, though phosphorus runoff regulations in Chesapeake Bay watershed states have tightened application protocols.
- Plasticizers:PVC compatibility and migration resistance sustain volume in construction and automotive interiors, yet European retailer sustainability scorecards are accelerating pilot programs with epoxidized soybean oil alternatives in German and Dutch consumer goods.
Plasticizers retains the largest installed base while personal care climbs fastest amid clean-label formulation trends.
End User:
Customer type fragmentation reflects divergent procurement sophistication, with industrial buyers demanding joint development agreements while consumer goods purchasers prioritize regulatory pre-certification.
- Consumer Goods:Flame-retardant specifications for electronics housings and furniture textiles dominate, with Chinese export manufacturers in Guangdong province requalifying formulations to meet converging GB standards and multinational buyer requirements.
- Agriculture:Fertilizer efficiency coatings and pesticide emulsifiers sustain steady offtake, though environmental fate studies under EPA TSCA Section 5 have delayed novel molecular introductions in United States specialty crop applications.
- Pharmaceuticals:High-purity grades serve as excipients and solubilizers, with FDA Type II drug master file requirements concentrating qualified supplier lists among United States generic drug manufacturers.
- Industrial:Fire-resistant hydraulic fluids and metalworking lubricants anchor volume in German automotive stamping plants and United States aerospace machining clusters, with ISO 6743-4 specification compliance mandatory for aviation ground equipment.
Industrial commands the volume foundation while pharmaceuticals expands most quickly on high-margin specialty grade demand.
Form:
Supply concentration in liquid processing infrastructure favors continuous reactor operations, while powder and granular investments lag amid batch manufacturing fragmentation.
- Liquid:Dominant physical state for lubricant and hydraulic fluid applications, with integrated phosphorylation reactor networks in Germany's Ruhr region and China's Jiangsu province enabling 48-hour turnaround on customized specifications.
- Powder:Solid-state delivery suits polymer compounding operations, with micronization capabilities concentrated among Japanese and German specialty chemical processors serving engineered thermoplastics.
- Emulsion:Water-dispersible formulations serve agricultural spray adjuvants and personal care applications, with stability challenges in high-temperature storage limiting geographic distribution range.
- Granular:Controlled-release fertilizer coatings and solid flame-retardant masterbatches represent emerging demand, though granulation equipment investments remain concentrated among Chinese phosphorus derivatives producers.
Liquid retains volume dominance while granular posts the steepest expansion trajectory on controlled-release agricultural applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer processors and lubricant blenders in Germany, China, and the United States concentrate procurement authority for specification-grade phosphate esters. Each market enforces distinct regulatory entry barriers that fragment supplier qualification timelines.
United States
Aviation ground support equipment operators and automotive OEMs in Detroit drive fire-resistant hydraulic fluid demand. EPA TSCA Section 5 premanufacture notifications govern novel molecular introductions, extending qualification cycles for aryl phosphate ester producers. Gulf Coast petrochemical corridors near Houston host integrated phosphorylation capacity serving domestic lubricant blenders.
Germany
Automotive Tier 1 suppliers in Stuttgart and Wolfsburg specify UL 94 V-0 certified materials for electric vehicle battery housings. ECHA REACH Annex XIV authorization mandates comprehensive toxicological dossiers, compressing product development timelines for halogen-free alternatives. Ruhr region reactor networks enable 48-hour turnaround on customized phosphorus content specifications.
China
Export manufacturers in Guangdong province requalify formulations to meet converging GB standards and multinational buyer requirements. SAMR-administered GB 8624-2012 standard revisions tighten smoke density requirements for interior finishes. Jiangsu and Zhejiang polymer processors anchor flame-retardant formulation demand ahead of provincial enforcement inspections.
India
Polymer processing growth in Gujarat and Maharashtra outpaces domestic flame-retardant formulation capabilities. BIS certification gaps create import substitution potential for qualified suppliers meeting automotive and electronics specifications. Mumbai-Pune industrial corridors concentrate demand from consumer goods exporters targeting European retail compliance.
Japan
Engineered thermoplastic compounders in Kanto and Kansai regions demand micronized powder grades for precision polymer processing. METI industrial standards align with international flammability protocols while retaining country-specific testing requirements. Osaka-based specialty chemical processors serve regional automotive electronics clusters with application-technical support.
Global Phosphate Esters Market Competitive Landscape
Player mix skews toward integrated phosphorus chemistry specialists and regional toll manufacturers serving specification-driven procurement. Market structure concentrates qualified supplier lists among polymer compounders reducing approved vendor pools from twelve to four sources. Three archetypes dominate: integrated chemical majors with captive phosphorus supply, regional blenders with flexible batch capabilities, and toll manufacturers with reactor-integrated phosphorylation technology. Competitive moves center on joint development agreements with automotive OEMs and backward integration into yellow phosphorus feedstock security.
Among European integrated majors, BASF SE and Lanxess AG exemplify the premium-tier positioning anchored by regulatory affairs capabilities and dedicated technical service teams. Eastman Chemical Company represents North American specialty chemical positioning with proximity to domestic polymer processing clusters. Croda International Plc occupies a distinct niche serving personal care and industrial surfactant applications where mild formulation properties command specification premiums.
| Leading Market Players |
|---|
| BASF SE |
| Lanxess AG |
| Dow Chemical Co. |
| Croda International Plc |
| Evonik Industries AG |
| Stepan Co. |
| Clariant International Ltd. |
| Eastman Chemical Company |
| ExxonMobil Chemical |
| Others |
Supply & Pricing Matrix
Batch reactor utilization rates above 85% in Germany's Ruhr region and Jiangsu province create asymmetric scale economies that simultaneously concentrate supply authority and establish phosphorus-content price floors for specialty aryl phosphate esters. This capacity tightness allows integrated producers to index long-term supply agreements to yellow phosphorus spot markets while toll manufacturers absorb margin compression through flexible minimum-run pricing.
Pricing Analysis
Cost-plus contracts with yellow phosphorus indexation dominate long-term supply agreements between integrated producers and automotive OEM procurement teams. Three-tier pricing structure across premium, standard, and economy levels separates UL 94 V-0 certified grades from uncertified commodity batches and unbranded import alternatives. Cost compression in standard-grade alkyl phosphate esters is intensifying because Chinese export manufacturers are absorbing phosphorus feedstock volatility to maintain European market share. Polymer compounders in consumer electronics represent the most price-sensitive buyer segment, while German automotive Tier 1 suppliers demonstrate lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Just-in-time inventory strategies prevail among lubricant blenders in Detroit and Stuttgart, while polymer compounders maintain strategic stockpiles of UL-certified aryl phosphate esters to buffer against 18-24 month REACH authorization delays. Supply concentrates in China, Germany, and the United States, with yellow phosphorus production anchored in Yunnan and Guizhou provinces. Downstream distribution runs through specialized chemical distributors serving polymer processing clusters rather than commodity trading houses. Single-source vulnerability in phosphorus feedstock creates structural risk for Western formulators dependent on Chinese yellow phosphorus exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate ester chemistry is approaching a platform-economics inflection as automotive battery thermal management systems merge dielectric coolant and flame-retardant functions into unified specification regimes. This interoperability shift favors suppliers capable of joint development partnerships across previously siloed application domains.
For Market Incumbents: Consolidate regulatory affairs capabilities through dedicated ECHA liaison teams and captive toxicological dossier compilation to compress 18-24 month REACH timelines. Backward integration into yellow phosphorus supply through offtake agreements with Guizhou producers mitigates feedstock concentration risk from Yunnan supply disruptions.
For New Entrants and Emerging Players: Lead with India BIS certification gaps in Gujarat and Maharashtra polymer processing corridors, where domestic flame-retardant formulation capabilities lag demand growth. Target synthetic e-fluid convergence applications in battery thermal management as the most penetrable specification window, using toll manufacturing partnerships with Ruhr region reactor networks to bypass capital-intensive phosphorylation investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated phosphorus chemistry specialists with captive regulatory affairs infrastructure over commodity blenders facing margin compression. Long-term viability hinges on qualification moats in automotive OEM approved vendor lists. The signal to watch is REACH Annex XIV authorization velocity for novel molecular architectures as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive yellow phosphorus supply from Guizhou producers insulates Western formulators from SAMR export licensing volatility. |
| Joint Development Agreement | Automotive OEM partnerships in Stuttgart and Wolfsburg lock in UL 94 V-0 specification authority ahead of competitor qualification. |
| Regulatory Affairs Expansion | Dedicated ECHA liaison teams compress toxicological dossier timelines for aryl phosphate ester market entry. |
| Toll Manufacturing Partnership | Reactor-integrated phosphorylation technology in Ruhr region enables 48-hour turnaround without capital deployment. |
| Long-term Supply Agreement | Indexed phosphorus contracts with German automotive Tier 1 suppliers stabilize revenue through feedstock price cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing polymer compounders in Jiangsu and Zhejiang provinces, lubricant procurement leads at German automotive OEMs, flame-retardant technical directors at European electronics manufacturers, and toll manufacturing operators in the Ruhr region. Secondary validation drew from ECHA REACH registration databases, SAMR GB standard revision notices, SEC filings of listed chemical majors, and customs trade data tracking phosphorus derivative flows. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down capacity assessments from phosphorylation reactor networks.
Across the analysis window, the analytical framework modeled segmentation dimensions including molecular architecture tier, end-use industry cluster, certification status, and regional production hub concentration. CAGRs were derived through regression analysis of historical consumption patterns against polymer processing capacity expansion and regulatory substitution timelines. Industry-specific forecast inputs incorporated REACH authorization velocity projections and GB 8624-2012 enforcement inspection schedules.
Underlying assumptions cover sustained automotive electrification content growth and phosphorus feedstock supply continuity, with deviation risk concentrated in ECHA data requirement expansion or SAMR export licensing interventions. Revision becomes warranted when REACH Annex XIV authorization timelines extend beyond 30 months or Chinese environmental inspections disrupt Yunnan production clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Chemical Process Mixers Market