
 Fixed Crane Market | 2026-2036
Fixed Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Crane Market Analysis
Market Context
Modular assembly and precast integration is fragmenting traditional fixed crane deployment models across large-scale construction sites. Konecranes leverages its port automation expertise to anchor terminal crane contracts in Northern Europe. XCMG dominates domestic infrastructure bids through manufacturing scale and state-backed project pipelines. Liebherr differentiates via precision engineering for wind turbine installation vessels.
Technical Definition and Segments
A fixed crane denotes a lifting apparatus permanently anchored to foundations, rails, or structural frames, with load capacities spanning 5 to over 3,000 tonnes and slewing radii governed by counterweight geometry and boom configuration. Its primary purpose centers on sustained heavy-lift operations where mobility is unnecessary—tower cranes erect high-rise structures, gantry systems load container vessels, and derrick arrangements service offshore platforms. Top slewing configurations capture the largest share of construction applications due to height adaptability, while rail-mounted systems expand fastest in automated port environments where electric drive technology displaces hydraulic alternatives. Hydraulic technology still occupies legacy shipyard installations, though electric systems lead new orders driven by energy efficiency mandates and reduced maintenance intervals.
Regulatory Frame and Outlook
FAA obstruction standards govern tower crane height near US air corridors, while the EU Machinery Directive and CE marking enforce safety interlocks and operator visibility requirements across European installations. China's GB/T 5031 standard and SAMR oversight dictate domestic structural testing protocols, creating divergent certification paths for multinational suppliers. Stakeholders must monitor how regional decarbonization timelines alter powertrain specifications and foundation designs.
Market Dynamics
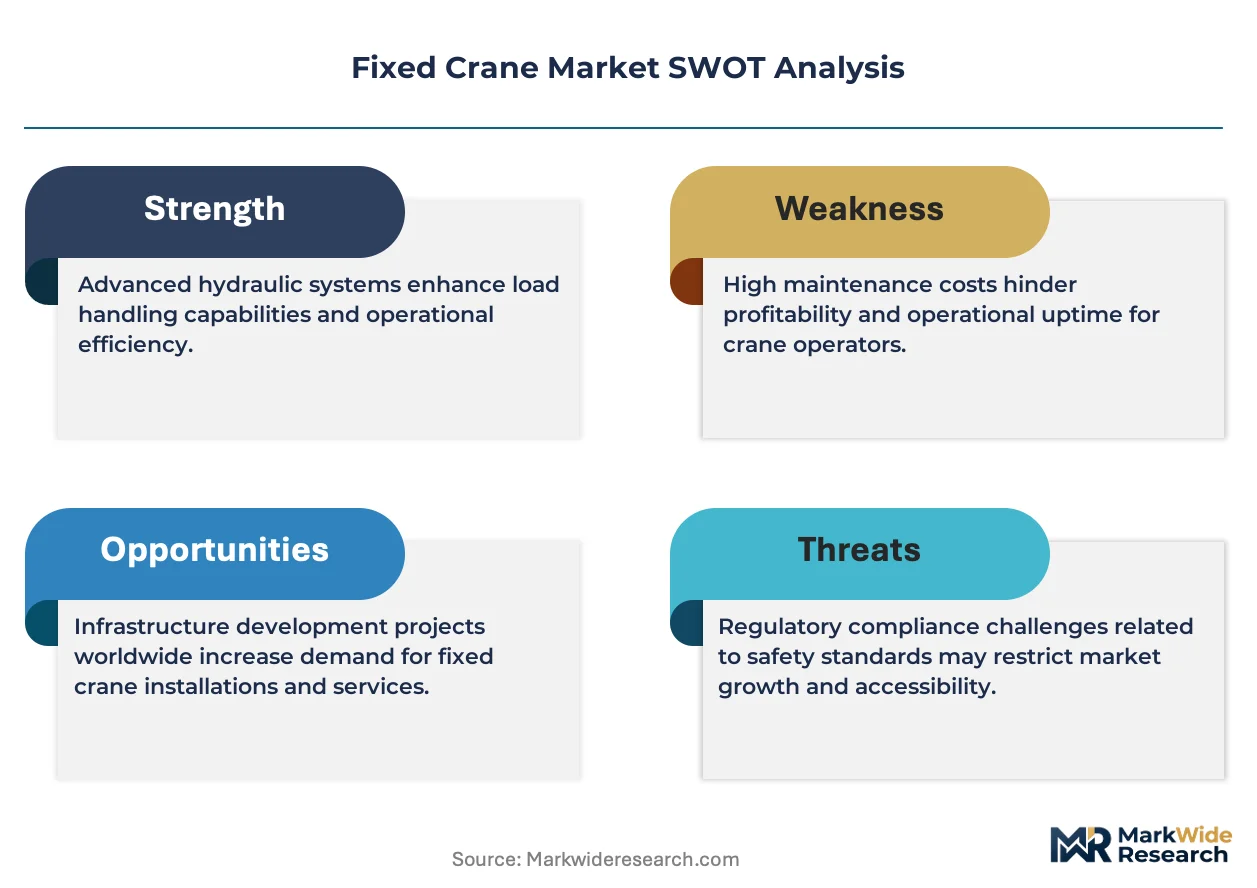
Electrification of port infrastructure and offshore wind vessel specifications are compressing demand for hydraulic fixed crane systems while expanding specifications for high-capacity electric drive configurations.
Growth Catalysts
- EU Machinery Directive compliance:CE marking mandates for safety interlocks and operator visibility are accelerating replacement cycles in European terminal installations.
- Offshore wind installation vessels:Heavy-lift specifications for turbine component handling are expanding orders for derrick and gantry configurations above 1,500 tonnes.
- China port automation:State-backed container terminal modernization is driving rail-mounted electric crane deployments at Qingdao and Shanghai facilities.
Market Restraints
- Specialized steel alloy supply:High-strength plate availability constrains production scheduling for ultra-heavy boom fabricators concentrated in Germany and Japan.
- FAA obstruction protocols:Height restrictions near US air corridors limit tower crane deployment in Dallas-Fort Worth and Chicago construction corridors.
- Modular construction substitution:Prefabricated building components reduce on-site lifting cycles, compressing rental demand for conventional tower configurations.
Strategic Opportunities
- India port expansion:Jawaharlal Nehru Port and Mundra Port automation initiatives create demand for rail-mounted container handling systems.
- EU Green Deal alignment:Carbon border adjustment mechanisms favor electric drive retrofits over hydraulic replacements in North Sea terminals.
- Digital twin convergence:Integration of IoT load monitoring with predictive maintenance platforms enables premium service tier pricing for fleet operators.
Industry Challenges
- Certification timeline compression:SAMR structural testing protocols in China and CE marking in Europe create parallel approval tracks that extend delivery schedules.
- Legacy hydraulic integration:Shipyard operators face capital-intensive retrofit requirements when electrifying existing foundation-mounted installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Crane Market |
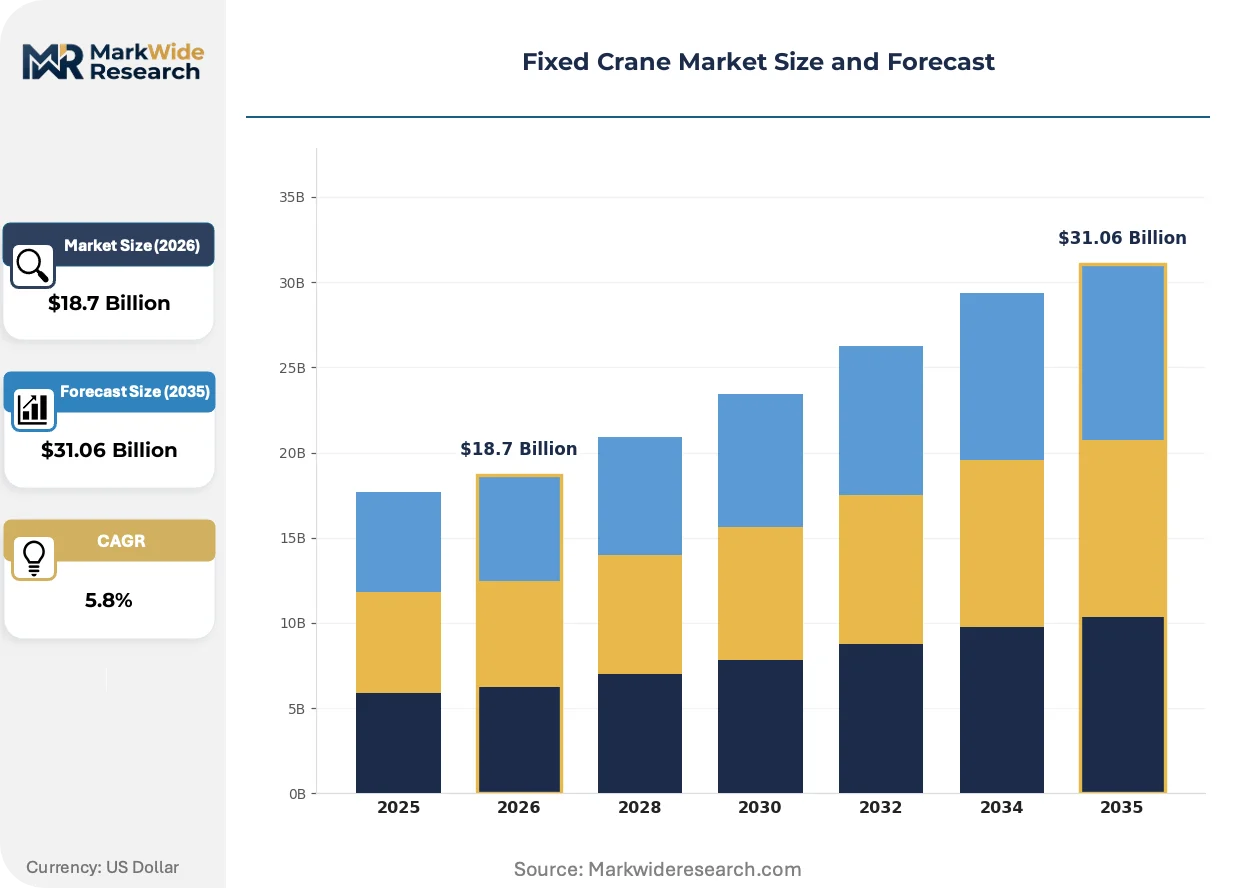
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Slewing, Bottom Slewing, Rail-Mounted, Stationary Application: Construction, Shipbuilding, Infrastructure, Manufacturing End User: Construction Companies, Shipping Yards, Manufacturers, Contractors Technology: Hydraulic, Electric, Manual, Pneumatic |
| Companies Covered | Konecranes, Tadano, XCMG, Terex, Manitowoc, Zoomlion, SANY Heavy Equipment, Palfinger, Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Crane Market Emerging Trajectories
Fixed crane architecture is pivoting from standalone mechanical systems to electrified, sensor-integrated platforms where energy efficiency and remote operability determine competitive viability.
Permanent magnet synchronous motor technology is rendering obsolete conventional wound-rotor induction drives in new port crane installations. Rotterdam and Hamburg terminal operators are specifying all-electric hoisting systems for container handling gantries. This transition is compressing aftermarket demand for hydraulic pump assemblies and specialized fluid maintenance services.
REACH substance restrictions on hydraulic fluids are forcing reformulation of synthetic lubricants used in legacy shipyard cranes. The regulation is elevating compliance costs for operators maintaining pre-2015 installations. Baltic Sea terminals are responding with accelerated electrification timelines to bypass fluid management complexity.
Lifecycle service contracting is displacing traditional equipment purchase-plus-maintenance arrangements in automated port environments. Terminal operators in Antwerp and Singapore are bundling crane availability guarantees with predictive analytics subscriptions. This shift is most pronounced in transshipment hubs where uptime metrics determine contract renewals.
Fixed Crane Market Segmentation
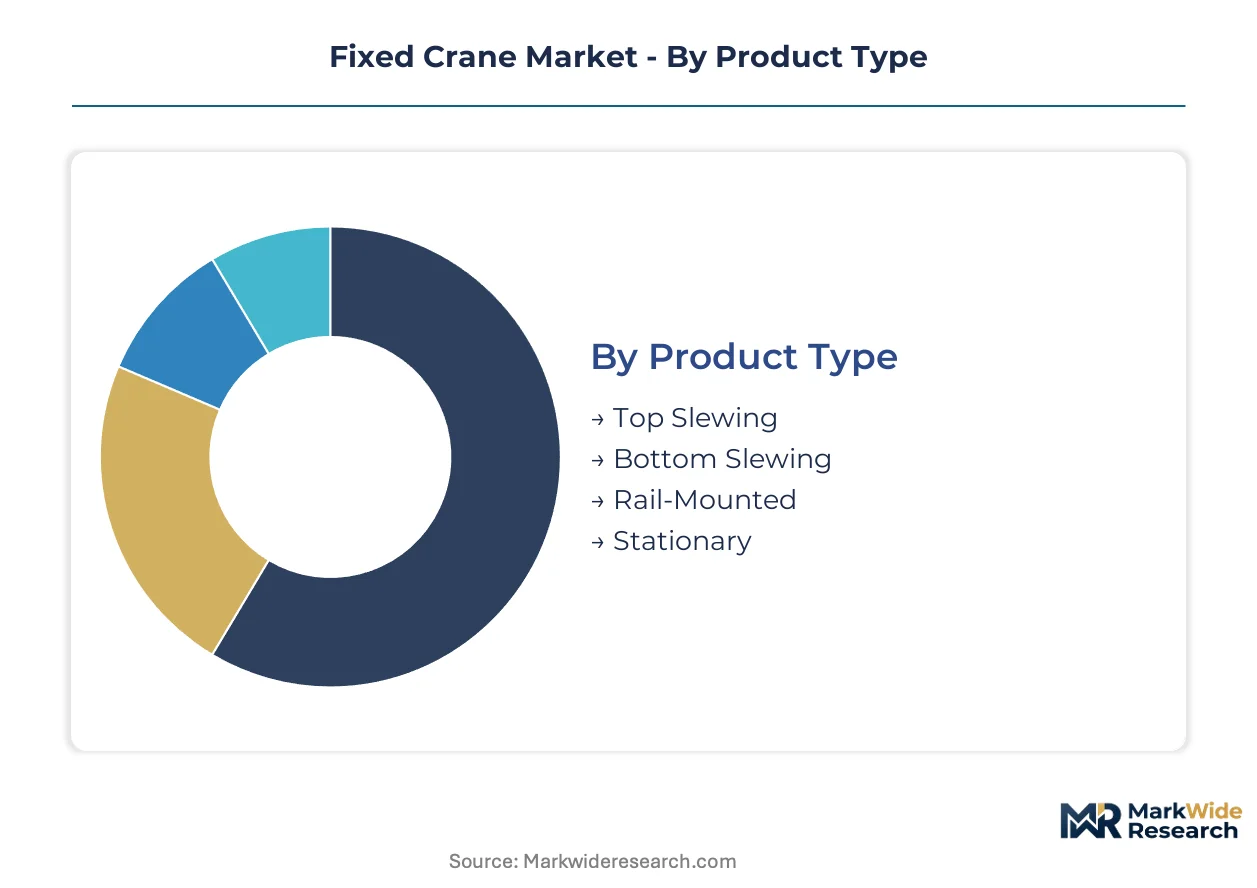
Fixed crane procurement patterns diverge sharply across deployment contexts, with port automation driving rail-mounted specifications while high-rise construction favors adaptable slewing architectures. Understanding these segment boundaries clarifies where electrification investments concentrate versus where hydraulic legacy systems persist.
Product Type:
Mature configurations dominate construction applications, yet emerging rail-mounted designs are capturing terminal automation contracts through integrated electric drive systems.
- Top Slewing:The boom and counterweight assembly rotates atop a vertical tower, enabling height extension through modular mast sections. Demand concentrates in Chinese urban cores where GB/T 5031 compliance governs high-rise erection projects facing dense airspace constraints. Tower adaptability makes this configuration indispensable for superstructure work above 200 meters.
- Rail-Mounted:Gantry systems traverse fixed tracks along quay walls or container yards, integrating with terminal operating systems for automated positioning. Shanghai and Qingdao port authorities specify these for 24/7 transshipment operations where electric drive technology displaces hydraulic alternatives under state-backed modernization mandates.
- Bottom Slewing:The slewing mechanism sits at the base, limiting tower height but reducing structural load requirements. German and French contractors deploy these for mid-rise residential clusters where FAA obstruction protocols do not apply.
- Stationary:Permanently anchored derrick arrangements serve offshore platforms and heavy industrial sites. North Sea wind installation vessels specify these above 1,500-tonne capacity for turbine component handling.
Top slewing retains volume leadership; rail-mounted holds the steepest expansion curve.
Application:
Cost tier differentiation separates high-specification offshore installations from standardized construction rental fleets.
- Construction:Tower and gantry deployments for building erection, precast assembly, and structural steel placement. Chinese infrastructure pipelines and Indian urbanization projects drive order volumes for rental fleet operators.
- Shipbuilding:Heavy-lift derrick and portal systems for hull assembly and block erection. South Korean and Japanese yards maintain hydraulic legacy installations despite REACH fluid restrictions elevating compliance burdens.
- Infrastructure:Bridge deck placement, tunnel segment handling, and nuclear containment construction. EU Green Deal alignment favors electric retrofits for North Sea terminal adjacent projects.
- Manufacturing:Overhead and gantry systems for heavy equipment assembly lines. German automotive and aerospace fabricators specify precision-engineered stationary configurations.
Construction commands the largest installed base; infrastructure exhibits the most rapid specification upgrading.
End User:
Customer type determines procurement modality, with fleet operators favoring lifecycle contracts versus capital purchase.
- Construction Companies:Rental fleet operators and general contractors acquiring tower cranes for project-specific deployment. Antwerp and Singapore terminal-adjacent construction groups are bundling availability guarantees with predictive analytics subscriptions.
- Shipping Yards:Port authorities and terminal operators specifying rail-mounted container handling systems. Jawaharlal Nehru Port and Mundra Port automation initiatives in India create concentrated demand.
- Manufacturers:Industrial facilities integrating overhead cranes into production lines. Japanese METI efficiency standards accelerate electric drive adoption.
- Contractors:Specialized erection firms and heavy-lift service providers. Offshore wind vessel operators in the North Sea and Baltic regions drive premium derrick specifications.
Shipping yards lead capital expenditure intensity; contractors show the fastest adoption of service-integrated contracting models.
Technology:
Supply concentration for high-strength alloys and permanent magnet motors is compressing hydraulic system viability in new installations.
- Electric:Permanent magnet synchronous motors and regenerative drive systems. Rotterdam and Hamburg terminal operators specify all-electric hoisting for container gantries, displacing aftermarket demand for hydraulic pump assemblies.
- Hydraulic:Fluid power systems with piston pumps and valve controls. Legacy shipyard installations in Japan and South Korea face capital-intensive retrofit requirements under REACH substance restrictions.
- Manual:Hand-cranked or lever-operated systems for low-capacity maintenance applications. Small-scale fabrication shops in India retain these for cost-sensitive auxiliary lifting.
- Pneumatic:Compressed air drive systems for explosion-sensitive environments. Chemical processing facilities specify these where electric spark risk is prohibitive.
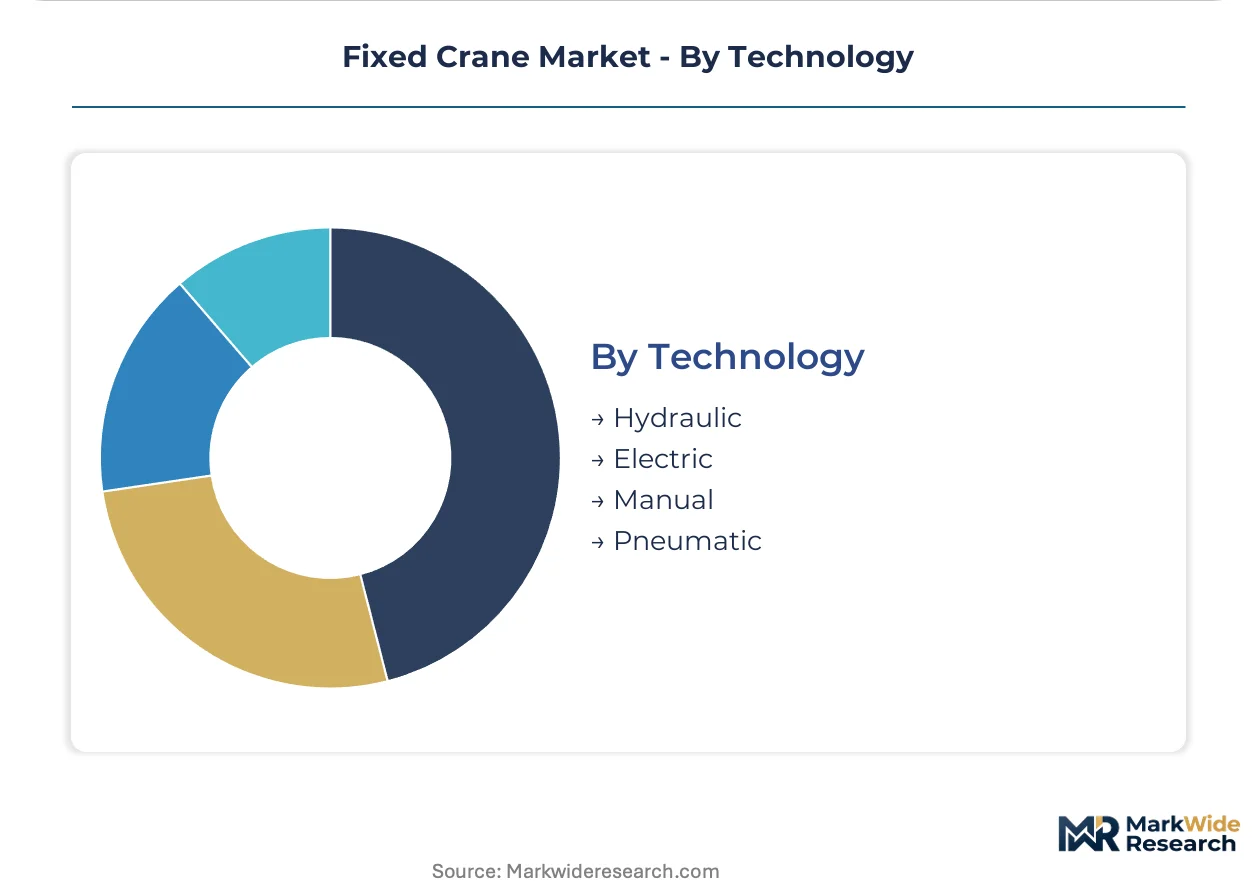
Electric systems dominate new order intake; hydraulic retains the largest installed base requiring maintenance revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators export heavy-lift fixed crane systems to North Sea offshore wind developers, while Chinese manufacturers supply rail-mounted configurations to automated port terminals across Asia and the Middle East.
China
State-backed infrastructure pipelines and nuclear construction projects drive orders for top-slewing and stationary configurations. SAMR structural testing protocols under GB/T 5031 standards govern domestic certification, creating divergent approval tracks for multinational suppliers. Shanghai and Qingdao port authorities deploy rail-mounted electric cranes for 24/7 transshipment operations.
Germany
Precision engineering for wind turbine installation vessels and automotive assembly lines sustains demand for high-capacity stationary systems. REACH substance restrictions on hydraulic fluids accelerate electrification timelines in Baltic Sea terminals. Hamburg terminal operators specify all-electric hoisting systems for container handling gantries.
United States
FAA obstruction protocols limit tower crane deployment height near Dallas-Fort Worth and Chicago air corridors, compressing available construction sites. OSHA and FAA joint oversight governs installation permits in dense urban airspace. Gulf Coast shipyards maintain hydraulic legacy installations despite compliance cost pressures.
India
Jawaharlal Nehru Port and Mundra Port automation initiatives create concentrated demand for rail-mounted container handling systems. CEA efficiency mandates and port authority modernization programs favor electric drive specifications. Maharashtra and Gujarat coastal clusters anchor domestic fabrication capacity expansion.
Japan
METI efficiency standards accelerate electric drive adoption in manufacturing-integrated overhead crane installations. South Korean and Japanese shipyards retain hydraulic legacy systems for hull assembly despite REACH-equivalent fluid management burdens. Nagoya and Osaka industrial corridors concentrate precision-engineered stationary configuration demand.
Fixed Crane Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: scale-driven fabricators anchoring state-backed infrastructure bids, precision-engineering houses serving offshore wind specifications, and automation-integrated vendors capturing port terminal contracts. Strategic moves concentrate on electrification portfolio pivots and lifecycle service contracting transitions. Geographic expansion into Indian and Middle Eastern port automation markets represents the dominant competitive vector.
Among Chinese scale-driven fabricators, XCMG and SANY Heavy Equipment occupy positions exemplifying state-backed project pipeline access. Liebherr anchors the precision-engineering tier for North Sea offshore wind installation vessels. Konecranes sits within the automation-integrated segment, representing port terminal system integration capabilities. These three company names from the raw data illustrate how competitive positioning fragments across capability specializations rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Konecranes |
| Tadano |
| XCMG |
| Terex |
| Manitowoc |
| Zoomlion |
| SANY Heavy Equipment |
| Palfinger |
| Liebherr |
| Others |
Supply Flow & Price Mechanics
Ruhr Valley fabricators in Germany anchor high-strength alloy supply for ultra-heavy boom assemblies, concentrating pricing power among specialized plate mills serving North Sea offshore wind specifications. Cost-plus contracts with steel indexation pass through raw material volatility to terminal operators and vessel integrators, compressing margins for crane OEMs without captive metallurgical capacity.
Pricing Analysis
Cost-plus contracts with LME steel indexation dominate procurement for heavy-lift configurations above 1,500 tonnes. Price differentiation rests on CE certification tier and electric drive integration level, with Hamburg terminal operators paying premiums for predictive maintenance bundling. Cost compression in standard tower crane rentals is intensifying because Chinese manufacturing scale floods mid-capacity segments. Rental fleet operators show highest price sensitivity; offshore wind vessel integrators demonstrate lowest.
Supply Chain Analysis
High-strength plate feedstock draws from Germany, Japan, and South Korea, where specialized mills control metallurgical specifications for 3,000-tonne capacity booms. Permanent magnet motors and precision gearboxes feed from Chinese and Japanese component clusters. Single-source vulnerability concentrates in rare-earth magnet supply for electric drive retrofits. Distribution runs through OEM-direct contracts for large installations and rental fleet aggregators for construction tower deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed crane architecture is approaching a platform-economics inflection where IoT-enabled predictive maintenance and terminal operating system interoperability determine contract renewals. The convergence of crane availability guarantees with software subscriptions restructures vendor-customer relationships toward outcome-based pricing.
For Market Incumbents: Pre-empt modular construction substitution by acquiring prefabrication logistics capabilities or partnering with building component suppliers. Defend against Chinese scale-driven fabricators by deepening vertical integration into permanent magnet motor supply. CE certification investment and Hamburg port automation reference contracts anchor premium positioning in European terminal markets. For New Entrants and Emerging Players: Indian port automation at Jawaharlal Nehru and Mundra represents the most penetrable entry point for rail-mounted electric crane specialists lacking established port relationships. Mid-capacity tower crane rental for Indian urban construction offers secondary white-space with lower capital barriers. Go-to-market through CEA efficiency mandate alignment and state port authority direct procurement channels accelerates initial contract wins. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation-integrated vendors with lifecycle service contracting penetration above fifty percent in transshipment hub installations. Long-term viability favors precision-engineering houses with offshore wind vessel specification track records and software-integrated fleet management platforms. Watch Baltic Sea terminal electrification timelines as inflection indicator for hydraulic-to-electric retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Rotterdam terminal operators specify all-electric hoisting, displacing hydraulic aftermarket revenue pools. |
| Predictive Maintenance Platform Launch | Antwerp and Singapore hub operators bundle availability guarantees with IoT analytics subscriptions. |
| CE Marking Pathway Acceleration | EU Machinery Directive compliance timelines determine European terminal replacement cycle capture. |
| Backward Integration into High-Strength Plate | Ruhr Valley metallurgical capacity secures boom fabrication scheduling for North Sea wind projects. |
| Joint Venture with Port Authority | Qingdao and Shanghai state-backed modernization creates captive demand for rail-mounted electric systems. |
Methodological Framework
A spread of perspectives from crane fleet operators, terminal engineering directors, offshore wind vessel integrators, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, port authority procurement disclosures, and SEC filings of listed equipment manufacturers. Bottom-up installation forecasts and top-down infrastructure spending projections were triangulated against GB/T 5031 certification records and EU Machinery Directive compliance databases.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by slewing configuration, technology tier by drive architecture, and application split across construction, port automation, and offshore wind vessel specifications. CAGRs were derived from rolling average infrastructure investment trajectories and electrification mandate adoption curves. Forecast inputs included SAMR structural testing protocol timelines and REACH substance restriction phase-out schedules for hydraulic fluids.
Macroeconomic conditions sit as an overlay; deviation in steel alloy pricing, container shipping volumes, or offshore wind auction awards would shift the trajectory. Forecasts reflect documented assumptions on electrification subsidy continuity and port automation capital allocation priorities. Material shifts in EU carbon border adjustment mechanism implementation or Chinese dual carbon goal acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Used Backhoe Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
CNC Machine Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Spray Washer Market
Construction Equipment
Truck Crane Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market