
 CNC Machine Market | 2026-2036
CNC Machine Market Size, Share, and Industry Trends Forecast 2026-2036
CNC Machine Market Intelligence
Five-axis precision-grade machining is redrawing competitive boundaries in metal fabrication. DMG MORI leverages in-house spindle production to control quality across its vertical machining centers. FANUC sustains dominance in servo motor and control system supply, anchoring downstream machine builders. Okuma differentiates through thermo-friendly design that compensates for thermal deformation during extended cuts.
A computer numerical control machine executes pre-programmed sequences of machining commands via servomechanisms and ball screws, achieving positional accuracies below five microns for cutting, milling, or grinding operations. Vertical machining centers lead unit shipments for general metalworking, while CNC lathes command stronger margins in automotive powertrain production. CAD/CAM integration represents the fastest-expanding technology segment as shops eliminate manual G-code programming. Contract manufacturers and OEM manufacturers split end-user demand, with the former prioritizing machine flexibility and the latter demanding dedicated transfer lines.
OSHA lockout/tagout rules and EPA metalworking fluid standards shape machine design and facility compliance costs in the United States. CE marking under the EU Machinery Directive governs market access across Germany, Italy, and France. Japan's METI promotes smart factory adoption through JIS standards for connected equipment. Stakeholders must weigh control architecture openness against vendor lock-in as adaptive control and DNC systems converge with industrial IoT platforms.
Market Dynamics
The CNC machine market is experiencing a fundamental restructuring as five-axis precision-grade machining redistributes competitive advantage toward systems integrators capable of controlling thermal deformation and spindle quality in-house.
Growth Catalysts
- Aerospace Manufacturing Mandates:Commercial aircraft programs in the United States and France require complex titanium and composite machining that only five-axis centers can deliver. Tier-1 suppliers are retrofitting facilities to meet Boeing and Airbus qualification standards.
- EU Machinery Directive Compliance:CE marking requirements are accelerating replacement cycles across Germany, Italy, and France as legacy equipment fails to meet updated safety and interoperability protocols for connected factory floors.
- CAD/CAM Integration:Machine shops are eliminating manual G-code programming through seamless design-to-manufacturing workflows. This technology pull is strongest among contract manufacturers serving medical device and automotive powertrain verticals.
Market Restraints
- High-Precision Ball Screw Supply Concentration:Japanese and German suppliers dominate the critical motion control components market, creating vulnerability for machine builders outside these geographies during capacity constraints.
- EPA Metalworking Fluid Standards:United States facilities face escalating compliance costs for coolant capture and disposal systems, compressing operating margins for mid-tier job shops.
- Technical Talent Scarcity:The intersection of mechanical engineering, software programming, and thermal systems expertise required for modern CNC operation outpaces vocational training pipeline output in most manufacturing economies.
Strategic Opportunities
- India Manufacturing Expansion:The country's PLI scheme for precision engineering and automotive components is creating first-time demand for mid-range vertical machining centers among domestic contract manufacturers.
- Adaptive Control Convergence:Real-time tool wear compensation algorithms are merging with industrial IoT platforms, enabling predictive maintenance revenue streams for equipment suppliers.
- Medical Device Micro-Machining:Orthopedic implant and surgical instrument manufacturers require sub-micron positional accuracy that opens premium pricing tiers for specialized Swiss-type lathe configurations.
Industry Challenges
- Servo Motor Tuning Expertise Gap:The shift from analog to digital drive architectures demands control engineers fluent in both mechanical dynamics and embedded software, a combination rarely found in legacy maintenance workforces.
- CE Marking Certification Timelines:European conformity assessment procedures for safety-related control systems extend product launch windows by 8-14 months, delaying revenue recognition for new machine introductions.
- Legacy DNC System Integration:Brownfield facilities running 1990s-era direct numerical control networks face prohibitive retrofit costs to achieve ISO 14649 interoperability with modern CAD/CAM suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNC Machine Market |
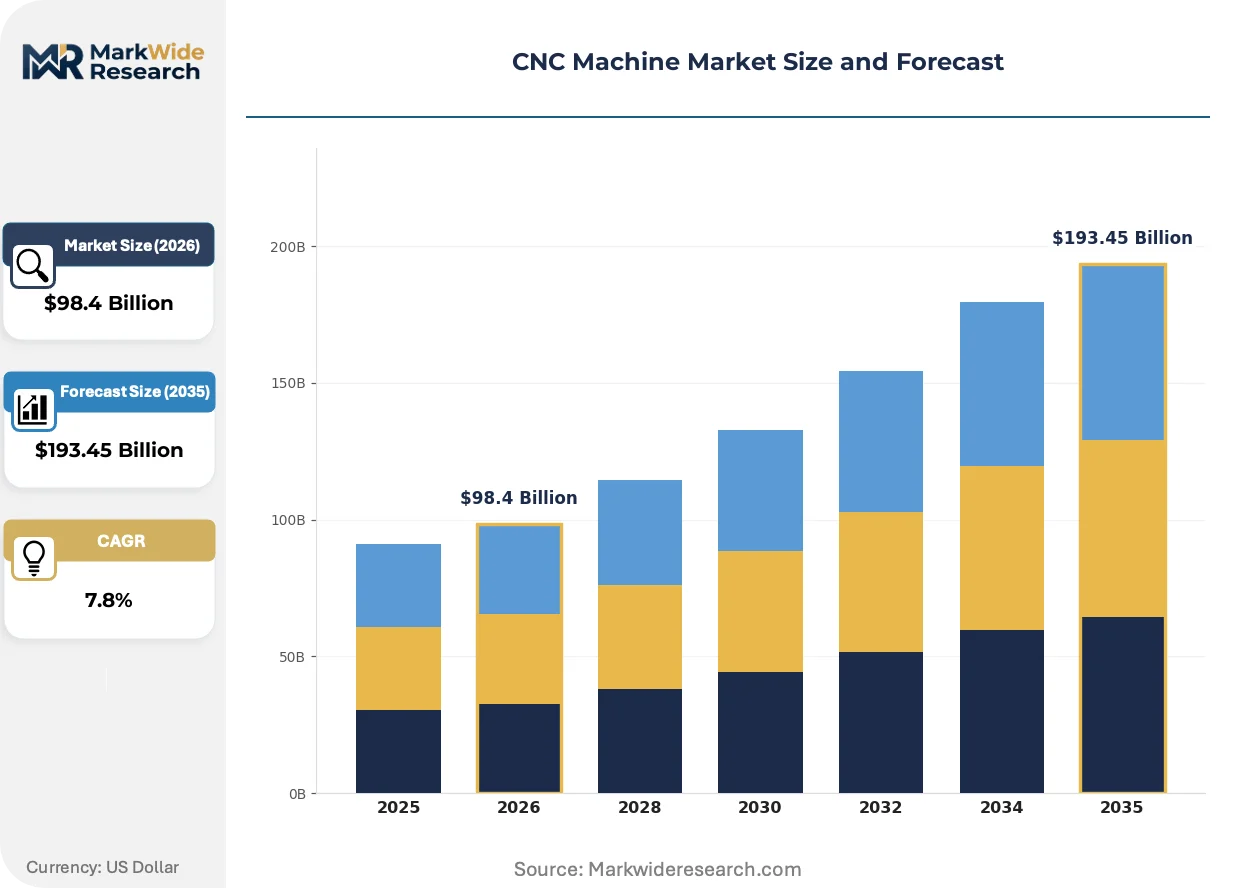
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $193.45 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Machining Centers, Horizontal Machining Centers, CNC Lathes, CNC Routers, CNC Plasma Cutters Technology: Computer Numerical Control, Direct Numerical Control, Adaptive Control, DNC Systems, CAD/CAM Integration Application: Aerospace Manufacturing, Electronics Fabrication, Tool & Die Making, Furniture Production, Jewelry Crafting End User: Machine Shops, OEM Manufacturers, Prototyping Centers, Contract Manufacturers, Research Laboratories |
| Companies Covered | Okuma, FANUC, DMG MORI, TRUMPF, Hurco, Mazak Corporation, Makino, Doosan, Haas Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNC Machine Market Strategic Shifts & Innovations
Control architecture decisions are becoming the primary battlefield for machine builders as openness standards collide with vendor ecosystem strategies and adaptive machining capabilities mature.
Linear motor direct-drive technology is miniaturizing the mechanical stack in high-speed milling applications. Japanese and Swiss machine tool builders are deploying these systems in medical device and watchmaking sectors where elimination of ball screw backlash enables sub-micron contouring accuracy. The structural consequence is compression of traditional mechanical transmission supply chains as electromagnetic solutions capture premium positioning.
Japan's METI smart factory standards are mandating OPC-UA connectivity and data dictionary uniformity for equipment receiving productivity subsidies. Machine builders serving the Japanese market must rearchitect control systems to expose spindle load, thermal drift, and tool life data in standardized formats. European and Korean suppliers are adapting identical protocols to maintain access to this high-specification demand pool.
After-sales service unbundling is disrupting traditional capital equipment economics. Aerospace and automotive OEMs are separating maintenance contracts from initial machine purchases, forcing builders to develop subscription-based predictive analytics offerings. This pattern is most visible in Germany and the United States, where fleet operators with 50+ unit installations possess sufficient scale to negotiate performance-based uptime agreements rather than fixed service retainers.
CNC Machine Market Segmentation
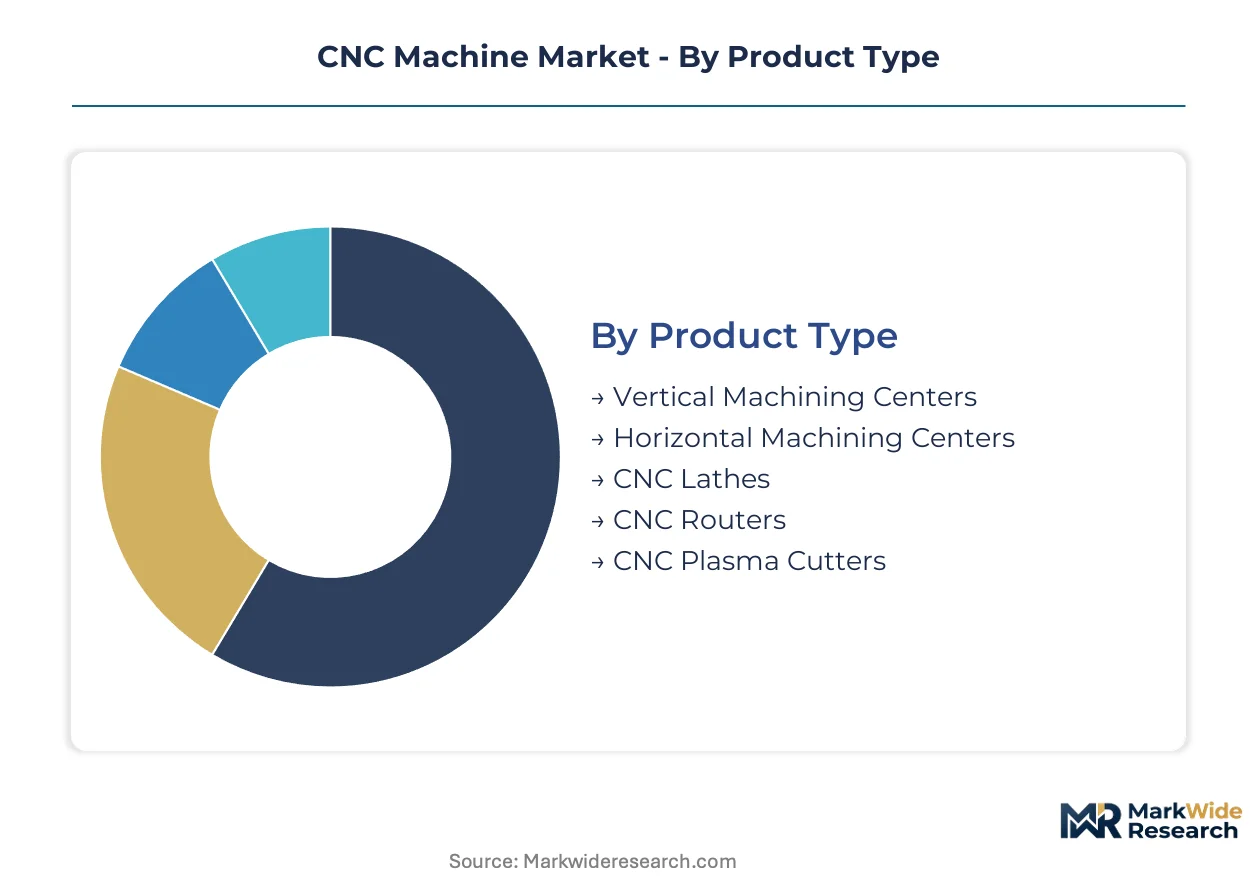
Segmentation in the CNC machine market reveals how regulatory compliance, precision requirements, and production scale reshape equipment selection across manufacturing verticals. Understanding these divisions exposes where capital allocation concentrates and where technology transitions create displacement risk.
Product Type:
CE marking under the EU Machinery Directive and Japan's METI smart factory standards impose divergent mechanical safety and connectivity requirements that favor certain configurations over others.
- Vertical Machining Centers:These configurations position the spindle vertically above the worktable, enabling gravity-assisted chip evacuation and simplified workpiece loading. General metalworking shops in Germany and the United States favor this format for its footprint efficiency and lower foundation requirements compared to horizontal alternatives. Demand concentrates among contract manufacturers serving automotive and medical device supply chains where batch flexibility outweighs dedicated throughput.
- CNC Lathes:Rotational workpiece machining dominates automotive powertrain production, delivering stronger margins through dedicated bar-feed automation and live tooling integration. Japanese and German OEM manufacturers specify these systems for crankshaft, camshaft, and transmission component manufacturing where concentricity tolerances fall below two microns.
- Horizontal Machining Centers:Pallet-based workpiece exchange enables uninterrupted machining during part loading cycles, prized by high-volume aerospace suppliers.
- CNC Routers:Gantry-based cutting systems serve furniture production and sign manufacturing with lower spindle speeds and softer material specialization.
- CNC Plasma Cutters:Thermal cutting via ionized gas streams dominates thick plate fabrication in steel service centers and heavy equipment manufacturing.
Established volume favors Vertical Machining Centers; emerging adoption favors CNC Lathes.
Technology:
Control architecture investments separate price tiers more sharply than mechanical specifications, with software openness commanding premium positioning.
- CAD/CAM Integration:Seamless design-to-manufacturing workflows eliminate manual G-code programming, compressing setup times from hours to minutes. Medical device and aerospace fabricators in France and the United States drive adoption as qualification protocols demand full process traceability from digital model to finished component.
- Computer Numerical Control:Conventional CNC with localized program storage and operator-mediated setup retains dominance in mid-tier job shops where capital constraints limit connectivity infrastructure investment. German and Italian machine builders optimize these systems for the European market's emphasis on standalone reliability over network integration.
- Adaptive Control:Real-time spindle load monitoring and automatic feed rate adjustment extend tool life in variable material conditions.
- Direct Numerical Control:Centralized program storage and distribution characterizes legacy installations in brownfield automotive facilities.
- DNC Systems:Networked program management enables distributed manufacturing control across multi-machine installations.
Legacy installed base concentrates in Computer Numerical Control; capability upgrade spending flows toward CAD/CAM Integration.
Application:
Precision mandates and material hardness dictate machine specification intensity across manufacturing verticals.
- Aerospace Manufacturing:Five-axis simultaneous machining of titanium and nickel superalloys for turbine blades and structural components demands thermal compensation systems and in-process probing. Boeing and Airbus qualification standards in the United States and France require specific machine configurations that exclude general-purpose equipment from Tier-1 supplier facilities.
- Electronics Fabrication:Miniaturized component machining for connectors, heat sinks, and enclosures requires high-speed spindles above 30,000 RPM and compact work envelopes. Japanese and South Korean semiconductor capital equipment suppliers specify Swiss-type lathes and micromachining centers for sub-millimeter feature production.
- Tool & Die Making:Hardened steel machining for injection molds and stamping dies prioritizes rigidity and surface finish over speed.
- Furniture Production:Wood and composite panel processing favors gantry routers with vacuum workholding and dust collection integration.
- Jewelry Crafting:Precious metal micromachining and engraving employ compact desktop CNC systems with specialized spindle control.
Capital intensity peaks in Aerospace Manufacturing; unit volume concentrates in Electronics Fabrication.
End User:
Purchasing authority and utilization patterns fragment demand between maintenance-driven replacement and capacity expansion investments.
- Contract Manufacturers:Job shop operators serving multiple industry verticals prioritize machine flexibility and rapid changeover capability over dedicated throughput. India's PLI scheme beneficiaries in precision engineering represent emerging demand concentration as domestic automotive and aerospace supply chains develop.
- OEM Manufacturers:Captive production facilities for automotive, aerospace, and industrial equipment specify dedicated transfer lines and high-volume horizontal machining centers. German and Japanese automotive powertrain plants demand 95%+ equipment availability with predictive maintenance integration.
- Machine Shops:Independent metalworking service providers balance equipment versatility against financing constraints in fragmented competitive environments.
- Prototyping Centers:Research and development facilities emphasize quick-turn programming and multi-axis capability for design iteration.
- Research Laboratories:Academic and government research installations prioritize experimental control and data acquisition over production efficiency.
Replacement cycles dominate Machine Shops; technology upgrade spending concentrates in Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine tool exports flow predominantly to aerospace suppliers in France and automotive powertrain facilities in the United States, establishing a transatlantic corridor for five-axis precision equipment.
United States
Boeing and Lockheed Martin qualification standards drive Tier-1 aerospace suppliers toward thermal-compensated machining centers. OSHA lockout/tagout regulations and EPA metalworking fluid standards reshape facility compliance investments. Seattle-Tacoma and Wichita clusters concentrate titanium machining capacity for commercial and defense aircraft programs.
Germany
Automotive OEM captive plants demand 95% equipment availability with predictive maintenance integration for powertrain component manufacturing. CE marking under the EU Machinery Directive accelerates replacement cycles as legacy equipment fails updated safety protocols. Stuttgart and Munich industrial corridors anchor high-precision vertical machining center demand from Bosch and Continental supplier networks.
Japan
Semiconductor capital equipment suppliers specify Swiss-type lathes and micromachining centers for sub-millimeter connector production. METI smart factory subsidies mandate OPC-UA connectivity and standardized data dictionaries for connected equipment. Nagoya and Osaka manufacturing belts concentrate FANUC servo motor integration with domestic machine builder supply chains.
India
PLI scheme beneficiaries in precision engineering create first-time demand for mid-range vertical machining centers among domestic contract manufacturers. BIS certification requirements and DGFT import duty structures influence equipment sourcing decisions. Pune and Chennai automotive clusters drive CNC lathe adoption for crankshaft and transmission component machining.
China
Domestic machine tool builders capture mid-tier demand as MIIT industrial upgrading policies prioritize import substitution in precision equipment. GB standards and SAMR certification timelines extend product launch windows for foreign suppliers. Yangtze River Delta manufacturing zones concentrate electronics fabrication demand for high-speed micromachining centers.
CNC Machine Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and control architecture openness, producing a tiered structure where scale-driven conglomerates face nimble configuration specialists. Japanese and German players dominate motion control component supply through captive spindle and servo motor production. Three archetypes define competitive positioning: vertically integrated precision specialists, modular platform builders, and regional cost-optimized fabricators. Consolidation pressure intensifies through strategic partnerships for CAD/CAM software integration and geographic expansion into India and Southeast Asia.
Among Japanese precision specialists, Okuma, FANUC, and DMG MORI exemplify contrasting strategic postures. Okuma occupies a position emphasizing thermo-friendly design compensation for thermal deformation during extended cutting cycles. FANUC anchors the control system and servo motor supply tier, supplying downstream machine builders across multiple geographies. DMG MORI represents vertical integration into in-house spindle production, enabling quality control across machining center portfolios.
| Leading Market Players |
|---|
| Okuma |
| FANUC |
| DMG MORI |
| TRUMPF |
| Hurco |
| Mazak Corporation |
| Makino |
| Doosan |
| Haas Automation |
| Others |
Cost & Logistics Intelligence
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation simultaneously, as certification timelines and safety protocol compliance separate premium European builders from cost-optimized Asian competitors while end-users absorb compliance premiums for qualified equipment.
Pricing Analysis
Five-axis precision-grade machining centers command substantial premiums over three-axis vertical configurations, while legacy DNC-controlled equipment trades at depreciation-driven discounts in secondary markets. Pricing stratifies across premium, standard, and economy tiers based on thermal compensation capability and servo motor control architecture. Cost compression in mid-range vertical machining centers is intensifying because contract manufacturers in India and Southeast Asia prioritize capital efficiency over connectivity features. OEM manufacturers demonstrate lowest price sensitivity, accepting extended payback periods for predictive maintenance integration.
Supply Chain Analysis
Japan and Germany anchor precision motion control component production, with THK, NSK, and Schaeffler dominating high-precision ball screw and linear guide supply. Machine builders draw from Japanese servo motor specialists, German spindle manufacturers, and Taiwanese casting suppliers for structural components. Single-source vulnerability concentrates in ceramic bearing supply for high-speed spindles above 30,000 RPM. Distribution runs through authorized dealer networks in developed markets and direct sales subsidiaries in emerging manufacturing economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CAD/CAM integration and adaptive control convergence represent technological inflection points reshaping competitive boundaries, while METI smart factory subsidies and EU Machinery Directive compliance deadlines compress decision windows for capital allocation.
For Market Incumbents: Secure captive spindle production capabilities to insulate margin structures from Japanese and German ball screw supply constraints. Invest in OPC-UA control architecture openness to defend against FANUC ecosystem lock-in among aerospace Tier-1 suppliers. Prioritize predictive maintenance subscription development as after-sales service unbundling accelerates in Germany and the United States.
For New Entrants and Emerging Players: Predictive analytics service gaps among legacy machine shop operators present white-space entry points where incumbents under-serve with traditional maintenance contracts. Target India's PLI scheme beneficiaries in precision engineering with mid-range vertical machining centers featuring simplified CAD/CAM interfaces. Pursue partnership-based go-to-market models with domestic distributors in Pune and Chennai automotive clusters.
For Investors and Strategic Acquirers: EU Machinery Directive recertification deadlines reshape the acquisition landscape toward distressed European machine builders with stalled CE marking pipelines. Five-to-ten-year viability favors specialists with thermo-friendly design IP and adaptive control software assets over commodity fabricators. Monitor BIS certification timeline announcements in India as inflection indicators for import substitution policy intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Production | DMG MORI's captive manufacturing insulates quality control from Japanese supply concentration. |
| Adaptive Control Software Development | Real-time tool wear algorithms enable subscription revenue streams from aerospace fleet operators. |
| OPC-UA Control Architecture Migration | METI subsidy compliance mandates standardized data dictionaries for Japanese market access. |
| Predictive Maintenance Platform Launch | German automotive OEMs negotiate performance-based uptime agreements for 50+ unit installations. |
| India Manufacturing Footprint Expansion | PLI scheme beneficiaries in precision engineering create first-time demand for mid-range equipment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and equipment shipment records. The research team conducted structured interviews with maintenance directors at automotive powertrain facilities, plant engineers at aerospace Tier-1 suppliers, OEM procurement teams at German and Japanese machine builders, and aftermarket service heads at distributor networks. Secondary validation drew from METI subsidy disclosure documents, EU Machinery Directive technical files, U.S. customs import records for machine tool components, and SEC filings from listed precision equipment manufacturers. Bottom-up unit shipment estimates triangulate against top-down capital expenditure surveys across manufacturing verticals.
Segmentation dimensions modeled include product type configuration, control technology generation, application vertical precision requirements, and end-user purchasing authority across the projection horizon. CAGRs derive from regression analysis of historical equipment replacement cycles, aerospace program ramp schedules, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate semiconductor capital equipment build rates and automotive powertrain platform transition timelines.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and METI smart factory subsidy frameworks; material policy shifts would require re-modeling of replacement cycle assumptions and connectivity investment trajectories. Specific risks that could revise projections include tariff restructuring affecting Japanese ball screw imports, sudden BIS certification requirement changes in India, and aerospace program delays altering five-axis demand concentration. Recalibration cycles align with material shifts in subsidy program renewals and major commercial aircraft production rate announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Excavator Augers Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Global Crane Market
Construction Equipment
Cold Planers Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Smart Crane Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Solar Pile Driving Equipment Market