
 Engineering Machinery Counterweight Iron Market | 2026-2036
Engineering Machinery Counterweight Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Machinery Counterweight Iron Market Insights
Foundry metallurgist availability is rotating toward scarcity across mature industrial bases, compressing production timelines for complex counterweight castings. FMGC (Farinia) leverages its European foundry network to sustain long-diameter ductile iron capacity for crane OEMs. Blackwood Engineering anchors UK and Middle Eastern supply through dedicated machining lines for construction equipment tiers. SIC Lazaro competes on Spanish-port proximity, reducing freight costs for Mediterranean crane system builders.
Engineering machinery counterweight iron denotes dense ferrous castings, typically 4.5–7.2 t/m³ specific gravity, produced via sand casting or centrifugal methods to offset tipping moments in mobile and stationary equipment. These components stabilize excavator booms, crane jibs, and material handler arms against dynamic load shifts during operation. Ductile iron grades command premium positioning where impact resistance and fatigue life determine equipment duty cycles, while gray iron occupies cost-sensitive agricultural machinery tiers. Construction Equipment applications concentrate volume demand, though Mining Equipment specifications are shifting toward alloy iron formulations for extreme-density requirements in limited-space machine envelopes.
EPA foundry MACT standards in the United States and REACH substance restrictions through ECHA constrain permissible alloying elements and binder chemistries in counterweight production. China's MEE enforces regional production caps that redirect casting capacity toward certified facilities serving heavy equipment OEMs. India's BIS certification mandates mechanical testing protocols for imported counterweight iron used in infrastructure equipment. Stakeholders must monitor evolving scrap metal traceability requirements, as carbon accounting pressures penetrate OEM procurement criteria and reshape supplier qualification timelines.
Market Dynamics
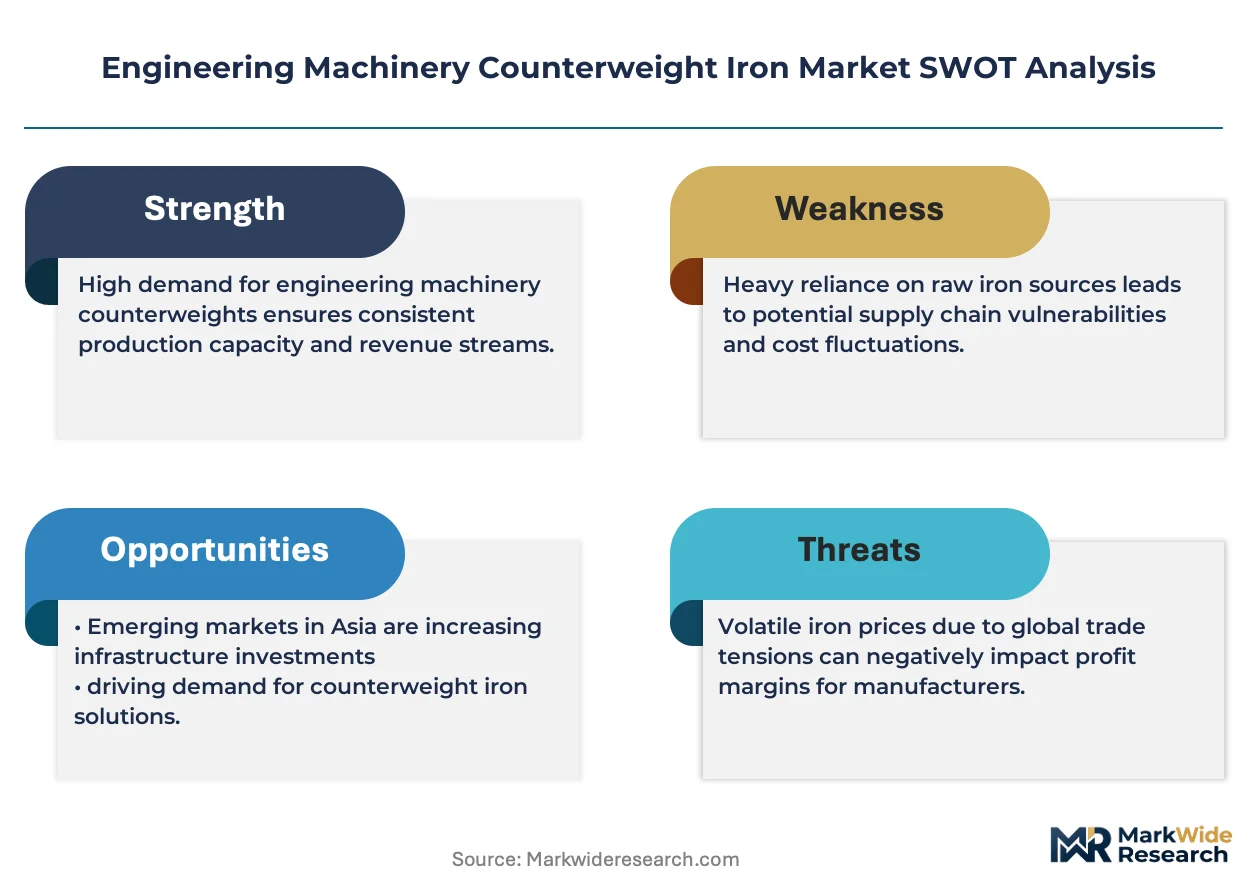
Foundry metallurgist scarcity across mature industrial bases compresses production timelines for complex counterweight castings, forcing OEMs to consolidate supplier relationships around certified facilities with proven ductile iron capacity.
Growth Catalysts
- Construction Equipment OEM Expansion:Machine tonnage ratings climb across excavator and crane portfolios, expanding counterweight procurement volumes from tier-one manufacturers.
- China's GB Standards Tightening:Foundry emissions and recycled content mandates redirect casting capacity toward certified facilities serving heavy equipment producers.
- Centrifugal Casting Methods:Advanced production techniques enable longer-diameter ductile iron components with superior fatigue life for high-duty cycle applications.
Market Restraints
- Scrap Metal Price Volatility:Ferrous feedstock cost swings compress margin predictability for sand-casting operations dependent on consistent alloy chemistry.
- East Asian Supply Concentration:Production gravity around Shanghai-Tangshan and Nagoya corridors creates freight cost penalties for European and North American OEMs.
- Gray Iron Substitution Ceiling:Cost-sensitive agricultural machinery tiers resist upgrading to ductile grades despite inferior impact resistance specifications.
Strategic Opportunities
- Mining Equipment Alloy Formulations:Extreme-density requirements in limited-space machine envelopes open premium positioning for specialized counterweight iron grades.
- Indian Infrastructure Build-Out:BIS certification protocols for imported counterweight iron create qualified supplier advantages for certified foundries.
- Carbon Accounting Integration:Scrap metal traceability requirements penetrating OEM procurement criteria reshape supplier qualification timelines toward low-carbon verified sources.
Industry Challenges
- Metallurgist Talent Pipeline Collapse:Foundry engineering programs at technical universities produce insufficient graduates to replace retiring specialists in sand-cast ductile iron operations.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with EPA foundry MACT standards, ECHA REACH substance restrictions, and China's MEE regional production caps extends qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Machinery Counterweight Iron Market |
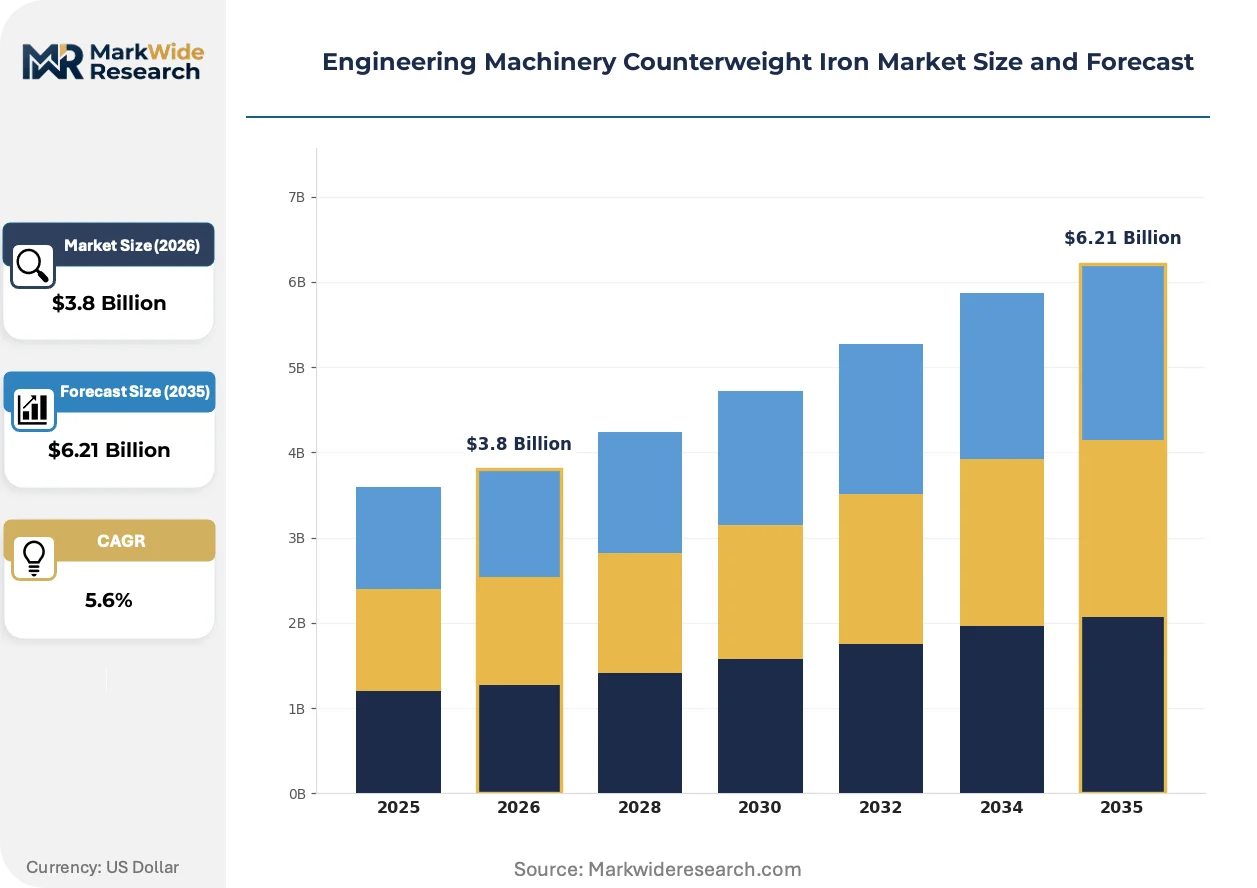
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Ductile Iron, Gray Iron, Malleable Iron, Alloy Iron Application: Construction Equipment, Material Handling, Agricultural Machinery, Mining Equipment, Crane Systems Manufacturing Stage: Raw Casting, Machining, Heat Treatment, Surface Finishing, Assembly End User Industry: Heavy Equipment OEMs, Rental Firms, Equipment Distributors, Contracting Companies |
| Companies Covered | FMGC (Farinia), Blackwood Engineering, SIC Lazaro, Gallizo, Mars Metal, Crescent Foundry, Max Iron, Swebor, Zunhua Wanxin Construction Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Machinery Counterweight Iron Market Trends and Innovations
Counterweight production is pivoting toward density-optimized formulations and digitally verified supply chains, with regulatory chemistry constraints and OEM carbon accounting requirements reshaping material specification protocols across construction and mining equipment tiers.
High-strength compacted graphite iron is supplanting conventional gray iron in mid-duty construction equipment counterweights. European crane OEMs now specify this grade for boom stabilization components where space constraints limit casting envelope dimensions. The material transition is compressing supplier qualification timelines as foundries retool melt chemistry controls to meet stricter nodularity requirements.
China's MEE regional production caps are reallocating foundry capacity toward heavy equipment OEMs with verified emission control systems. Domestic suppliers serving excavator manufacturers must demonstrate compliance with GB standards for particulate capture and recycled ferrous content. Tier-one construction equipment producers are consolidating procurement around MEE-certified facilities with integrated machining capabilities.
After-sales counterweight replacement cycles are compressing as equipment utilization rates climb in mining and material handling applications. Rental fleet operators now demand faster spare part turnaround from foundries with regional stocking agreements. This pattern is most visible in Australian and Chilean mining corridors where remote site logistics penalize long-lead procurement models.
Engineering Machinery Counterweight Iron Market Segmentation
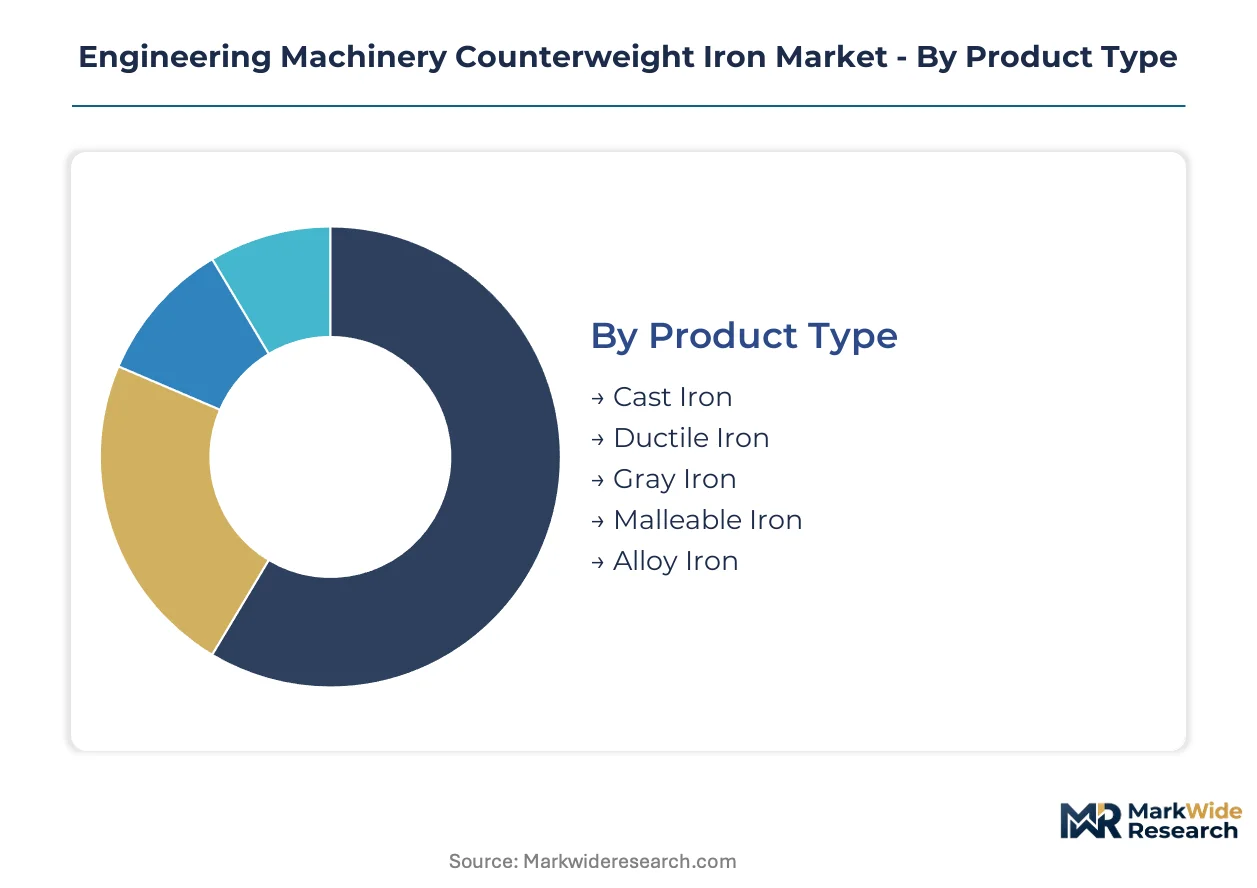
Counterweight iron procurement splits across metallurgical grades, equipment applications, and manufacturing stages. OEMs consolidate supplier relationships around certified foundries capable of spanning multiple segmentation dimensions simultaneously.
Product Type:
Margin pools concentrate in specialized iron grades where nodularity control and alloy chemistry command premium positioning against commodity gray iron alternatives.
- Ductile Iron:Spheroidal graphite microstructure delivers 4.5–7.2 t/m³ density with superior fatigue resistance for high-duty crane booms and excavator arms. Demand concentrates in European crane OEM supply chains where REACH substance restrictions favor compliant European foundry networks over Asian imports.
- Alloy Iron:Nickel-chromium or copper-alloyed formulations achieve extreme densities above 7.0 t/m³ for space-constrained mining equipment envelopes. Procurement is rotating toward certified facilities with integrated spectrographic testing capabilities as carbon accounting requirements penetrate OEM qualification protocols.
- Cast Iron:Generic ferrous casting category covering baseline counterweight specifications without nodularity requirements.
- Gray Iron:Flake graphite structure occupies cost-sensitive agricultural machinery tiers where impact resistance specifications remain minimal.
- Malleable Iron:Heat-treated white iron conversion yielding improved ductility for specialized material handler counterweight applications.
Ductile iron holds installed capacity across Shanghai-Tangshan and Nagoya manufacturing corridors. Alloy iron is rotating up the share rankings as mining equipment OEMs prioritize density-optimized formulations.
Application:
Volume distribution tracks equipment tonnage expansion cycles across construction and extractive industries.
- Construction Equipment:Excavator and loader counterweights dominate procurement volumes as machine ratings climb across 20-ton to 50-ton portfolios. OEMs in China face GB standards tightening that redirects casting capacity toward MEE-certified facilities with emission control verification.
- Crane Systems:Mobile and crawler crane counterweights require long-diameter ductile iron castings with precise dimensional tolerances for boom stabilization. European manufacturers leverage centrifugal casting methods to secure fatigue-rated components from specialized foundries.
- Mining Equipment:Extreme-density requirements in limited-space machine envelopes drive alloy iron specification upgrades.
- Material Handling:Reach stackers and container handlers require impact-resistant counterweight configurations for port operations.
- Agricultural Machinery:Gray iron persists in tractor ballast applications where cost sensitivity overrides performance specifications.
Construction equipment anchors procurement volumes across East Asian supply bases. Mining equipment is expanding most quickly as remote site logistics compress replacement cycle timelines.
Manufacturing Stage:
Supplier qualification timelines extend for foundries integrating downstream processing capabilities.
- Raw Casting:Sand-cast or centrifugally cast counterweight blanks require subsequent machining to achieve OEM dimensional specifications.
- Machining:CNC finishing lines transform rough castings to precision-matched counterweight assemblies for crane and excavator mounting interfaces.
- Heat Treatment:Stress relieving and annealing protocols stabilize casting dimensions for high-precision applications.
- Surface Finishing:Protective coating and shot blasting operations prepare counterweights for corrosive operating environments.
- Assembly:Modular counterweight stacking systems integrate multiple cast segments for adjustable machine configuration.
Machining capabilities differentiate tier-one suppliers from commodity foundries. Assembly integration is climbing the capability hierarchy as rental fleet operators demand faster field-configuration options.
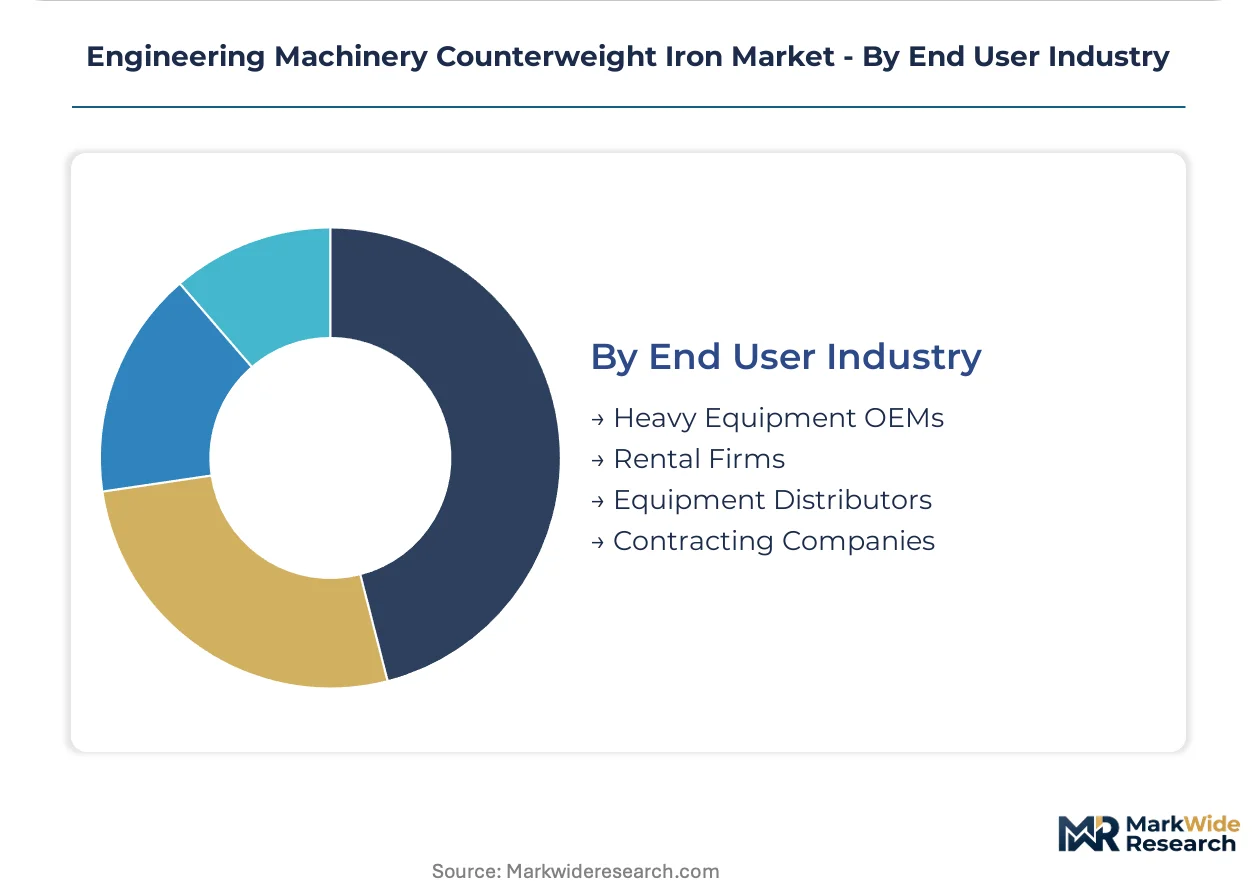
End User Industry:
Procurement authority concentrates in OEM engineering departments with direct foundry qualification oversight.
- Heavy Equipment OEMs:Direct counterweight specification authority resides with Caterpillar, Komatsu, and Sany engineering teams who audit foundry metallurgical controls. China's MEE regional production caps favor certified suppliers with integrated machining and emission verification.
- Rental Firms:United Rentals and similar fleet operators now specify aftermarket counterweight availability in OEM supply agreements. Australian and Chilean mining corridors drive fastest expansion in regional stocking requirements.
- Equipment Distributors:Regional dealers manage spare part procurement for legacy machine populations.
- Contracting Companies:Project-based operators purchase replacement counterweights through distributor channels.
Heavy equipment OEMs command specification authority through direct foundry relationships. Rental firms are gaining procurement influence through aftermarket availability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European foundries command 15-20% pricing premiums over East Asian suppliers for REACH-compliant ductile iron grades, while Chinese producers offset margin compression through integrated machining capabilities and Shanghai-Tangshan corridor logistics density.
China
Excavator OEMs Sany and XCMG expand counterweight procurement as machine tonnage ratings climb across 20-ton to 50-ton portfolios. MEE regional production caps redirect casting capacity toward certified facilities with verified emission control systems. The Shanghai-Tangshan industrial corridor anchors domestic supply, with Tangshan foundries consolidating around GB-standard compliance for particulate capture and recycled ferrous content mandates.
Germany
Liebherr and Sennebogen crane engineering teams specify long-diameter ductile iron castings with precise dimensional tolerances for boom stabilization. ECHA REACH substance restrictions constrain permissible alloying elements and binder chemistries in counterweight production. The Baden-Württemberg and North Rhine-Westphalia industrial regions host specialized foundries leveraging centrifugal casting methods for fatigue-rated components.
United States
Caterpillar and Deere engineering departments audit foundry metallurgical controls for construction equipment counterweight specifications. EPA foundry MACT standards enforce emission limits that compress qualified supplier pools. Midwest industrial corridors around Illinois and Ohio concentrate sand-casting capacity, though freight cost penalties persist for coastal OEMs sourcing from East Asian supply bases.
Japan
Komatsu and Hitachi Construction Machinery anchor procurement volumes for high-duty cycle excavator counterweights. METI industrial policy supports foundry modernization programs targeting ductile iron nodularity control. The Nagoya industrial corridor maintains specialized capacity for crane OEM supply chains, with JIS-standard mechanical testing protocols differentiating domestic from imported castings.
India
Domestic infrastructure build-out accelerates demand for imported counterweight iron in earthmoving equipment fleets. BIS certification mandates mechanical testing protocols that extend qualification timelines for foreign foundries. The Maharashtra and Gujarat industrial clusters concentrate casting capacity, though certified suppliers remain limited relative to procurement volume expansion.
Engineering Machinery Counterweight Iron Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Engineering Machinery Counterweight Iron Market. European foundries occupy premium positioning through REACH-compliant ductile iron grades and centrifugal casting capabilities, while East Asian producers compete on integrated machining scale and corridor logistics density. The market structures around three archetypes: metallurgical specialists with certified emission controls, vertically integrated construction equipment suppliers, and regional machining-focused fabricators. Capacity consolidation and carbon accounting qualification represent the dominant competitive moves reshaping supplier-OEM relationships.
Among European metallurgical specialists, FMGC (Farinia) and SIC Lazaro exemplify the certified-ductile-iron tier serving crane OEM supply chains. Blackwood Engineering occupies a position within the machining-integrated fabricator archetype, anchoring UK and Middle Eastern supply through dedicated production lines. These three companies represent contrasting geographic and capability positioning within a market where foundry certification and downstream processing integration determine procurement access.
| Leading Market Players |
|---|
| FMGC (Farinia) |
| Blackwood Engineering |
| SIC Lazaro |
| Gallizo |
| Mars Metal |
| Crescent Foundry |
| Max Iron |
| Swebor |
| Zunhua Wanxin Construction Machinery |
| Others |
Pricing and Supply Chain Analysis
MEE regional production caps in China gate both supply qualification and price differentiation simultaneously, as only certified foundries with verified emission control systems gain procurement access from tier-one construction equipment OEMs. This regulatory filter compresses the qualified supplier pool while enabling certified facilities to command premiums for ductile iron grades with integrated machining capabilities.
Pricing Analysis
Configured-to-order pricing for customized ductile iron counterweights with specific nodularity requirements and dimensional tolerances commands substantial premiums over standard gray iron commodity grades. Price differentiation rests on certification tier and geographic delivery cost, with REACH-compliant European foundries capturing 15-20% premiums against East Asian imports. Cost compression in gray iron agricultural tiers is intensifying because cost-sensitive buyers resist upgrading to ductile grades despite inferior impact resistance. Heavy equipment OEMs exhibit lowest price sensitivity due to duty cycle reliability requirements, while rental fleet operators show highest sensitivity for aftermarket replacement volumes.
Supply Chain Analysis
Strategic stockpiling of ferrous scrap feedstock dominates inventory strategy across sand-casting operations, insulating margin predictability against commodity price swings that would cripple just-in-time raw material sourcing. Supply concentrates in China, Germany, and Japan, with the Shanghai-Tangshan and Nagoya industrial corridors anchoring global ductile iron capacity. Raw material dependencies center on ferrous scrap, nodulizing alloys, and resin binder chemistries constrained by REACH and EPA MACT substance restrictions. Single-source vulnerability permeates long-diameter centrifugal casting capacity for crane OEMs. Distribution runs through direct OEM foundry relationships with integrated machining and regional stocking agreements for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting integration across OEM procurement protocols signals a platform-economics inflection, as scrap metal traceability requirements and verified low-carbon sourcing reshape supplier qualification into an interoperable certification ecosystem.
For Market Incumbents: Shield certified ductile iron capacity through backward integration into spectrographic testing and emission control verification systems. Consolidate machining capabilities in MEE-certified facilities to defend against emerging alloy iron specialists capturing mining equipment premium tiers. Prioritize carbon accounting qualification as the priority lever for long-term OEM retention.
For New Entrants and Emerging Players: Anchor in Indian infrastructure build-out corridors where BIS certification protocols create qualified supplier advantages for certified foundries with mechanical testing capabilities. Target alloy iron formulations for space-constrained mining equipment envelopes as the most penetrable premium segment. Pursue joint development agreements with regional crane system builders seeking Mediterranean or Middle Eastern supply proximity.
For Investors and Strategic Acquirers: China's MEE regional production caps reshapes the acquisition landscape toward certified facilities with integrated emission controls and machining capabilities. Long-term viability favors metallurgical specialists with proven ductile iron nodularity control and centrifugal casting capacity across the analysis window. Watch for carbon accounting verification becoming mandatory in OEM procurement criteria as the inflection signal for portfolio rebalancing toward low-carbon verified sources.
| Strategic Initiative | Industry Significance |
|---|---|
| MEE Certification Investment | Unlocks procurement access from Sany and XCMG engineering teams in China. |
| Centrifugal Casting Capacity Expansion | Secures fatigue-rated component supply for Liebherr crane boom stabilization. |
| Scrap Metal Traceability Integration | Aligns supplier qualification with Caterpillar carbon accounting protocols. |
| Regional Stocking Agreement Network | Compresses replacement cycle timelines for Australian mining corridor operators. |
| Alloy Iron Formulation Development | Captures premium positioning in Komatsu extreme-density mining equipment. |
Research Methodology
The analysis maps ductile iron grades, alloy iron formulations, gray iron commodity tiers, and compacted graphite iron transitions, each validated through foundry metallurgists, OEM procurement directors, rental fleet operators, and aftermarket service heads. Primary fieldwork combined structured interviews with secondary validation against customs trade data, GB standards documentation, SEC equipment manufacturer filings, and foundry emission registry disclosures. Bottom-up casting volume estimates triangulated against top-down construction and mining equipment production forecasts.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled metallurgical grade, equipment application, manufacturing stage, and end-user industry segmentation dimensions. CAGRs derived from equipment tonnage expansion cycles, regulatory capacity reallocation effects, and replacement cycle compression patterns in remote mining corridors.
Material uncertainties — scrap metal price volatility, metallurgist talent pipeline collapse, multi-jurisdiction certification burden extensions — sit outside the modeled envelope. Forecasts reflect assumptions regarding MEE enforcement continuity, REACH substance restriction stability, and OEM carbon accounting adoption trajectories. Revision becomes warranted when carbon accounting verification crosses mandatory thresholds in tier-one procurement protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market