
 Vietnam Prefabricated Buildings Market | 2026-2036
Vietnam Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Prefabricated Buildings Market Insights
Aftermarket service revenue for structural maintenance and component replacement is rewriting profit allocation across the Vietnam prefabricated buildings value chain. Zamil Steel Buildings Vietnam leverages its regional fabrication network to dominate heavy industrial envelope systems. ATAD Steel Structure Corp. sustains competitive intensity through specialized high-rise steel framing capabilities. TLC Modular differentiates by occupying the export-oriented modular residential segment serving regional hospitality developers.
Prefabricated buildings in Vietnam comprise factory-manufactured structural assemblies—typically steel frames with 50-150 mm insulated metal panels or precast concrete elements—engineered for rapid on-site erection within 30-90 days versus conventional 6-12 month construction cycles. These systems primarily serve industrial warehousing, commercial offices, and institutional facilities where capital velocity and labor scarcity constrain traditional building methods. Steel material systems lead volume adoption due to established domestic rolling capacity and cost transparency, while modular construction methods exhibit the fastest trajectory as hospitality and healthcare developers prioritize repeatable unit designs. Panelized methods retain mature share in low-rise commercial applications where design flexibility outweighs standardization benefits.
Vietnam's Ministry of Construction enforces National Technical Standards on fire resistance ratings and seismic design categories that prefabricated systems must satisfy for commercial occupancy permits. The country's national construction quality inspection regime under provincial departments of construction mandates third-party structural certification for imported steel components, shaping supplier qualification requirements. BIS-equivalent material testing protocols for welded connections and corrosion protection coatings further filter market access for international fabricators. Stakeholders must monitor evolving green building certification adoption by state-owned developers and the pace of digital permitting integration across provincial construction management offices.
Market Dynamics
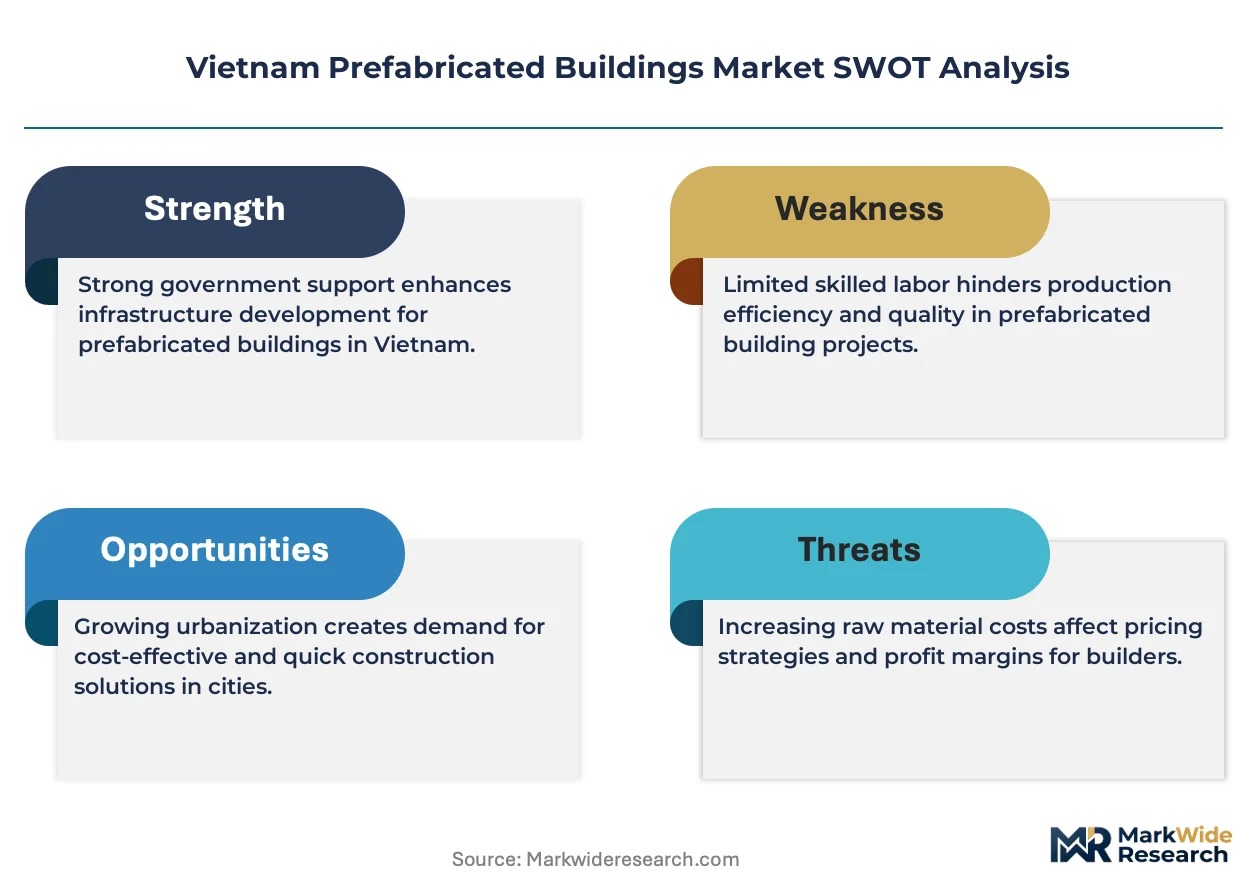
Vietnam's tightened fire safety and seismic construction codes under the Ministry of Construction are forcing rapid certification upgrades across the prefabricated buildings supply chain. These regulatory pressures compress project timelines while elevating technical barriers for fabricators serving warehouse and logistics developers.
Growth Catalysts
- E-commerce fulfillment networks:Warehouse developers across northern and southern industrial zones demand rapid-assembly structures to match 30-90 day construction cycles against conventional 6-12 month alternatives.
- Ministry of Construction seismic standards:Mandatory structural certification requirements filter out low-capability suppliers, concentrating procurement among qualified fabricators with proven welded connection testing.
- Binh Duong province manufacturing expansion:Infrastructure congestion around Ho Chi Minh City peripheries favors prefabricated methods that minimize on-site labor and material staging.
Market Restraints
- Structural steel price volatility:Domestic rolling capacity constraints expose developers to input cost swings that erode fixed-price contract viability.
- Imported component certification friction:Third-party structural verification for foreign-sourced steel assemblies adds 4-8 week procurement delays.
- Concrete panel substitution:Precast concrete retains cost advantage in low-rise commercial applications where thermal mass outweighs steel's speed benefits.
Strategic Opportunities
- Central Highlands hospitality corridor:Modular residential units for resort developers remain underpenetrated relative to industrial heartlands.
- Green building certification adoption:State-owned developer mandates for sustainable construction create specification pull for insulated metal panel systems with verified embodied carbon data.
- Digital permitting integration:Provincial construction management offices piloting electronic approval workflows reward fabricators with pre-validated design libraries.
Industry Challenges
- Welding certification scarcity:Qualified structural welders for seismic-grade connections command 40-60% wage premiums, constraining fabrication throughput.
- Legacy foundation integration:Existing industrial sites with conventional footings require costly structural adaptation for prefabricated superstructure mounting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Prefabricated Buildings Market |
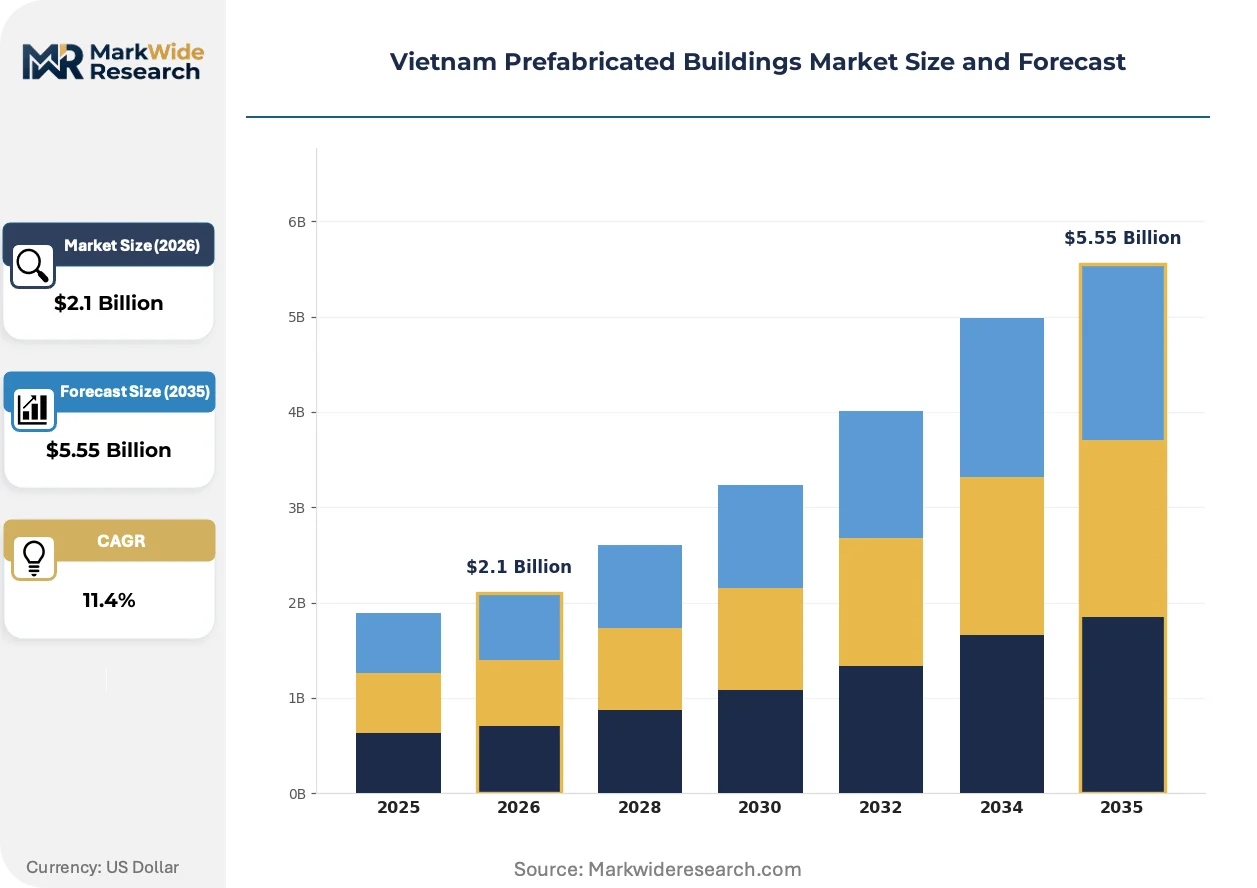
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Industrial, Institutional Material: Steel, Concrete, Wood, Composite Construction Method: Modular, Panelized, 3D Printing, Hybrid End User: Developers, Contractors, Government, Non-Profit |
| Companies Covered | Zamil Steel Buildings Vietnam, ATAD Steel Structure Corp., BMB Steel, Dai Dung Metallic Structure, Hoa Binh Construction Group, Coteccons Construction, VinGroup, TLC Modular, Smart Modular Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Prefabricated Buildings Market Trends and Innovations
Building information modeling and automated fabrication workflows are compressing design-to-erection timelines for Vietnamese industrial developers. These digital threads reshape competitive differentiation around speed and customization rather than pure material cost.
Parametric design software is digitizing structural steel detailing for warehouse envelope systems, enabling real-time clash detection before fabrication begins. Logistics facility developers in Dong Nai and Long An provinces now mandate BIM deliverables as standard procurement terms. This capability compression is eliminating rework costs that previously consumed 8-12% of project contingencies.
Vietnam's Ministry of Construction revised National Technical Standards on fire resistance ratings now require 90-minute rated assemblies for commercial occupancy. Prefabricated panel manufacturers must retest product lines under BIS-equivalent protocols to maintain market access. Heavy industrial envelope suppliers face the steepest compliance recalibration as their legacy 60-minute systems no longer qualify for new warehouse permits.
Developer procurement teams now unbundle after-sales structural maintenance from initial construction contracts, creating standalone service revenue streams. Third-party inspection firms capture recurring contracts for welded connection monitoring across Binh Duong manufacturing zones. This service-layer separation is most visible among Japanese and Korean capital sources operating in northern industrial provinces.
Vietnam Prefabricated Buildings Market Segmentation
Segmentation reveals how prefabricated building procurement diverges across buyer priorities—speed versus customization, capital efficiency versus design flexibility, and regulatory compliance versus cost minimization. Each dimension shapes supplier qualification requirements and margin structures differently across Vietnam's northern and southern industrial corridors.
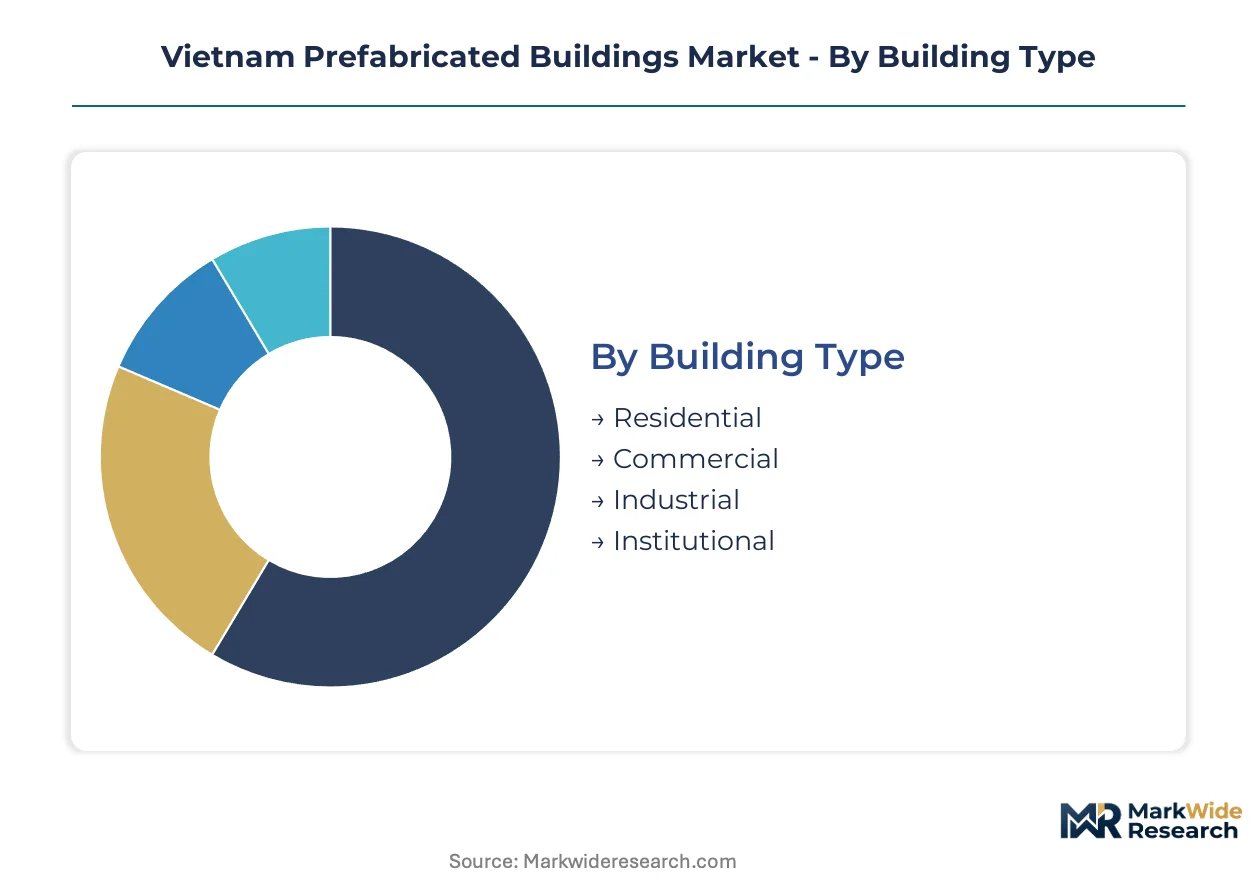
Building Type:
Industrial warehousing commands procurement volume through e-commerce fulfillment network expansion, while residential modular construction accelerates through hospitality corridor development.
- Residential:Modular units for resort developments in the Central Highlands and coastal hospitality zones prioritize repeatable room configurations with 30-day installation cycles. TLC Modular dominates this segment through export-oriented production serving regional hotel operators in Da Nang and Phu Quoc.
- Commercial:Low-rise office and retail structures in Ho Chi Minh City peripheries favor panelized steel systems where design flexibility outweighs standardization benefits. Binh Duong province accounts for the densest concentration of commercial prefabricated builds outside the core metropolitan area.
- Industrial:Warehouse and logistics facilities represent the fastest-expanding buyer segment as northern and southern industrial zones multiply fulfillment infrastructure.
- Institutional:Schools and healthcare facilities face stringent Ministry of Construction fire resistance mandates that filter procurement toward certified heavy envelope suppliers.
The dominant share belongs to Industrial, while Residential is closing the gap fastest.
Material:
Cost tiers separate premium corrosion-resistant systems from standard domestic rolling stock, with thermal performance requirements driving specification divergence.
- Steel:Structural steel frames with 50-150 mm insulated metal panels dominate volume adoption due to established domestic rolling capacity and cost transparency. Zamil Steel leverages regional fabrication networks to capture heavy industrial envelope contracts across Dong Nai and Long An provinces.
- Concrete:Precast concrete elements retain cost advantage in low-rise commercial applications where thermal mass outweighs steel's speed benefits, particularly in legacy foundation integration scenarios.
- Wood:Engineered timber systems face moisture resistance constraints in Vietnam's tropical climate, limiting penetration to boutique hospitality projects seeking aesthetic differentiation.
- Composite:Fiber-reinforced polymer panels command premium positioning for corrosive industrial environments in coastal manufacturing zones.
Steel maintains structural dominance, though Composite is expanding most quickly in specialized industrial niches.
Construction Method:
Volume concentration favors established panelized workflows, while emerging methods reshape competitive differentiation around digital design-to-fabrication integration.
- Modular:Factory-complete volumetric units enable 30-90 day project delivery versus conventional 6-12 month cycles, with strongest traction in hospitality and healthcare repeatable designs. ATAD Steel Structure Corp. sustains positioning through high-rise steel framing capabilities that extend modular methods vertically.
- Panelized:Factory-manufactured wall and roof assemblies retain mature share where on-site customization remains necessary for irregular footprints or existing foundation constraints.
- 3D Printing:Additive construction methods remain experimental in Vietnam, with pilot projects concentrated in research partnerships rather than commercial deployment.
- Hybrid:Combined modular-panelized approaches optimize material efficiency for complex industrial facilities requiring both speed and structural adaptation.
Panelized methods hold the largest installed base, yet Modular is gaining share fastest through hospitality developer adoption.
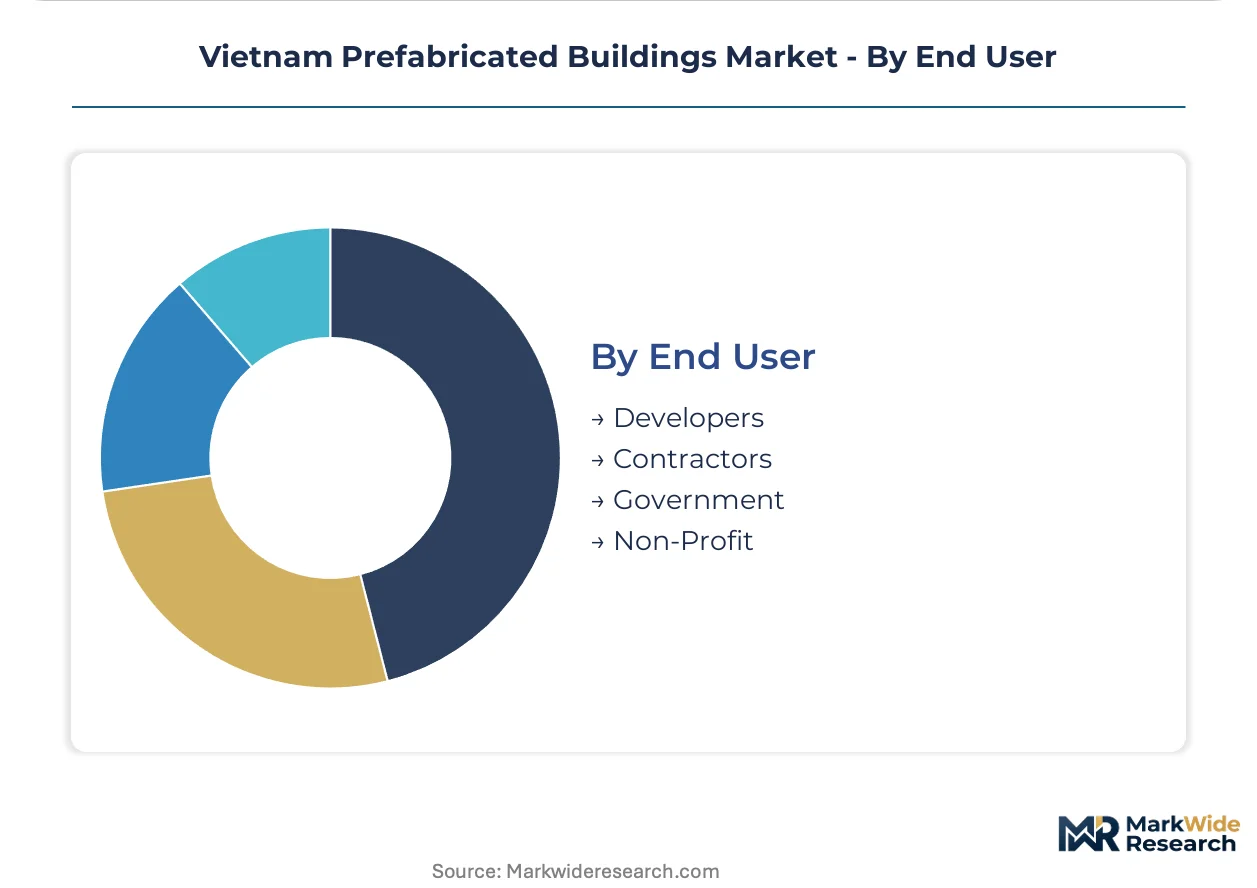
End User:
Customer type determines procurement sophistication—institutional buyers mandate certified compliance while private developers prioritize capital velocity.
- Developers:Warehouse and logistics facility developers drive fastest segment expansion through rapid-assembly requirements for e-commerce fulfillment networks across northern and southern zones.
- Contractors:General construction firms adopt prefabricated superstructures to offset qualified welder scarcity and compress project timelines amid labor cost inflation.
- Government:State-owned developers increasingly specify green building certification requirements, creating specification pull for insulated metal panel systems with verified embodied carbon data.
- Non-Profit:Social housing and community facility developers face capital constraints that favor lowest-first-cost panelized solutions over performance-optimized alternatives.
Developers command the dominant procurement volume, while Government buyers are expanding specifications most rapidly through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters around Ho Chi Minh City and Hanoi, with provincial construction departments enforcing divergent certification timelines. Binh Duong and Dong Nai provinces concentrate heavy industrial envelope production, while northern industrial zones around Hai Phong and Bac Ninh serve Korean and Japanese capital sources.
Ho Chi Minh City Periphery
Logistics facility developers in Dong Nai and Long An provinces drive warehouse construction demand. The Ministry of Construction's seismic design categories filter procurement toward certified fabricators with proven welded connection testing. Binh Duong province hosts the densest concentration of commercial prefabricated builds outside the metropolitan core.
Hanoi and Northern Industrial Corridor
Korean and Japanese manufacturing investors in Bac Ninh and Hai Phong provinces specify rapid-assembly structures for production facilities. Provincial departments of construction mandate third-party structural certification for imported steel components, adding procurement delays. Hai Phong's port infrastructure supports steel import flows serving northern fabrication networks.
Central Highlands Hospitality Zone
Resort developers in Da Lat and surrounding provinces adopt modular residential units for repeatable room configurations. The Ministry of Construction's fire resistance ratings apply uniformly, though enforcement capacity varies across provincial offices. Da Nang serves as the logistics hub for coastal hospitality projects in Quang Nam and Thua Thien-Hue provinces.
Mekong Delta Industrial Fringe
Food processing and light manufacturing investors in Can Tho and An Giang provinces represent emerging demand pockets. National Technical Standards on commercial occupancy permits apply, but qualified fabricator presence remains thinner than in northern and southern cores. Long An province bridges this zone to Ho Chi Minh City's supplier base.
Central Coast Manufacturing Belt
Textile and footwear producers in Quang Nam and Binh Dinh provinces expand production facilities using panelized methods. Provincial construction management offices pilot digital permitting workflows that reward fabricators with pre-validated design libraries. This corridor remains underpenetrated relative to the dominant northern and southern industrial zones.
Vietnam Prefabricated Buildings Market Competitive Landscape
Regional steel fabricators and specialized modular constructors split the market along speed-versus-customization lines. The vendor base organizes around three archetypes: heavy industrial envelope suppliers with regional fabrication networks, high-rise steel framing specialists, and export-oriented modular residential producers. Competitive intensity concentrates on certification maintenance under tightening Ministry of Construction standards and aftermarket service unbundling.
Within the heavy industrial tier, Zamil Steel Buildings Vietnam anchors regional envelope supply through fabrication network scale. ATAD Steel Structure Corp. occupies positioning around high-rise steel framing capabilities. TLC Modular exemplifies the export-oriented modular segment serving hospitality developers. These three represent distinct strategic archetypes rather than direct substitutes, with procurement patterns diverging across warehouse, commercial, and residential end uses.
| Leading Market Players |
|---|
| Zamil Steel Buildings Vietnam |
| ATAD Steel Structure Corp. |
| BMB Steel |
| Dai Dung Metallic Structure |
| Hoa Binh Construction Group |
| Coteccons Construction |
| VinGroup |
| TLC Modular |
| Smart Modular Vietnam |
| Others |
Pricing and Supply Chain Analysis
China's structural steel rolling capacity concentration anchors input cost volatility that reshapes margin capture across Vietnamese prefabricated building tiers. Domestic fabricators with captive galvanizing lines command pricing power over importers exposed to BIS-equivalent certification delays and ocean freight swings.
Pricing Analysis
Ministry of Construction fire resistance mandates dictate the pricing tier structure across commercial and industrial segments. Three-tier pricing structure across premium certified, standard compliant, and economy non-rated levels separates Zamil Steel's heavy envelope systems from regional fabricators serving low-rise commercial. Price differentiation rests on seismic-grade welding certification and after-sales structural maintenance bundling. Cost compression in the economy tier is intensifying because precast concrete substitutes erode steel's speed premium in legacy foundation scenarios. Non-profit social housing developers exhibit highest price sensitivity; Japanese and Korean capital sources in northern provinces show lowest.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk calculus for structural steel inputs. Geographic supply concentration centers on China for hot-rolled coil, South Korea for high-tensile beam sections, and domestic mills in Thai Nguyen and Ba Ria-Vung Tau provinces. Raw material dependencies hinge on zinc for corrosion protection coatings, mineral wool for fire-rated insulation cores, and epoxy primers for coastal durability. Single-source vulnerability persists in seismic-grade welding consumables qualified under Ministry of Construction protocols. Distribution runs through provincial construction material depots in Binh Duong and Dong Nai with direct-to-site logistics for time-sensitive warehouse developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehouse and logistics developer consolidation around e-commerce fulfillment networks is shifting procurement power toward volume buyers capable of demanding turnkey service bundles and extended warranty terms.
For Market Incumbents: Entrench certification advantages by deepening in-house production of seismic-grade welded connections before Ministry of Construction standards tighten further. Add capacity in Long An province to intercept Mekong Delta demand before qualified fabricator presence thickens. Control channel access through exclusive service contracts with third-party inspection firms monitoring Binh Duong manufacturing zones.
For New Entrants and Emerging Players: Build out modular residential production targeting Central Highlands hospitality corridors where TLC Modular's export focus leaves domestic resort developers underserved. Penetrate the institutional healthcare segment through repeatable patient room configurations that satisfy 90-minute fire resistance mandates. Enter via design-build partnerships with provincial construction management offices piloting digital permitting workflows.
For Investors and Strategic Acquirers: Capital is best deployed toward heavy industrial envelope suppliers with pre-validated BIM design libraries and established aftermarket service revenue streams. Long-term viability favors fabricators integrating parametric detailing capabilities with regional galvanizing assets. Watch green building certification adoption by state-owned developers as the signal indicating specification pull acceleration for insulated metal panel systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Certification Investment | Ministry of Construction mandates filter procurement toward qualified fabricators with proven welded connection testing. |
| Backward Integration into Galvanizing | Captive corrosion protection coating capacity insulates margin from zinc price volatility and import certification friction. |
| Digital Permitting Integration | Pre-validated BIM design libraries reward fabricators with faster approval workflows across provincial construction offices. |
| Aftermarket Service Unbundling | Standalone structural maintenance contracts create recurring revenue streams from Japanese and Korean capital sources. |
| Central Highlands Geographic Expansion | Modular residential production in Da Nang corridor captures hospitality developer demand outside industrial heartlands. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with steel fabrication plant managers, warehouse developer procurement leads, provincial construction department officials, and third-party structural inspection firms; and secondary validation through Ministry of Construction technical circulars, BIS-equivalent material testing protocols, customs trade data on steel imports, and provincial construction permit databases. Bottom-up project pipeline assessment triangulated against top-down macroeconomic construction spend indicators.
Forecast inputs considered building type segmentation, material system tiers, construction method adoption curves, and end-user procurement sophistication across the projection horizon. CAGRs were derived from regression analysis of historical permit issuance against industrial zone expansion timelines. Modeled variables included e-commerce fulfillment network capex cycles, seismic code compliance cost pass-through rates, and green building certification penetration among state-owned developers.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment by Chinese-backed entrants or sudden Ministry of Construction standard acceleration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Oman Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Australia Construction Market
Building Construction
GCC Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
El Salvador Construction Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Eastern Europe Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Africa Construction Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
China Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
Malaysia Construction Market