
 Americas Hydraulic Submersible Pumps Market | 2026-2036
Americas Hydraulic Submersible Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Hydraulic Submersible Pumps Market Outlook
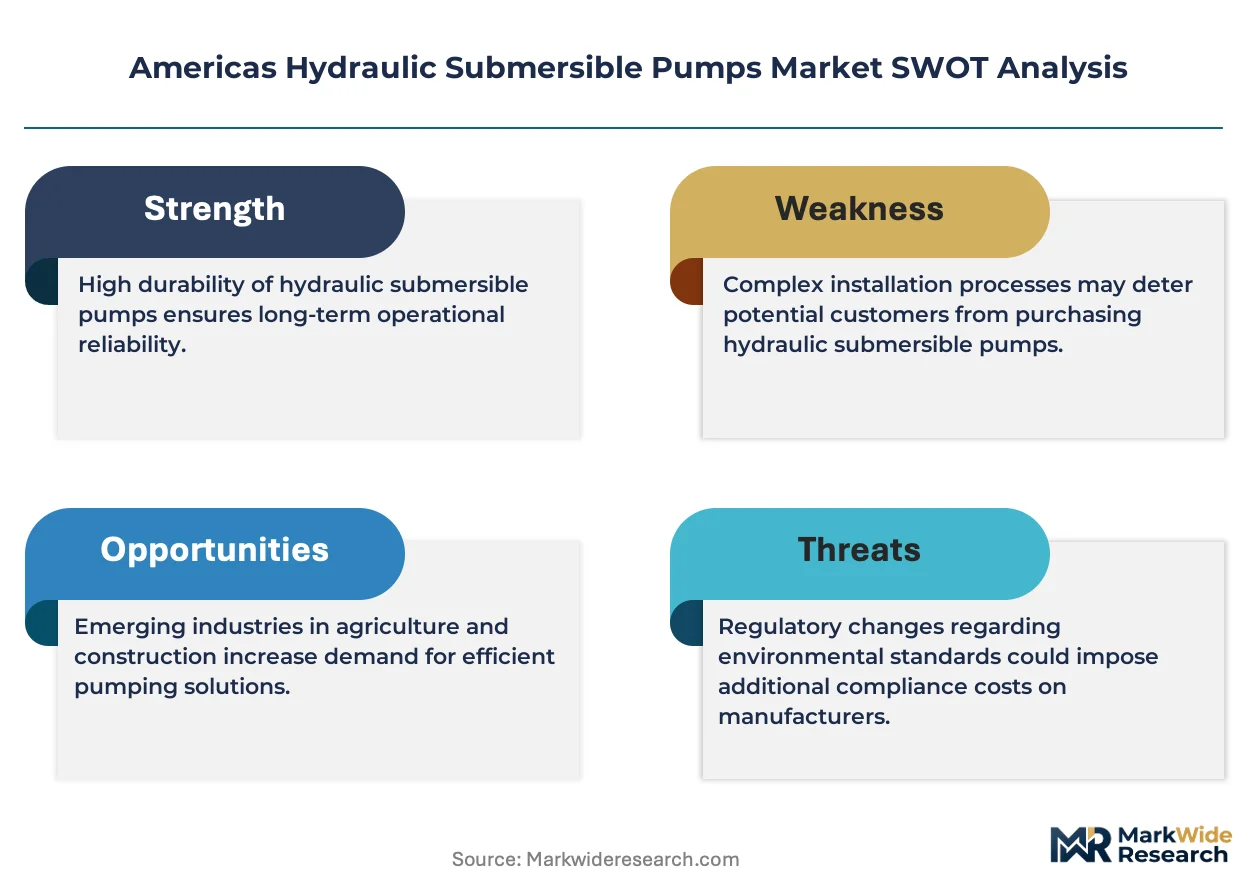
EPA effluent limitation guidelines is expanding the cost-of-entry calculus for pump manufacturers serving North American wastewater utilities. Xylem Inc. leverages its vertical integration across pump systems and digital monitoring platforms to sustain pricing power in municipal contracts. Griffin Dewatering Corporation anchors its position through specialized rental fleets deployed across U.S. construction and mining sites. Sulzer Ltd. competes by concentrating engineering resources on abrasion-resistant hydraulic designs for oil sands applications.
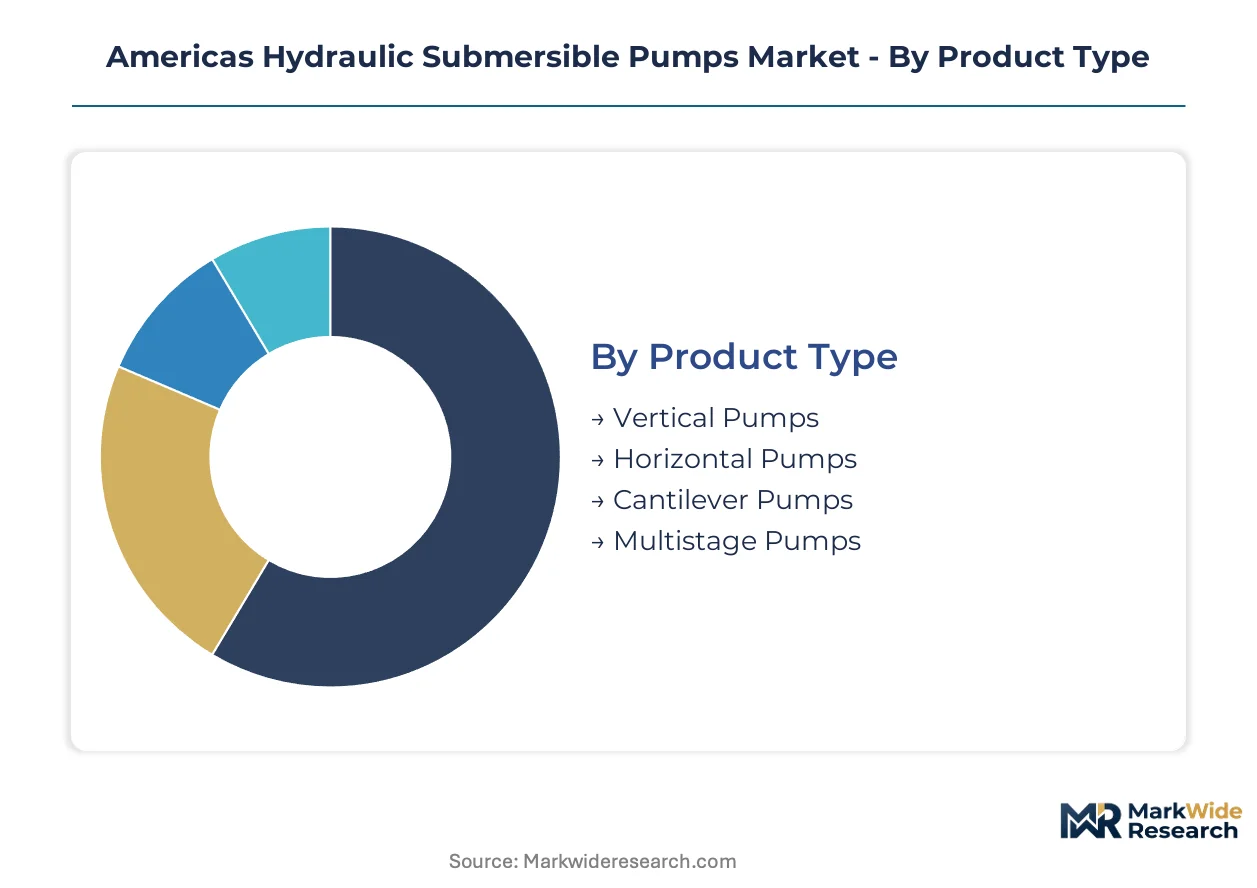
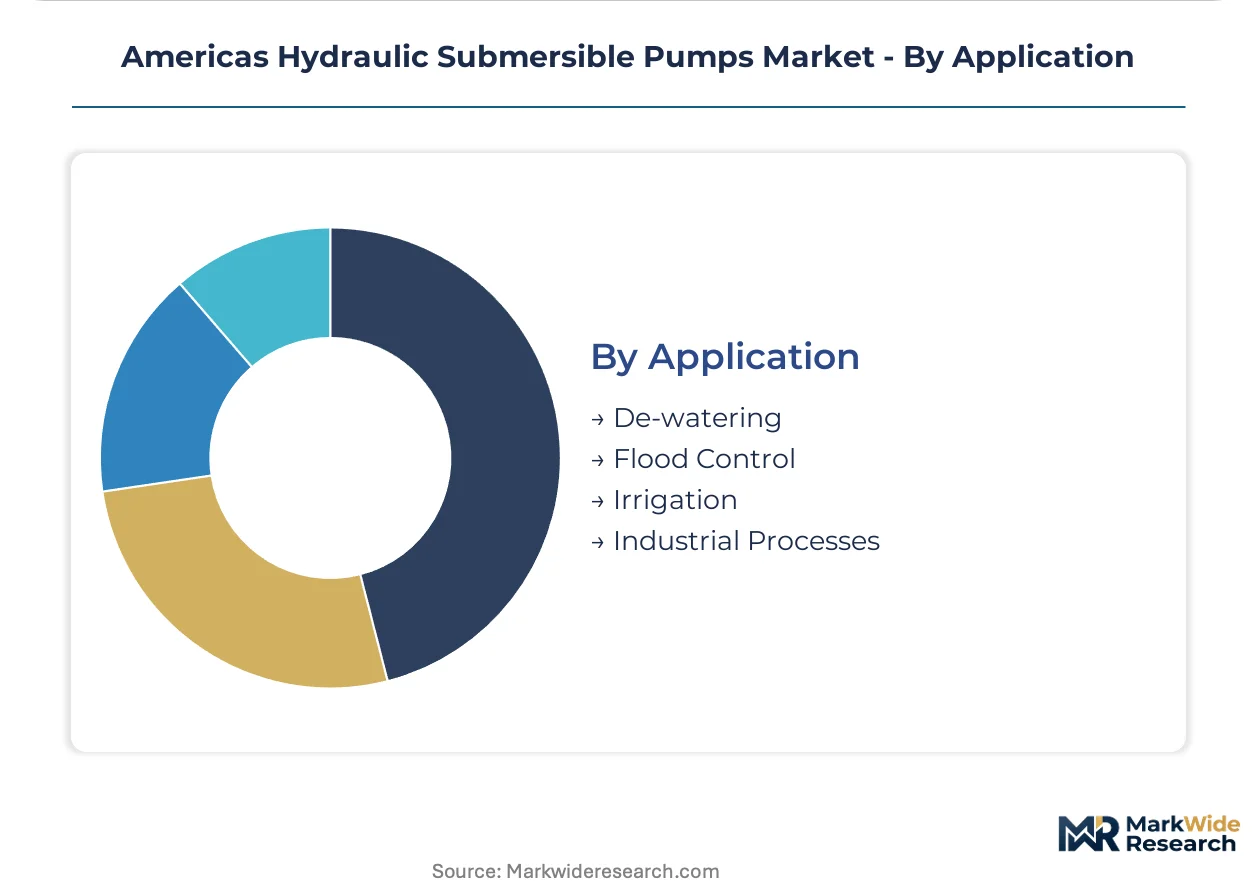
Hydraulic submersible pumps are centrifugal units driven by hydraulic power units rather than electric motors, enabling operation in submerged environments where electrical ignition risks or power availability constraints exclude conventional pump types; these systems typically handle solids passage of 50-80mm and operate at hydraulic pressures of 100-250 bar, serving primary purposes in mine dewatering, tunnel construction drainage, and emergency flood response where portable, explosion-safe pumping capacity is required. Vertical pumps dominate unit shipments across the Americas due to their compact footprint and direct column discharge configuration suited to sump installations, while multistage pumps command premium positioning in deep-well oil field applications where single-stage head limitations would otherwise require cascading pump arrays. De-watering applications generate the largest revenue pool within the application dimension, though flood control procurement is accelerating fastest as climate adaptation budgets expand across Gulf Coast and Caribbean jurisdictions.
The U.S. EPA and Brazil's national environmental regulator shape product standards through effluent and equipment safety mandates, while OSHA confined space entry regulations drive specification of hydraulic over electric systems in hazardous atmosphere conditions. API standards for oil field equipment and ANSI hydraulic power unit specifications further constrain design choices for manufacturers seeking cross-border market access. Stakeholders must monitor how proposed revisions to U.S. Buy American procurement thresholds redirect municipal purchasing toward domestic assembly operations.
Market Dynamics
EPA effluent limitation guidelines and Brazil's ANVISA equipment safety mandates are compressing product lifecycles while concentrating procurement authority among fewer municipal buyers with larger contract values.
Growth Catalysts
- Clean Water Act enforcement:EPA discharge standard tightening compels U.S. wastewater utilities to replace aging pump infrastructure with higher-capacity hydraulic systems.
- Mining dewatering intensity:Brazil's southeastern industrial corridor is scaling equipment replacement cycles as iron ore and copper extraction deepens below water tables.
- Hydraulic power unit portability:Tunnel construction contractors across the Andes are specifying explosion-safe hydraulic drives over electric alternatives for confined atmosphere work.
Market Restraints
- Steel and alloy input volatility:Abrasion-resistant pump casting materials face price swings that compress manufacturer margins on fixed municipal contracts.
- Single-source hydraulic component concentration:High-pressure seal and valve suppliers cluster in German and Japanese industrial zones, creating supply vulnerability for Americas-based assemblers.
- Electric submersible substitution in non-hazardous settings:Lower operating cost electric pumps displace hydraulic units in surface dewatering applications where explosion risk is absent.
Strategic Opportunities
- Caribbean flood control infrastructure:Climate adaptation budgets in Gulf Coast and island jurisdictions are accelerating emergency response pump procurement with federal disaster resilience funding.
- Digital monitoring convergence:Integration of hydraulic power units with IoT pressure sensors and predictive maintenance platforms creates premium pricing tiers for fleet operators.
- Rental fleet channel expansion:Construction contractors in Texas shale fields and Alberta oil sands are shifting from ownership to short-term hydraulic pump rentals for project-specific dewatering.
Industry Challenges
- Hydraulic technician scarcity:Specialized maintenance skills for 100-250 bar pressure systems are concentrating among aging workforces in U.S. mining regions without adequate training pipeline replacement.
- API certification timeline compression:Oil field equipment approval cycles are extending as ANVISA and EPA standards diverge on seal material specifications, delaying cross-border product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Hydraulic Submersible Pumps Market |
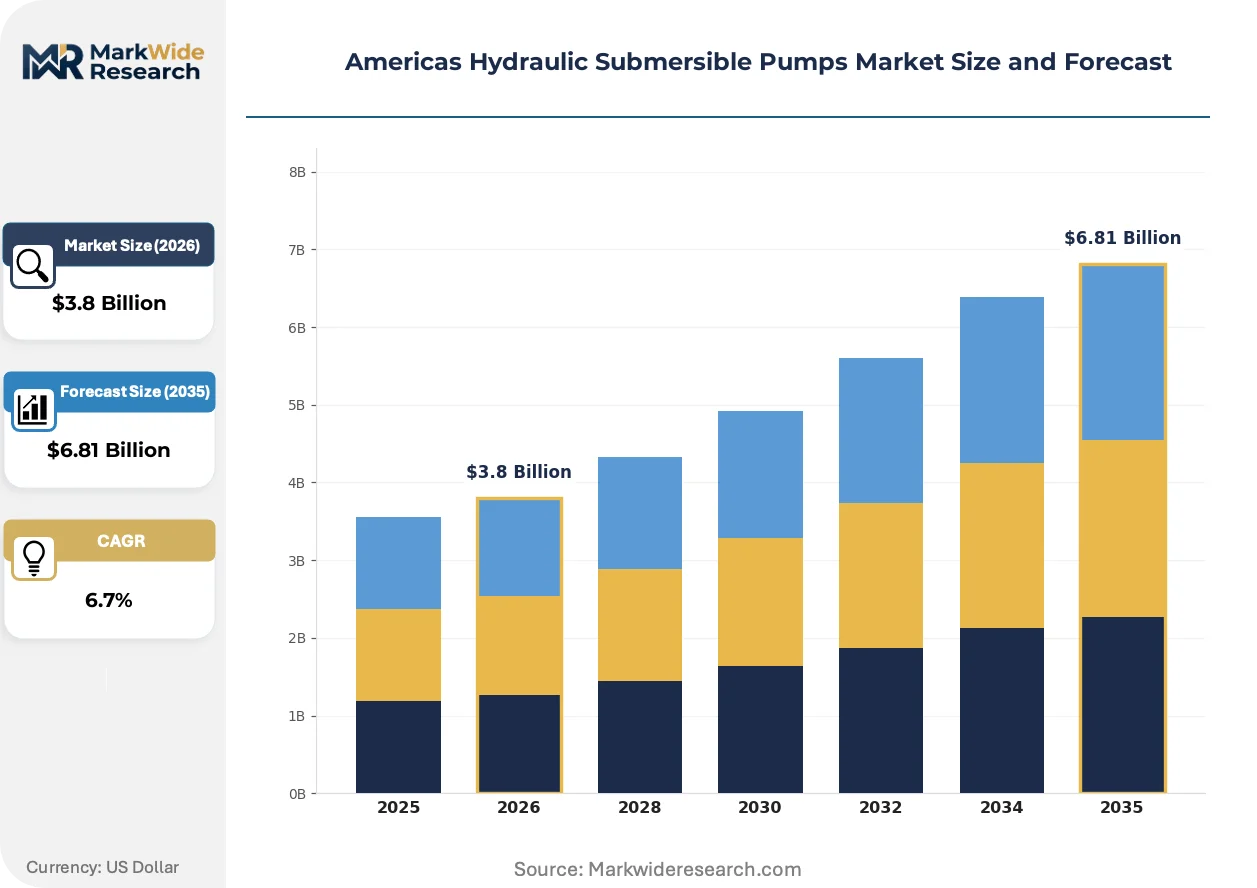
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Pumps, Horizontal Pumps, Cantilever Pumps, Multistage Pumps End User: Mining Industry, Oil & Gas, Construction, Wastewater Treatment Material: Cast Iron, Stainless Steel, Plastic, Alloy Application: De-watering, Flood Control, Irrigation, Industrial Processes |
| Companies Covered | Atlas Copco AB, BAKERCORP, Cornell Pump Company, The Gorman-Rupp Company, Griffin Dewatering Corporation, Xylem Inc., Sulzer Ltd., KSB America, Weir Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Hydraulic Submersible Pumps Market Strategic Shifts
Active substitution of conventional drive systems, regulatory harmonization pressures, and procurement centralization are restructuring how hydraulic submersible pumps are specified, serviced, and financed across municipal and industrial buyer segments.
Variable frequency drive integration with hydraulic power units is electrifying traditional fixed-speed pump operations. Mining contractors in Chile and Peru are retrofitting existing hydraulic fleets with electronically controlled pressure modulation to match variable inflow conditions. This electrification is compressing energy consumption per cubic meter pumped while extending seal life through reduced pressure cycling.
OSHA confined space entry regulations are tightening specification requirements for explosion-safe equipment in hazardous atmosphere conditions. Industrial safety officers at U.S. petrochemical facilities now mandate hydraulic over electric systems in sump applications where volatile gas accumulation is possible. ANSI hydraulic power unit specifications are being revised to incorporate these operational constraints, forcing redesign of legacy product lines.
After-sales service unbundling is fragmenting traditional manufacturer-dealer relationships. Municipal wastewater utilities in São Paulo and Mexico City are negotiating direct maintenance contracts with specialized hydraulic service firms rather than OEM channel partners. This disintermediation is most visible in large-volume dewatering fleets where in-house technical capability justifies bypassing distributor markups for spare parts and field repair.
Americas Hydraulic Submersible Pumps Market Segmentation
Equipment specification patterns across the Americas reveal distinct upgrade cycles by product architecture and end-use intensity. Procurement authority concentrates among municipal buyers with multi-year replacement programs and industrial operators managing deep-well extraction below water tables.
Product Type:
Replacement cycles vary sharply by pump architecture, with compact footprint designs commanding municipal sump installations and multistage arrays dominating deep extraction economics.
- Vertical Pumps:These units deploy direct column discharge configurations that minimize floor space in confined sump environments. Municipal wastewater utilities across São Paulo and Mexico City specify vertical architectures for sludge handling upgrades driven by EPA effluent tightening.
- Multistage Pumps:Cascaded impeller arrays overcome single-stage head limitations in oil field applications. Brazil's southeastern industrial corridor deploys these systems for iron ore dewatering as extraction depths descend below regional water tables.
- Horizontal Pumps:Side-discharge configurations suit surface-mounted installations with accessible maintenance access.
- Cantilever Pumps:Bearing-free submerged designs eliminate seal wear in abrasive slurry conditions.
Volume placements concentrate in Vertical Pumps; the faster expansion belongs to Multistage Pumps.
End User:
Customer procurement scale determines service model economics, with rental fleet operators capturing construction volatility and municipal utilities locking in decade-long maintenance contracts.
- Mining Industry:Abrasive slurry handling at 100-250 bar operating pressures demands abrasion-resistant casting specifications. Chilean copper operators and Brazilian iron ore extractors are compressing equipment replacement cycles as pit depths advance below water tables.
- Wastewater Treatment:Solids passage requirements of 50-80mm diameter govern specification for municipal sludge transfer. U.S. Clean Water Act enforcement is compelling infrastructure upgrades across Gulf Coast utilities with federal resilience funding.
- Oil & Gas:Explosion-safe hydraulic drives predominate in volatile atmosphere sump applications.
- Construction:Project-specific dewatering demand is shifting procurement toward short-term rental channels.
Revenue concentration sits with Mining Industry deployments; Wastewater Treatment is climbing the fastest on regulatory compliance spending.
Material:
Input cost volatility across alloy supply chains is forcing specification tradeoffs between abrasion resistance and procurement budget certainty.
- Cast Iron:Standard-grade housings dominate municipal procurement where abrasive content remains moderate and capital budgets face political approval cycles.
- Stainless Steel:Corrosion-resistant specifications command premium positioning in coastal flood control installations and chemical process environments.
- Alloy:Hardened compositions address oil sands and mining slurry abrasion but face price volatility from concentrated German and Japanese supplier bases.
- Plastic:Polymer housings serve low-pressure irrigation and temporary dewatering with minimal capital exposure.
Shipments concentrate in Cast Iron; Alloy specifications are gaining share fastest on mining intensity.
Application:
Climate adaptation budgets are restructuring demand geography, with emergency response procurement accelerating across Caribbean and Gulf Coast jurisdictions.
- De-watering:Mine and tunnel drainage generates the largest revenue pool across the Americas. Andean construction contractors specify explosion-safe hydraulic drives over electric alternatives for confined atmosphere work.
- Flood Control:Portable high-capacity pumping capacity serves emergency response deployment. Federal disaster resilience funding is accelerating procurement across Caribbean island jurisdictions and Texas Gulf Coast municipalities.
- Industrial Processes:Continuous-duty specifications in petrochemical and refining environments demand API-certified seal configurations.
- Irrigation:Seasonal surface water management employs lower-specification units where explosion risk is absent.
De-watering captures the dominant placement volume; Flood Control is expanding most quickly on climate adaptation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone concentrates hydraulic power unit assembly for Andean mining contractors, while Mexico's IMMEX maquiladora program draws pump component fabrication to Nuevo León and Chihuahua border corridors.
United States
Gulf Coast wastewater utilities deploy vertical pumps for stormwater management upgrades. EPA effluent limitation guidelines tighten discharge standards across Louisiana and Texas municipalities. Houston's petrochemical corridor specifies explosion-safe hydraulic drives for sump applications under OSHA confined space rules.
Brazil
Iron ore dewatering intensifies in Minas Gerais as pit depths descend below water tables. ANVISA equipment safety mandates compress product approval timelines for imported hydraulic systems. São Paulo's metropolitan sanitation authority locks in decade-long maintenance contracts for sludge handling infrastructure.
Canada
Alberta oil sands operators demand abrasion-resistant multistage pumps for tailings pond management. Health Canada and PMRA coordinate equipment safety standards with API certification requirements. Calgary's energy services cluster scales rental fleet operations for project-specific dewatering contracts.
Mexico
Tunnel construction across the Sierra Madre Occidental drives specification of portable hydraulic power units. IMMEX maquiladora incentives concentrate component fabrication in Nuevo León for North American assembly. Mexico City's wastewater authority upgrades aging infrastructure with federal resilience funding.
Chile
Copper extraction in the Atacama Desert deploys multistage pumps for groundwater control at extreme depths. The national mining regulator enforces equipment safety standards aligned with ISO hydraulic power specifications. Antofagasta's mining services cluster retrofits existing fleets with variable frequency drive integration.
Americas Hydraulic Submersible Pumps Market Competitive Environment
North American producers anchor the integrated systems tier; European specialists hold premium positioning in abrasion-resistant engineering. The vendor base separates into three strategic archetypes: full-line pump manufacturers with captive hydraulic power unit production, specialized dewatering rental fleet operators, and regional component fabricators serving municipal procurement. Consolidation pressure concentrates among mid-scale assemblers facing input cost volatility, while technology licensing agreements proliferate for digital monitoring platform integration.
Among diversified industrial conglomerates, Atlas Copco AB exemplifies the integrated systems archetype through its established position in compressed air and power solutions. Xylem Inc. and Sulzer Ltd. occupy positions within the premium engineering tier, with the former representing vertical integration across pump systems and monitoring platforms, and the latter anchoring specialized expertise in demanding slurry applications. Griffin Dewatering Corporation sits within the rental fleet operator archetype, serving project-based demand across construction and mining sites where capital ownership economics prove unfavorable.
| Leading Market Players |
|---|
| Atlas Copco AB |
| BAKERCORP |
| Cornell Pump Company |
| The Gorman-Rupp Company |
| Griffin Dewatering Corporation |
| Xylem Inc. |
| Sulzer Ltd. |
| KSB America |
| Weir Group |
| Others |
Value Chain & Pricing Dynamics
Alloy casting material costs cascade from concentrated German and Japanese supplier zones through three-tier pricing structures separating API-certified multistage arrays from standard municipal vertical pumps. Brazilian iron ore operators absorb premium markups for abrasion-resistant specifications while Gulf Coast utilities negotiate fixed-price contracts against volatile stainless steel indices.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate spot rental fleet deployments from scheduled municipal procurement cycles. Project-based pricing dominates construction dewatering where Griffin Dewatering and similar operators bundle hydraulic power units with on-site technical support. Price differentiation rests on API certification tier and after-sales service bundling rather than base equipment specifications. Municipal wastewater authorities exhibit highest price sensitivity due to political budget approval cycles, while oil sands operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific component origins compresses margins for Americas-based assemblers dependent on just-in-time seal and valve inventories. High-pressure hydraulic component manufacturing concentrates in Germany, Japan, and South Korea, with final pump assembly clustering in Brazil's Manaus Free Trade Zone and Mexico's IMMEX corridors. Raw material dependencies span nickel-alloy castings, specialized elastomer seals, and precision-machined valve bodies. Single-source vulnerability in high-pressure seal technology creates supply risk exposure. Distribution runs through OEM-direct channels for municipal utilities and rental fleet intermediaries for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas hydraulic submersible pumps market functions as a vertical-integration race where captive hydraulic power unit production determines margin capture. Players are pursuing backward integration into high-pressure seal manufacturing to escape German and Japanese supplier concentration.
For Market Incumbents: Anticipate electric submersible substitution pressure in surface dewatering applications by deepening backward integration into alloy casting capabilities. Lock in decade-long maintenance contracts with São Paulo and Mexico City sanitation authorities before specialized hydraulic service firms consolidate aftermarket share. Prioritize API certification investment to defend positioning in Brazilian oil sands and Chilean copper extraction. For New Entrants and Emerging Players: Begin with Caribbean flood control procurement where federal disaster resilience funding accelerates emergency response pump deployment. Target municipal rental fleet partnerships in Texas shale fields where project-specific dewatering demand outpaces ownership economics. Pursue digital monitoring platform licensing agreements rather than competing on base equipment specifications. For Investors and Strategic Acquirers: ANVISA approval timeline compression for imported hydraulic systems is the leading indicator that Brazilian domestic assembly assets will command scarcity premiums. Position for five-to-ten year holding periods centered on rental fleet operators with established maintenance technician networks. Monitor OSHA confined space regulation enforcement intensity as signal for explosion-safe hydraulic drive substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Reduces dependency on German and Japanese high-pressure component suppliers for Americas-based assemblers. |
| Digital Monitoring Platform Licensing | Enables predictive maintenance revenue streams for fleet operators serving Chilean copper and Brazilian iron ore extraction. |
| API Certification Pathway Investment | Accelerates market access for multistage pump arrays in Alberta oil sands and Texas petrochemical corridors. |
| Rental Fleet Channel Expansion | Captures project-based construction demand across Andean tunnel contractors and shale field operators. |
| Maintenance Technician Training Pipeline | Addresses workforce scarcity constraining aftermarket service capacity in U.S. mining regions. |
Study Parameters
Document review covered EPA effluent limitation guidelines, ANVISA equipment safety mandates, API standards documentation, and OSHA confined space regulations, complemented by interviews with municipal wastewater procurement directors, mining maintenance managers, rental fleet operations heads, and hydraulic power unit engineering leads. Secondary validation drew from customs trade data, SEC filings of listed pump manufacturers, and Brazilian mining regulator disclosure databases. Bottom-up equipment shipment estimates triangulated against top-down infrastructure spending projections across the analysis window.
Cross-referencing historical replacement cycle patterns with panel input from Andean construction contractors and Gulf Coast utility planners shaped the analytical framework. Segmentation modeling spanned product architecture, end-use intensity, material specification grade, and application type throughout the forecast period. CAGRs derived from equipment lifecycle compression rates and regulatory compliance spending trajectories. Industry-specific inputs included iron ore pit depth advancement curves and federal disaster resilience funding authorization patterns.
Underlying measurement precision varies by segment; municipal wastewater procurement data carries tighter precision than informal construction rental channel estimates. Forecasts reflect assumptions regarding EPA enforcement intensity and Brazilian mining output stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dozer Blade Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Yard Crane Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Powered Screed Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Felling Heads Market
Construction Equipment
Global Excavators Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Construction Lasers Market