
 Spray Washer Market | 2026-2036
Spray Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Washer Market Analytics
Skilled technician availability for high-pressure system maintenance is collapsing across industrialized economies, forcing OEMs to redesign machines for remote diagnostics and modular component swap-outs. Alfred Kärcher SE & Co. KG leverages its captive service network across Europe to sustain aftermarket attachment rates. Nilfisk Group anchors its position through specialized stainless-steel architectures for food-grade wash-down compliance. DEWALT competes aggressively in the portable electric segment through channel control at big-box retail.
A spray washer is a mechanized cleaning apparatus that directs pressurized water, solvent, or aqueous solution through fixed or rotating nozzle arrays to remove contaminants from surfaces, typically operating between 1,000 and 4,000 PSI in industrial configurations with programmable cycle timers and filtration stages. Its primary purpose is to automate degreasing, descaling, and particulate removal in production environments where manual cleaning introduces inconsistency or safety hazards. Pressure washers occupy the largest revenue pool due to cross-sector versatility from residential driveways to fleet maintenance yards, while ultrasonic washers command premium positioning in semiconductor and medical device sub-supplier tiers where cavitation precision prevents substrate damage. Electric washers are gaining specification share in indoor manufacturing settings as facility managers restrict gas-powered emissions under ventilation constraints.
EPA effluent guidelines under the Clean Water Act constrain discharge chemistry from aqueous cleaning operations, compelling end-users to specify washers with integrated oil-water separators and zero-discharge loops. REACH restrictions on chlorinated solvents and chromium-based passivation agents redirect European buyers toward alkaline detergent and steam-based platforms that ECHA has cleared for sustained use. OSHA lockout-tagout and noise-exposure standards shape guarding and acoustic-dampening requirements that add engineering cost but also create specification stickiness once equipment is certified. Stakeholders must monitor how carbon-border adjustment mechanisms and state-level water-stress regulations will reshape total-cost-of-ownership calculations for capital-intensive cleaning infrastructure.
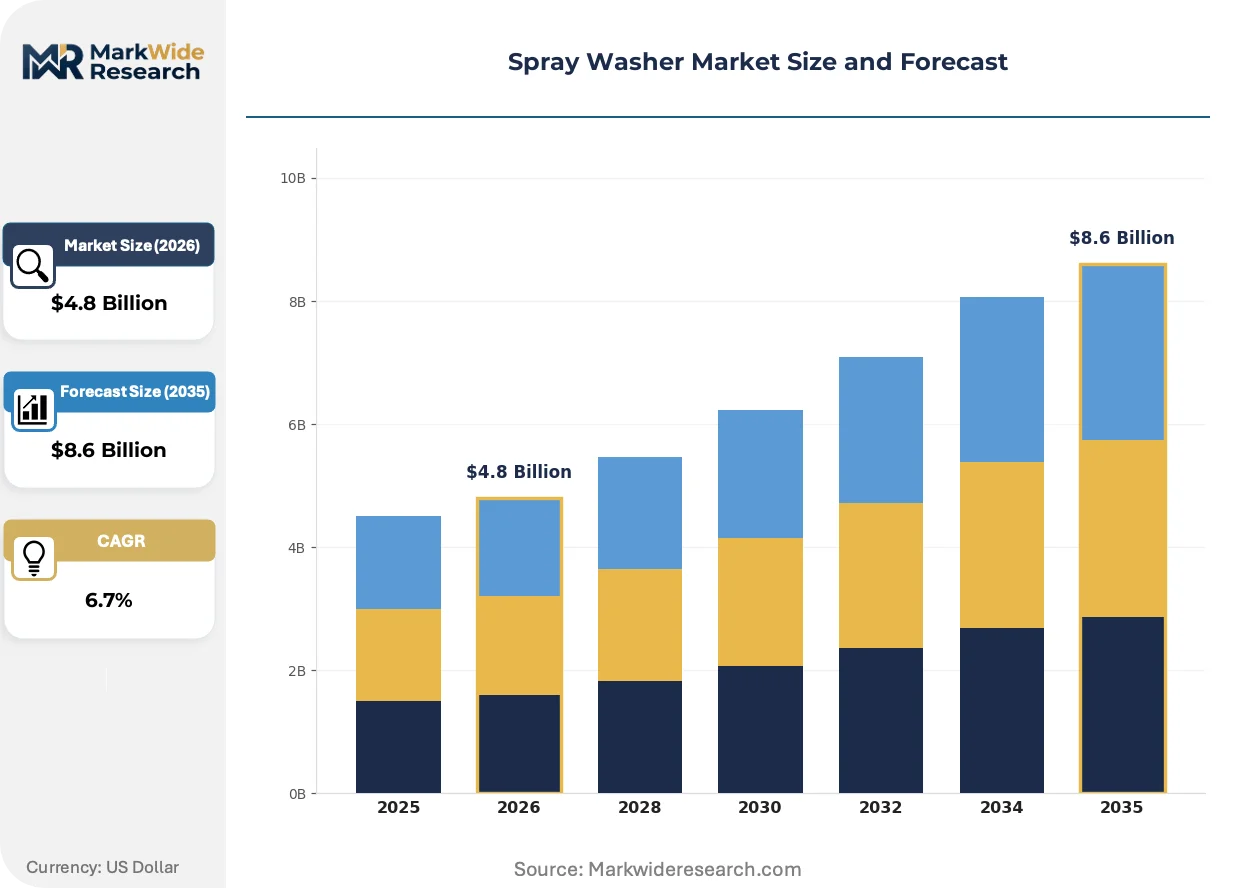
Market Dynamics
Automotive assembly plants are forcing equipment redesign through automated parts-cleaning workflows that eliminate manual intervention, while EPA effluent standards and REACH chemical restrictions simultaneously push manufacturers toward closed-loop water-recovery architectures that alter capital deployment patterns.
Growth Catalysts
- REACH chemical restrictions:European buyers redirect procurement toward alkaline detergent and steam-based platforms that ECHA has cleared for sustained use, expanding specification-grade equipment demand.
- Precision-engineering clusters:Germany's concentration of advanced manufacturing facilities drives procurement of high-specification wash systems with programmable cycle timers and integrated filtration stages.
- Indoor manufacturing ventilation constraints:Facility managers across industrialized economies restrict gas-powered emissions, pulling electric washer specification share upward in enclosed production environments.
Market Restraints
- Stainless-steel input cost volatility:Food-grade wash-down compliance requirements mandate specialized architectures that expose OEMs to nickel and chromium price swings.
- Skilled technician scarcity:High-pressure system maintenance expertise is collapsing across industrialized economies, forcing service network dependence or costly remote diagnostic redesign.
- Ultrasonic substitution in precision tiers:Semiconductor and medical device sub-suppliers favor cavitation-based cleaning where substrate damage prevention outweighs spray washer throughput advantages.
Strategic Opportunities
- Carbon-border adjustment mechanisms:Emerging trade instruments will reshape total-cost-of-ownership calculations for capital-intensive cleaning infrastructure, favoring low-emission platform providers.
- Modular component swap-out architectures:OEMs can capture aftermarket attachment rates through designs that enable rapid field replacement without specialized labor.
- State-level water-stress regulations:Sub-national jurisdictions in water-constrained regions are tightening discharge limits ahead of federal timelines, creating first-mover advantage for zero-discharge loop suppliers.
Industry Challenges
- OSHA lockout-tagout compliance:Guarding and acoustic-dampening requirements add engineering cost and certification timeline complexity that extends sales cycles.
- Legacy aqueous chemistry integration:End-users face reconfiguration friction when retrofitting closed-loop systems onto existing detergent-based workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Washer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Washers, Stationary Washers, Pressure Washers, Ultrasonic Washers End User: Automotive Industry, Manufacturing Sector, Food Service, Residential Users Technology: Electric Washers, Gas-Powered Washers, Steam Washers, Hybrid Washers Application: Surface Cleaning, Vehicle Detailing, Industrial Cleaning, Equipment Maintenance |
| Companies Covered | Alfred Kärcher SE & Co. KG, DEWALT, Stanley Black & Decker, Generac Power Systems, BOSCH, Nilfisk Group, FNA Group, Briggs & Stratton, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Washer Market Evolving Landscape
Remote diagnostics capability is fragmenting competitive advantage away from pure equipment specification toward integrated service architecture, while regulatory chemistry restrictions and buyer procurement consolidation simultaneously reshape value capture mechanisms across the supply chain.
Closed-loop water-recovery technology is fragmenting the traditional capital-sale model by enabling outcome-based pricing tied to effluent compliance guarantees rather than equipment throughput metrics. Automotive Tier-1 suppliers in Germany and precision-engineering clusters across Central Europe are adopting these systems fastest. The technology is fragmenting vendor margins between hardware, chemistry management, and ongoing water-quality monitoring services.
EPA effluent guidelines under the Clean Water Act are constraining discharge chemistry from aqueous cleaning operations, compelling end-users to specify integrated oil-water separators and zero-discharge loops. This industrial consequence is compressing the viable supplier set to those with certified separation technology. Metal fabrication and fleet maintenance yards in water-stressed US states are most affected and are responding by bundling washer procurement with ongoing compliance monitoring contracts.
Buyer concentration among automotive OEMs is compressing switching cycles and unbundling after-sales service from initial equipment procurement. Direct sourcing teams at major assembly plant operators are displacing distributor intermediaries in specification conversations. This pattern is most visible in Germany and the US Midwest where production capacity expansions are concentrating procurement authority within centralized engineering functions.
Spray Washer Market Segmentation
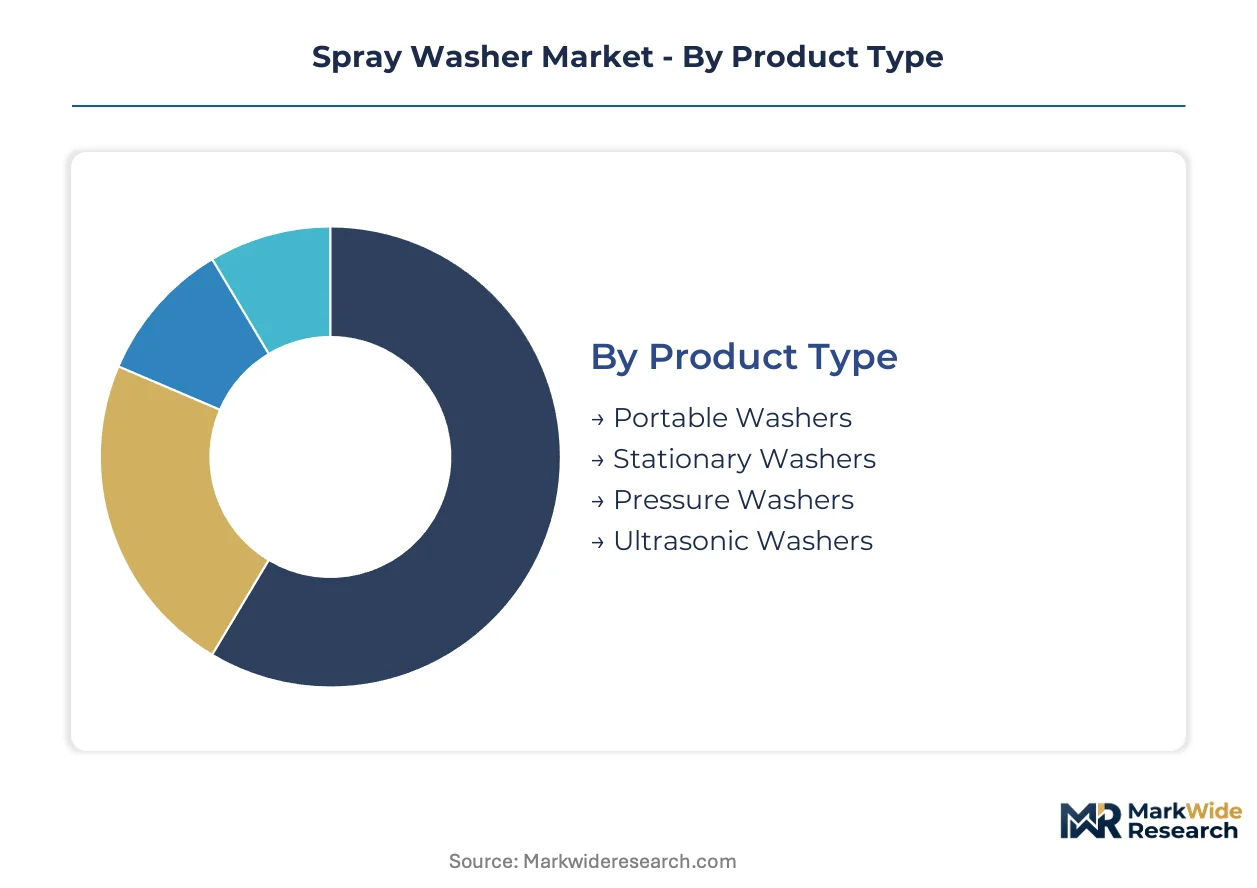
Spray washer procurement patterns diverge sharply across product configurations, with regulatory compliance and operational environment dictating specification priorities. Understanding these segment boundaries reveals where technology substitution and margin compression concentrate competitive pressure.
Product Type:
EPA effluent guidelines and REACH chemical restrictions create divergent certification burdens across product architectures, compressing the viable supplier set for aqueous discharge systems while opening specification windows for closed-loop alternatives.
- Pressure Washers:These systems operate between 1,000 and 4,000 PSI with programmable cycle timers and multi-stage filtration, dominating revenue pools through cross-sector versatility from residential driveways to fleet maintenance yards in Germany and the US Midwest. Demand concentrates where throughput consistency outweighs precision requirements.
- Ultrasonic Washers:Cavitation-based cleaning prevents substrate damage in semiconductor and medical device sub-supplier tiers, commanding premium positioning where precision outweighs spray washer throughput advantages. ECHA-cleared chemistry platforms expand specification-grade equipment demand in European precision-engineering clusters.
- Portable Washers:Compact mobile units serve intermittent cleaning needs across construction sites and small-scale maintenance operations.
- Stationary Washers:Fixed-installation systems anchor automated parts-cleaning workflows in automotive assembly plants with integrated oil-water separators.
Established volume favors Pressure Washers; emerging adoption favors Ultrasonic Washers.
End User:
Cost tier stratification separates capital-intensive automated workflows from intermittent-use procurement, with compliance burden and service network dependence scaling inversely with purchase frequency.
- Automotive Industry:Tier-1 suppliers and OEM assembly plants drive automated parts-cleaning workflow adoption, eliminating manual intervention through fixed-installation systems with zero-discharge loops. Procurement authority concentrates within centralized engineering functions in Germany and the US Midwest.
- Manufacturing Sector:Metal fabrication and precision-engineering facilities specify integrated oil-water separators under EPA effluent guidelines, with water-stressed US states bundling washer procurement with ongoing compliance monitoring contracts.
- Food Service:Specialized stainless-steel architectures for wash-down compliance expose operators to nickel and chromium price volatility.
- Residential Users:Intermittent-use purchasers prioritize channel accessibility and upfront cost over service architecture depth.
Capital deployment scale favors Automotive Industry; specification complexity favors Manufacturing Sector.
Technology:
Customer type and application environment dictate power source selection, with indoor ventilation constraints and carbon-border adjustment mechanisms reshaping total-cost-of-ownership calculations.
- Electric Washers:Zero-emission operation enables specification in enclosed production environments where facility managers restrict gas-powered emissions under ventilation constraints. Indoor manufacturing settings across industrialized economies pull electric washer specification share upward.
- Gas-Powered Washers:Higher mobility and output pressure serve outdoor fleet maintenance and construction applications where ventilation is unrestricted.
- Steam Washers:Alkaline detergent and steam-based platforms cleared by ECHA for sustained use redirect European buyers from chlorinated solvent systems.
- Hybrid Washers:Dual-power architectures address transitional compliance environments where emission regulations tighten unevenly across jurisdictions.
Specification momentum favors Electric Washers; outdoor mobility retention favors Gas-Powered Washers.
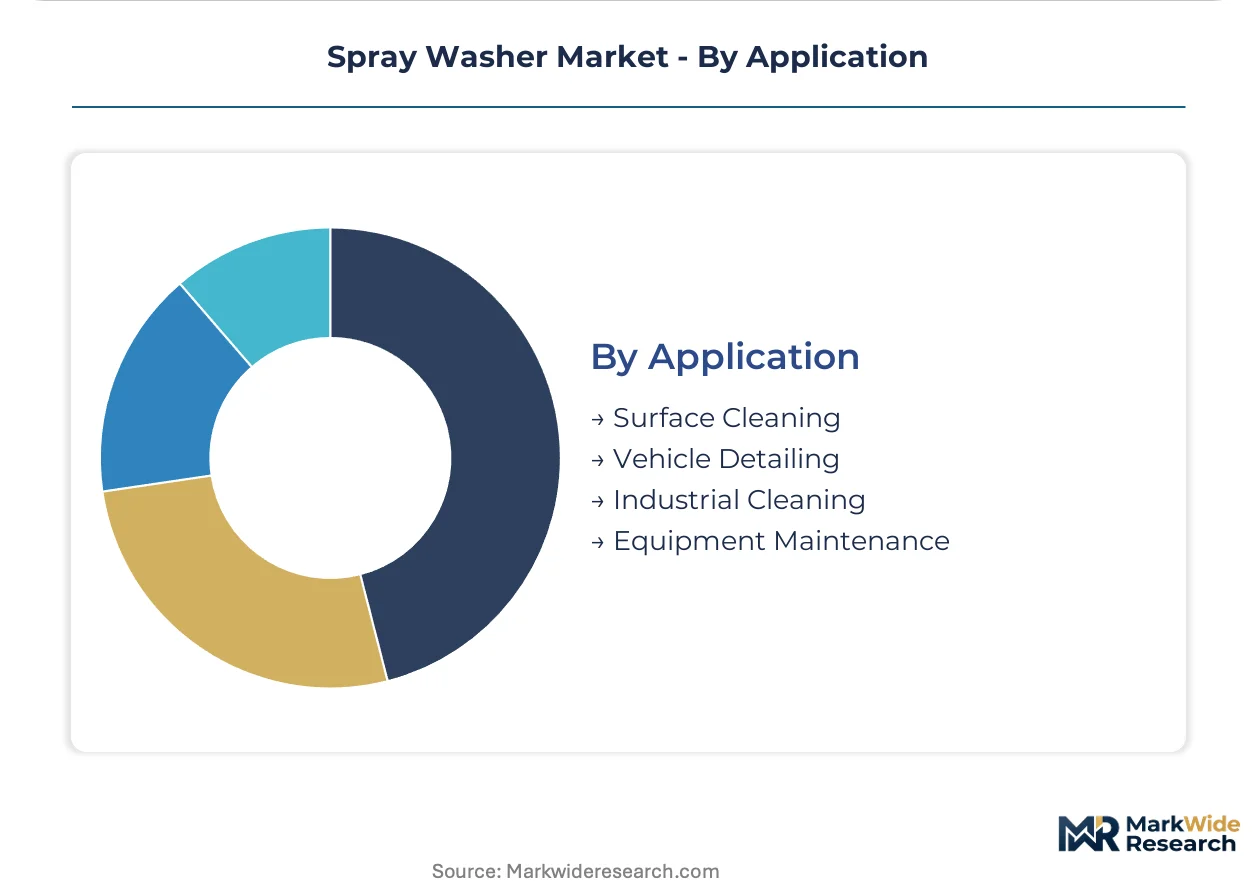
Application:
Margin structure and aftermarket attachment rates vary by cleaning task complexity, with outcome-based pricing emerging fastest where compliance guarantees replace throughput metrics.
- Industrial Cleaning:Degreasing and descaling operations in production environments specify closed-loop water-recovery systems with programmable cycle timers, fragmenting vendor margins between hardware, chemistry management, and ongoing water-quality monitoring services.
- Equipment Maintenance:Fleet yards and metal fabrication facilities respond to state-level water-stress regulations by bundling washer procurement with compliance monitoring contracts.
- Surface Cleaning:General particulate removal spans residential through commercial tiers with lowest specification stickiness.
- Vehicle Detailing:Cosmetic cleaning applications prioritize portability and speed over filtration stage integration.
Service revenue potential favors Industrial Cleaning; standardization favors Surface Cleaning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision-engineering corridors, where specification-grade equipment commands premiums that Mexican assembly plants cannot replicate under NAFTA cost pressures. This asymmetry shapes procurement patterns across automotive and manufacturing tiers.
United States
Automotive assembly plants in Michigan and Ohio are forcing automated parts-cleaning workflow adoption, eliminating manual intervention through fixed-installation systems. EPA effluent guidelines under the Clean Water Act compel metal fabrication facilities to specify integrated oil-water separators. Fleet maintenance yards in water-stressed California and Arizona respond by bundling washer procurement with ongoing compliance monitoring contracts.
Germany
Precision-engineering clusters across Bavaria and Baden-Württemberg drive procurement of high-specification wash systems with programmable cycle timers. REACH restrictions on chlorinated solvents redirect buyers toward alkaline detergent platforms that ECHA has cleared for sustained use. Stuttgart's automotive Tier-1 suppliers are adopting closed-loop water-recovery technology fastest, fragmenting vendor margins between hardware and chemistry management services.
China
MIIT emission standards and provincial water-stress regulations in the Yangtze River Delta are tightening discharge limits ahead of national timelines. Manufacturing facilities in Jiangsu and Zhejiang provinces specify electric washers to satisfy indoor ventilation constraints under GB standards. Shanghai's precision electronics sub-suppliers favor cavitation-based cleaning where substrate damage prevention outweighs spray washer throughput advantages.
Japan
METI energy-efficiency mandates accelerate specification of zero-emission electric platforms in enclosed production environments. Automotive OEMs in Aichi Prefecture's Toyota City corridor concentrate procurement authority within centralized engineering functions. Osaka-based metal fabricators integrate closed-loop architectures to satisfy stricter local effluent standards that exceed national baselines.
India
BIS certification requirements and state-level water conservation rules in Maharashtra and Gujarat reshape capital deployment patterns for aqueous cleaning operations. Automotive component suppliers in Pune and Chennai adopt automated workflows to satisfy OEM quality audits. The PLI scheme for manufacturing incentivizes Tier-1 suppliers to upgrade from intermittent-use portable units to fixed-installation systems with filtration stages.
Spray Washer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium specification-grade equipment vendors operate at margins distinct from mass-market portable suppliers. The vendor set compresses around certified separation technology providers under tightening EPA and REACH discharge constraints. Three archetypes dominate: European precision-engineering specialists with captive service networks, Asian scale manufacturers with channel control at big-box retail, and diversified industrial conglomerates with backward integration into pump and motor components. Competitive moves concentrate on modular component architectures that enable rapid field replacement and strategic partnerships bundling equipment with ongoing compliance monitoring services.
Among European specialists, Alfred Kärcher SE & Co. KG and Nilfisk Group represent the premium-tier vector where aftermarket attachment rates sustain margin structures. DEWALT occupies a position within the mass-market electric segment where channel density at retail intermediaries determines specification share. These three exemplify how competitive advantage fragments between integrated service architecture and pure equipment specification under regulatory chemistry restrictions.
| Leading Market Players |
|---|
| Alfred Kärcher SE & Co. KG |
| DEWALT |
| Stanley Black & Decker |
| Generac Power Systems |
| BOSCH |
| Nilfisk Group |
| FNA Group |
| Briggs & Stratton |
| Techtronic Industries |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for stainless-steel pump assemblies concentrate procurement leverage with German and Japanese foundries, amplifying price premiums for specification-grade equipment against mass-market alternatives.
Pricing Analysis
Configured-to-order pricing commands a substantial premium over standard catalog configurations in the spray washer market. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-certified closed-loop systems from basic aqueous discharge units. Price differentiation stems from certification grade and after-sales service bundling. Cost compression in the portable electric segment intensifies because channel density at big-box retail rewards volume scale over margin depth. Residential users exhibit highest price sensitivity; automotive Tier-1 suppliers show lowest sensitivity due to compliance-driven specification stickiness.
Supply Chain Analysis
Inventory buffers for nickel-alloy components have compressed to thirty-day levels, exposing OEMs to commodity price volatility. Manufacturing concentrates in Germany, China, and Italy for precision pump assemblies and nozzle arrays. The supply chain draws from stainless-steel mills, high-pressure seal manufacturers, and programmable controller suppliers. Single-source vulnerability concentrates in specialized ceramic nozzle production. Distribution runs through captive service networks for premium-tier equipment and retail intermediaries for portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapse of skilled technician availability for high-pressure system maintenance creates acute capability scarcity, rewarding vendors with integrated remote diagnostics and rapid field-replacement architectures.
For Market Incumbents: Secure aftermarket attachment rates through modular component swap-out designs that eliminate specialized labor dependence. Deepen backward integration into pump and motor production to offset stainless-steel input cost volatility. Invest in ECHA certification breadth to defend specification-grade positioning against alkaline detergent platform competitors.
For New Entrants and Emerging Players: Lead with zero-discharge loop offerings in water-stressed US states where state-level regulations tighten ahead of federal timelines. Target compliance monitoring service contracts bundled with equipment procurement. Establish direct relationships with automotive OEM centralized engineering functions to bypass distributor intermediaries.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized pump technology divisions and stranded stainless-steel fabrication capacity. Long-term viability favors vendors with chemistry management service revenue streams rather than pure hardware plays. Watch carbon-border adjustment mechanism implementation timing as inflection indicator for low-emission platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Assemblies | In-house production of high-pressure components insulates margin from nickel price volatility. |
| Closed-Loop Water-Recovery Certification | ECHA-cleared systems capture specification-grade procurement in German precision-engineering clusters. |
| Remote Diagnostics Platform Deployment | Integrated service architecture addresses skilled technician scarcity across industrialized economies. |
| Compliance Monitoring Service Bundling | Outcome-based contracts with fleet yards respond to EPA effluent guidelines in water-stressed states. |
| Electric Platform Expansion | Zero-emission specifications satisfy indoor ventilation constraints under OSHA and METI mandates. |
Research Methodology
A spread of perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined structured interviews with technical validation from equipment operators and facility managers. Secondary sources included customs and trade data, SEC filings from listed industrial conglomerates, EPA enforcement databases, and ECHA substance restriction notifications. Bottom-up unit economics triangulated against top-down sector expenditure patterns.
Segmentation dimensions modeled encompass product type, end-user industry, power source technology, and application environment across the projection horizon. CAGRs were derived from fitted growth curves anchored to observed replacement cycles and regulatory compliance timelines. Industry-specific inputs included automotive production capacity expansion schedules, REACH restriction implementation phases, and state-level water-stress regulation adoption curves.
Forecasts assume regulatory continuity in EPA effluent guidelines and REACH chemical restrictions; material policy shifts would require re-modeling. Stainless-steel price volatility and carbon-border adjustment mechanism scope represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Hybrid Construction Equipment Market