
 Truck Crane Market | 2026-2036
Truck Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Crane Market Outlook
The EU Green Deal's construction equipment decarbonization timeline is pivoting procurement criteria across European rental fleets. Tadano Ltd. sustains its telescopic crane leadership through integrated Japanese manufacturing. Zoomlion Heavy Industry Science & Technology Co. Ltd. dominates Chinese domestic infrastructure tenders with scale production. Liebherr Group anchors premium all-terrain positioning through German engineering specialization.
A truck crane integrates a hydraulically operated lifting boom mounted on a commercial truck chassis, typically achieving load ratings from five to over fifty tons through telescopic or articulating boom configurations designed for rapid site mobility and versatile load placement. The telescopic product type captures the largest volume share due to highway-speed transit requirements in urban construction logistics. Articulating variants occupy narrower-margin niches where maneuverability in confined European city centers justifies operational trade-offs. The rental deployment channel leads revenue contribution as fleet outsourcing reduces capital intensity for mid-sized contractors across North American and Asian markets.
The EPA's Tier 4 Final and upcoming Tier 5 emissions frameworks in the United States compel engine retrofit investments or new powertrain architectures for diesel-powered truck cranes entering regulated zones. China's MEE enforces national Stage IV emissions compliance, filtering non-conforming equipment from municipal and state-level procurement pools. ISO 4309 wire rope inspection standards and regional operator certification mandates collectively shape aftermarket service attach rates and residual value curves. Stakeholders must calibrate fleet composition between emission-compliant new units and extending legacy asset life through remanufacturing programs as regulatory phase-ins diverge across operating geographies.
Market Dynamics
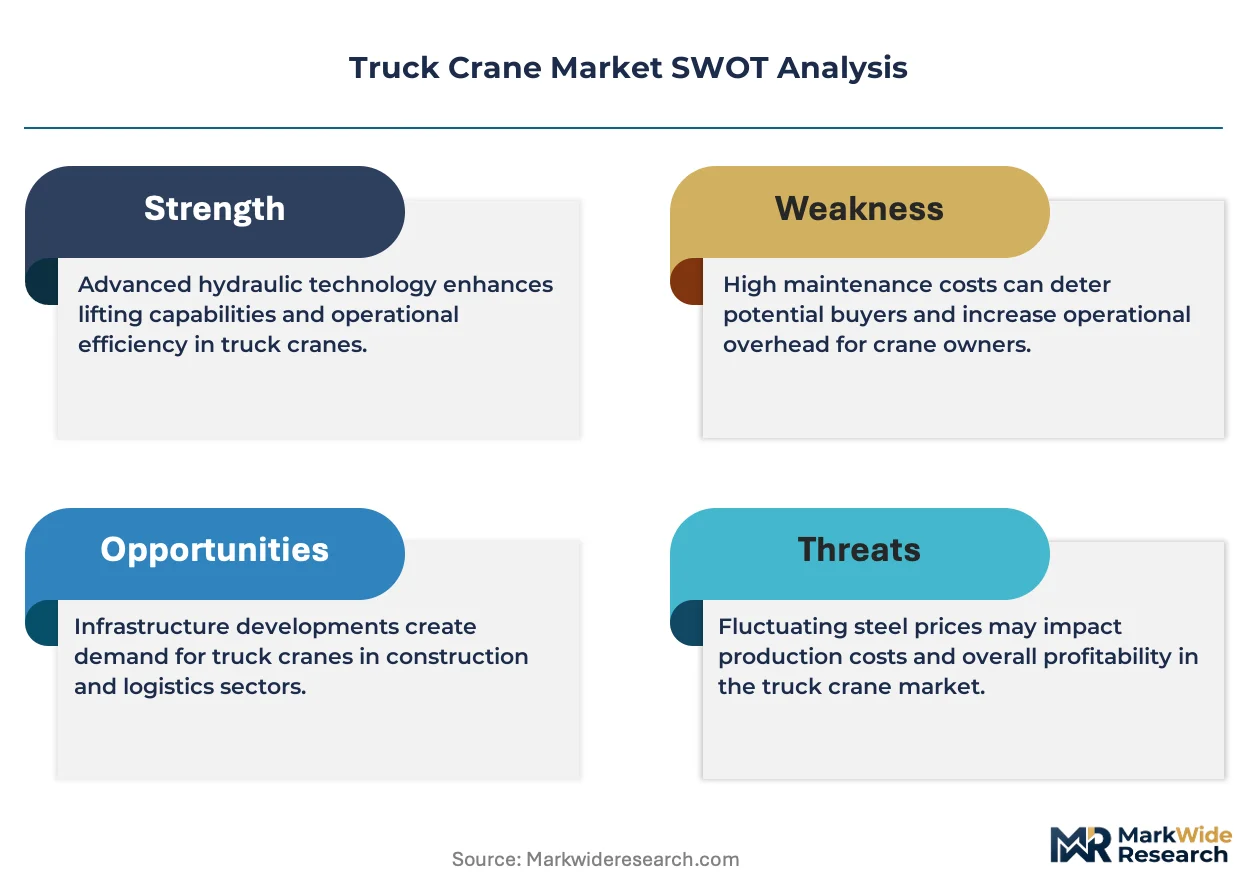
Engine electrification and hybrid powertrain development are compressing the operational cost structure for fleet operators while forcing capital reallocation across manufacturing and rental channels.
Growth Catalysts
- Indonesia's port modernization:State-backed infrastructure corridors are generating concentrated equipment procurement from domestic contractors and multinational fleet lessors.
- EU Green Deal construction decarbonization:The framework's equipment procurement criteria are redirecting rental fleet investment toward emission-compliant units.
- Telescopic boom configurations:Highway-speed transit capabilities are unifying urban logistics requirements across North American and Asian construction markets.
Market Restraints
- High-strength steel input volatility:Boom fabrication costs fluctuate with specialty alloy pricing from German and Japanese metallurgical suppliers.
- China's GB certification tightening:Mobile crane stability and emissions standards are filtering non-conforming equipment from municipal procurement pools.
- Used equipment import substitution:Secondary markets in Southeast Asia and Africa are absorbing price-sensitive demand that might otherwise flow to new unit sales.
Strategic Opportunities
- Vietnam's power grid expansion:Transmission line construction is opening fleet deployment corridors for rental operators with regional logistics networks.
- Telematics-integrated predictive maintenance:Sensor-enabled service models are converging with fleet management software to capture aftermarket revenue streams.
- India's PLI scheme for construction equipment:Domestic manufacturing incentives are creating localized assembly opportunities for multinational OEMs.
Industry Challenges
- Certified operator scarcity:ISO 4309 wire rope inspection standards and regional licensing mandates are constraining fleet utilization rates.
- Legacy diesel unit stranding risk:EPA Tier 5 and China Stage IV phase-ins are compressing residual value curves for non-compliant assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Crane Market |
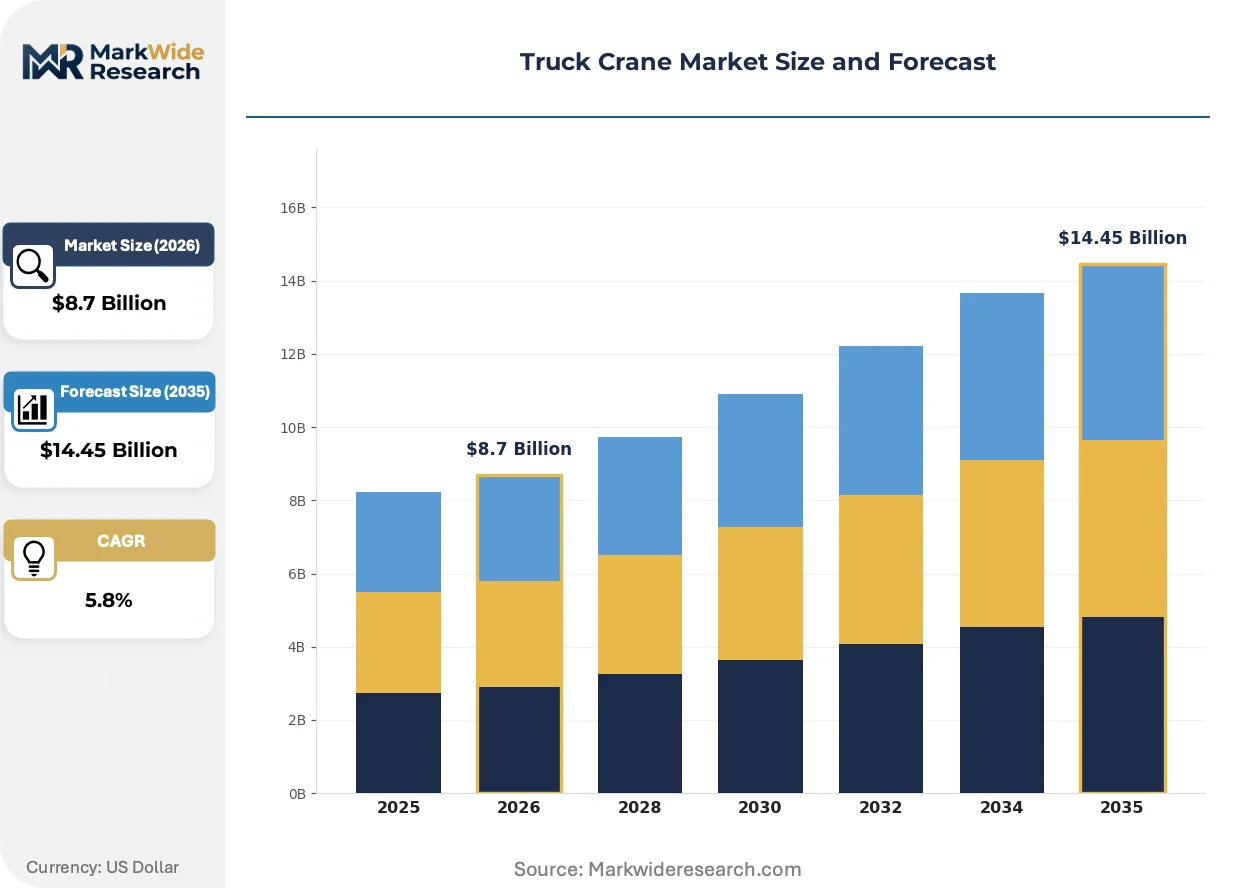
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic, Articulating, Rough Terrain, All Terrain End User: Construction, Oil & Gas, Mining, Transportation Capacity: 5 Ton, 10 Ton, 20 Ton, 50 Ton Deployment: On-Site, Off-Site, Rental, Direct Sales |
| Companies Covered | Tadano Ltd., Zoomlion Heavy Industry Science & Technology Co. Ltd., Liebherr Group, Altec, XCMG, Manitowoc Company Inc., SANY Group Co. Ltd., Grove, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Crane Market Strategic Shifts
Powertrain diversification and connected fleet management are restructuring capital deployment patterns across rental and contractor segments.
Hybrid-electric drivetrains are unifying crane operation and highway transit under single power management systems. European rental fleets are adopting these configurations fastest to meet municipal low-emission zone requirements. The technology is unifying previously separate engine architectures into modular platforms that reduce spare parts complexity.
China's MEE Stage IV emissions enforcement is removing non-compliant equipment from state-level procurement eligibility. Domestic manufacturers are accelerating engine redesign cycles to maintain tender access. Municipal construction authorities in Beijing, Shanghai, and Shenzhen are responding with accelerated fleet replacement schedules.
Equipment-as-a-service contracting is displacing traditional lease-to-own structures among mid-sized North American contractors. Rental operators are unbundling maintenance and telematics into subscription tiers. This model is most visible in Texas and California construction corridors where capital discipline pressures are strongest.
Truck Crane Market Segmentation
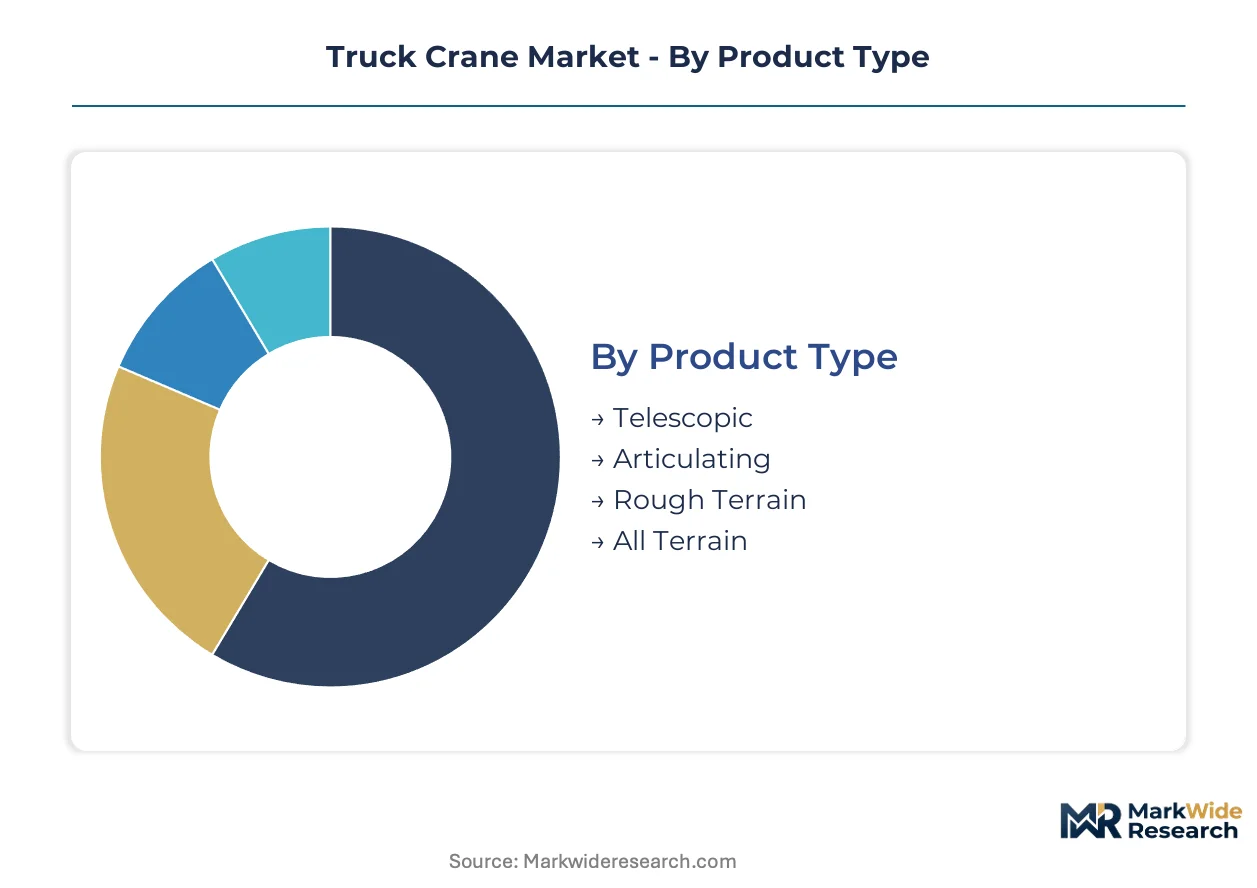
Truck crane procurement patterns diverge sharply between highway-speed logistics requirements and confined-site maneuverability needs. Fleet operators calibrate segment mix against urban density, emission zone access, and project duration economics.
Product Type:
Telescopic configurations dominate volume flows while articulating variants command premium positioning in constrained European city centers.
- Telescopic:Hydraulically extending boom sections enable highway-speed transit without disassembly, matching urban construction logistics demands across Indonesian port corridors and North American metropolitan buildouts. Highway mobility requirements unify procurement criteria across fleet operators in Indonesia's port modernization zones and Texas construction corridors.
- Articulating:Knuckle-boom geometry permits load placement through narrow street envelopes and overhead obstacles, justifying operational trade-offs where European municipal low-emission zones restrict larger equipment. Maneuverability premiums concentrate in Paris, Berlin, and Amsterdam urban renewal contracts where site access constraints override transit speed priorities.
- Rough Terrain:Outrigger-stabilized chassis with four-wheel drive for unimproved ground conditions.
- All Terrain:Dual-mode highway and off-road capability with multi-axle steering for European wind farm installation corridors.
Today's leader: Telescopic. Tomorrow's challenger: All Terrain hybrid-electric configurations.
End User:
Application-driven specifications separate mobile fleet requirements from fixed-site heavy-lift operations.
- Construction:Urban high-rise and infrastructure projects drive the largest equipment procurement volumes across rental fleet deployment channels.
- Oil & Gas:Refinery maintenance and pipeline construction demand explosion-proof electrical systems and extended boom reach specifications.
- Mining:Dust-sealed hydraulics and reinforced boom structures address abrasive operating environments in Australian and Chilean extraction zones.
- Transportation:Port container handling and intermodal yard operations require rapid cycle times and precision load placement.
Construction anchors current fleet utilization. Mining equipment replacement cycles are expanding most quickly as commodity price volatility extends asset lifespans.
Capacity:
Load rating tiers align with project scale economics and operator certification requirements.
- 5 Ton:Light utility applications and municipal maintenance fleets.
- 10 Ton:Mid-rise building materials handling dominates European rental fleet composition.
- 20 Ton:Infrastructure beam placement and precast component installation across Indonesian power grid expansion corridors.
- 50 Ton:Heavy industrial module lifting with specialized transport permitting requirements.
10 Ton and 20 Ton ratings capture overlapping demand zones. 50 Ton specifications are gaining share fastest as modular construction methods proliferate.
Deployment:
Capital intensity preferences segment ownership models across contractor size classes and project duration profiles.
- On-Site:Dedicated equipment for multi-year infrastructure projects with continuous utilization.
- Off-Site:Mobilization from regional equipment yards for intermittent project demands.
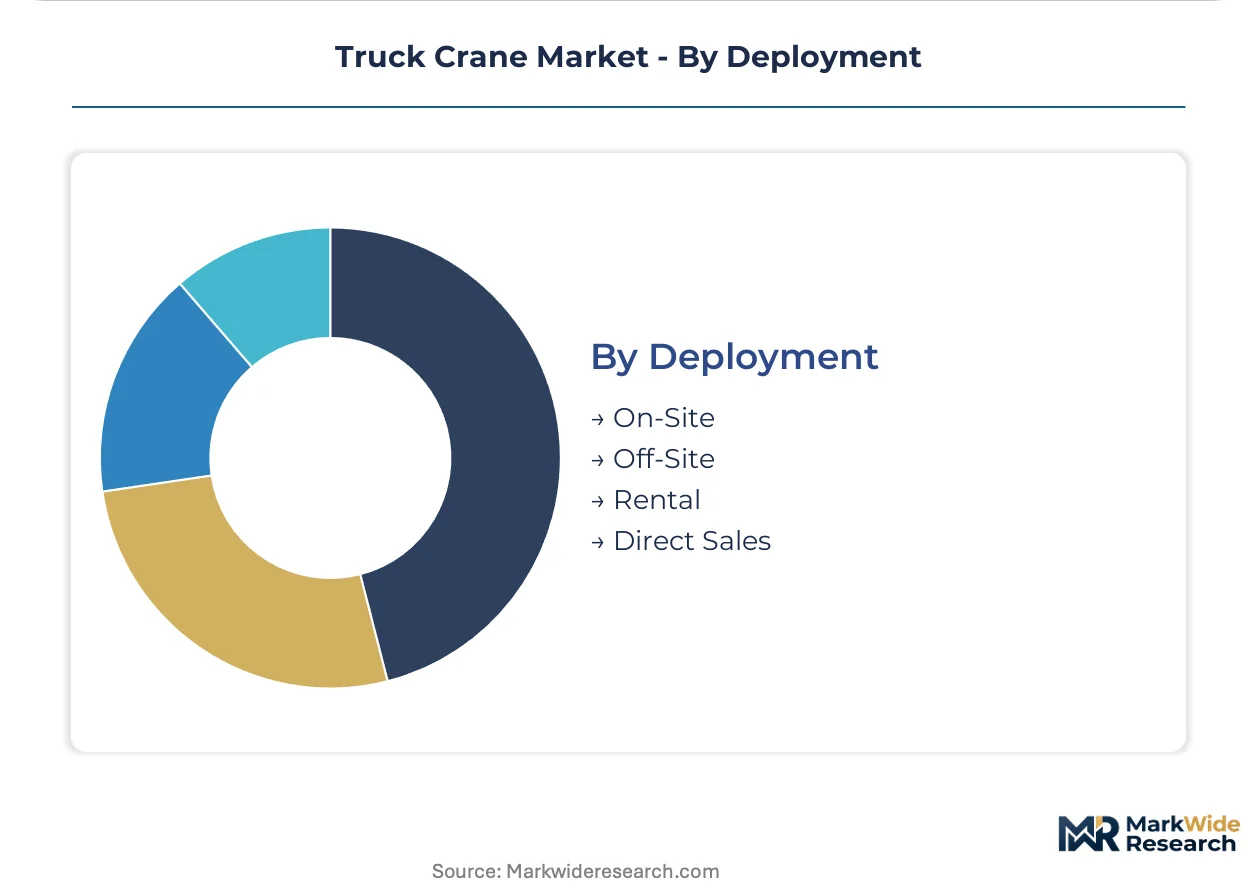
- Rental:Fleet outsourcing reduces capital commitment for mid-sized contractors across North American and Asian markets, with telematics-integrated service tiers capturing aftermarket revenue.
- Direct Sales:Large contractor and government fleet procurement with customized specification packages.
Rental channels lead revenue contribution. Equipment-as-a-service subscription models are climbing the fastest among Texas and California mid-market contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized crane operator pools in Germany, Japan, and the United States anchor the industry's technical workforce concentration. These talent clusters support precision manufacturing and complex deployment logistics across high-specification markets. Regional procurement patterns diverge sharply between emission-compliant European fleets and capacity-scaling Asian infrastructure corridors.
United States
Texas and California construction corridors drive telescopic crane deployment through equipment-as-a-service subscription growth. The EPA's Tier 4 Final and upcoming Tier 5 emissions frameworks compel engine retrofits or new powertrain investments for diesel-powered units entering regulated zones. Houston's petrochemical maintenance clusters and Dallas-Fort Worth urban buildouts concentrate fleet utilization among mid-market contractors.
Germany
Wind farm installation corridors across Lower Saxony and Bavaria demand all-terrain hybrid-electric configurations with multi-axle steering precision. The EU Green Deal's construction equipment decarbonization timeline redirects rental fleet investment toward emission-compliant units. Munich and Berlin municipal low-emission zones restrict non-conforming equipment, accelerating replacement schedules among regional lessors.
China
Beijing-Tianjin-Hebei and Yangtze River Delta infrastructure tenders concentrate demand for 20-ton and 50-ton load ratings in modular construction applications. The MEE enforces national Stage IV emissions compliance, filtering non-conforming equipment from municipal and state-level procurement pools. Shanghai and Shenzhen construction authorities have accelerated fleet replacement schedules in response.
Indonesia
Port modernization in Jakarta and Surabaya generates concentrated equipment procurement from domestic contractors and multinational fleet lessors. State-backed infrastructure corridors prioritize telescopic configurations for highway-speed transit between urban logistics nodes. Power grid expansion across Java and Sumatra opens deployment corridors for 20-ton rated units in transmission line construction.
Japan
Tokyo and Osaka urban renewal contracts prioritize maneuverability in confined site envelopes, sustaining demand for specialized articulating geometries. METI industrial standards and JIS certification requirements shape aftermarket service attach rates and residual value curves. Yokohama's port logistics clusters and Nagoya's manufacturing belt concentrate fleet deployment for precision load placement applications.
Truck Crane Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent manufacturing and rental channel strategies. Integrated foundry operations in Germany and Japan sustain premium positioning through captive metallurgical supply chains. The market structure organizes around three archetypes: scale-driven Chinese fabricators, precision-engineered European specialists, and vertically integrated Japanese manufacturers. Dominant competitive moves include hybrid powertrain platform development and telematics-integrated service model expansion.
Among Japanese manufacturers, Tadano Ltd. exemplifies the integrated production archetype through domestic telescopic crane leadership. Zoomlion Heavy Industry Science & Technology Co. Ltd. anchors the scale-driven tier with Chinese domestic infrastructure tender dominance. Liebherr Group occupies the premium engineering position through German all-terrain specialization. These three companies collectively represent the geographic and strategic poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Tadano Ltd. |
| Zoomlion Heavy Industry Science & Technology Co. Ltd. |
| Liebherr Group |
| Altec |
| XCMG |
| Manitowoc Company Inc. |
| SANY Group Co. Ltd. |
| Grove |
| Terex Corporation |
| Others |
Value Chain & Pricing Dynamics
Mid-sized construction contractors in Texas and California anchor procurement volumes through equipment-as-a-service subscriptions, compressing capital outlays into recurring operational expenditures that reshape manufacturer pricing power toward bundled service tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates manufacturer quotations, with ISO 4309 certification tiers and telematics integration depth serving as primary price differentiation drivers. Cost compression in the economy tier is intensifying because used equipment import substitution from Southeast Asian secondary markets absorbs price-sensitive demand. Rental fleet operators exhibit lowest price sensitivity due to service revenue capture, while independent contractors in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
GB standards certification and EPA Tier compliance requirements gate supplier access to municipal procurement pools in China and regulated US zones. Boom fabrication draws from German and Japanese high-strength steel metallurgical suppliers, with hydraulic system components sourced from Italian and South Korean precision manufacturers. Single-source vulnerability concentrates in specialty alloy supply chains. Distribution runs through regional equipment yards and multinational rental fleet networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strategic positioning in this market functions as a geographic-arbitrage play, with China's Stage IV emissions enforcement creating compliance-cost differentials against Southeast Asian markets where regulatory phase-ins lag.
For Market Incumbents: Anchor fleet replacement schedules in Beijing, Shanghai, and Shenzhen municipal procurement pools where accelerated compliance timelines concentrate demand. Deepen backward integration into captive metallurgical supply chains to defend margin position against high-strength steel input volatility. Prioritize hybrid powertrain platform development to preempt EPA Tier 5 stranding risk for legacy diesel assets. For New Entrants and Emerging Players: Equipment-as-a-service digital platforms offer the lowest barrier entry route for mid-market contractors in Texas and California construction corridors. Vietnam's power grid expansion corridors present the most penetrable white-space geography for rental operators with regional logistics networks. Pursue telematics-integrated predictive maintenance subscriptions as the primary go-to-market wedge. For Investors and Strategic Acquirers: Chinese construction equipment OEMs are the most active acquirer in this space, seeking manufacturing scale and tender access. Long-term viability hinges on emission-compliant product portfolio depth and aftermarket service attach rates. Monitor Indonesia's port modernization procurement velocity as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Platform Development | Unifies crane operation and highway transit under single power management systems for EU Green Deal compliance. |
| Telematics-Integrated Service Tier Expansion | Captures aftermarket revenue streams through sensor-enabled predictive maintenance models for rental fleets. |
| Backward Integration into Metallurgical Supply | Secures captive high-strength steel access from German and Japanese suppliers against input volatility. |
| Regional Equipment Yard Network Expansion | Establishes mobilization corridors for intermittent project demands across Indonesian infrastructure zones. |
| Stage IV Emissions Certification Investment | Maintains municipal and state-level procurement eligibility under China's MEE enforcement framework. |
Study Parameters
Direct dialogue with fleet operations directors, OEM procurement managers, aftermarket service heads, and municipal construction authority planners grounded qualitative findings. Secondary validation incorporated customs trade data, SEC 10-K filings from listed equipment manufacturers, EPA emissions compliance databases, and Chinese GB standards documentation. Bottom-up equipment deployment estimates triangulated against top-down infrastructure investment flows.
Segmented outputs across product type, capacity tier, deployment channel, and end-use application modeled demand patterns over the projection horizon. CAGRs derived from regression analysis against historical fleet replacement cycles and infrastructure tender pipelines. Hybrid powertrain adoption curves and emission regulation phase-in schedules served as primary forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for battery-electric drivetrains would alter the outlook for diesel unit residual values. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and commodity price stability. A model refresh is warranted upon material change in Indonesia's port modernization procurement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Induction Furnace Market