
 Used Backhoe Market | 2026-2036
Used Backhoe Market Size, Share, and Industry Trends Forecast 2026-2036
Used Backhoe Market Analytics
Modular attachment bundling is recalibrating buyer choice in the used backhoe channel. Caterpillar Inc. leverages its dealer network to package hydraulic quick-couplers with certified pre-owned units. John Deere anchors its position through PowerReverser transmission warranties that transfer to second owners. Komatsu Ltd. competes on remanufactured hydraulic system reliability in mining resale.
A used backhoe is a wheeled or tracked excavator-loader hybrid with an articulated boom-mounted bucket on the rear and a front loader arm, typically powered by diesel engines from 60 to 120 horsepower, designed for trenching, material handling, and site preparation in confined work zones. Standard backhoes dominate resale volume in construction applications due to their balance of reach and transportability, while mini backhoes capture expanding landscaping demand where site access limits machine footprint. Certified pre-owned condition units command pricing premiums because dealer servicing records reduce buyer uncertainty in auction and direct sales channels.
The EPA enforces Tier 4 Final emission standards that restrict resale eligibility for pre-2014 diesel backhoes in regulated counties, while OSHA excavation safety rules mandate operator certification that sustains demand for machines with ROPS-certified cabs. ISO 9001 remanufacturing protocols and CE marking requirements in Europe shape cross-border refurbishment quality benchmarks. Stakeholders must monitor how telematics data portability affects residual value calculations as connected fleet history becomes a tradable asset in secondary markets.
Market Dynamics
EPA Tier 4 Final emission standards are structurally culling the pre-2014 diesel backhoe population, forcing municipal fleets and independent contractors toward certified remanufactured units with compliant powertrains and documented service histories.
Growth Catalysts
- Utility infrastructure mandates:Gas pipeline maintenance programs in the southeastern United States are sustaining demand for standard backhoes with verified hydraulic system integrity and ROPS-certified operator cabs.
- Telematics data portability:Connected fleet history is becoming a tradable asset in secondary markets, with machine-hour logs and maintenance records reducing buyer uncertainty in auction channels.
- REACH compliance protocols:European remanufacturing facilities adhering to CE marking and ISO 9001 refurbishment standards are unlocking cross-border resale eligibility for Tier 4-equivalent units.
Market Restraints
- Steel and hydraulic component volatility:Input cost fluctuations for boom fabrication and cylinder remanufacturing are compressing refurbishment margins for independent dealers.
- Supply concentration in certified dealer networks:OEM-controlled distribution of warranty-transferable units limits auction liquidity and price discovery for non-affiliated resellers.
- Battery-electric substitution threat:Compact electric excavators are capturing landscaping site-access applications where mini backhoes previously dominated resale volume.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and rural electrification projects are creating demand for cost-optimized used standard backhoes with PowerReverser transmission durability.
- OSHA excavation safety alignment:Operator certification mandates are sustaining premium pricing for machines with documented ROPS cab integrity and hydraulic system reliability.
- Auction platform digitization:Online remarketing channels with embedded telematics verification are compressing transaction friction and expanding geographic buyer pools beyond traditional regional markets.
Industry Challenges
- Certified hydraulic technician scarcity:Remanufacturing capacity is constrained by limited workforce pipeline for high-pressure system rebuilds and quick-coupler integration.
- Telematics standardization fragmentation:Proprietary data formats from OEM-connected fleets are creating integration complexity for independent valuation platforms and cross-brand resale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Backhoe Market |
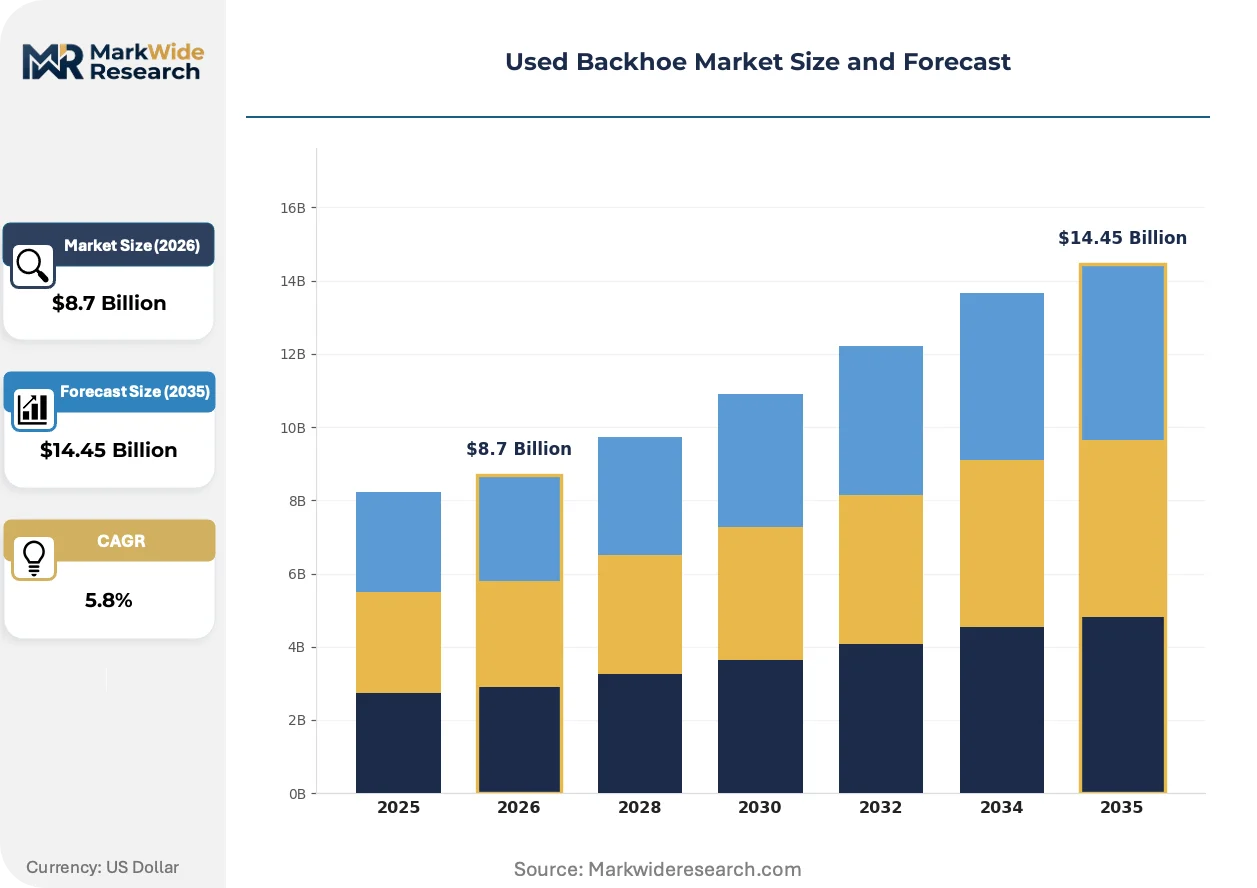
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Backhoes, Standard Backhoes, Large Backhoes, Urban Backhoes End User: Construction, Agriculture, Landscaping, Mining Distribution Channel: Direct Sales, Dealers, Auctions, Online Marketplaces Condition: Refurbished, As-Is, Certified Pre-Owned, Fully Serviced |
| Companies Covered | Caterpillar Inc., John Deere, Case CE, JCB, Volvo Construction Equipment, Komatsu Ltd., Hitachi Construction Machinery, CNH Industrial NV, Doosan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Backhoe Market Evolving Landscape
Digital verification tools and modular attachment architectures are restructuring how buyers evaluate residual value and operational flexibility in secondary equipment markets.
Quick-coupler hydraulic systems are modularizing the functional identity of used backhoes. Municipal fleets in Texas and Florida are retrofitting certified pre-owned standard units with interchangeable trenching, grapple, and auger attachments. This modularity is compressing the traditional trade-off between reach specifications and transportability that once segmented buyer preferences.
EPA enforcement of Tier 4 Final standards is eliminating resale eligibility for non-compliant diesel units in regulated counties. Equipment owners in California and New York are accelerating trade-in cycles ahead of county-level registration deadlines. Mining contractors in Arizona and Nevada are absorbing compliant remanufactured units to maintain operational continuity.
Buyer preference is gravitating toward machines with exportable telematics histories. Utility contractors now screen auction listings for connected fleet documentation before physical inspection. This behavioral shift is most pronounced in the southeastern United States where gas pipeline maintenance contracts require verifiable machine-hour records for insurance and bonding compliance.
Used Backhoe Market Segmentation
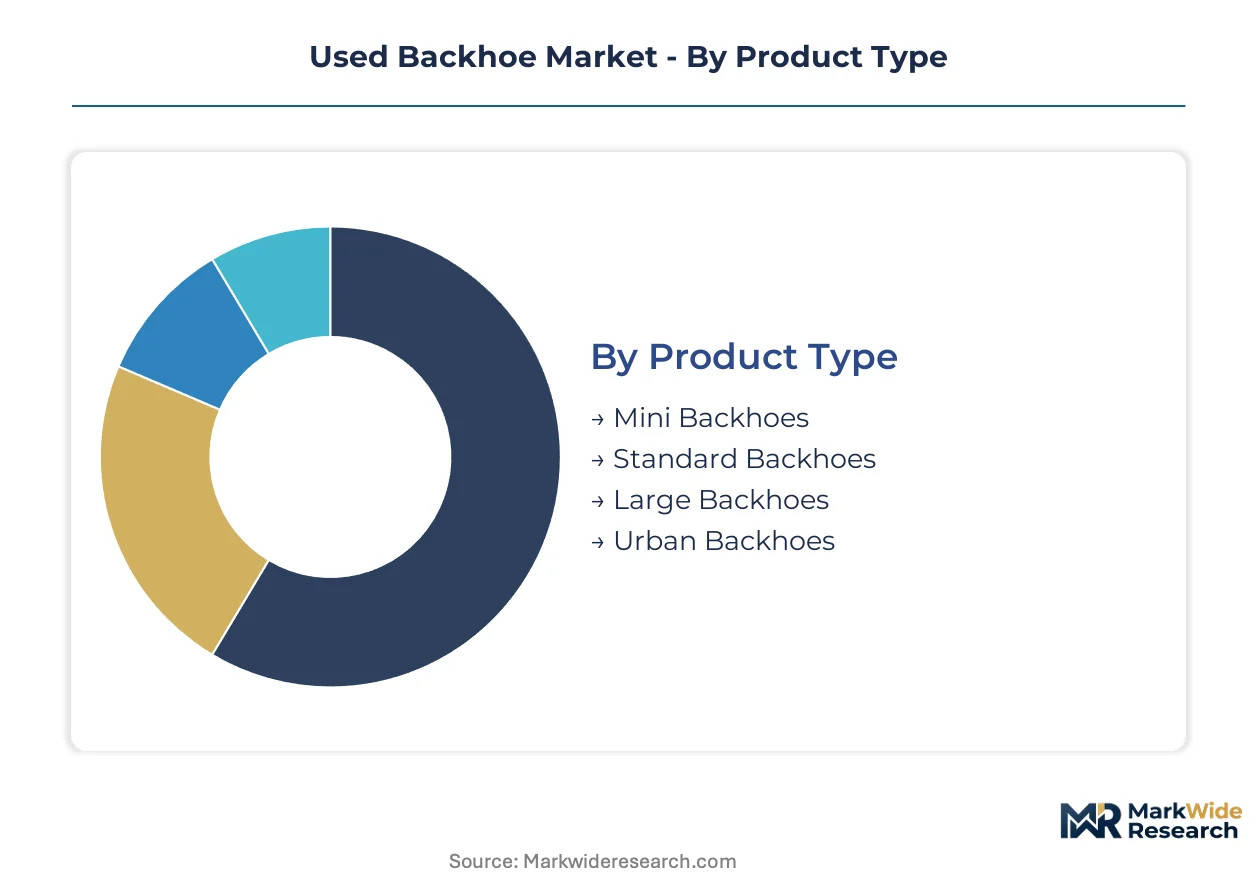
Backhoe resale channels fragment across four structural dimensions that determine pricing power and buyer risk tolerance. Product type and condition grade together dictate residual value, while distribution channel selection shapes warranty transferability and telematics verification access.
Product Type:
Standard backhoes dominate unit volume in construction applications, while mini backhoes command expanding premiums in landscaping where site access constraints limit machine footprint.
- Standard Backhoes:Wheeled excavator-loader hybrids with 60-120 horsepower diesel engines balance reach specifications against transportability for trenching and material handling. Municipal fleets in Texas and Florida prioritize these units for gas pipeline maintenance programs requiring ROPS-certified cabs and verified hydraulic integrity.
- Mini Backhoes:Compact footprint machines under 8,000 pounds capture landscaping demand where residential site access prohibits larger equipment. Battery-electric excavators are displacing this segment in urban green space maintenance applications.
- Large Backhoes:High-horsepower units above 120 horsepower serve mining and heavy civil applications with extended reach requirements.
- Urban Backhoes:Specialized compact designs with zero-tail-swing configurations navigate confined street corridors and utility vaults.
Today's leader: Standard Backhoes. Tomorrow's challenger: Mini Backhoes.
End User:
Construction contractors absorb the majority of certified pre-owned volume, while utility infrastructure mandates sustain premium pricing across municipal procurement channels.
- Construction:General contractors and specialty trades drive standardized backhoe demand for site preparation and foundation work. EPA Tier 4 compliance requirements are forcing fleet turnover toward remanufactured units with documented service histories.
- Agriculture:Farm operators favor PowerReverser transmission durability for loader-intensive tasks in dairy and livestock operations.
- Landscaping:Residential and commercial grounds maintenance contractors prioritize mini backhoes with quick-coupler attachment versatility.
- Mining:Surface extraction operations in Arizona and Nevada absorb remanufactured hydraulic systems with extended cylinder warranties.
Construction sets the volume baseline. Utility infrastructure programs in the southeastern United States are climbing the fastest.
Distribution Channel:
Dealer networks capture warranty-transferable transactions, while auction digitization is compressing price discovery friction for as-is equipment.
- Direct Sales:Fleet-to-fleet transactions between municipal departments and large contractors with established maintenance documentation.
- Dealers:OEM-affiliated networks package certified pre-owned units with hydraulic quick-couplers and transferable transmission warranties.
- Auctions:Physical and online remarketing channels with embedded telematics verification expand geographic buyer pools beyond regional markets.
- Online Marketplaces:Digital platforms with machine-hour log integration reduce buyer uncertainty in peer-to-peer transactions.
Dealers control the premium tier. Online marketplaces with telematics verification are gaining share fastest.
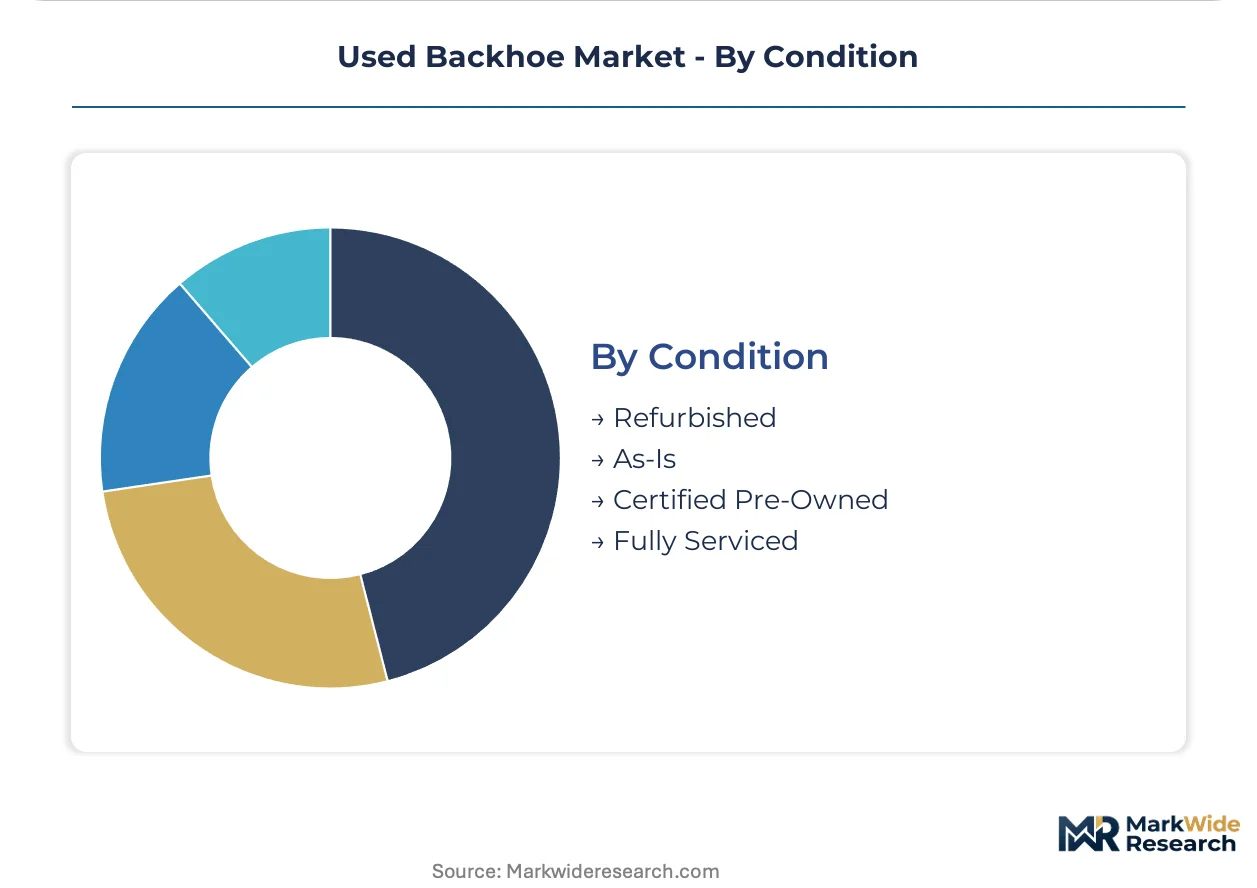
Condition:
Certification grade determines pricing stratification, with dealer servicing records reducing buyer uncertainty in auction and direct sales channels.
- Certified Pre-Owned:Dealer-remanufactured units with ISO 9001 refurbishment protocols and transferable warranties command substantial premiums.
- Fully Serviced:Independent dealer rebuilds with documented hydraulic system pressure testing and cab integrity verification.
- Refurbished:Component-level rebuilds addressing Tier 4 emission compliance through powertrain replacement.
- As-Is:Uninspected units trading at discount for buyer-assumed remanufacturing risk.
Certified Pre-Owned anchors pricing power. Refurbished Tier 4-compliant units represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The used backhoe market traces its commercial scale to post-war American infrastructure buildouts, where municipal fleets in Texas and Florida pioneered standardized refurbishment protocols for trenching equipment. Equipment trading networks subsequently expanded across industrialized economies as emission regulations forced fleet turnover cycles.
United States
Gas pipeline maintenance programs in Texas and Florida sustain demand for certified pre-owned standard backhoes with ROPS-certified cabs. EPA Tier 4 Final enforcement eliminates resale eligibility for pre-2014 diesel units in California and New York counties. Houston-area equipment dealers anchor the southeastern refurbishment cluster, packaging hydraulic quick-couplers with transferable warranties.
Germany
REACH compliance protocols and CE marking requirements shape cross-border remanufacturing quality benchmarks for Tier 4-equivalent units. The country's national environmental regulator enforces stringent refurbishment documentation standards. Bavarian industrial zones concentrate ISO 9001-certified hydraulic system rebuild facilities serving central European resale channels.
India
National highway expansion and rural electrification projects generate demand for cost-optimized used standard backhoes with PowerReverser transmission durability. The Bureau of Indian Standards mandates equipment safety certifications for infrastructure procurement. Maharashtra and Gujarat host the dominant secondary equipment trading hubs for subcontinent distribution.
China
Mining contractors in western provinces absorb remanufactured hydraulic systems with extended cylinder warranties for surface extraction operations. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate diesel fleet retirement timelines. Sichuan-Chongqing industrial corridors concentrate hydraulic component remanufacturing capacity.
Australia
Surface mining operations in Western Australia and Queensland sustain demand for large backhoes with verified hydraulic integrity above 120 horsepower. The national workplace safety regulator mandates ROPS cab certification for excavation contracting. Perth equipment dealers specialize in high-hour unit refurbishment for Pilbara iron ore maintenance fleets.
Used Backhoe Market Competitive Landscape
The competitive structure tilts toward OEM-affiliated dealer networks with warranty-transferable inventory. Equipment manufacturers with captive finance arms and certified pre-owned programs command pricing premiums over independent resellers. Three archetypes dominate: integrated machinery conglomerates with full-line distribution, specialized hydraulic remanufacturers serving mining sectors, and digital auction platforms with embedded telematics verification. Consolidation pressures intensify through dealer network expansion and proprietary data format lock-in.
Within the integrated machinery tier, Caterpillar Inc. and John Deere exemplify dealer-network dominance through transferable warranty programs and certified refurbishment protocols. Komatsu Ltd. occupies a distinct position among Japanese manufacturers emphasizing remanufactured hydraulic system reliability for mining resale applications.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| John Deere |
| Case CE |
| JCB |
| Volvo Construction Equipment |
| Komatsu Ltd. |
| Hitachi Construction Machinery |
| CNH Industrial NV |
| Doosan Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between dealer-remanufactured units and as-is auction inventory manifests in parallel supply chain configurations: OEM-affiliated networks capture warranty-transferable premiums through captive refurbishment capacity, while independent dealers absorb compressed margins on component-rebuild Tier 4 compliance conversions.
Pricing Analysis
Three-tier pricing structure across certified pre-owned, fully serviced, and as-is condition grades anchors transaction economics. Price differentiation centers on ISO 9001 refurbishment documentation and transferable warranty coverage versus buyer-assumed remanufacturing risk. Pricing pressure stems from steel and hydraulic component input volatility squeezing independent dealer margins. Municipal procurement channels show lowest price sensitivity due to bonding compliance requirements, while landscaping contractors exhibit highest sensitivity to upfront acquisition costs.
Supply Chain Analysis
Reverse-logistics flows for hydraulic cylinder remanufacturing and powertrain refurbishment concentrate refurbishment capacity in the United States, Germany, and India. Used backhoe supply chains draw from specialized steel fabrication for boom assemblies, high-pressure hydraulic component casting, and Tier 4-compliant diesel engine cores. Single-source vulnerability sits with certified hydraulic technician scarcity constraining remanufacturing throughput. Distribution runs through OEM-affiliated dealer networks for warranty-transferable units, with auction digitization expanding geographic reach for as-is inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The used backhoe market compounds steadily as EPA Tier 4 enforcement perpetuates forced fleet turnover cycles and sustains refurbishment demand across municipal and contractor segments.
For Market Incumbents: Extend transferable warranty programs to cover telematics data portability, locking in buyer preference for connected fleet histories. Deepen backward integration into hydraulic component remanufacturing to defend margin position against steel price volatility. Battery-electric excavator substitution in landscaping applications threatens mini backhoe resale volumes; anchor defensive positioning through quick-coupler attachment bundling on standard units.
For New Entrants and Emerging Players: Enter via auction platform digitization with embedded machine-hour verification, capturing price discovery friction reduction in peer-to-peer transactions. Target independent dealer networks in India and southeastern United States utility corridors where infrastructure buildout sustains demand for cost-optimized PowerReverser transmission units. Lead with telematics data standardization as a go-to-market wedge against OEM proprietary format lock-in.
For Investors and Strategic Acquirers: Consolidation pressure builds where telematics standardization fragmentation and certified technician scarcity constrain independent scaling capacity. Long-term viability favors platforms with cross-border refurbishment certification and connected fleet data assets. Watch OSHA excavation safety rule enforcement intensity and county-level Tier 4 registration deadline acceleration as inflection signals for remanufacturing capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydraulic Quick-Coupler Bundling | Caterpillar dealer networks package modular attachments with certified pre-owned units to compress buyer trade-off calculus. |
| Telematics Data Portability Investment | Machine-hour log exportability reduces auction buyer uncertainty and sustains premium pricing in utility procurement channels. |
| PowerReverser Transmission Warranty Transfer | John Deere anchors agricultural and infrastructure resale through second-owner coverage on loader-intensive applications. |
| ISO 9001 Refurbishment Certification | CE marking alignment unlocks cross-border resale eligibility for European remanufacturing facilities serving Tier 4-equivalent demand. |
| Online Remarketing Platform Expansion | Embedded telematics verification compresses transaction friction and expands geographic buyer pools beyond traditional regional markets. |
Research Methodology
Direct dialogue with equipment fleet managers, municipal procurement officers, OEM aftermarket service directors, and independent hydraulic remanufacturing technicians grounded qualitative assessment. Secondary validation drew from EPA enforcement documentation, OSHA excavation safety rule filings, equipment auction transaction records, and ISO 9001 certification registries. Bottom-up unit volume modeling and top-down market sizing triangulated across dealer network inventory data and regional fleet turnover surveys.
Segment-level projections across product type, condition grade, distribution channel, and end-use application generated volume and value estimates across the analysis window. CAGRs derived from regression analysis of historical replacement cycle patterns, emission regulation phase-in schedules, and infrastructure spending commitments. Forecast inputs incorporated hydraulic technician workforce pipeline constraints and telematics data format standardization trajectories.
Inputs from dealer service records and auction transaction databases were available through the study window; gaps in independent remanufacturer cost structure disclosure introduce uncertainty bands around refurbishment margin projections. Forecasts reflect documented assumptions regarding EPA county-level enforcement uniformity and steel price trajectory stability. Practitioners should monitor battery-electric excavator substitution rates in landscaping applications and telematics interoperability standard adoption for early signals of segment displacement risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Europe Crane Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Winch Market
Construction Equipment
North America Mobile Light Tower Market