
 Heavy Construction Equipment Market | 2026-2036
Heavy Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Construction Equipment Market Intelligence
Chinese manufacturers, having saturated domestic capacity, are pivoting toward export-led growth models targeting Southeast Asia and Latin America. Caterpillar leverages its extensive global dealer network and brand recognition to maintain a strong position in established markets. Komatsu differentiates through its focus on autonomous haulage systems and smart construction technologies. Volvo Construction Equipment specializes in electric and hybrid models, aligning with sustainability goals in Europe.
Heavy construction equipment comprises mobile machinery designed for earthmoving, lifting, and material handling tasks on large-scale civil engineering and mining projects. These machines typically feature high-capacity hydraulic systems and powerful diesel or electric powertrains to generate immense torque and lifting force. Excavators and loaders constitute the largest product segments by volume, essential for site development and material handling applications. The rental services end-user segment is expanding as contractors seek to minimize capital expenditure, with electric models gaining traction in this channel.
Emissions standards, such as the EPA's Tier 4 Final in the United States and Europe's Stage V, mandate reductions in NOx and particulate matter. Regulations like the EU's CE marking govern machine safety and operational standards, while China's MEE sets strict domestic pollution controls. Manufacturers must now decide how to balance investment between legacy diesel platforms and the development of next-generation electric and autonomous equipment.
Market Dynamics
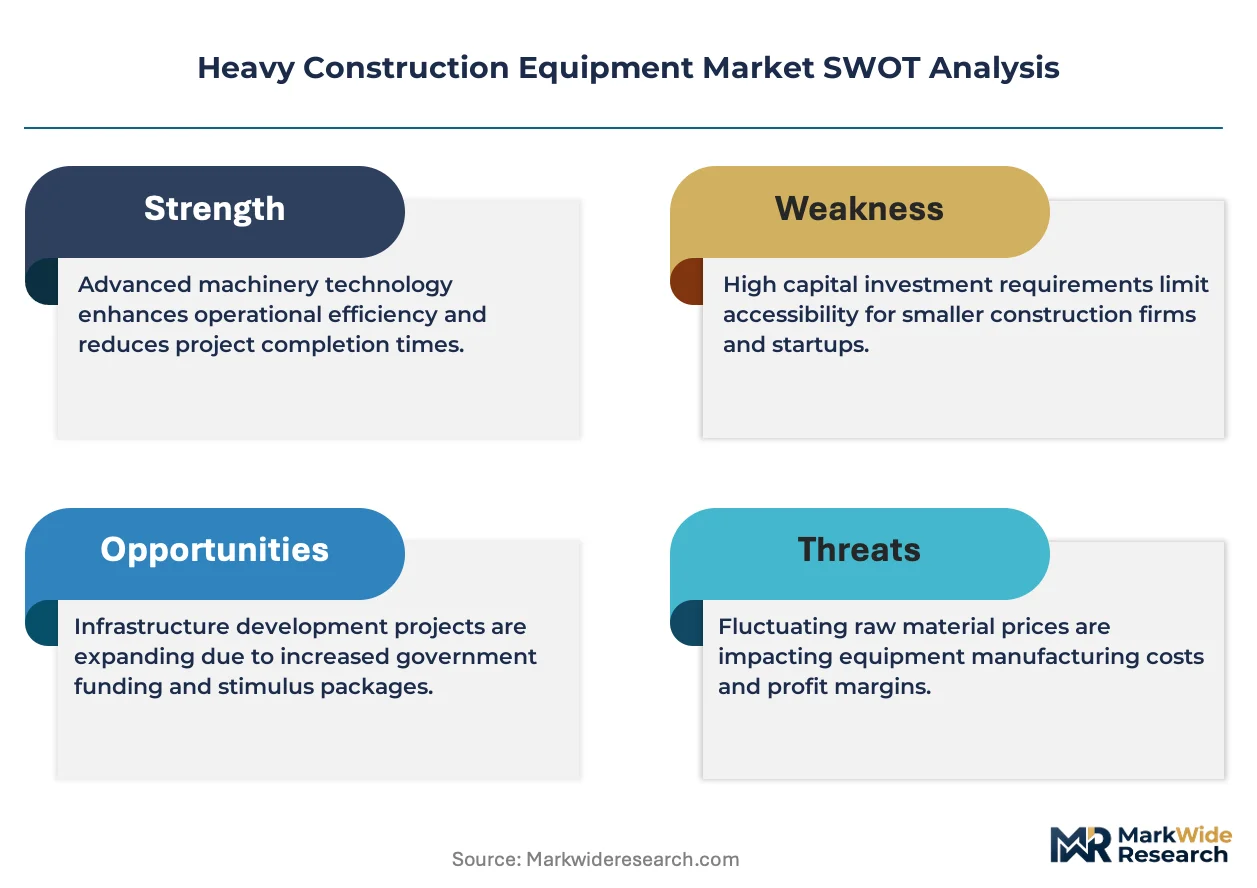
The central force shaping the market is the capital-intensive transition from diesel platforms to electric and autonomous systems. This shift is compelled by stringent emissions regulations and evolving operational economics.
Growth Catalysts
- Infrastructure Investment:Government programs, like India's National Infrastructure Pipeline, create sustained demand for earthmoving and road construction machinery.
- Urbanization Projects:Large-scale urban development and public transportation projects stimulate sales of compact and specialized equipment.
- Emissions Regulations:Strict standards like EU Stage V accelerate the industry's pivot toward developing and marketing electric powertrain options.
Market Restraints
- High Capital Costs:The significant upfront investment for electric and autonomous equipment is a major barrier for smaller contractors.
- Input Material Volatility:Price fluctuations in steel and semiconductor shortages create production instability and margin pressure.
- Battery Technology Limits:Current battery energy density restricts the runtime and performance of large electric machines in remote mining applications.
Strategic Opportunities
- Equipment-as-a-Service (EaaS):Expanding rental and subscription models allows contractors to access modern equipment while minimizing capital expenditure.
- Modular Power Systems:Developing swappable battery packs for electric equipment can solve on-site charging delays and extend operational uptime.
- Export Market Penetration:Targeting infrastructure projects in Latin America and Southeast Asia offers a growth avenue for established diesel models.
Industry Challenges
- Skilled Labor Gap:A shortage of technicians trained to service complex electronics, telematics, and hydraulics hinders equipment uptime and increases maintenance costs.
- Regulatory Fragmentation:Manufacturers must engineer multiple engine configurations to comply with divergent emissions standards like the EPA's Tier 4 Final.
- System Interoperability:Ensuring seamless data exchange between mixed-fleet telematics platforms and construction management software remains a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Construction Equipment Market |
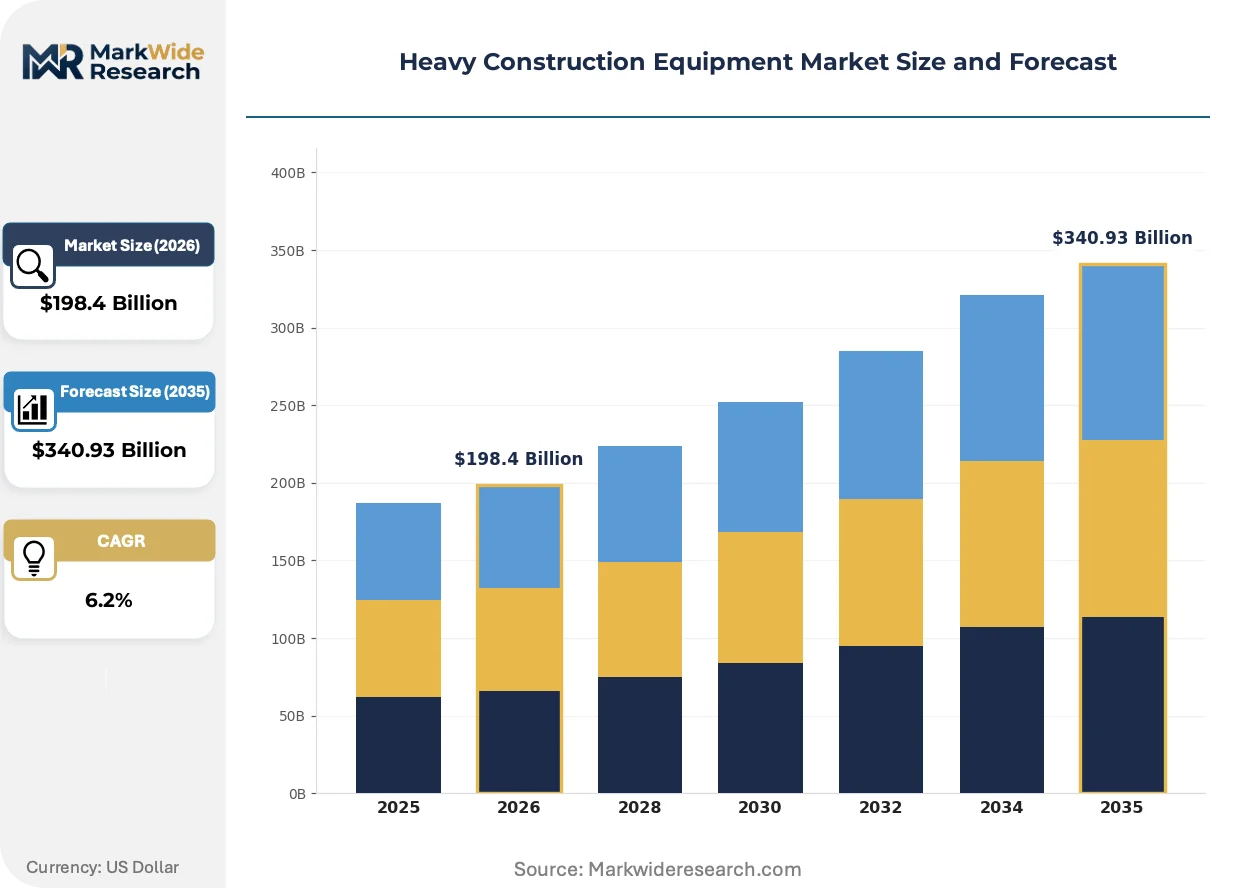
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $340.93 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Loaders, Cranes End User: Construction Companies, Government Projects, Mining Operations, Rental Services Technology: Hydraulic, Electric, Diesel, Hybrid Application: Road Construction, Site Development, Demolition, Material Handling |
| Companies Covered | XCMG, Sany, Caterpillar, Volvo Construction Equipment, Hitachi Construction Machinery, Komatsu, Liebherr, JCB, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Construction Equipment Market Strategic Shifts & Innovations
The industry is being reshaped by the convergence of digitalization and decarbonization mandates. These forces compel a re-evaluation of equipment design, fleet management, and the underlying business models for asset utilization.
Autonomous Haulage Systems (AHS) use GPS, LiDAR, and AI to guide unmanned trucks in controlled environments like large mines. Major mining operators are the primary adopters, seeking to enhance site safety and operational efficiency. This technology is automating repetitive material transport, reducing labor dependency and optimizing fuel consumption.
Europe's Stage V emissions standard mandates sharp reductions in particulate matter and NOx from non-road mobile machinery. This forces manufacturers to integrate complex after-treatment systems like diesel particulate filters into their engine platforms. The earthmoving segment is most affected, accelerating the push toward hybrid and electric models in the EU.
A distinct behavioral change is the move from direct equipment ownership toward flexible rental and subscription-based access. This trend disrupts traditional dealer sales, favoring large rental fleets and direct manufacturer leasing programs. The shift is most visible in North American and European urban construction, where tight project budgets are common.
Heavy Construction Equipment Market Segmentation
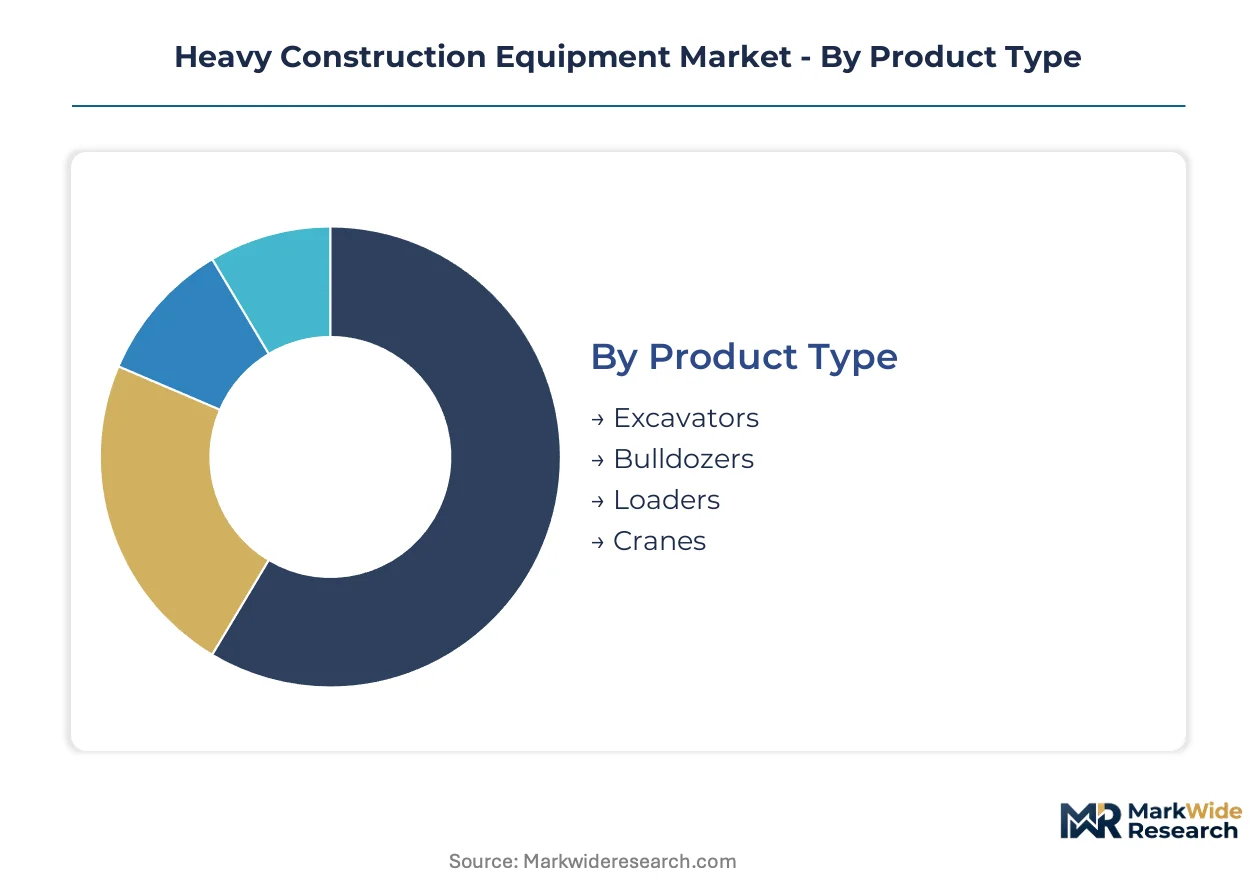
The heavy construction equipment market segments across product type, end-user, technology, and application, reflecting diverse operational needs and regulatory pressures. Understanding these distinctions helps manufacturers tailor product development and market strategies. Each segment faces unique challenges and opportunities driven by infrastructure investment and technological advancements.
Product Type:
Different heavy construction equipment product types face varying certification burdens, with some requiring specific safety and emissions approvals like the EU's CE marking or EPA's Tier 4 Final for engines.
- Excavators:These machines utilize a bucket, arm, and cab on a rotating platform for digging and material loading. Their hydraulic systems generate immense force, making them essential for large-scale earthmoving and trenching operations in urban development projects across India and China.
- Loaders:Designed for scooping and transporting loose materials like sand, gravel, or asphalt, loaders feature large front-mounted buckets. They are critical for material handling on construction sites and in mining operations, supporting efficient logistics in North American and European markets.
- Bulldozers:Powerful tracked machines with a broad front blade for pushing earth and debris. They are fundamental for land clearing and grading tasks.
- Cranes:These machines lift and move heavy objects using cables, ropes, and sheaves. They are indispensable for erecting structures and assembling large components.
Excavators sit at the top of the volume ranking, with Loaders climbing the fastest.
End User:
End-user segments exhibit distinct purchasing behaviors based on their operational scale and capital expenditure capabilities, influencing equipment acquisition strategies.
- Construction Companies:These firms represent the largest end-user segment, acquiring diverse equipment for residential, commercial, and industrial building projects. Their demand is driven by project pipelines and the need for reliable, high-performance machinery.
- Rental Services:This segment provides equipment to contractors on a temporary basis, minimizing capital outlay for project-specific needs. Rental fleets increasingly incorporate electric models to meet sustainability targets and offer flexible access.
- Government Projects:Public sector initiatives, including national infrastructure programs, drive demand for heavy machinery. These projects often prioritize durability and long-term operational efficiency.
- Mining Operations:Large-scale mining requires specialized, high-capacity equipment for material extraction and transport. Autonomous haulage systems are gaining traction.
Construction companies represent the largest procurement volume, while rental services are gaining share rapidly.
Technology:
Technology choices in heavy construction equipment are primarily driven by specific application requirements and evolving environmental compliance objectives.
- Diesel:Traditional diesel powertrains remain prevalent due to their high power density and established refueling infrastructure. Manufacturers integrate complex after-treatment systems to meet emissions standards like Europe's Stage V and EPA's Tier 4 Final.
- Electric:Electric models, powered by batteries, offer zero-emission operation and reduced noise levels, aligning with stricter urban environmental regulations. They are gaining traction in rental fleets and smaller-scale applications where charging infrastructure is accessible.
- Hydraulic:Hydraulic systems form the backbone of most heavy equipment, providing immense force for digging, lifting, and pushing. They ensure precise control.
- Hybrid:Hybrid systems combine diesel engines with electric motors to improve fuel efficiency and reduce emissions. These models offer a transitional solution.
Diesel powertrains continue to dominate legacy fleets, but electric models are experiencing the steepest expansion trajectory.
Application:
The volume of equipment deployed across different applications reflects the scale and frequency of specific construction activities globally.
- Site Development:This application involves land clearing, excavation, and grading to prepare areas for construction. It requires a wide array of earthmoving equipment, including excavators and bulldozers, for initial project phases in burgeoning urban centers.
- Road Construction:Building and maintaining roads, highways, and bridges demands specialized machinery for paving, compacting, and material transport. Government infrastructure projects, particularly in India, are significant drivers for this segment.
- Demolition:This involves dismantling structures, requiring specialized excavators with attachments like hydraulic breakers and shears. Safety and precision are paramount.
- Material Handling:Tasks like loading, unloading, and transporting materials on job sites fall under this application. Loaders and cranes are essential for efficient logistics.
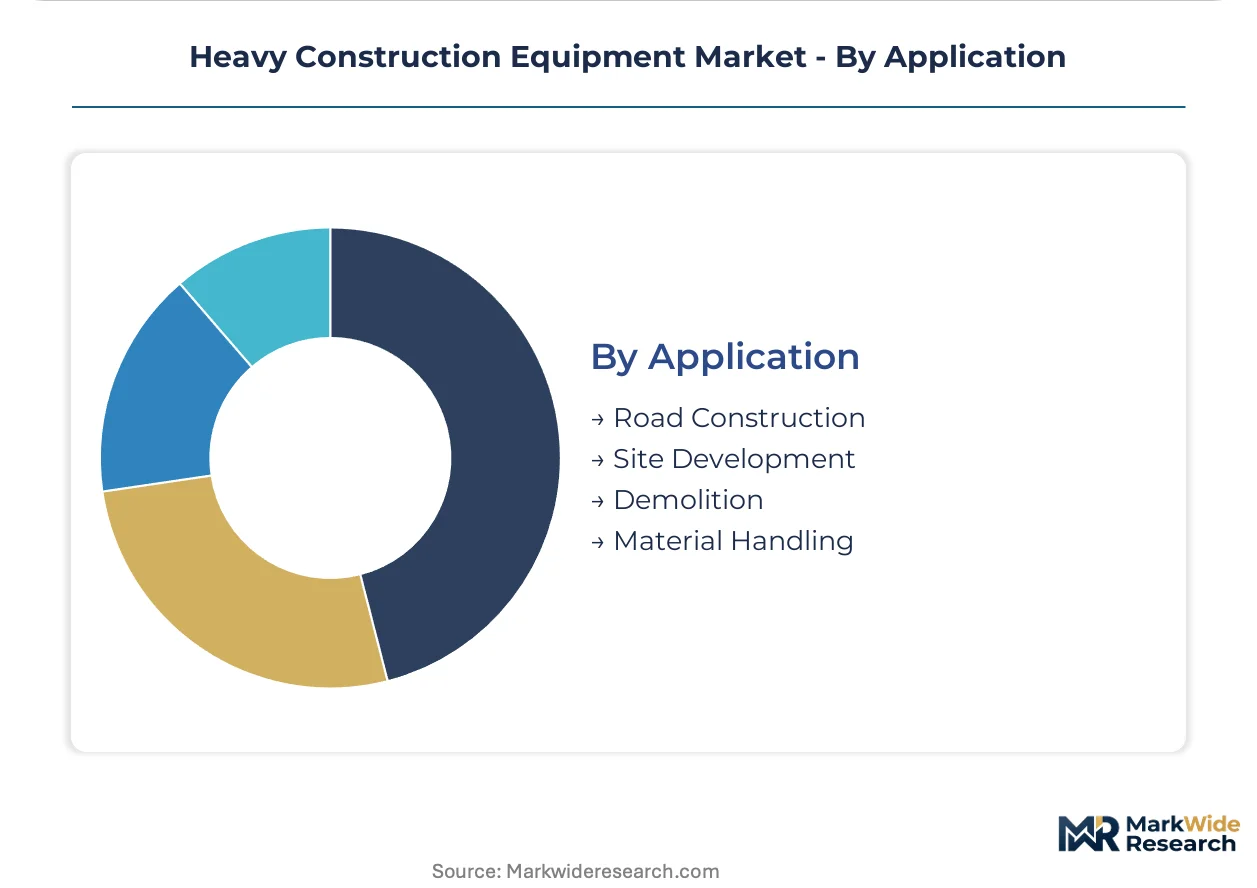
Site development applications consistently consume the highest equipment volumes, with road construction projects also requiring substantial machinery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global heavy construction equipment market exhibits distinct regional dynamics driven by varying regulatory landscapes, often compelling manufacturers to balance investment between compliant and export-focused models. This regulatory arbitrage influences production strategies, especially for diesel platforms facing stringent emissions standards. Manufacturers strategically allocate resources based on regional demand and environmental mandates.
India
India's National Infrastructure Pipeline creates substantial demand for earthmoving and road construction machinery. The government's focus on large-scale public works, supported by the PLI scheme, drives equipment procurement. Major urban centers like Mumbai and Delhi-NCR are experiencing rapid urbanization, requiring diverse compact equipment.
China
Chinese manufacturers, facing saturated domestic capacity, pivot toward export-led growth models for heavy construction equipment. Strict MEE pollution controls and national dual carbon goals necessitate ongoing product development for cleaner technologies. The Yangtze River Delta region, a manufacturing powerhouse, serves as a primary hub for equipment production and export.
United States
Demand in the United States is strong for site development and material handling equipment, with rental services gaining significant traction. EPA's Tier 4 Final emissions standards mandate advanced after-treatment systems for diesel engines, influencing product availability. Major infrastructure projects in states like Texas and California drive sales of high-capacity machinery.
Germany
Germany leads in the adoption of electric and hybrid construction equipment, aligning with stringent sustainability goals. Europe's Stage V emissions standard forces manufacturers to integrate complex after-treatment systems and accelerate electric powertrain development. Industrial clusters in Bavaria and North Rhine-Westphalia focus on engineering high-performance machinery and smart construction technologies.
Brazil
Brazil's heavy construction equipment market is driven by significant mining operations and ongoing infrastructure development projects. Local environmental licensing and safety regulations influence equipment specifications and operational practices. The state of Minas Gerais concentrates demand for specialized mining machinery, while São Paulo remains a key hub for general construction equipment.
Heavy Construction Equipment Market Key Industry Players
Asian producers anchor one tier of the heavy construction equipment market; established Western specialists hold another. This market exhibits a tiered structure, with a few global integrators alongside numerous regional players. Strategic archetypes include large-scale global manufacturers, specialized innovators focusing on electrification, and high-volume, export-oriented firms. Geographic expansion into emerging markets and substantial investment in product portfolio diversification, particularly in electric powertrains, are dominant competitive moves.
Within the global integrator tier, Caterpillar Inc. exemplifies broad market reach and extensive dealer networks, maintaining a strong position across established markets. Sany Group Co., Ltd., a Chinese manufacturer, represents the high-volume, export-oriented archetype, targeting growth in Southeast Asia and Latin America. Volvo Construction Equipment AB, a European entity, sits within the specialized innovator segment, aligning its product strategy with sustainability goals through electric and hybrid models. These companies demonstrate distinct approaches to market leadership, leveraging their respective strengths in distribution, scale, and technological specialization.
| Leading Market Players |
|---|
| XCMG |
| Sany |
| Caterpillar |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Komatsu |
| Liebherr |
| JCB |
| John Deere |
| Others |
Cost & Logistics Intelligence
Vertical integration into key component manufacturing anchors major OEMs' supply positions, allowing them to exert significant influence over final equipment pricing.
Pricing Analysis
Distributor margins often dictate retail pricing for heavy construction equipment, reflecting the value of local sales and aftermarket support. The dominant pricing model is per-unit transactional, frequently complemented by contract-based volume discounts for large fleet purchases. Price differentiation stems from brand recognition, the inclusion of advanced telematics, and compliance with specific regulatory certifications like EPA's Tier 4 Final. Pricing pressure stems from increased competition from Chinese manufacturers targeting export markets. Smaller contractors exhibit higher price sensitivity compared to large mining operations.
Supply Chain Analysis
Workforce availability in manufacturing hubs like China and Germany impacts the consistent production of heavy construction equipment. Geographic supply concentrates in China, Japan, and the United States, reflecting established manufacturing capabilities. Raw material dependencies include steel, specialized hydraulic components, and semiconductors. Commodity price volatility presents a structural risk, creating production instability and margin pressure for manufacturers. Distribution primarily runs through extensive global dealer networks and specialized rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy construction equipment represents a late-cycle quality story, driven by demand for advanced, emissions-compliant machinery in mature markets.
For Market Incumbents: Extend product lifecycles through enhanced aftermarket support and digital upgrades, mitigating the threat from lower-cost entrants. Invest in R&D for next-generation electric powertrains to meet evolving emissions regulations like Europe's Stage V. Deepen channel control by strengthening global dealer networks and expanding rental fleet partnerships, securing market access. This strategy counters the skilled labor gap by providing advanced diagnostics and remote service capabilities.
For New Entrants and Emerging Players: Capture white-space opportunities in modular electric power systems for urban construction, targeting rental fleets with flexible subscription models. Focus on compact and specialized equipment segments where charging infrastructure is more accessible, particularly in European and North American cities. Develop user-friendly telematics and interoperable software solutions to address system integration challenges. This approach provides a penetrable entry point into the market.
For Investors and Strategic Acquirers: Roll-up economics work for specialized technology providers because rapid innovation in electrification and autonomy creates fragmented expertise. The market offers long-term viability due to sustained global infrastructure spending and urbanization projects. Acquisition targets should include firms specializing in battery technology, autonomous guidance systems, or advanced hydraulic components. Practitioners should monitor adoption rates of electric models in rental fleets for early signals of market transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand electric model portfolio | This addresses stringent emissions regulations and aligns with sustainability goals in Europe. |
| Invest in autonomous haulage R&D | This enhances operational efficiency and safety for large-scale mining operations globally. |
| Strengthen global dealer networks | This maintains market reach and provides essential after-sales support for complex machinery. |
| Develop modular battery solutions | This solves on-site charging delays and extends operational uptime for electric equipment users. |
| Target export markets in Southeast Asia | This leverages established diesel platforms for infrastructure projects in growing economies. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The analysis combines in-depth interviews with construction company executives, rental fleet managers, mining operations directors, and equipment engineers with extensive secondary validation. Secondary data sources include government infrastructure reports, OEM annual reports, trade association publications, and regulatory filings. Bottom-up and top-down triangulation ensures data consistency.
Rate-of-change decomposition frames the market's evolution, analyzing shifts across product type, end-user, technology, and application. The analytical framework incorporates market drivers, restraints, and opportunities throughout the forecast period. Compound Annual Growth Rates (CAGRs) are derived from historical trends and future projections, integrating factors like national infrastructure spending and electric model production ramp-up. Segmentation dimensions include regional regulatory compliance and equipment capacity tiers.
Underlying measurement precision varies by segment; electric models and autonomous systems carry tighter precision than legacy diesel platforms. Forecasts reflect assumptions regarding economic stability, technological advancements, and regulatory enforcement. Geopolitical shifts, raw material price volatility, and new regulatory mandates represent risk factors. Practitioners should monitor infrastructure spending patterns and regulatory shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Jib Crane Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Field Marking Equipment Market