
 Precision Strain Wave Reducer Gearboxes Market | 2026-2036
Precision Strain Wave Reducer Gearboxes Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Strain Wave Reducer Gearboxes Market Insights
Buyer concentration among automation providers is shifting as mid-tier machine tool manufacturers and emerging robotics integrators fragment the traditional OEM-dominated procurement landscape. Harmonic Drive Systems Inc. leverages decades of flexspline metallurgy expertise to sustain premium positioning in semiconductor wafer handling. Nabtesco Corporation anchors Japanese supply chains through captive control of wave generator bearing assemblies. SPINEA, s.r.o. competes on compact hollow-shaft architectures for collaborative robot joints.
Precision strain wave reducer gearboxes transmit torque through elastic deformation of a thin-walled flexspline engaged with a rigid circular spline, achieving single-stage reduction ratios exceeding 100:1 with zero backlash and positional repeatability below one arc-minute. Metallic harmonic drives dominate installed base volumes while ceramic-composite variants capture expanding share in satellite reaction wheel mechanisms where mass reduction and thermal stability outweigh cost premiums. Robotics applications lead absolute demand, though aerospace systems and satellite mechanisms represent the fastest-growing margin pools as constellation deployments multiply.
FDA device manufacturing guidelines, EU machinery directives under CE marking, and Japan's METI industrial technology roadmap collectively shape product certification requirements and cross-border market access for precision motion suppliers. China's GB standards and NMPA quality frameworks impose additional testing protocols on gearboxes deployed in medical automation and surgical robotics. Stakeholders must monitor evolving F-Gas Regulation amendments and REACH material restrictions as these frameworks increasingly constrain lubricant formulations and surface treatment chemistries in European supply chains.
Market Dynamics
Automotive and electronics manufacturers are consolidating six-axis articulated arm deployments, compressing procurement cycles and forcing flexspline suppliers to absorb volume volatility without long-term order commitments.
Growth Catalysts
- EU Green Deal machinery directives:Stricter efficiency benchmarks under CE marking are mandating zero-backlash motion systems in Bavarian automation clusters, accelerating harmonic drive replacements of legacy planetary units.
- China MIIT dual carbon goals:Energy intensity targets in Guangdong-Hong Kong-Macao precision manufacturing zones are prioritizing high-ratio single-stage reducers over multi-stage alternatives in SCARA platforms.
- Constellation satellite deployments:Ceramic-composite flexspline architectures are capturing reaction wheel mechanisms where thermal stability and mass reduction outweigh metallic unit costs.
Market Restraints
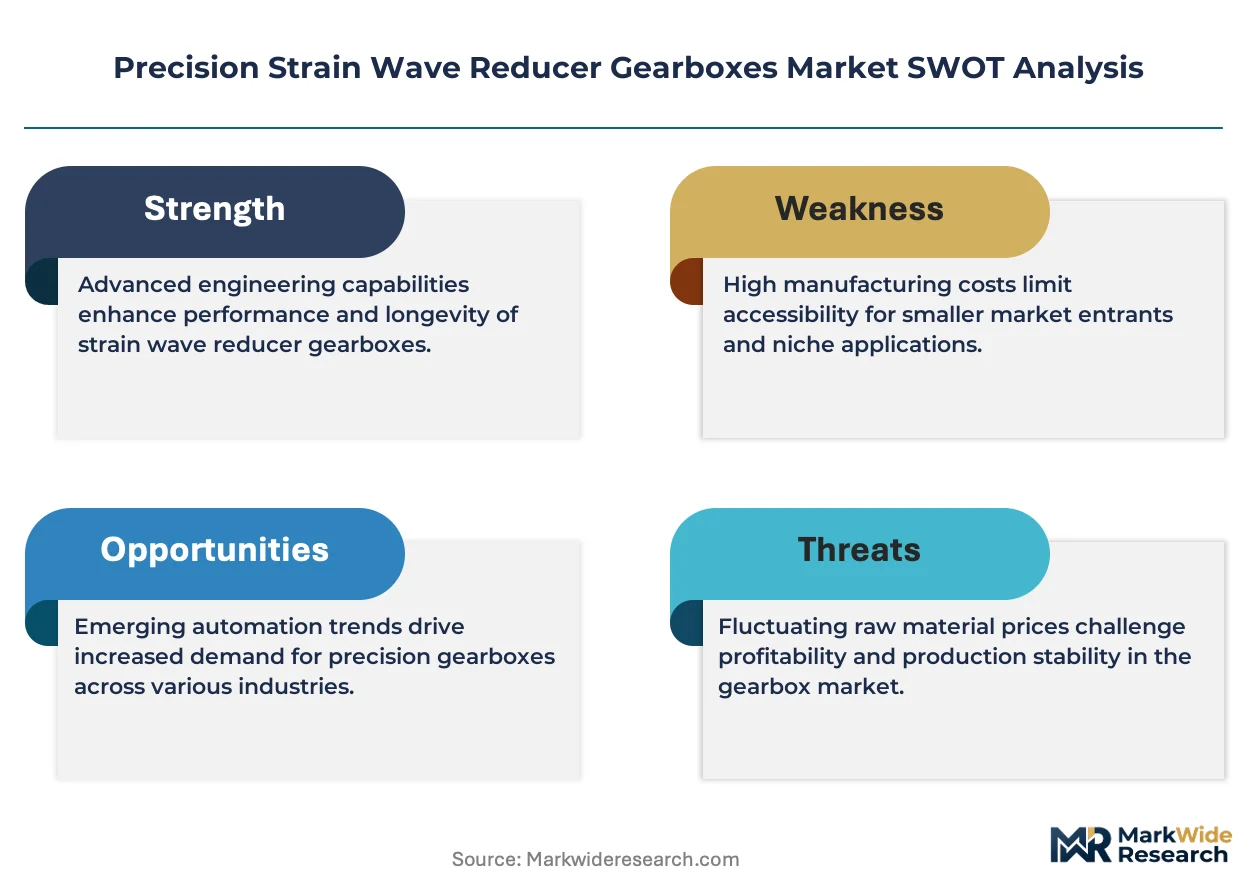
- Specialized alloy input volatility:Thin-walled flexspline production depends on maraging steel and precipitation-hardened alloys subject to spot price swings and Japanese bearing assembly supply concentration.
- REACH material restrictions:ECHA surface treatment chemistries and F-Gas Regulation lubricant formulations are constraining European supply chain configurations and extending qualification timelines.
- Planetary gearbox substitution:Lower-precision collaborative robot joints are tolerating cycloidal and planetary alternatives where arc-minute repeatability is not specified.
Strategic Opportunities
- Surgical robotics certification pathways:FDA device manufacturing guidelines and NMPA quality frameworks are creating premium tier demand for medical-automation-grade harmonic drives with extended fatigue life ratings.
- Collaborative robot hollow-shaft architectures:Compact torque transmission through robot joint centers is enabling cable routing integration previously impossible with solid-shaft planetary systems.
- Japan METI industrial technology roadmap:National robotics corridor investments in Nagoya are funding next-generation wave generator bearing assembly domestic production capacity.
Industry Challenges
- Flexspline metallurgy talent scarcity:Deep expertise in elastic deformation fatigue modeling and thin-wall machining resides with aging specialist engineers in Japanese and German supplier bases.
- Multi-jurisdictional certification timelines:Simultaneous FDA, CE marking, and NMPA qualification for medical automation gearboxes extends product launch windows by 18-24 months.
- Legacy controller integration friction:Zero-backlash harmonic drives require servo loop retuning when retrofitting existing six-axis arms designed for backlash-accommodating planetary systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Strain Wave Reducer Gearboxes Market |
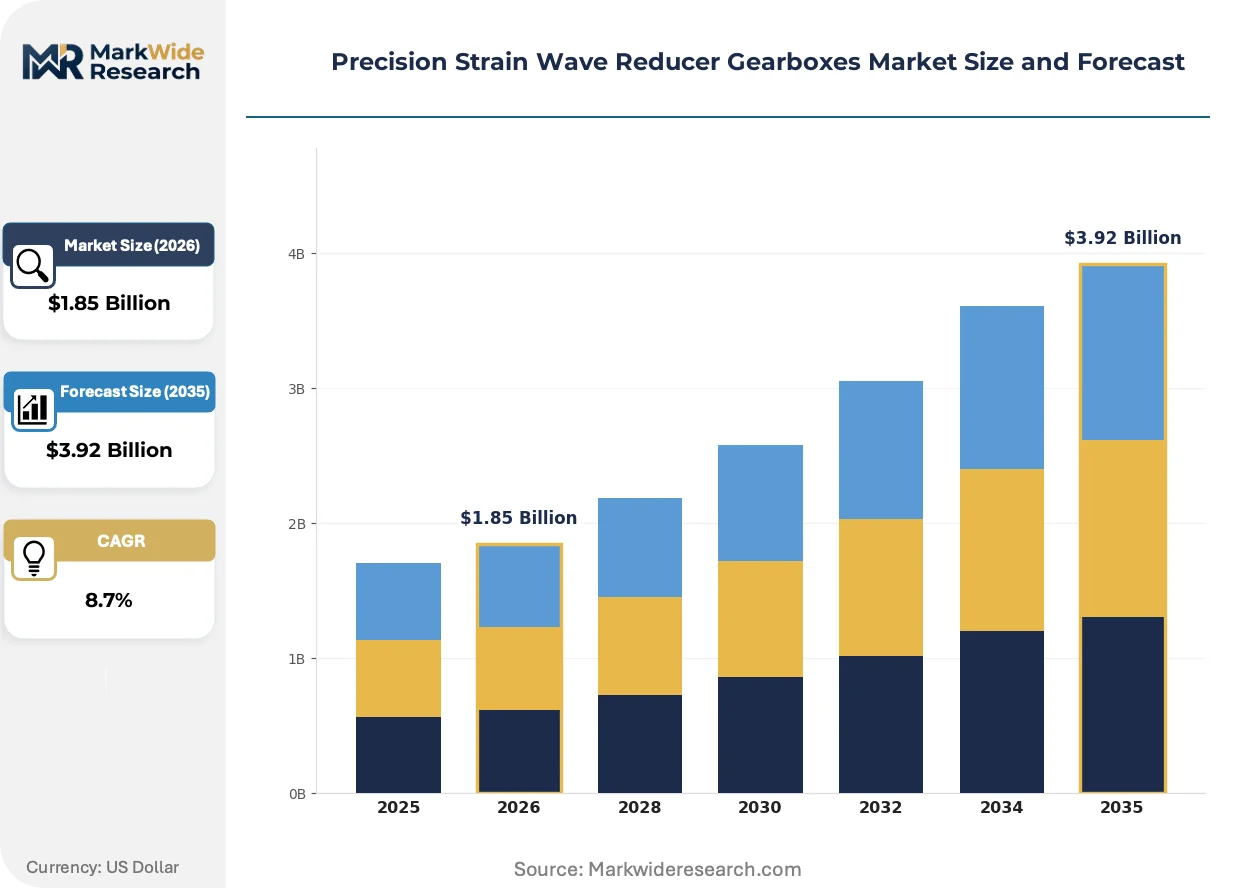
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harmonic Drive, Circular Spline, Flexspline, Wave Generator Technology: Metallic, Composite, Ceramic, Polymer Application: Robotics, Aerospace Systems, Satellite Mechanisms, Precision Instruments End User: Machine Tool Manufacturers, Automation Providers, Defense Equipment Makers, Optical Equipment Producers |
| Companies Covered | Beijing CTKM Harmonic Drive Technology Co., Ltd., SPINEA, s.r.o., Harmonic Drive LLC, Hiwin Corporation, Zhejiang Laifual, Nidec-Shimpo Corporation, Leaderdrive Technology Co., Ltd., Harmonic Drive Systems Inc., Nabtesco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Strain Wave Reducer Gearboxes Market Trends and Innovations
Ceramic-composite flexspline architectures, regulatory chemistry constraints, and buyer consolidation around system integrators are compressing traditional component supplier margins while opening premium niches.
Metallic-ceramic hybrid flexspline laminates are consolidating high-performance satellite reaction wheel supply chains. Aerospace prime contractors in European constellation programs are specifying these units for thermal stability under orbital cycling. The technology is consolidating procurement around qualified Japanese and German suppliers capable of ceramic metallization bonding.
F-Gas Regulation amendments are restricting perfluorinated lubricant formulations in precision motion components. ECHA compliance is forcing reformulation of wave generator bearing greases toward synthetic hydrocarbon and polyether alternatives. European automation OEMs are absorbing qualification costs and extending supplier audit cycles to verify REACH substance compliance.
Machine tool manufacturers and emerging robotics integrators are fragmenting traditional OEM-dominated procurement channels. Volume buyers are consolidating purchasing through specialized motion component distributors rather than direct manufacturer relationships. This channel shift is most visible in China's Guangdong precision manufacturing zone where mid-tier integrators now specify harmonic drives independently of arm OEM sourcing agreements.
Precision Strain Wave Reducer Gearboxes Market Segmentation
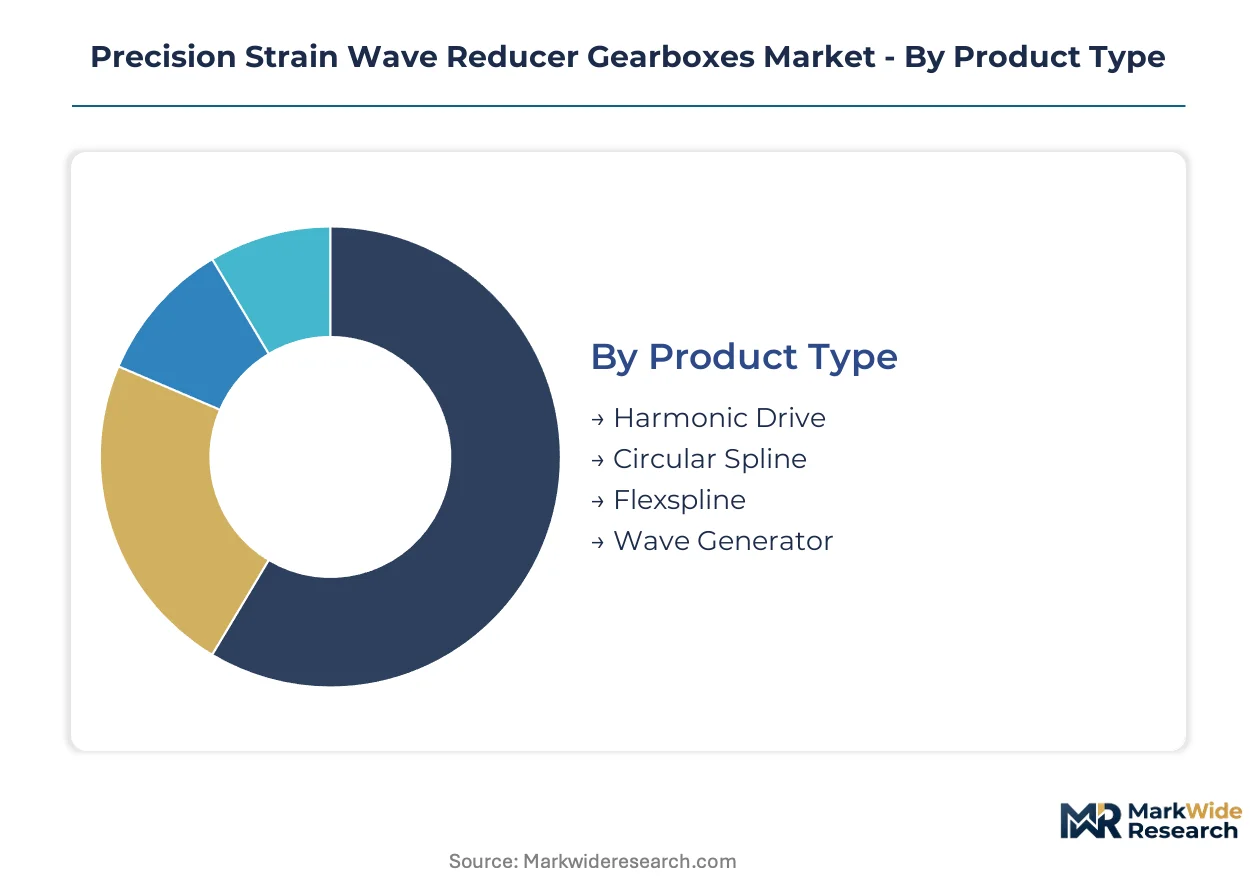
Component-level segmentation in precision strain wave reducers determines upgrade economics and retrofit compatibility. Procurement patterns diverge sharply between OEMs specifying complete harmonic drive assemblies and integrators sourcing individual flexsplines or wave generators for field repairs.
Product Type:
Replacement cycles vary dramatically across product types, with complete harmonic drive units commanding longer intervals than consumable flexspline elements.
- Harmonic Drive:Integrated assemblies combining flexspline, circular spline, and wave generator into sealed units. Automotive six-axis arm OEMs in Germany's Bavarian automation cluster specify these for factory-installed precision motion systems requiring zero field maintenance.
- Circular Spline:Rigid ring gear with internal involute teeth meshing against the flexspline's external profile. Demand concentrates in Japanese robotics corridors where captive bearing assembly suppliers control precision grinding capacity for hardened steel variants.
- Flexspline:Thin-walled cylindrical cup undergoing elastic deformation during torque transmission. Mid-tier machine tool manufacturers source these separately for cost-sensitive SCARA platform retrofits.
- Wave Generator:Elliptical cam assembly driving flexspline deformation. Ceramic bearing variants capture satellite reaction wheel mechanisms where mass reduction outweighs terrestrial cost structures.
Harmonic Drive sits at the top of the volume ranking, with Wave Generator climbing the fastest.
Technology:
Material selection tracks thermal and mass requirements across orbital versus terrestrial deployment environments.
- Metallic:Maraging steel and precipitation-hardened alloy constructions dominate industrial robotics installed base volumes. China's Guangdong-Hong Kong-Macao precision manufacturing zone absorbs the majority of metallic unit procurement for electronics fabrication SCARA platforms.
- Composite:Carbon-fiber-reinforced polymer laminates targeting collaborative robot joints where reduced inertia improves dynamic response. European automation OEMs specify these for CE-marked machinery under EU Green Deal efficiency directives.
- Ceramic:Silicon nitride and alumina compositions for satellite reaction wheels requiring thermal stability across orbital temperature cycling. Aerospace prime contractors in constellation programs consolidate procurement around qualified Japanese and German suppliers.
- Polymer:Injection-molded high-performance thermoplastics for laboratory automation and low-load precision instruments. FDA device manufacturing guidelines constrain polymer selection for medical automation gearboxes.
Metallic technology retains the dominant share position, though Ceramic gains share fastest in margin-weighted revenue terms.
Application:
Application segmentation separates volume-driven industrial automation from premium-margin aerospace and defense systems.
- Robotics:Six-axis articulated arms and SCARA platforms in automotive assembly and electronics fabrication. China's MIIT dual carbon goals prioritize high-ratio single-stage reducers over multi-stage alternatives in Guangdong precision manufacturing zones.
- Aerospace Systems:Flight control surface actuation and landing gear mechanisms requiring MIL-STD qualification. Defense equipment makers specify these for extended temperature range and shock resistance beyond commercial ratings.
- Satellite Mechanisms:Reaction wheels and solar array drives for constellation deployments. Ceramic-composite architectures capture expanding share where thermal stability and mass reduction outweigh metallic unit costs.
- Precision Instruments:Optical equipment and semiconductor wafer handling systems demanding sub-arc-minute repeatability. NMPA quality frameworks impose additional testing protocols on gearboxes deployed in Chinese medical automation.
Robotics leads absolute demand volume, with Satellite Mechanisms expanding most quickly.
End User:
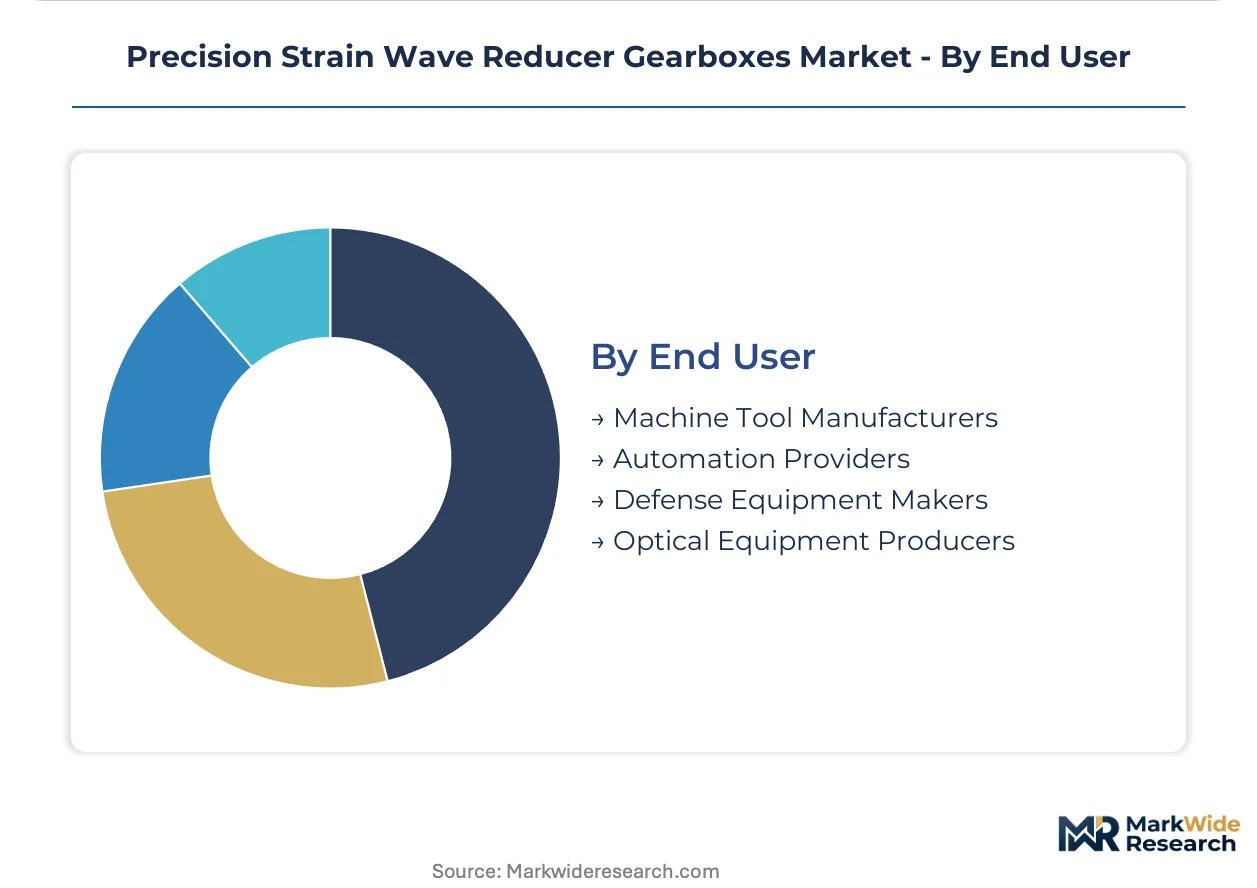
End user concentration shapes procurement channel structure and pricing power distribution.
- Machine Tool Manufacturers:CNC machining centers and multi-axis positioning systems. Japan's METI industrial technology roadmap funds domestic production capacity for wave generator bearing assemblies serving this segment.
- Automation Providers:System integrators consolidating purchasing through specialized motion component distributors. Mid-tier integrators in China's Guangdong zone now specify harmonic drives independently of arm OEM sourcing agreements.
- Defense Equipment Makers:Military robotics and precision targeting systems requiring ITAR and export-controlled supply chains. REACH material restrictions constrain European supplier configurations for lubricant formulations.
- Optical Equipment Producers:Telescope drives, lithography systems, and laser positioning stages. ECHA surface treatment chemistries extend qualification timelines for European supply chain participants.
Automation Providers command the largest procurement volume, with Defense Equipment Makers posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan command premium-tier procurement for precision motion systems, while China's Guangdong manufacturing zone absorbs the highest absolute volumes for electronics fabrication automation.
Germany
Automotive six-axis arm OEMs in Bavaria specify zero-backlash harmonic drives for factory-installed precision motion systems. The EU Green Deal machinery directives under CE marking mandate efficiency benchmarks that accelerate harmonic drive replacements of legacy planetary units. Stuttgart and Munich automation clusters concentrate procurement for semiconductor wafer handling and optical equipment production.
China
Electronics fabrication SCARA platforms in the Guangdong-Hong Kong-Macao Greater Bay Area drive metallic unit procurement at scale. MIIT dual carbon goals impose energy intensity targets that prioritize high-ratio single-stage reducers over multi-stage alternatives. Shenzhen and Dongguan precision manufacturing zones absorb the majority of volume for mid-tier machine tool retrofits.
Japan
Nagoya's robotics corridor anchors domestic supply chains through captive control of wave generator bearing assemblies. METI industrial technology roadmap investments fund next-generation wave generator bearing assembly production capacity. Osaka and Yokohama precision manufacturing bases concentrate flexspline metallurgy expertise for satellite reaction wheel mechanisms.
United States
Defense equipment makers specify MIL-STD qualified units for military robotics and precision targeting systems requiring ITAR-controlled supply chains. FDA device manufacturing guidelines shape certification requirements for surgical robotics and medical automation gearboxes. California and Texas aerospace clusters drive ceramic-composite procurement for constellation satellite deployments.
Precision Strain Wave Reducer Gearboxes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Japanese and German suppliers anchor premium positioning through metallurgy expertise and captive bearing assembly control. Chinese fabricators capture volume-tier procurement for domestic electronics fabrication automation. Strategic moves concentrate on backward integration into flexspline material supply and geographic expansion through distributor channel consolidation.
Within the Japanese supplier tier, Harmonic Drive Systems Inc. and Nabtesco Corporation exemplify archetypes of metallurgy-focused premium positioning and captive supply chain control respectively. SPINEA, s.r.o. occupies a position among European specialists in compact hollow-shaft architectures. Beijing CTKM Harmonic Drive Technology Co., Ltd. and Leaderdrive Technology Co., Ltd. represent Chinese volume-tier fabricators serving domestic automation demand.
| Leading Market Players |
|---|
| Beijing CTKM Harmonic Drive Technology Co., Ltd. |
| SPINEA, s.r.o. |
| Harmonic Drive LLC |
| Hiwin Corporation |
| Zhejiang Laifual |
| Nidec-Shimpo Corporation |
| Leaderdrive Technology Co., Ltd. |
| Harmonic Drive Systems Inc. |
| Nabtesco Corporation |
| Others |
Pricing and Supply Chain Analysis
Mid-tier machine tool manufacturer procurement consolidation in China's Guangdong precision manufacturing zone is forcing flexspline suppliers to absorb volume volatility without long-term order commitments, compressing margins and accelerating channel migration toward specialized motion component distributors.
Pricing Analysis
Capacity additions in China's domestic harmonic drive fabrication are reshaping price floors for metallic flexspline units in the volume tier. Three-tier pricing structure across premium, standard, and economy levels separates Japanese metallurgy-certified units for semiconductor wafer handling from Chinese domestic-grade alternatives for SCARA retrofits. Pricing pressure stems from planetary gearbox substitution in collaborative robot joints where arc-minute repeatability is not specified. Automation providers in Germany's Bavarian cluster exhibit lowest price sensitivity due to EU Green Deal efficiency mandates, while mid-tier integrators in Guangdong demonstrate highest sensitivity to unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese bearing assembly suppliers controlling wave generator production capacity for precision grinding of hardened steel variants. Geographic supply concentration centers on Japan for flexspline metallurgy expertise, Germany for circular spline precision grinding, and China for volume-tier metallic unit fabrication. Raw material dependencies draw from maraging steel spot markets, precipitation-hardened alloy inventories, and ceramic-composite laminate feedstocks. Supply chain risk manifests as REACH material restrictions constraining European lubricant formulations and surface treatment chemistries. Distribution runs through specialized motion component distributors consolidating purchasing for mid-tier integrators independently of arm OEM sourcing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in precision strain wave reducers rests on ceramic-composite architecture premiums in satellite mechanisms and surgical robotics certification tiers displacing commoditized metallic industrial units.
For Market Incumbents: Lock in flexspline metallurgy expertise through captive training pipelines and long-term employment contracts with aging specialist engineers in Nagoya and Stuttgart clusters. Deepen backward integration into maraging steel alloy supply to buffer spot price volatility threatening standard-tier margins. Prioritize FDA and NMPA dual certification investments to capture surgical robotics premium tiers before Chinese domestic competitors qualify. For New Entrants and Emerging Players: Ceramic-composite flexspline laminates for satellite reaction wheel mechanisms offer the most penetrable white-space target, as constellation deployment timelines outpace qualified supplier capacity. Hollow-shaft wave generator architectures for collaborative robot joints present secondary entry point through cable routing integration advantages over solid-shaft planetary alternatives. Pursue direct qualification with Guangdong mid-tier integrators bypassing traditional arm OEM sourcing gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with Japanese and German pure-play specialists possessing certified ceramic metallization bonding capabilities for aerospace prime contractor procurement. Long-term viability across the analysis window favors suppliers controlling captive wave generator bearing assembly production rather than fabrication-only flexspline machining operations. Monitor FDA 510(k) clearance timelines for surgical robotics gearboxes as inflection indicator for medical-automation-grade premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive maraging steel sourcing buffers Japanese spot market volatility for flexspline producers. |
| Ceramic-Composite Certification Investment | Aerospace prime contractor qualification unlocks constellation satellite reaction wheel procurement tiers. |
| Dual Jurisdiction Regulatory Qualification | Simultaneous FDA and NMPA pathways capture surgical robotics premium pricing in medical automation. |
| Distributor Channel Consolidation | Direct relationships with Guangdong mid-tier integrators bypass arm OEM procurement gatekeepers. |
| Metallurgy Talent Captive Programs | Long-term specialist engineer contracts defend Nagoya and Stuttgart flexspline fatigue modeling expertise. |
Research Methodology
Multiple input streams — primary interviews with robotics OEM procurement directors, flexspline metallurgy engineers, and medical device regulatory affairs leads; secondary validation through SEC filings of listed precision motion suppliers, ECHA REACH substance databases, and FDA 510(k) device clearance records; customs trade data for harmonic drive unit imports — were reconciled through bottom-up unit volume modeling and top-down market value triangulation.
Data-stream reconciliation across product type, technology material class, application segment, and end-user concentration dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate differential analysis. Forecast inputs incorporated MIIT dual carbon policy implementation timelines, EU Green Deal machinery directive enforcement phases, and constellation satellite deployment schedules from aerospace prime contractor procurement disclosures.
The model holds under stable alloy input pricing and sustained robotics automation capital expenditure; deviation in maraging steel spot volatility or REACH lubricant formulation bans would shift volume-tier margin assumptions. Forecasts reflect documented base-case assumptions regarding regulatory qualification timelines and ceramic-composite adoption curves in aerospace applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Precision Engineering Machines Market