
 Construction Equipment Rental Market | 2026-2036
Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Rental Market Intelligence
Equipment distribution through national branch networks is reshaping how contractors access machinery across North America. United Rentals leverages its density of locations to sustain same-day availability in metropolitan corridors. Sunbelt Rentals anchors its position through specialized climate-controlled and powered access fleets. Ashtead Group competes by extending digital fleet tracking across its North American and European operations.
Construction equipment rental denotes the temporary provision of heavy machinery—typically diesel or electric-powered units rated by engine horsepower, load capacity, and boom reach—without transfer of ownership, serving contractors seeking capital efficiency and operational flexibility. The equipment type dimension shows excavators and loaders commanding the largest fleet allocations due to their ubiquity in earthmoving and material handling, while cranes generate premium daily rates owing to specialized operator requirements and safety certification overhead. Within service type, project-based rentals capture expanding share as infrastructure owners shift risk away from fixed-asset ownership, though long-term rentals retain margin strength among industrial clients with predictable utilization cycles.
EPA emissions regulations and OSHA worksite safety standards constrain fleet composition and maintenance protocols across the United States, while the EU Green Deal and F-Gas Regulation pressure European operators toward lower-carbon equipment procurement. The EU AI Act introduces emerging compliance dimensions for autonomous and telematics-enabled machinery deployed in member states. Stakeholders must monitor regulatory divergence between jurisdictions to align fleet investment with evolving compliance thresholds and carbon accounting requirements.
Market Dynamics
EPA emissions standards for diesel-powered machinery are forcing fleet operators to accelerate equipment turnover and redirect capital toward Tier 4 Final and electric alternatives, compressing asset life cycles across the rental industry.
Growth Catalysts
- Infrastructure Investment:Large-scale civil projects and utility upgrades across the United States sustain rental volume as contractors outsource fleet ownership to preserve liquidity.
- EPA Tier 4 Final Compliance:Stricter emissions thresholds push smaller contractors toward rental models to avoid capital-intensive engine retrofits and replacement cycles.
- Telematics Integration:Real-time fleet tracking and predictive maintenance systems reduce downtime and extend equipment utilization rates for rental providers.
Market Restraints
- Diesel Engine Supply Concentration:Limited certified engine manufacturers create procurement bottlenecks and pricing volatility for Tier 4 Final-compliant machinery.
- Steel and Hydraulic Component Costs:Input price fluctuations for high-grade steel and precision hydraulics compress margin predictability across fleet procurement cycles.
- OSHA Certification Overhead:Specialized operator requirements for cranes and aerial lifts extend onboarding timelines and limit fleet deployment flexibility.
Strategic Opportunities
- Electric Equipment Transition:Battery-powered excavators and compact loaders open urban corridor contracts where noise and emissions restrictions exclude diesel units.
- Project-Based Rental Expansion:Infrastructure owners shifting risk away from fixed-asset ownership create demand for short-term, milestone-linked rental structures.
- EU Green Deal Alignment:European rental operators can capture carbon-accounting-conscious contractors through lower-carbon fleet procurement and F-Gas Regulation compliance.
Industry Challenges
- Certified Technician Scarcity:EPA-compliant engine diagnostics and electric drivetrain maintenance require skills that outpace vocational training pipeline output.
- Legacy Fleet Integration:Telematics retrofits for pre-2015 equipment face compatibility gaps and connectivity standard fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Rental Market |
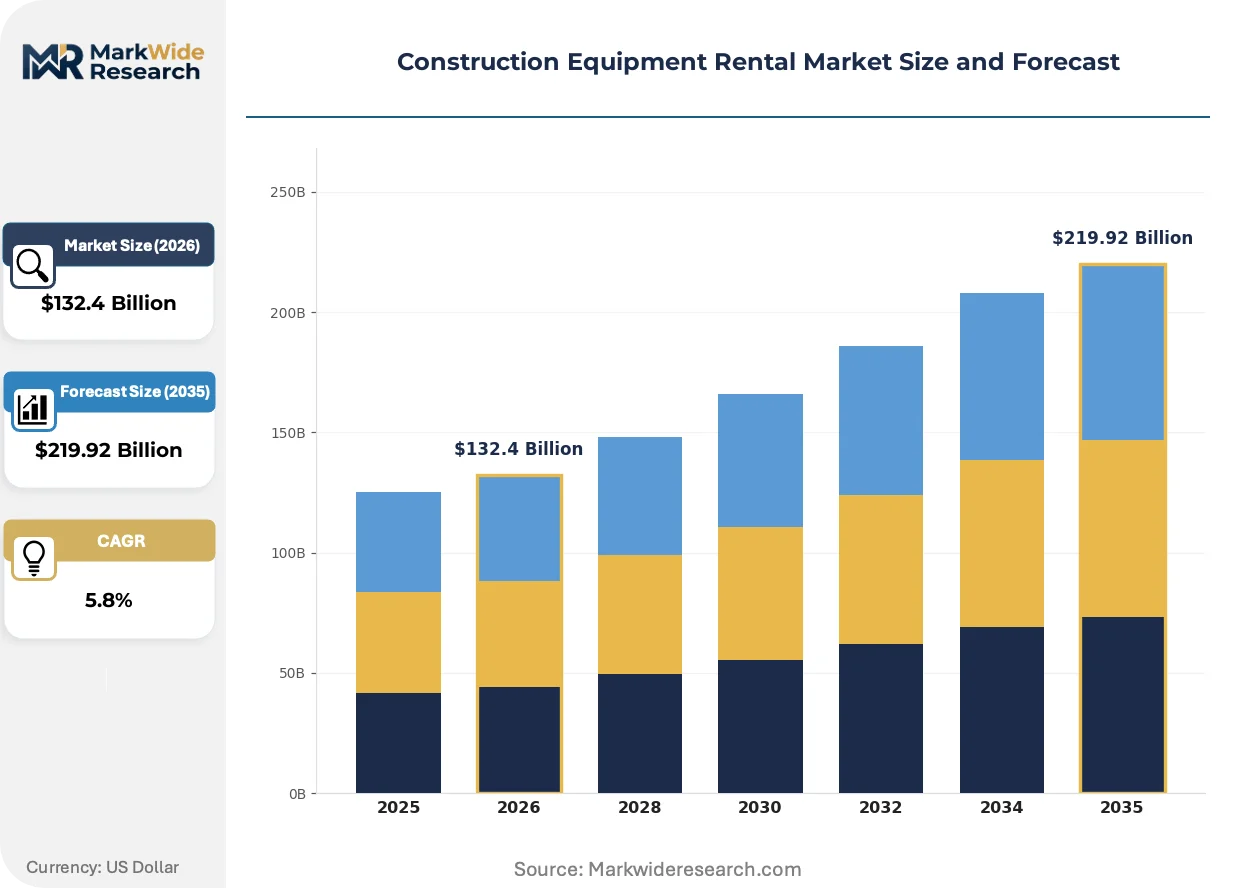
| Market Size in 2026 | $132.4 Billion |
| Market Size in 2035 | $219.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Service Type: Short-Term Rentals, Long-Term Rentals, Project-Based Rentals, Lease Financing Customer Type: Contractors, Construction Companies, Government Agencies, DIY Users Deployment Model: On-Site Rentals, Off-Site Rentals, Managed Rentals, Emergency Rentals |
| Companies Covered | United Rentals, Sunbelt Rentals, Herc Rentals, Loxam, Ashtead Group, Ahern Rentals, H&E Equipment Services, Aktio Corporation, Boels Rental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Rental Market Strategic Shifts & Innovations
Digital fleet management and powertrain electrification are compressing traditional rental operating models. Equipment connectivity, emissions compliance automation, and flexible contracting structures now determine competitive position.
Autonomous grade-control systems integrated with GPS and machine vision are rendering obsolete manual staking and survey-dependent earthmoving workflows. Mid-sized site contractors in the United States are adopting these systems at accelerating rates for residential and commercial pad preparation. The technology is rendering obsolete the historical reliance on skilled surveyor presence and reducing rework cycles that previously consumed 8-12% of project schedules.
The EU AI Act introduces compliance dimensions for telematics-enabled and semi-autonomous machinery deployed in member states. Equipment rental operators must document algorithmic transparency and risk classification for fleet assets crossing into European markets. Crane and aerial lift categories face the steepest documentation requirements, prompting operators to segment EU-dedicated fleets or accelerate supplier certification partnerships.
Fixed-asset avoidance has become the dominant procurement logic among infrastructure contractors managing balance sheet constraints. Equipment-as-a-service contracts with bundled maintenance and uptime guarantees are displacing traditional daily-rate rentals for multi-year civil projects. This pattern concentrates in United States metropolitan corridors where municipal bond financing and federal infrastructure grants create sustained project pipelines.
Construction Equipment Rental Market Segmentation
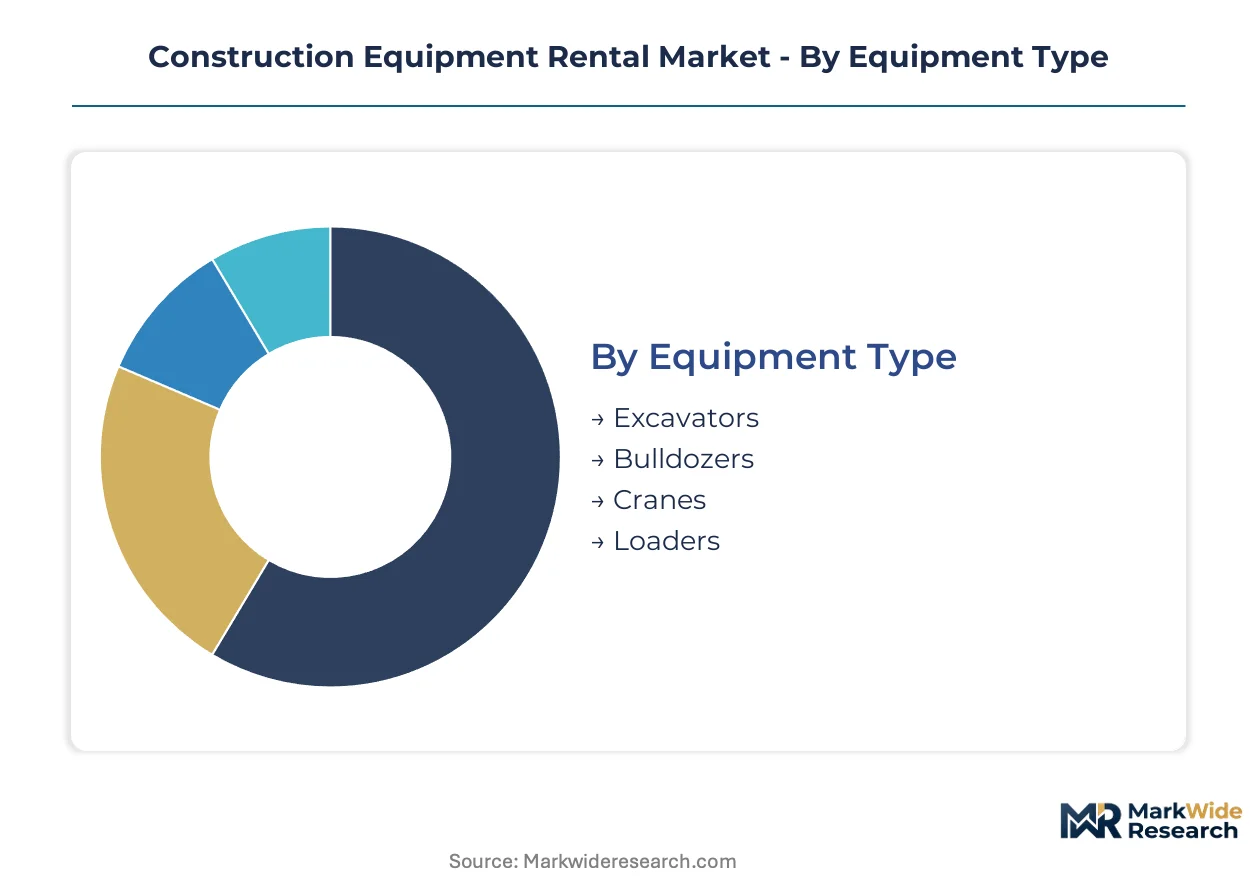
Equipment rental segmentation reveals how fleet operators balance asset velocity against contract duration. Cycle time variations across categories dictate working capital intensity and margin capture patterns for rental providers.
Equipment Type:
Earthmoving equipment turns fastest on short-cycle urban jobs, while lifting equipment locks capital longest due to certification and transport complexity.
- Excavators:Hydraulic machines with bucket capacities from 0.5 to 5 cubic yards dominate municipal trenching and foundation work. United States infrastructure contractors deploy compact models for utility corridor upgrades where EPA Tier 4 Final compliance costs deter ownership.
- Loaders:Wheel and track configurations rated by breakout force and dump height command the largest fleet allocations. Material handling at commercial and residential sites drives sustained rental volume, particularly where seasonal demand spikes punish capital-intensive purchases.
- Bulldozers:Tracked dozers with blade widths exceeding 13 feet serve land clearing and rough grading. Pipeline and solar farm developers in Texas and Arizona favor rental models to match equipment scale to project phase.
- Cranes:Mobile and tower configurations require certified operators and engineered lift plans. Premium daily rates reflect OSHA compliance overhead and specialized rigging logistics that extend deployment timelines.
Excavators dominate installed base. Cranes are where expansion concentrates for margin-focused operators.
Service Type:
Contract structures segment by balance sheet risk transfer, with shorter terms preserving customer liquidity and longer terms locking utilization predictability.
- Project-Based Rentals:Milestone-linked contracts align payment to construction phases. United States civil contractors facing municipal bond financing constraints adopt these structures to match equipment liability to project cash flows.
- Long-Term Rentals:Multi-year agreements with bundled maintenance serve industrial clients with predictable utilization cycles. Manufacturing and energy sector operators in the Gulf Coast corridor favor this model for refinery turnaround and expansion work.
- Short-Term Rentals:Daily and weekly rates accommodate demand spikes and emergency replacement. Storm recovery and seasonal construction peaks in Florida and California sustain this segment's volume.
- Lease Financing:Capital lease structures with nominal purchase options appeal to mid-sized contractors building equity positions. Equipment title transfer at lease end differentiates this from true rental arrangements.
Long-term rentals dominate installed base. Project-based structures are climbing the fastest as infrastructure owners shift risk away from fixed-asset ownership.
Customer Type:
Buyer sophistication and credit capacity determine contract terms, with institutional clients extracting volume discounts and individual users paying retail premiums.
- Contractors:Licensed trade specialists in electrical, mechanical, and earthmoving disciplines. EPA emissions compliance costs push smaller operators toward rental models to preserve liquidity for labor and bonding.
- Construction Companies:General and specialty contractors managing multi-trade projects. Large-scale civil builders in metropolitan corridors outsource fleet ownership to optimize balance sheet metrics for project financing.
- Government Agencies:Federal, state, and municipal procurement entities with mandated competitive bidding. Infrastructure grants and utility upgrade programs drive sustained rental volume through master service agreements.
- DIY Users:Residential and small commercial operators executing limited-scope work. Home improvement retailers and compact equipment specialists serve this price-sensitive segment with simplified rate structures.
Construction companies dominate installed base. Government agencies represent the steepest expansion trajectory as federal infrastructure investment flows through state procurement channels.
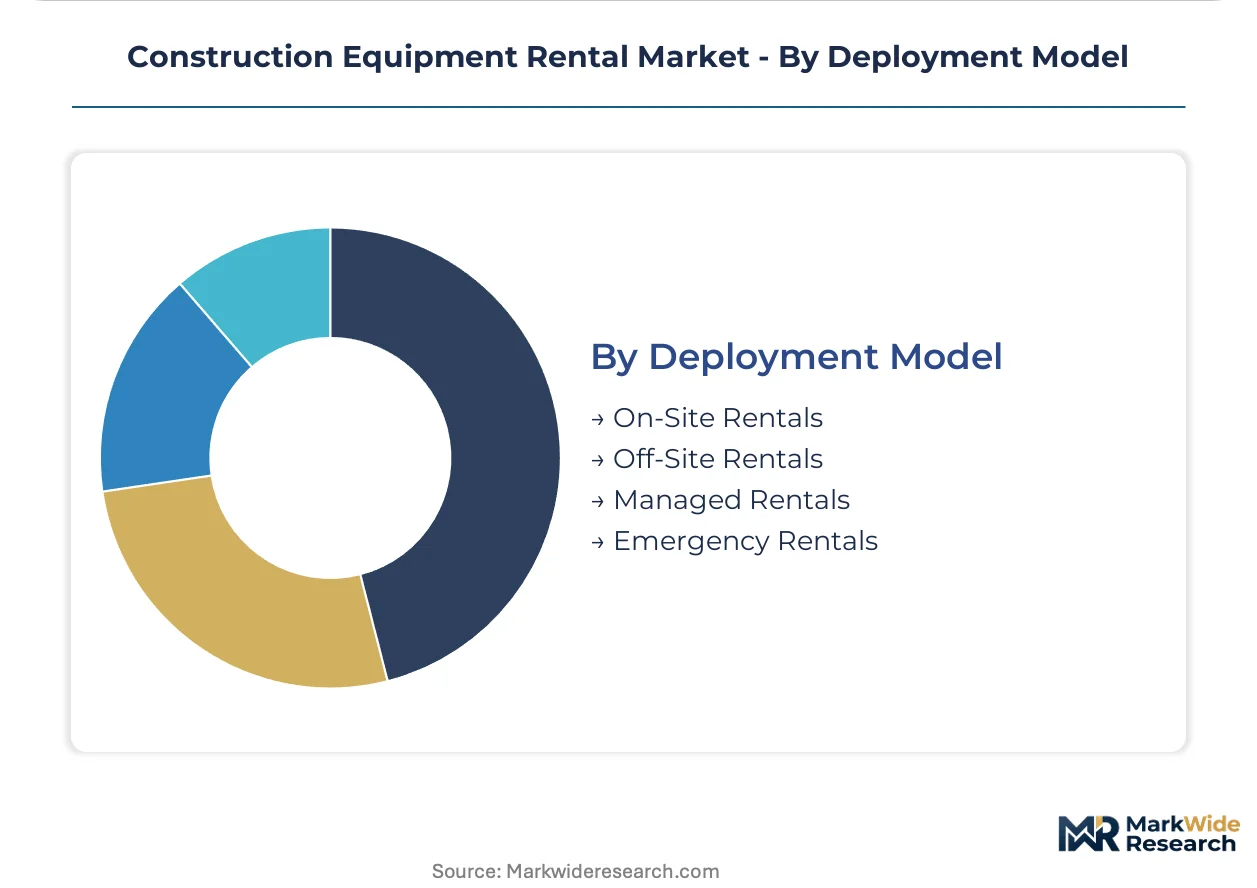
Deployment Model:
Logistics configuration determines fleet positioning cost and response velocity, with proximity to demand centers driving competitive differentiation.
- On-Site Rentals:Equipment positioned at customer locations for exclusive use. Large-scale civil projects in Texas and California adopt this model to eliminate transport delays and secure guaranteed availability.
- Managed Rentals:Full-service arrangements with operator provision and maintenance inclusion. Industrial clients with complex safety protocols favor this model to outsource compliance liability.
- Off-Site Rentals:Yard-based pickup and return with customer transport responsibility. Cost-conscious contractors in equipment-dense metropolitan corridors accept this friction for rate savings.
- Emergency Rentals:Expedited deployment for breakdown replacement and disaster response. Hurricane and wildfire recovery operations in Florida and California sustain premium pricing for 24-hour availability guarantees.
On-site rentals dominate installed base. Managed rentals are gaining share fastest as labor scarcity and safety complexity push operational burden onto rental providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rental rate premiums in the United States exceed those in India by 40-60% for comparable excavator classes, reflecting divergent fleet quality standards and regulatory compliance burdens. This pricing-power asymmetry concentrates investment returns in developed markets while volume expansion accelerates in emerging economies.
United States
Federal infrastructure grants and municipal bond financing sustain rental demand across metropolitan corridors. EPA Tier 4 Final emissions standards compress asset life cycles and redirect capital toward compliant fleet procurement. Texas and California anchor national volume, with Houston and Los Angeles serving as primary equipment redistribution hubs for energy and commercial construction verticals.
Germany
Industrial refurbishment cycles and renewable energy construction drive sustained loader and crane utilization. EU Green Deal carbon-accounting requirements pressure fleet operators toward electric alternatives and F-Gas Regulation compliance. The Rhine-Ruhr and Munich-Stuttgart corridors concentrate rental demand, with Bavarian solar farm developers favoring rental models to match equipment scale to project phase.
China
Urban rail expansion and western provincial infrastructure programs sustain excavator rental volume despite property sector headwinds. MEE emissions standards and dual carbon goals accelerate electric equipment procurement in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Chengdu and Xi'an emerge as interior growth poles where rental penetration lags coastal markets by 15-20 percentage points.
India
National highway expansion and smart city programs drive earthmoving equipment demand across state-level contractors. BIS certification requirements and state pollution control board emissions enforcement fragment fleet compliance costs. Maharashtra and Gujarat lead installed base, with Mumbai-Ahmedabad industrial corridor projects adopting project-based rental structures to preserve liquidity for labor and bonding.
UAE
NEOM infrastructure and Expo legacy developments sustain premium crane and aerial lift utilization. Saudi and UAE national building codes mandate certified equipment documentation that favors established rental operators over informal market entrants. Dubai and Riyadh anchor Gulf demand, with Abu Dhabi municipal projects requiring bundled maintenance and operator provision through managed rental contracts.
Construction Equipment Rental Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in fleet management technology and certified maintenance services. The rental market structures around three concentration tiers: national branch networks with same-day metropolitan availability, regional specialists capturing industrial cluster density, and equipment-as-a-service platforms bundling maintenance and uptime guarantees. Strategic archetypes include fleet-scale aggregators, technology-integrated operators, and project-financing intermediaries. Competitive dynamics center on geographic density expansion and telematics platform integration.
Among North American fleet-scale operators, United Rentals and Sunbelt Rentals exemplify the branch-density archetype, while Ashtead Group occupies a position spanning transatlantic markets with digital tracking integration. These three entities represent the dominant competitive anchors against which mid-sized regional operators and emerging equipment-as-a-service platforms define differentiation strategies.
| Leading Market Players |
|---|
| United Rentals |
| Sunbelt Rentals |
| Herc Rentals |
| Loxam |
| Ashtead Group |
| Ahern Rentals |
| H&E Equipment Services |
| Aktio Corporation |
| Boels Rental |
| Others |
Cost & Logistics Intelligence
The Houston Ship Channel freight corridor compresses margins for Tier 4 Final engine imports while amplifying price differentiation between EPA-certified and non-compliant fleet tiers. Steel input volatility from domestic mills feeds through to daily rental rate adjustments, with certified-technician scarcity widening spreads between standard and configured-to-order equipment provisioning.
Pricing Analysis
The customization-premium spread separates standard daily-rate excavators from configured units with telematics integration and bundled maintenance. Pricing stratifies across premium, standard, and economy tiers based on EPA certification grade and operator provision inclusion. Cost compression in the economy tier is intensifying because smaller contractors defer ownership to preserve bonding capacity. DIY users exhibit highest price sensitivity while industrial clients with multi-year utility contracts accept premium positioning for uptime guarantees.
Supply Chain Analysis
Caterpillar, Komatsu, and John Deere manufacturing concentration in the United States, Japan, and Germany anchors global fleet procurement. High-grade steel, precision hydraulic systems, and EPA-certified diesel engines constitute critical input dependencies. Single-source vulnerability for Tier 4 Final engine platforms from Cummins and Volvo Penta creates procurement bottlenecks during fleet renewal cycles. Distribution runs through national branch networks with yard-based inventory positioning for same-day metropolitan availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician pipelines lag fleet electrification timelines, constraining maintenance capacity expansion and compressing service-level differentiation for rental operators unable to secure skilled labor.
For Market Incumbents: Entrench density advantages in Texas and California metropolitan corridors where municipal bond financing sustains project pipelines. Acquire regional specialists with established EPA-certified maintenance capabilities to offset technician scarcity. Deepen backward integration into telematics platforms to reduce third-party dependency for fleet tracking and predictive maintenance. For New Entrants and Emerging Players: Pursue project-based rental structures in the Mumbai-Ahmedabad industrial corridor where state-level contractors face BIS certification fragmentation and liquidity constraints. Target government agency procurement channels with carbon-accounting-compliant electric equipment offerings. Differentiate through managed rental contracts bundling operator provision and maintenance to capture industrial clients outsourcing compliance liability. For Investors and Strategic Acquirers: EPA Tier 5 emissions deliberations reshape the acquisition landscape by extending asset life uncertainty and redirecting capital toward electric alternatives. Five-to-ten year viability hinges on fleet operators' progress in battery-powered equipment procurement and technician retraining infrastructure. Acquisition targets should demonstrate established supplier certification partnerships with OEMs advancing electric drivetrain platforms. Monitor EPA rulemaking dockets for engine emissions thresholds as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition | Battery-powered excavators from Volvo and Caterpillar unlock urban corridor contracts with noise restrictions. |
| Telematics Platform Integration | Real-time fleet tracking through United Rentals and Ashtead Group systems reduces customer downtime penalties. |
| Certified Technician Pipeline Development | Vocational partnerships with community colleges address EPA-compliant engine diagnostics skill gaps. |
| Project-Based Contract Expansion | Milestone-linked structures align municipal bond financing timelines with contractor equipment liability. |
| EU Green Deal Alignment | F-Gas Regulation compliance and carbon accounting capture European infrastructure procurement channels. |
Research Approach
Operator-level perspectives from fleet managers, maintenance directors, municipal procurement officers, and OEM account executives anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, EPA emissions certification databases, and equipment registration records. Bottom-up equipment unit economics triangulated against top-down infrastructure spending forecasts.
Scenario-bracketing framed projections across the analysis window using equipment type, service duration, customer credit tier, and regional regulatory cluster segmentation. CAGRs derived from fleet utilization rate modeling and replacement cycle velocity assumptions. Forecast inputs incorporated EPA rulemaking timelines and electric equipment cost parity trajectories.
Sensitivities concentrate around EPA emissions standard acceleration, steel input price volatility, and certified technician training pipeline output. Forecasts reflect documented assumptions on infrastructure grant disbursement rates and municipal bond issuance volumes. Quarterly review of EPA regulatory dockets and OEM electric equipment launch schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Static Crane Market
Construction Equipment
Deep Hole Drilling Machines Market