
 Latin America Heavy Construction Equipment Rental Market | 2026-2036
Latin America Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Heavy Construction Equipment Rental Market Analytics
Modular equipment bundling is expanding across Latin America as rental providers package excavators with maintenance, operators, and fuel into single contracts. Madisa CAT leverages its Caterpillar dealership network to anchor premium fleet availability across Mexico and Central America. Grupo Vamos competes through aggressive fleet renewal and dense branch coverage in Brazilian metropolitan markets. SK Rental Group specializes in crane and lifting equipment, dominating Chilean mining-adjacent rental corridors.
Heavy construction equipment rental encompasses the short-to-medium-term provision of earthmoving, lifting, and material-handling machinery typically powered by diesel engines rated above 100 horsepower, designed for civil engineering, mineral extraction, and energy infrastructure projects. Excavators constitute the largest equipment type segment by fleet value, driven by trenching and foundation work across Brazilian infrastructure corridors. Monthly rental and long-term lease service models are capturing the fastest growth as mining and oil & gas operators seek to preserve capital flexibility amid commodity price volatility. Daily rental remains structurally important for emergency replacement and seasonal construction peaks, though margin pools concentrate in extended agreements with integrated maintenance clauses.
Brazil's ANTT and environmental agencies enforce emissions compliance and transport permit standards that directly shape fleet replacement cycles and cross-border equipment mobility. Mexico's PROFEPA and SEMARNAT regulations on noise and particulate matter are narrowing the operational window for older diesel equipment, pushing rental providers toward newer Tier-compliant assets. Stakeholders must monitor how proposed carbon-border adjustments and local content requirements in Argentine and Colombian public works tenders reshape competitive positioning for foreign versus domestically sourced rental fleets.
Market Dynamics
Capital discipline among mining and energy operators is compressing equipment ownership cycles across Latin America, with fleet outsourcing replacing balance-sheet-heavy asset accumulation in Chilean copper corridors and Brazilian iron ore basins.
Growth Catalysts
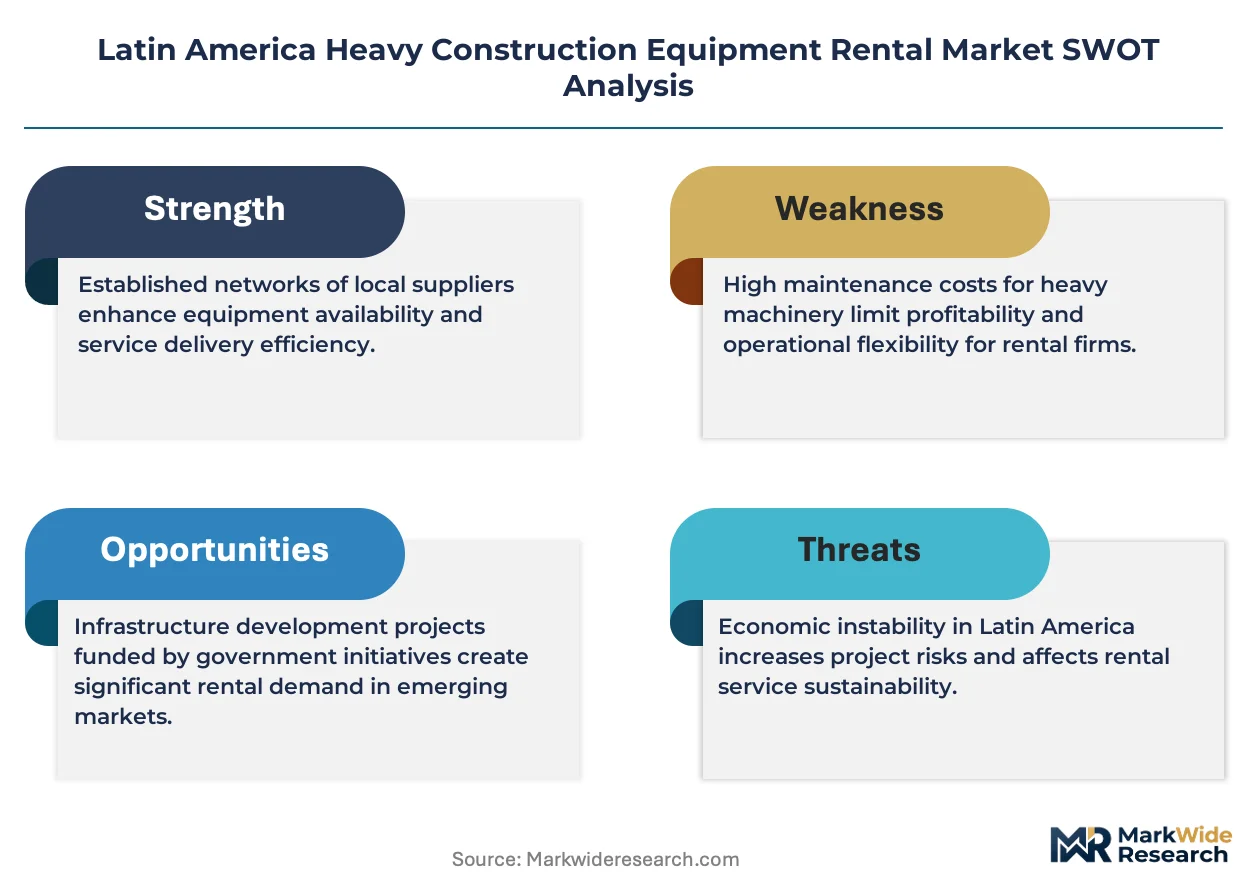
- ANTT Emissions Mandates:Brazil's freight logistics regulator is accelerating replacement of pre-Tier 3 diesel fleets, forcing rental providers to refresh inventory with compliant assets.
- Copper Price Volatility:Chilean and Peruvian mining contractors are preserving liquidity through operational leases rather than capital purchases, expanding addressable rental demand.
- Telematics Integration:Real-time fuel consumption and utilization tracking is enabling usage-based billing models that align rental costs with actual project output.
Market Restraints
- Import Duty Structure:Brazilian industrial equipment tariffs inflate new fleet acquisition costs by 35-60 percent, constraining rental provider expansion velocity.
- Diesel Price Exposure:Fuel represents 25-35 percent of total rental operating costs across the region, with pass-through clauses eroding margin predictability.
- Skilled Operator Scarcity:Certified equipment operators concentrate in São Paulo and Santiago metropolitan zones, limiting fleet deployment flexibility in secondary corridors.
Strategic Opportunities
- Colombian Infrastructure Tenders:Bogotá's 4G and 5G highway concessions are mandating contractor fleet flexibility clauses, opening rental penetration in a historically ownership-heavy market.
- Hybrid-Electric Fleets:Battery-assisted excavators and wheel loaders are qualifying for Mexican PROFEPA emissions credits, creating first-mover positioning in urban construction zones.
- Modular Service Bundling:Integrated contracts combining machinery with maintenance and certified operators are capturing premium pricing in Brazilian metropolitan construction corridors.
Industry Challenges
- Cross-Border Fleet Mobility:Mercosur customs protocols and national transport permits create 15-30 day equipment repositioning delays between Brazil, Argentina, and Uruguay.
- Depreciation Rate Mismatch:Rental providers face accelerated asset obsolescence as Brazilian environmental agencies tighten particulate matter enforcement faster than standard accounting depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Heavy Construction Equipment Rental Market |
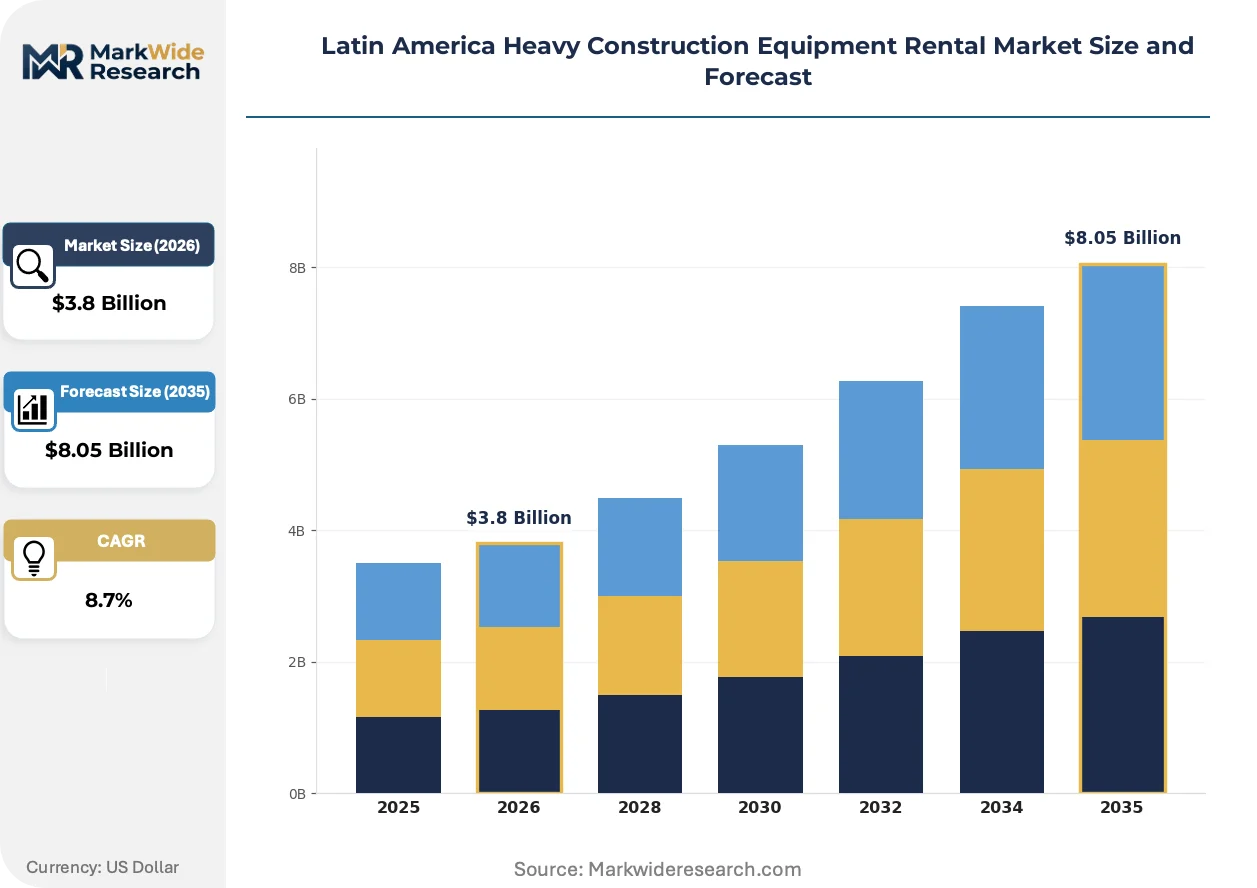
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Customer Type: Contractors, Construction Companies, Government Projects, Rental Agencies Application: Infrastructure, Mining, Oil & Gas, Demolition Service Model: Daily Rental, Weekly Rental, Monthly Rental, Long-term Lease |
| Companies Covered | Madisa CAT, SK Rental Group, Grupo Vamos, Casa do Construtor, APR Energy, Mills Solaris, Ouro Verde, Locar Guindastes e Transportes Intermodales, Aggreko, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Heavy Construction Equipment Rental Market Evolving Landscape
Digital fleet management and emissions compliance technologies are restructuring how rental providers compete on asset utilization and regulatory risk transfer across Latin American construction and extractive sectors.
Machine control and guidance systems are automating excavation precision in Brazilian foundation and trenching work. Mid-tier contractors in São Paulo's residential high-rise sector are adopting GPS-enabled grading and digging automation at twice the pace of smaller regional players. This capability compression is automating the traditional operator skill premium, enabling less experienced crews to deliver specification-grade earthwork.
PROFEPA and SEMARNAT noise and particulate regulations in Mexico are narrowing operational windows for older diesel equipment in urban construction zones. Industrial consequence includes forced fleet renewal among rental providers serving Mexico City and Monterrey metropolitan markets. Affected segments are responding by accelerating Tier 4 Final and Stage V engine deployment ahead of statutory deadlines to secure municipal permit preferences.
Flexible tenure structures are displacing rigid lease terms among mining and oil & gas operators seeking capital preservation. Long-term rental with embedded maintenance and mid-contract fleet reconfiguration options is capturing share from traditional finance leases in Chilean copper and Peruvian polymetallic extraction corridors. This shift is most visible in Antofagasta and Arequipa mining-adjacent rental markets where commodity price swings drive acute demand for operational expenditure flexibility.
Latin America Heavy Construction Equipment Rental Market Segmentation
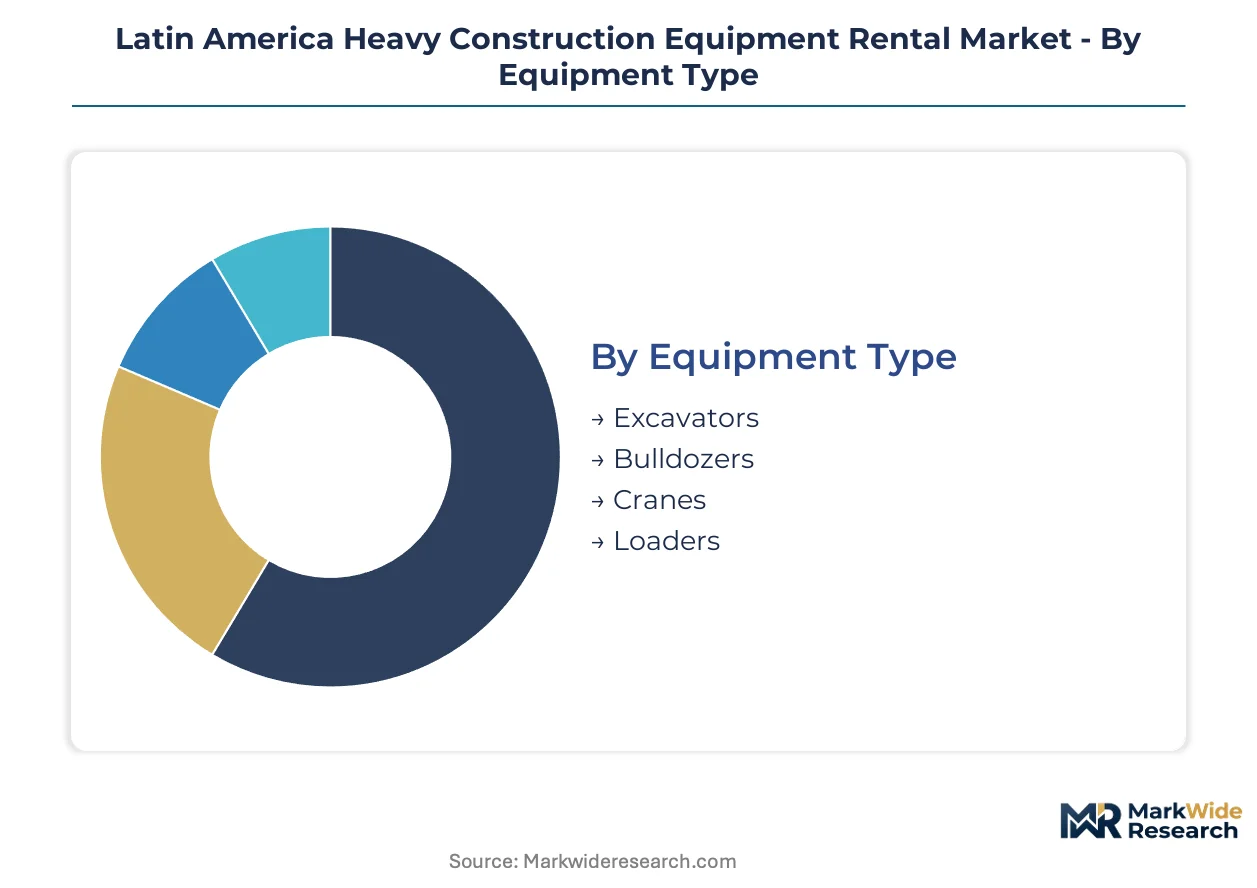
Equipment rental segmentation in Latin America reflects divergent capital strategies across extractive industries and urban construction corridors. Fleet composition and contract tenure choices vary sharply between Chilean mining contractors preserving liquidity and Brazilian infrastructure developers navigating ANTT compliance mandates.
Equipment Type:
Volume concentration favors earthmoving machinery, while premium positioning clusters in specialized lifting assets serving mining and energy infrastructure.
- Excavators:Hydraulic and crawler configurations dominate fleet value, with 20-40 ton class machines handling trenching and foundation work across São Paulo's construction corridor. Brazilian contractors favor this segment for its versatility across residential high-rise and highway earthwork applications.
- Cranes:Tower and mobile lifting equipment command the highest daily rates, concentrated in Chilean copper belt infrastructure and Brazilian precast concrete assembly. SK Rental Group's specialization in this segment reflects mining-adjacent demand for heavy-lift precision.
- Bulldozers:Track-type tractors serve mass earthmoving in Brazilian iron ore basins and Colombian highway cut-and-fill operations.
- Loaders:Wheel and track loaders handle material handling across Mexican urban construction zones and Peruvian polymetallic processing facilities.
Mature deployment sits with excavators. Newer deployment is concentrated in crane fleets upgraded for automated lifting systems.
Customer Type:
Contractor scale determines whether rental relationships emphasize operational flexibility or integrated service bundling with maintenance and certified operators.
- Contractors:Mid-tier civil engineering firms in Brazil's southeastern corridor drive monthly rental demand, combining equipment with operator provision to bypass skilled labor scarcity in secondary markets.
- Construction Companies:Large developers in São Paulo and Mexico City metropolitan zones favor long-term leases with embedded fleet reconfiguration clauses.
- Government Projects:Colombian 4G and 5G highway concessions mandate contractor flexibility clauses, accelerating rental penetration in historically ownership-heavy public works.
- Rental Agencies:Sub-leasing intermediaries serve seasonal demand spikes in Argentine agricultural infrastructure and Peruvian coastal construction.
Integrated service bundling is expanding most quickly among construction companies. Daily spot demand clusters with rental agencies.
Application:
Commodity price exposure shapes whether operators prioritize capital preservation through rental or balance-sheet asset ownership.
- Mining:Chilean copper and Brazilian iron ore contractors are expanding operational leases to preserve liquidity amid price volatility, with fleet outsourcing replacing ownership in Antofagasta and Carajás basins.
- Infrastructure:Brazilian highway and urban construction drives excavator and loader demand, with ANTT emissions mandates forcing fleet renewal toward Tier-compliant assets.
- Oil & Gas:Mexican and Colombian energy operators seek flexible tenure structures with mid-contract reconfiguration options.
- Demolition:Specialized hydraulic attachments and high-reach equipment serve São Paulo urban renewal and Mexico City vertical deconstruction.
Steepest expansion trajectory belongs to mining applications. Infrastructure maintains the largest installed rental base.
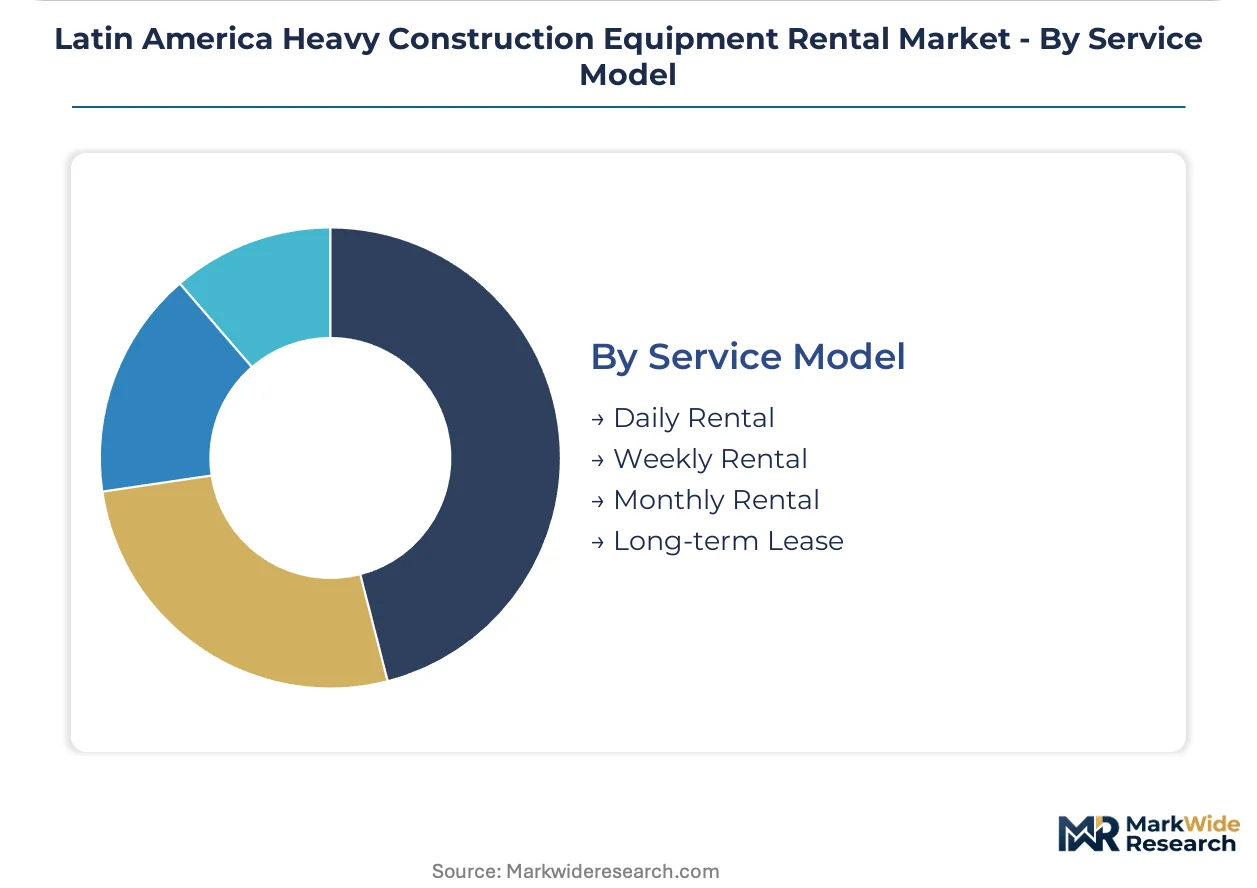
Service Model:
Tenure flexibility aligns rental costs with project cash flow patterns and regulatory compliance timelines.
- Monthly Rental:The dominant growth format captures mining and oil & gas operators seeking operational expenditure flexibility without capital commitment, climbing fastest in Chilean and Peruvian extraction corridors.
- Long-term Lease:Extended agreements with integrated maintenance clauses concentrate margin pools, favored by Brazilian construction companies navigating multi-year infrastructure concessions.
- Daily Rental:Emergency replacement and seasonal peak coverage remains structurally important, though margin compression limits provider investment.
- Weekly Rental:Intermediate tenure serves project mobilization phases and equipment trials before monthly commitment.
Long-term lease structures dominate mature mining relationships. Monthly rental is gaining share fastest in infrastructure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives and São Paulo state industrial tax abatements concentrate heavy equipment rental demand in Brazil's southeastern corridor. Chilean copper belt mining concessions and Peruvian polymetallic extraction zones anchor Andean rental fleet deployment.
Brazil
Highway concessions across São Paulo, Rio de Janeiro, and Minas Gerais drive excavator and loader demand. ANTT emissions mandates force fleet renewal toward Tier-compliant diesel assets. Rental providers concentrate branch networks in the southeastern construction corridor to capture multi-year infrastructure contracts.
Chile
Antofagasta and Atacama copper mining operations favor operational leases over equipment ownership. The Mining Ministry's environmental licensing requirements accelerate fleet modernization timelines. SK Rental Group anchors crane and lifting equipment availability in mining-adjacent rental corridors.
Mexico
PROFEPA and SEMARNAT noise regulations narrow operational windows for older diesel equipment in Mexico City and Monterrey construction zones. Battery-assisted excavators qualify for emissions credits in urban markets. Madisa CAT leverages Caterpillar dealership networks across Mexico and Central America.
Peru
Arequipa and Cajamarca polymetallic extraction contractors preserve capital through flexible rental structures. Ministry of Energy and Mines permitting processes extend equipment deployment cycles. Mining operators prioritize mid-contract fleet reconfiguration options amid copper price volatility.
Colombia
Bogotá's 4G and 5G highway concessions mandate contractor flexibility clauses in public tenders. National Infrastructure Agency contracting standards accelerate rental penetration in historically ownership-heavy markets. Fleet providers expand coverage to capture Andean infrastructure modernization programs.
Latin America Heavy Construction Equipment Rental Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin American rental markets. Market structure tilts toward consolidated national networks with dense branch coverage rather than fragmented regional operators. Three archetypes dominate: manufacturer-affiliated dealership networks, independent fleet-scale specialists, and mining-focused lifting equipment providers. Competitive moves concentrate on fleet renewal velocity and integrated service bundling rather than price-based rivalry.
Within the manufacturer-affiliated tier, Madisa CAT exemplifies dealership-network leverage across Mexico and Central America. Grupo Vamos occupies a position among Brazilian metropolitan-scale independents with aggressive fleet renewal programs. SK Rental Group anchors the specialized lifting segment in Chilean mining corridors. These three represent distinct strategic postures: premium brand alignment, dense urban coverage, and extractive-industry focus.
| Leading Market Players |
|---|
| Madisa CAT |
| SK Rental Group |
| Grupo Vamos |
| Casa do Construtor |
| APR Energy |
| Mills Solaris |
| Ouro Verde |
| Locar Guindastes e Transportes Intermodales |
| Aggreko |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up rental specialists anchor supply concentration across Brazil's southeastern corridor, compressing pricing discipline through fleet-scale advantages while passing diesel cost volatility to contractors via fuel-adjustment clauses. Their balance-sheet capacity for Tier-compliant asset renewal creates tiered pricing power that independent regional operators cannot match.
Pricing Analysis
Margin tightening in standard equipment tiers reflects Brazilian import duty burdens on new fleet acquisitions and ANTT-mandated emissions compliance investments. Three-tier pricing structure across premium, standard, and economy levels separates Tier 4 Final-certified fleets with telematics integration from older diesel assets and bare-metal daily rentals. Cost-down pressure on economy-tier daily rates accelerates because contractor procurement teams exploit transparent cross-provider quoting platforms. Mid-tier civil engineering firms in São Paulo's construction corridor exhibit highest price sensitivity, while Chilean mining contractors prioritize operational flexibility over rate minimization.
Supply Chain Analysis
Direct-to-rental-fleet channels handle hyperscale manufacturer relationships, with Caterpillar and Komatsu production in Brazil, Japan, and the United States feeding regional inventory pools. Steel plate, hydraulic systems, and Tier 4 Final engine components draw from East Asian and North American supplier networks. Single-source vulnerability concentrates in electronic control module supply for telematics-enabled fleet management systems. Distribution runs through manufacturer-affiliated dealership networks and independent fleet specialists with dense branch coverage in metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled usage-based billing is displacing fixed-term lease structures across Latin American rental markets, rewarding providers who integrate real-time utilization tracking with automated maintenance scheduling.
For Market Incumbents: Lock in fleet renewal velocity advantages by accelerating Tier 4 Final and hybrid-electric asset deployment ahead of PROFEPA and SEMARNAT regulatory deadlines in Mexican urban markets. Secure exclusive operator certification partnerships with São Paulo and Santiago technical institutes to defend against skilled labor scarcity threatening deployment flexibility. Prioritize backward integration into captive maintenance facilities across Brazil's southeastern construction corridor. For New Entrants and Emerging Players: Caterpillar and Komatsu dealership networks represent the most viable channel partnership path for fleet-scale expansion without manufacturer-direct relationships. Colombian 4G and 5G highway concessions offer the most penetrable white-space target, as mandated contractor flexibility clauses disrupt historically ownership-heavy public works procurement. Target hybrid-electric excavator positioning in Mexico City and Monterrey metropolitan zones to capture PROFEPA emissions credit advantages. For Investors and Strategic Acquirers: ANTT regulatory announcements accelerating pre-Tier 3 fleet retirement timelines are the leading indicator that consolidation momentum will intensify among Brazilian rental providers unable to fund compliance-driven capital expenditure. Long-term viability favors consolidated national networks with dense branch coverage and integrated service bundling capabilities over fragmented regional operators. Acquisition target archetype: independent fleet-scale specialists in Chilean mining-adjacent corridors with crane and lifting equipment specialization.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | Battery-assisted excavators qualify for Mexican PROFEPA emissions credits in urban construction zones. |
| Telematics Platform Integration | Real-time fuel consumption tracking enables usage-based billing aligned with project output. |
| Operator Certification Partnership | São Paulo technical institute alliances address skilled labor scarcity limiting fleet deployment. |
| Cross-Border Fleet Mobility Investment | Mercosur customs protocol navigation reduces 15-30 day equipment repositioning delays. |
| Modular Service Bundling Expansion | Integrated contracts combining machinery with maintenance capture premium pricing in Brazilian metros. |
Research Methodology
Trade publications, customs and freight logistics databases, and mining concession regulatory filings formed the secondary backbone of this analysis. Primary interviews with fleet procurement managers at Chilean copper contractors, Brazilian highway concession operators, and Mexican construction company equipment directors validated demand patterns and contract structure evolution. ANTT enforcement bulletins and PROFEPA emissions compliance records anchored regulatory impact assessment. Bottom-up equipment deployment estimates triangulated against top-down market size reconstruction.
Historical fleet utilization trendlines and commodity price cycle correlation analysis structured the projection framework. Segmentation modeling spanned equipment type, customer scale, application sector, and service tenure across the analysis window. CAGRs derived from equipment replacement cycle acceleration, emissions mandate compliance timelines, and mining capital discipline indicators. Diesel price pass-through elasticity and telematics adoption curves informed operating cost trajectory assumptions.
Caveats apply where Brazilian tariff policy shifts, Chilean copper price collapse scenarios, or Mercosur customs protocol renegotiations could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and commodity price band stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Smart Crane Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market