
 Compressed Earth Block Machine Market | 2026-2036
Compressed Earth Block Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Earth Block Machine Market Insights
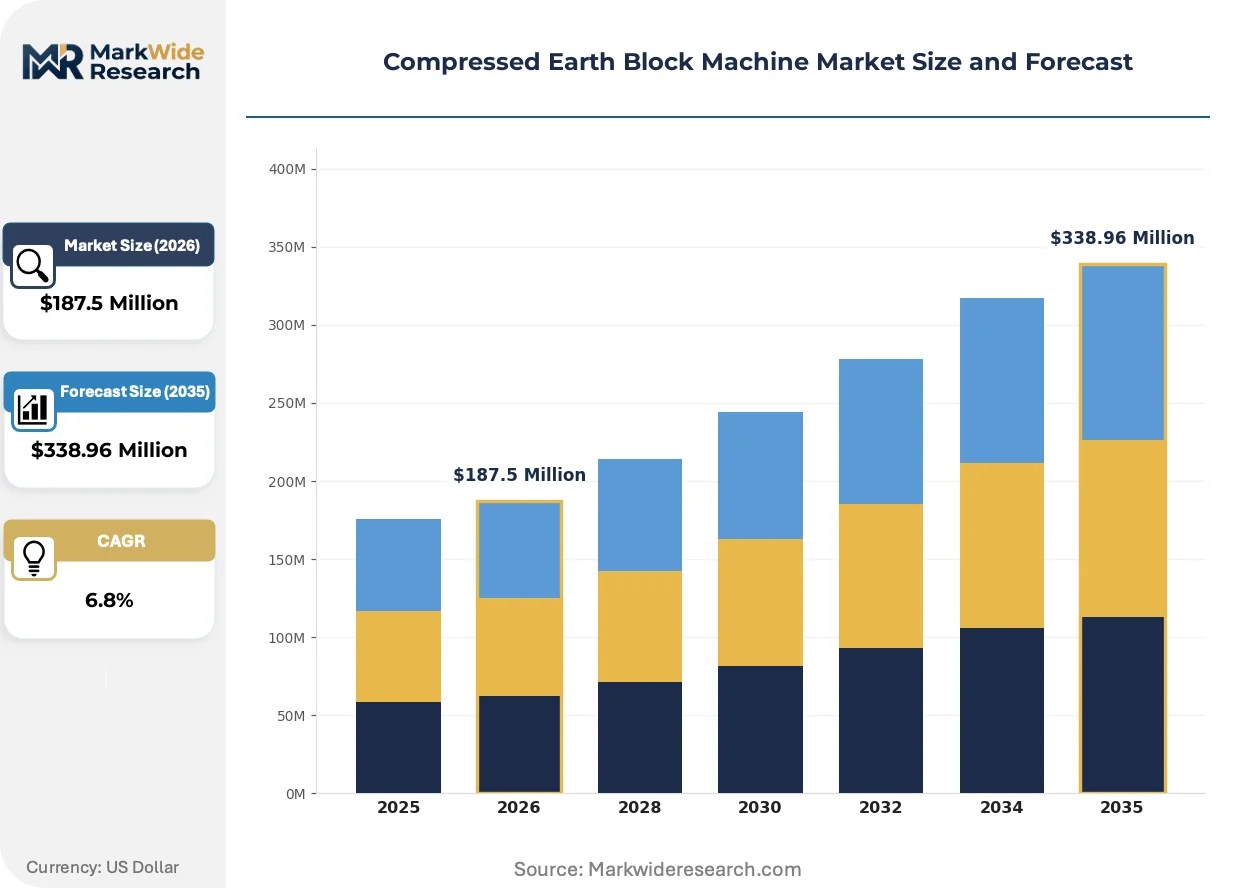
Government agencies are reorganizing procurement priorities toward mechanized soil-stabilization equipment for low-cost housing programs. Hydraform International dominates interlocking block system supply across African public-sector tenders. AECT leverages its Texas manufacturing base to sustain channel control in North American training and technical support services. Dwell Earth specializes in turnkey plant configurations that anchor its position among international development contractors.
A compressed earth block machine mechanically compresses a mixture of soil, stabilizer, and moisture into uniform masonry units under pressures typically ranging from 5 to 20 MPa, producing blocks that substitute for fired clay or concrete masonry in load-bearing wall construction. Semi-automatic configurations currently occupy the largest installed base due to their balance of labor intensity and capital efficiency, while fully automatic lines are capturing margin pools in commercial-scale projects where throughput consistency determines viability. Sustainable housing applications lead technology adoption as carbon-accounting frameworks elevate earthen materials over emission-intensive alternatives.
ISO 22475 geotechnical investigation standards, Kenya's KEBS building material certification, and India's BIS earthen masonry specifications collectively shape product compliance requirements and cross-border equipment acceptance. FEMA and Eurocode 6 provisions on seismic and moisture resistance directly influence machine design specifications for markets seeking formal construction integration. Stakeholders must monitor how national housing finance corporations revise material eligibility criteria, as these determinations gate machine demand more directly than raw technology performance metrics.
Market Dynamics
Formal construction integration requirements are compressing demand toward certified equipment configurations that satisfy FEMA seismic provisions and Eurocode 6 moisture-resistance standards, forcing manufacturers to redesign compression systems and curing protocols.
Growth Catalysts
- Public housing procurement:Kenya's National Housing Corporation and Rwanda's housing finance agencies are channeling development bank funds into decentralized block production facilities.
- KEBS certification alignment:Equipment meeting Kenya Bureau of Standards building material specifications gains preferential access to East African public tenders.
- Carbon accounting frameworks:Lifecycle assessment protocols for construction materials are elevating stabilized soil blocks over fired clay alternatives in institutional procurement scoring.
Market Restraints
- Stabilizer cost volatility:Cement and lime input prices fluctuate with energy markets, compressing margins for block producers operating on fixed-price municipal contracts.
- Skill concentration:Qualified soil mechanics technicians and compression equipment operators cluster in urban centers, limiting rural deployment scalability.
- Concrete masonry substitution:Established supply chains for conventional blocks in peri-urban zones create switching friction for developers under timeline pressure.
Strategic Opportunities
- India BIS pathway:Equipment certified to Bureau of Indian Standards earthen masonry specifications can access state-level rural housing programs.
- ISO 22475 integration:Machines incorporating automated geotechnical testing protocols reduce site preparation labor for development contractors.
- Turnkey plant bundling:Packaging compression equipment with soil testing kits and operator training creates stickier customer relationships among international development agencies.
Industry Challenges
- Certification timeline compression:FEMA and Eurocode 6 compliance documentation requires extended third-party validation cycles that delay revenue recognition.
- Aftermarket service dispersion:Remote project sites strain technical support networks, forcing manufacturers to train local technicians or absorb travel costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Earth Block Machine Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $338.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Hybrid Application: Residential Construction, Commercial Projects, Infrastructure Development, Sustainable Housing End User: Builders, Contractors, Government Agencies, NGOs Technology: Hydraulic Pressing, Rammed Earth, Interlocking System, Vibratory Compaction |
| Companies Covered | Advanced Earthen Construction Technologies (AECT), Dwell Earth, Verde Eco, Earth Block Technology, Zenith Maschinenfabrik GmbH, Hydraform International, PMSA, Reva Engineering Enterprises, KEME International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Earth Block Machine Market Trends and Innovations
Automation is penetrating soil-stabilization equipment at divergent rates across market tiers, with commercial-scale projects demanding throughput consistency while semi-automatic configurations retain dominance in decentralized production models.
Variable-frequency drive compression systems are displacing fixed-pressure mechanical configurations in commercial-scale installations. Large housing developers in Kenya and Rwanda are specifying these units for municipal contract fulfillment. The technology is displacing manual pressure adjustment protocols that previously required constant operator intervention.
Eurocode 6 masonry standards and FEMA building codes are tightening material certification requirements for seismic and moisture resistance. Equipment manufacturers must redesign mold geometries and curing chamber specifications to satisfy these provisions. East African markets seeking formal construction integration are most affected, with procurement specifications now requiring documented compliance traceability.
Development finance institutions are consolidating vendor relationships around turnkey equipment-and-training packages. International contractors previously sourced machines and operator instruction separately. This consolidation is most visible in Rwanda, where the national housing agency mandates bundled procurement for all publicly financed block production facilities.
Compressed Earth Block Machine Market Segmentation
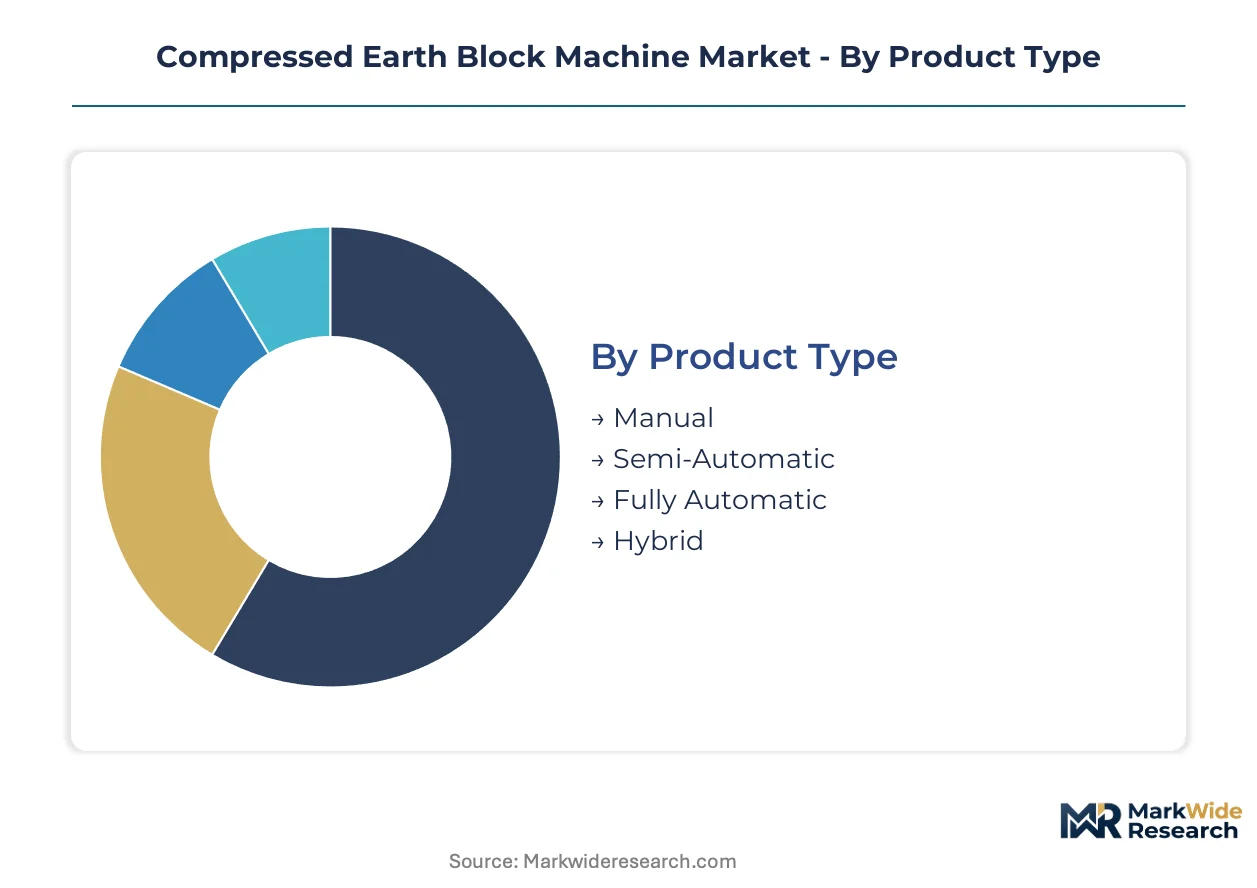
Equipment configuration determines channel economics in the compressed earth block machine market. Procurement patterns diverge sharply between decentralized rural production and centralized municipal supply chains.
Product Type:
Channel mix varies dramatically by automation level, with semi-automatic units flowing through equipment distributors while fully automatic lines sell direct to housing developers.
- Manual:Hand-lever compression systems operate without external power, suiting off-grid rural sites. Demand clusters in remote Ethiopian highlands and northern Nigerian settlements where electrification remains unreliable and labor costs stay minimal.
- Semi-Automatic:Motorized compression with manual material feeding balances throughput against capital outlay. Kenyan county governments and Rwandan district housing offices specify these units for decentralized block production under development bank financing.
- Fully Automatic:Integrated material handling, compression, and ejection systems achieve consistent output for commercial-scale projects. Large housing developers in Nairobi and Kigali deploy these for municipal contract fulfillment where timeline penalties apply.
- Hybrid:Configurable power modes switch between grid and renewable sources. Off-grid solar integration attracts mission-driven housing programs in Tanzania and Malawi.
Semi-automatic configurations dominate installed base. Fully automatic lines represent where expansion concentrates.
Application:
Cost tier segmentation separates premium certified equipment for formal construction from economy units serving informal building.
- Residential Construction:Single-family and multi-family housing projects specify stabilized soil blocks for wall assembly. Rwanda's Vision City development and Kenya's affordable housing initiative drive specification of KEBS-certified equipment.
- Commercial Projects:Retail, office, and institutional buildings require load-bearing masonry meeting Eurocode 6 standards. Equipment serving this tier incorporates automated curing chambers and compression monitoring systems.
- Infrastructure Development:Schools, health clinics, and administrative buildings in rural districts employ interlocking block systems. District procurement offices in Uganda and Burundi favor turnkey plant configurations.
- Sustainable Housing:Carbon-accounting protocols elevate earthen materials in green building certification schemes. Development finance institutions weight lifecycle assessments heavily in equipment vendor selection.
Residential construction commands volume leadership. Sustainable housing applications show steepest expansion trajectory.
End User:
Customer type determines service bundling requirements, with government agencies demanding training packages NGOs rarely require.
- Builders:Small-scale construction firms purchase semi-automatic units through equipment distributors. Price sensitivity drives preference for manual and hybrid configurations in peri-urban markets.
- Contractors:Mid-sized construction companies operating municipal contracts specify fully automatic lines with documented compliance traceability. Kenyan and Rwandan public tenders require KEBS certification.
- Government Agencies:National housing corporations and district development offices procure turnkey plant configurations. Rwanda's national housing agency mandates bundled equipment-and-training packages.
- NGOs:International development organizations deploy manual and semi-automatic units in refugee settlements and post-disaster reconstruction. UN-Habitat programs in East Africa favor interlocking block systems for community-based production.
Government agencies anchor formal procurement volume. NGO deployment is climbing fastest among decentralized production models.
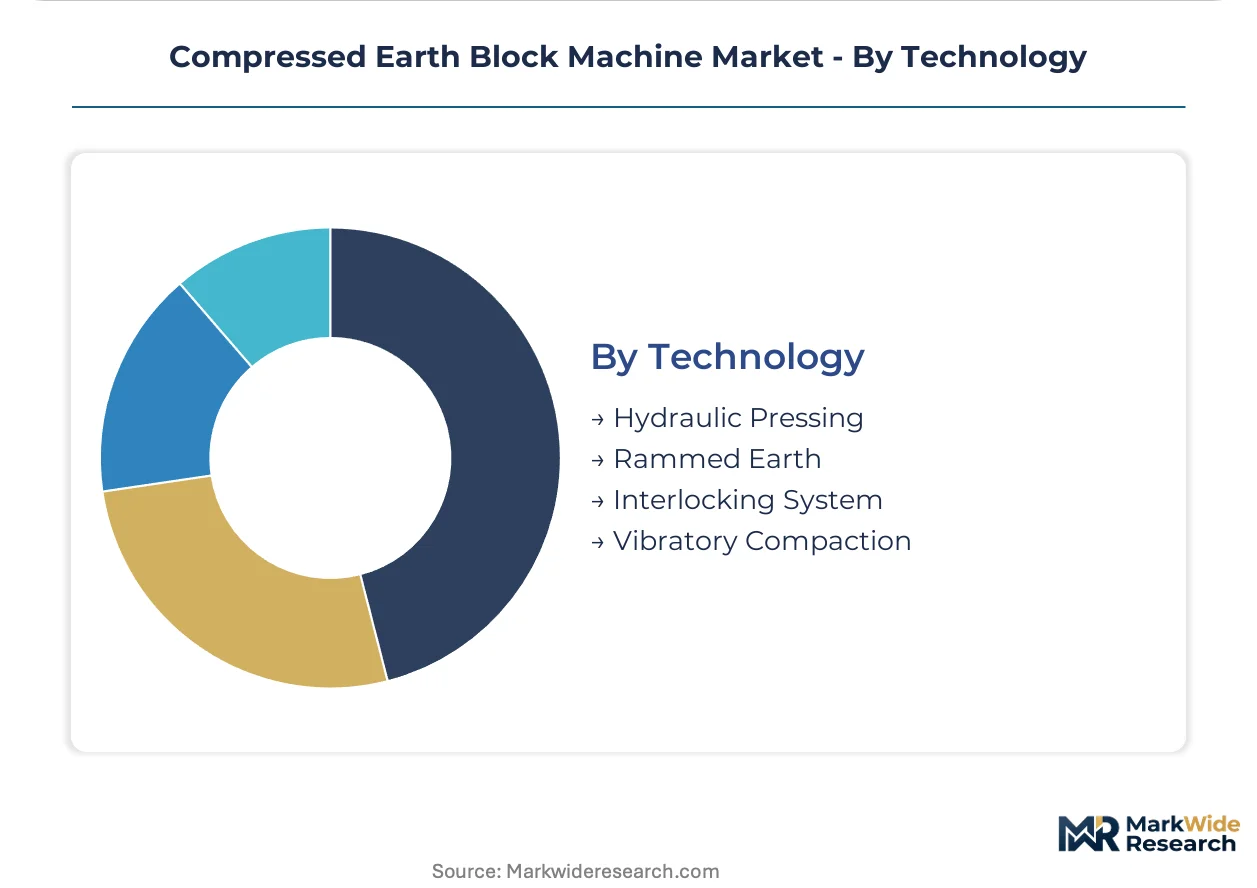
Technology:
Volume concentration follows technology maturity, with hydraulic pressing established and interlocking systems gaining specification share.
- Hydraulic Pressing:Oil-driven compression cylinders deliver consistent pressure from 5 to 20 MPa. This mature technology dominates commercial-scale installations across Kenyan municipal housing projects.
- Rammed Earth:Layered soil compaction produces monolithic wall sections rather than discrete blocks. Specialist contractors in France and Germany employ this technique for high-end residential architecture.
- Interlocking System:Mold geometries create self-aligning block profiles that reduce mortar requirements. Hydraform International's proprietary designs dominate African public-sector tenders.
- Vibratory Compaction:High-frequency vibration densifies soil-stabilizer mixtures without hydraulic pressure. Lower maintenance requirements attract remote site operators in Tanzania and Mozambique.
Hydraulic pressing retains installed base dominance. Interlocking systems are gaining specification share fastest in East African public housing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian equipment fabricators supply semi-automatic block machines to East African housing agencies under development bank financing arrangements. South African manufacturers export hydraulic pressing systems to sub-Saharan public works departments. Chinese producers dominate vibratory compaction equipment shipments to Southeast Asian infrastructure programs.
United States
FEMA building codes drive specification of seismic-certified compression equipment for disaster-resistant housing prototypes. The International Building Code adoption across jurisdictions elevates documented compliance traceability requirements. Texas-based fabricators anchor North American technical support networks for operator training services.
Kenya
Kenya's National Housing Corporation channels World Bank funds into county-level block production facilities. KEBS certification mandates govern equipment eligibility for public tenders. Nairobi and Mombasa industrial zones concentrate turnkey plant procurement for Vision 2030 affordable housing clusters.
Rwanda
Rwanda Housing Finance Agency mandates bundled equipment-and-training packages for all publicly financed facilities. District development offices specify interlocking block systems for decentralized rural construction. Kigali's special economic zone hosts commercial-scale fully automatic line deployments for municipal contract fulfillment.
India
Bureau of Indian Standards earthen masonry specifications open state-level rural housing program access for certified equipment. Pradhan Mantri Awaas Yojana subsidies accelerate semi-automatic unit adoption in Maharashtra and Gujarat. Reva Engineering Enterprises anchors domestic fabrication capacity for village-level production models.
Germany
Eurocode 6 masonry standards tighten moisture-resistance certification requirements for export-bound equipment. Zenith Maschinenfabrik GmbH represents precision engineering archetypes serving African public-sector tenders. Bavarian technical institutes collaborate on automated curing protocol development for tropical climate adaptation.
Compressed Earth Block Machine Market Competitive Landscape
Player mix skews toward regional specialists with established development finance relationships rather than diversified construction equipment conglomerates. Market structure fragments across hydraulic pressing, interlocking system, and vibratory compaction technology vectors. Strategic archetypes include turnkey solution bundlers, certification-focused premium tier suppliers, and volume-oriented semi-automatic fabricators. Competitive moves concentrate on geographic expansion through local assembly partnerships and technology licensing for climate-specific adaptation.
Among Africa-focused interlocking system specialists, Hydraform International exemplifies the turnkey bundling archetype through its dominance of public-sector tender specifications. Texas-based Advanced Earthen Construction Technologies occupies a position within the North American technical support tier, leveraging proximity to FEMA code development processes. German precision engineering representation sits with Zenith Maschinenfabrik GmbH, which anchors Eurocode 6 compliance documentation capabilities for export markets. Dwell Earth represents the international development contractor specialization vector through its turnkey plant configuration focus.
| Leading Market Players |
|---|
| Advanced Earthen Construction Technologies (AECT) |
| Dwell Earth |
| Verde Eco |
| Earth Block Technology |
| Zenith Maschinenfabrik GmbH |
| Hydraform International |
| PMSA |
| Reva Engineering Enterprises |
| KEME International |
| Others |
Pricing and Supply Chain Analysis
FEMA seismic certification and Eurocode 6 moisture-resistance documentation gate both equipment qualification and price stratification in the compressed earth block machine market. Buyers seeking formal construction integration must absorb premium pricing for validated compliance traceability, while uncertified configurations compete on capital outlay alone in informal building segments.
Pricing Analysis
Fixed-pressure mechanical configurations trade at substantial discounts to variable-frequency drive compression systems now specified by Kenyan and Rwandan municipal contractors. Three-tier pricing structure across premium certified, standard semi-automatic, and economy manual levels reflects certification grade and after-sales bundling intensity. Pricing pressure stems from cement and lime stabilizer cost volatility compressing block producer margins. Government agencies exhibit lowest price sensitivity given development bank financing availability, while peri-urban builders face acute capital constraints.
Supply Chain Analysis
India and South Africa anchor semi-automatic hydraulic pressing fabrication for East African public housing tenders, while Germany precision-engineers Eurocode 6 compliant systems for export markets. Steel compression cylinders, hydraulic pump assemblies, and soil-stabilizer mixing chambers constitute critical component dependencies. Single-source vulnerability concentrates in specialized mold geometry suppliers serving interlocking system specialists. Distribution runs through equipment distributors for manual and semi-automatic tiers, with fully automatic lines selling direct to housing developers and government procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical support and operator training services are expanding faster than hardware sales as Rwanda's national housing agency mandates bundled procurement for all publicly financed facilities. This service-attach dynamic reorients vendor economics toward recurring revenue streams.
For Market Incumbents: Fortify certification documentation capabilities against tightening FEMA and Eurocode 6 validation timelines that delay revenue recognition. Invest in Kenyan and Rwandan local assembly partnerships to compress logistics costs and accelerate aftermarket response. Channel control through distributor networks for semi-automatic tiers remains defensible against Chinese vibratory compaction entrants. For New Entrants and Emerging Players: Differentiate on ISO 22475 integrated geotechnical testing protocols that reduce site preparation labor for development contractors. Target Tanzania and Malawi mission-driven housing programs where off-grid solar-hybrid configurations face limited incumbent penetration. Pursue turnkey plant bundling with soil testing kits to match Rwanda's procurement specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fully automatic commercial-scale lines as variable-frequency drive technology and automated curing chambers raise equipment costs. Acquire regional specialists with established KEBS certification pathways and development bank vendor relationships. Monitor national housing finance corporation material eligibility criteria revisions as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| KEBS Certification Investment | Unlocks preferential access to Kenya National Housing Corporation county-level tenders. |
| Turnkey Plant Bundling | Aligns with Rwanda Housing Finance Agency mandated procurement specifications. |
| Local Assembly Partnership | Reduces logistics costs and accelerates technical support response in East African markets. |
| Variable-Frequency Drive Integration | Addresses Kenyan municipal contract requirements for throughput consistency and timeline compliance. |
| Operator Training Program Expansion | Captures service-attach revenue streams growing faster than hardware sales. |
Research Methodology
The analysis maps manual, semi-automatic, fully automatic, and hybrid equipment configurations, each validated through equipment distributors, government procurement officers, development agency program managers, and soil mechanics technicians. Primary interviews with Kenyan county housing directors and Rwandan district development offices combined with secondary validation from KEBS certification records, World Bank procurement databases, and Eurocode 6 technical documentation. Bottom-up county-level demand aggregation and top-down development bank financing flow analysis provided triangulation.
Consistency checks against FEMA building code adoption timelines and carbon-accounting framework penetration rates validated projection outputs across the analysis window. Segmentation dimensions modeled include automation level, application type, end-user category, and compression technology. CAGRs derived from equipment shipment tracking and public tender award analysis. Stabilizer cost volatility indices and certification timeline documentation informed scenario weighting.
Material uncertainties — regulatory timeline compression, development bank funding allocation shifts, and stabilizer input price spikes — sit outside the modeled envelope. Forecasts reflect assumptions on formal construction integration rates and national housing program execution pace. Recalibration cycles align with material shifts in KEBS eligibility criteria and FEMA code revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Case Erectors Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Jackhammer Market
Construction Equipment
Shield Machines Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Europe Crane Market
Construction Equipment
Indonesia Construction Equipment Market