
 Cutting and Bending Machine Market | 2026-2036
Cutting and Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting and Bending Machine Market Outlook
ISO 23125 safety certification for machine tools is rotating the competitive field toward vendors with documented compliance engineering. Amada Co. Ltd leverages its captive servo-drive technology to command premium positioning in precision sheet metal shops. TRUMPF Group anchors European supply through vertically integrated laser source production. Bystronic Group specializes in software-integrated cutting workflows that reduce nesting waste for job-shop operators.
Cutting and bending machines encompass equipment that severs or permanently deforms metal stock using mechanical force, thermal energy, or fluid pressure, with CNC systems achieving positional accuracies within 0.01 mm for complex contour generation. These systems serve primary industrial purposes in transforming raw metal into dimensioned components for assembly operations. Laser Cutter systems capture the highest value per unit among product types, while CNC Machine configurations are displacing hydraulic alternatives in high-mix, low-volume fabrication environments. Metal Fabrication applications generate the deepest installed base, though Aerospace Engineering requirements for titanium forming are driving accelerated replacement cycles in the technology tier.
CE marking under the EU Machinery Directive and OSHA lockout/tagout standards in the United States jointly elevate barrier-to-entry for non-compliant imports, while China's SAMR enforcement of GB energy-efficiency labels is reshaping procurement criteria for domestic buyers. The European Union's F-Gas Regulation further constrains refrigerant-based cooling options for high-power laser systems, pushing OEMs toward liquid-cooled architectures. Stakeholders must weigh regulatory compliance timelines against the capital deployment needed to capture shifting demand in electrified manufacturing ecosystems.
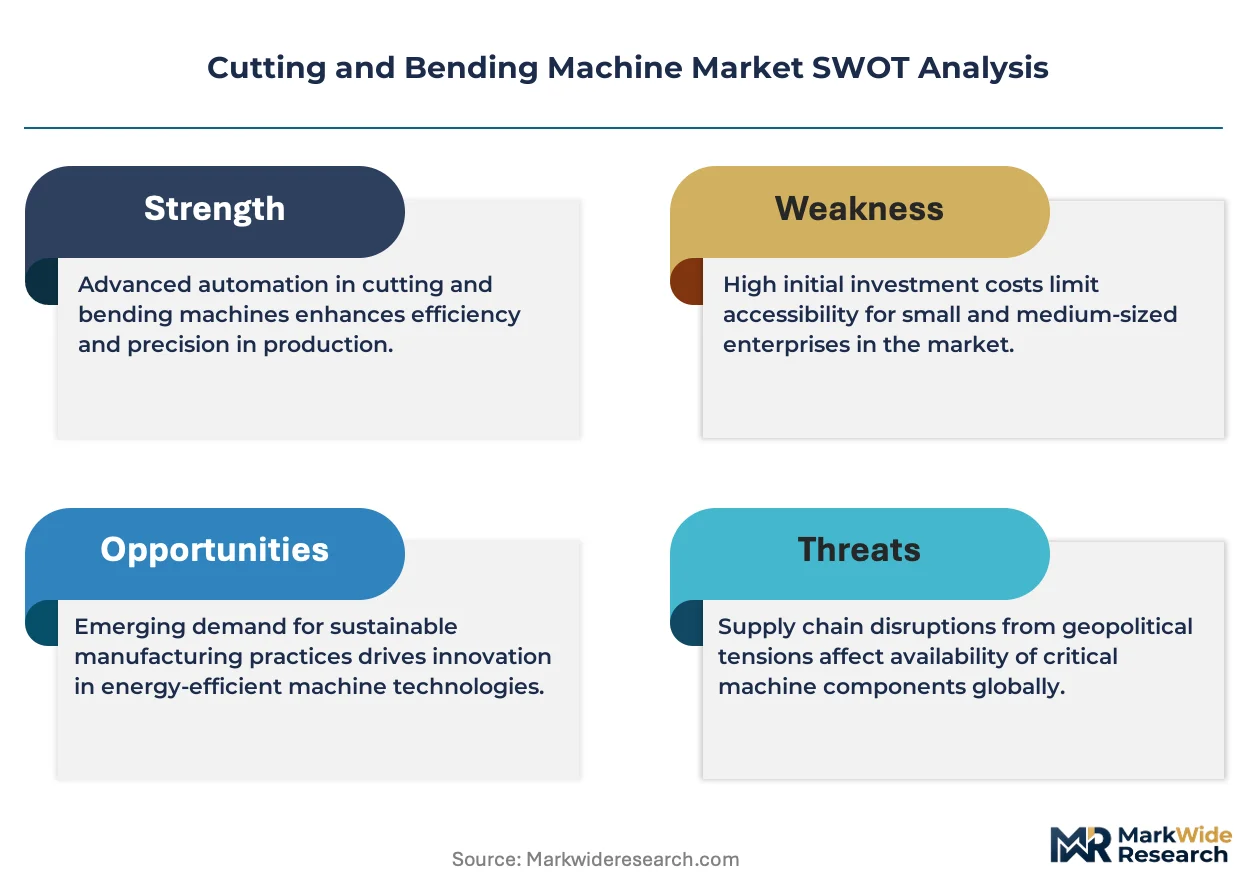
Market Dynamics
Servo-electric actuation is displacing hydraulic power units across precision fabrication, compressing maintenance intervals and energy draw while demanding recalibrated workforce competencies.
Growth Catalysts
- Automotive retooling:Electric vehicle platform rollouts in Germany and China are mandating automated bending lines for aluminum-intensive chassis architectures.
- GB 17167 energy metering:China's mandatory energy-efficiency monitoring for industrial equipment is accelerating replacement of legacy mechanical presses in export-oriented supplier parks.
- Titanium forming demand:Aerospace Engineering specifications for complex contour generation are pulling high-force servo-hydraulic systems into active procurement cycles.
Market Restraints
- Copper and rare-earth magnet costs:Servo-motor supply chains concentrate in Chinese processing facilities, exposing OEMs to input price volatility and export quota uncertainty.
- CE Machinery Directive compliance:Third-party certification timelines for safety-integrated control systems extend delivery schedules by 4-8 months for non-European vendors.
- Waterjet substitution:Cold-cutting systems for reflective and composite materials are capturing applications previously reserved for fiber-laser installations in job-shop environments.
Strategic Opportunities
- India's PLI scheme for machine tools:Production-linked incentives for capital goods manufacturing are creating localized assembly footholds for mid-range CNC bending systems.
- Laser-software convergence:Real-time nesting algorithms paired with high-speed cutting heads are enabling zero-waste workflows that command premium positioning in sheet-metal job shops.
- Refrigerant cooling phaseout:The EU F-Gas Regulation is pushing liquid-cooled laser architectures that open service-contract revenue streams for thermal management retrofit kits.
Industry Challenges
- ISO 23125 safety engineering scarcity:Documented compliance expertise for machine-tool functional safety remains concentrated among German and Japanese engineering consultancies, inflating project staffing costs.
- Legacy hydraulic integration:Retrofitting servo-electric controls into existing press-brake mechanical frames requires custom mechanical adaptation that fragments vendor support capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting and Bending Machine Market |
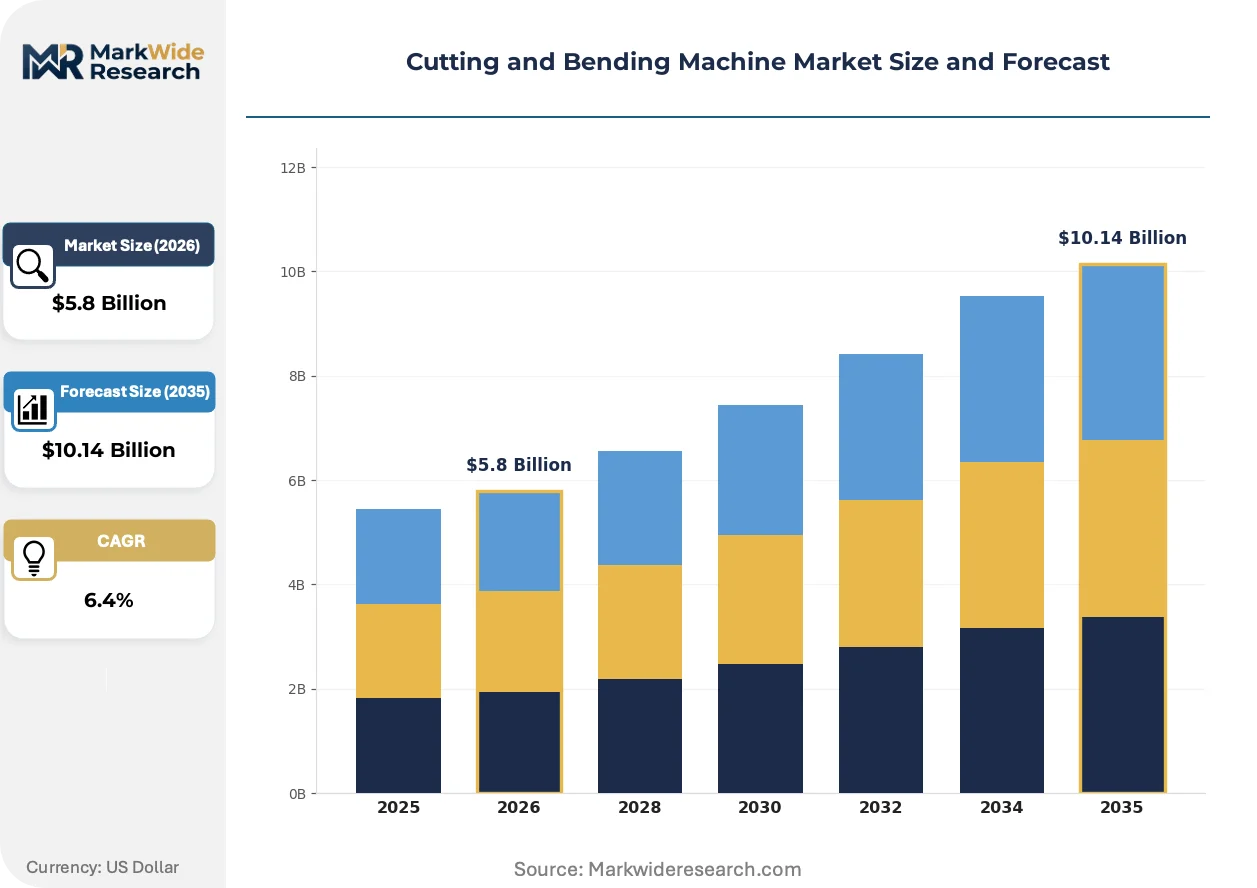
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Press, CNC Machine, Mechanical Bender, Laser Cutter Technology: Hydraulic Technology, Electric Technology, Pneumatic Technology, Manual Operation Application: Metal Fabrication, Construction, Automotive Manufacturing, Aerospace Engineering End User: Manufacturing Plants, Construction Companies, Automotive OEMs, Heavy Machinery Providers |
| Companies Covered | Amada Co. Ltd, TRUMPF Group, Bystronic Group, Prima Industrie S.p.A., HACO Group, LVD Group, Salvagnini Group, BLM Group, SOCO Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting and Bending Machine Market Strategic Shifts
Control-system architectures are converging with industrial IoT platforms, compressing the boundary between machine operation and predictive maintenance analytics.
Servo-electric press-brake technology is miniaturizing force-generation components while maintaining positional accuracy within 0.01 mm. Tier-one automotive stampers in Germany and Japan are adopting these compact systems for cell-based manufacturing layouts. The footprint reduction is enabling fabricators to reconfigure shop floors around flexible part-flow rather than fixed linear layouts.
The EU F-Gas Regulation is constraining refrigerant-based cooling for high-power laser resonators. OEMs are responding with closed-loop liquid-cooled designs that eliminate greenhouse-gas dependency. European job-shop operators face accelerated replacement timelines for thermal management subsystems, reshaping aftermarket parts demand.
After-sales service unbundling is fragmenting traditional OEM revenue models. End-users in North American metal fabrication are purchasing maintenance kits and remote diagnostics separately from capital equipment, pressuring vendors to price software subscriptions independently of hardware margins. This shift is most pronounced among multi-site operators with internal technical capabilities.
Cutting and Bending Machine Market Segmentation
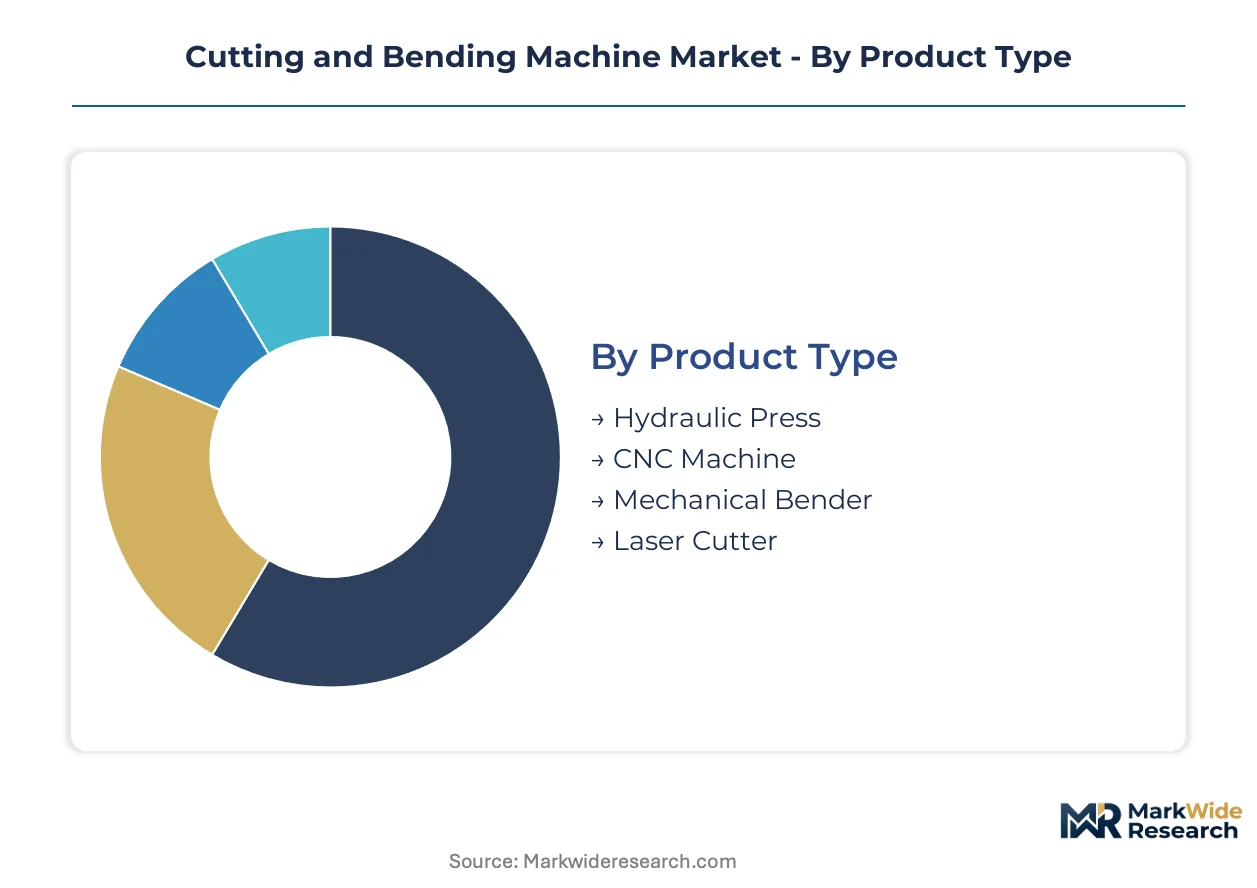
Segmentation reveals how capital deployment patterns diverge across equipment categories. Procurement channels for cutting and bending machinery split between direct OEM relationships for high-specification systems and distributor networks for standardized units.
Product Type:
Channel mix varies sharply by product complexity—laser cutters and CNC machines flow through technical sales engineers, while hydraulic presses and mechanical benders move through regional equipment distributors.
- Laser Cutter:Fiber and CO2 resonator systems achieve cutting speeds exceeding 100 meters per minute on thin-gauge steel. Demand concentrates in German automotive supplier parks where OEMs specify zero-defect edge quality for aluminum-intensive EV architectures.
- CNC Machine:Servo-electric and servo-hydraulic architectures deliver positional accuracy within 0.01 mm through closed-loop feedback control. German Mittelstand fabricators are displacing legacy hydraulic alternatives as GB 17167 energy metering mandates accelerate replacement cycles in export-oriented supplier bases.
- Hydraulic Press:High-force systems dominate heavy-gauge forming in shipbuilding and structural steel operations.
- Mechanical Bender:Entry-level equipment serves developing-market job shops with limited automation requirements.
By volume, CNC Machine leads. By growth pace, Laser Cutter is climbing the fastest.
Technology:
Margin structures align with energy efficiency tiers—electric technology commands premium positioning while hydraulic and pneumatic alternatives compete on first-cost metrics.
- Electric Technology:Servo-motor actuation eliminates hydraulic fluid maintenance while reducing energy draw by 40-60% versus conventional systems. Chinese SAMR enforcement of GB energy-efficiency labels is reshaping procurement criteria toward electric architectures in domestic supplier parks.
- Hydraulic Technology:High-force density suits thick-plate forming and heavy-gauge structural applications where electric actuation remains cost-prohibitive. German heavy machinery fabricators retain installed bases despite rising energy costs and maintenance intervals.
- Pneumatic Technology:Compressed-air systems occupy niche applications in explosive atmospheres and food-processing environments.
- Manual Operation:Hand-powered equipment persists in artisanal metalwork and educational training facilities.
By installed base, Hydraulic Technology dominates. By replacement velocity, Electric Technology is gaining share fastest.
Application:
Customer type determines specification intensity—job shops prioritize flexibility while dedicated production lines optimize for throughput.
- Metal Fabrication:General-purpose job shops generate the deepest installed base across cutting, bending, and forming operations. North American multi-site operators are unbundling after-sales service from capital equipment purchases, pressuring OEMs to price software subscriptions independently.
- Aerospace Engineering:Titanium and nickel-alloy forming demands high-force servo-hydraulic systems with thermal management for sustained operation. Specifications for complex contour generation are pulling active procurement cycles as airframe OEMs retool for next-generation platforms.
- Automotive Manufacturing:Stamping lines and chassis fabrication require automated bending cells with robotic part handling.
- Construction:Structural steel processors utilize heavy-gauge cutting and plate rolling for infrastructure projects.
By unit volume, Metal Fabrication leads. By specification intensity, Aerospace Engineering shows the steepest expansion trajectory.
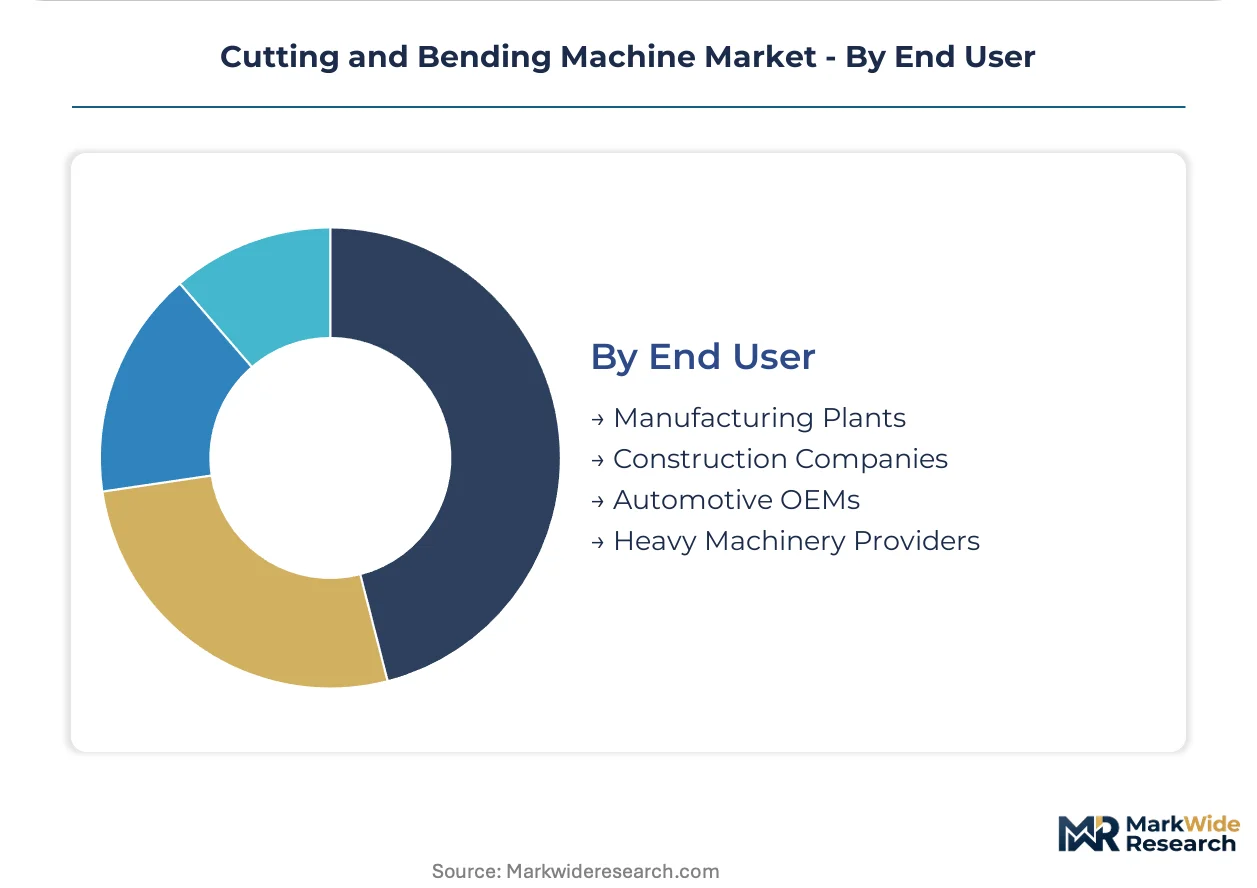
End User:
Procurement scale separates segments—automotive OEMs negotiate enterprise frameworks while construction companies purchase through equipment lessors.
- Automotive OEMs:Platform retooling for electric vehicle production mandates automated bending lines with aluminum-compatible tooling. German and Chinese manufacturers are expanding orders as they reconfigure stamping operations for battery-electric architectures.
- Manufacturing Plants:Diverse industrial fabricators maintain mixed equipment fleets across cutting, bending, and forming processes. India's PLI scheme for machine tools is creating localized assembly footholds for mid-range CNC bending systems serving this segment.
- Construction Companies:Project-based equipment utilization favors rental and lease arrangements over capital purchase.
- Heavy Machinery Providers:Mining and agricultural equipment OEMs source formed structural components from tiered supplier networks.
By capital deployment, Manufacturing Plants lead. By specification advancement, Automotive OEMs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs are redirecting capital flows across major manufacturing economies. Industrial clusters in Germany, China, India, Japan, and the United States are retooling fabrication infrastructure to meet tightening energy-efficiency mandates and automotive platform transitions.
Germany
Mittelstand metal fabricators in the industrial corridor are replacing legacy mechanical systems with servo-electric equipment. The EU F-Gas Regulation is accelerating phaseout of refrigerant-based cooling for laser systems. Stuttgart and Augsburg host concentrated supplier parks serving automotive OEMs retooling for electric vehicle architectures.
China
Export-oriented supplier bases are upgrading equipment to meet GB standards on machine tool energy efficiency. SAMR enforcement of GB energy-efficiency labels is reshaping procurement criteria across domestic supplier parks. Yangtze River Delta manufacturing hubs are absorbing automated bending lines for aluminum-intensive chassis production.
India
Production-linked incentives for capital goods manufacturing are creating localized assembly footholds for mid-range CNC bending systems. The PLI scheme for machine tools is attracting component suppliers to Gujarat and Maharashtra. Pune and Chennai industrial zones are expanding fabrication capacity for automotive tier-one suppliers.
Japan
Precision sheet metal shops are commanding premium positioning through captive servo-drive technology adoption. METI industrial efficiency guidelines are compressing payback periods for electric actuation investments. Nagoya and Osaka manufacturing clusters are integrating predictive maintenance analytics into press-brake operations.
United States
Multi-site operators with internal technical capabilities are unbundling after-sales service from capital equipment purchases. OSHA lockout/tagout standards elevate barrier-to-entry for non-compliant imports. Midwest fabrication hubs in Michigan and Ohio are replacing hydraulic alternatives with servo-electric press brakes.
Cutting and Bending Machine Market Competitive Environment
Listed leaders compete with private specialists across technology tiers and geographic reach. The vendor base splits between consolidated multinational groups with captive component production and mid-scale specialists with focused application expertise. Three archetypes dominate: integrated technology providers controlling upstream drive systems, software-centric workflow specialists, and regional equipment assemblers serving price-sensitive job shops. Competitive moves center on backward integration into servo-motor supply and geographic expansion through distributor network acquisition.
Within the integrated technology tier, Amada Co. Ltd and TRUMPF Group exemplify archetypes built on captive manufacturing of critical subsystems. Amada represents the servo-drive technology anchor, while TRUMPF occupies a position anchored in vertically integrated laser source production. Bystronic Group sits within the software-integrated workflow specialization, exemplifying competitive positioning built on nesting optimization and real-time process control rather than hardware manufacturing depth.
| Leading Market Players |
|---|
| Amada Co. Ltd |
| TRUMPF Group |
| Bystronic Group |
| Prima Industrie S.p.A. |
| HACO Group |
| LVD Group |
| Salvagnini Group |
| BLM Group |
| SOCO Machinery Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with servo-motor suppliers lock in both component access and cost visibility for European and Japanese OEMs retooling for electric vehicle platform demand. These contractual structures insulate fabricators from rare-earth magnet price volatility while compressing procurement lead times for high-force press-brake systems.
Pricing Analysis
Certification level (ISO 23125/CE-grade) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects safety-integrated control system documentation depth and aftermarket bundling intensity. Price erosion runs through mid-range CNC bending systems as Indian PLI-subsidized assemblers compress first-cost positioning. Job-shop operators with internal technical capabilities exhibit highest price sensitivity, while automotive OEMs negotiating enterprise frameworks prioritize specification compliance over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending inbound logistics cycles for laser resonator components and servo-drive assemblies. Manufacturing concentration in China, Germany, and Japan anchors component supply for precision motion systems, with rare-earth magnet processing concentrated in Chinese facilities. Single-source vulnerability in permanent-magnet supply chains exposes OEMs to export quota uncertainty. Distribution runs through technical sales engineers for high-specification laser and CNC systems, while standardized hydraulic equipment flows via regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where ISO 23125 certification documentation and CE Machinery Directive compliance engineering create defensible incumbent positions. Switching costs for end-users escalate once safety-integrated control systems are embedded in production workflows.
For Market Incumbents: Secure backward integration into servo-motor supply chains to insulate margin structures from rare-earth price volatility. Lock in channel control through exclusive distributor agreements in India's PLI-subsidized manufacturing zones. Waterjet substitution threats in job-shop environments demand accelerated software-subscription unbundling to capture recurring revenue independent of hardware cycles. For New Entrants and Emerging Players: Differentiate on liquid-cooled laser thermal management retrofit kits as EU F-Gas Regulation phaseout accelerates replacement demand. Target India's mid-range CNC bending segment where localized assembly incentives lower capital barriers. Pursue white-space in aerospace-tier titanium forming specifications where servo-hydraulic system scarcity concentrates among German and Japanese engineering consultancies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-integrated workflow specialists with independent nesting optimization platforms. Five-to-ten year viability favors vendors controlling captive servo-drive technology or vertically integrated laser source production. Acquisition target archetype: mid-scale specialists with documented ISO 23125 compliance engineering and established automotive OEM supplier relationships. Signal to watch: GB 17167 energy-metering enforcement intensity in Chinese export-oriented supplier parks as procurement criteria inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Supply | Captive rare-earth magnet sourcing insulates margins from Chinese export quota volatility. |
| Liquid-Cooled Laser Architecture Transition | EU F-Gas Regulation compliance opens thermal management retrofit contract revenue streams. |
| Software Subscription Unbundling | Independent predictive analytics pricing captures multi-site operator lifetime value. |
| Localized Assembly in PLI-Subsidized Zones | India's machine tool incentives reduce capital barriers for mid-range CNC bending entry. |
| ISO 23125 Compliance Engineering Investment | Documented functional safety expertise concentrates project staffing premium capture. |
Study Parameters
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, SEC 10-K filings, and industrial equipment registration databases. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure patterns across automotive, aerospace, and metal fabrication end-use segments.
Sensitivity analysis tested forecast robustness across rare-earth magnet price volatility scenarios and regulatory compliance timeline variations. Segmentation dimensions modeled include product type, actuation technology, application intensity, and end-user procurement scale across the projection horizon. CAGRs derived from equipment replacement cycle analysis, platform retooling schedules, and energy-efficiency mandate enforcement trajectories. Industry-specific inputs incorporated GB 17167 metering adoption curves and EU F-Gas Regulation phaseout schedules.
Decision-makers should treat outputs as directional under sustained automotive electrification capex and stable rare-earth supply chain configurations; material deviation would warrant model refresh. Forecasts assume continued SAMR enforcement intensity for Chinese domestic supplier parks and unaltered CE Machinery Directive certification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Soil Compaction Equipment Market