
 Friction Stir Welding Market | 2026-2036
Friction Stir Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Friction Stir Welding Market Intelligence
FAA and EASA airworthiness directives for fatigue-critical structures is expanding the addressable market for solid-state joining. Major automation providers like KUKA AG leverage robotics expertise to offer integrated systems for automotive production lines. In contrast, specialists such as Grenzebach Maschinenbau GmbH and PaR Systems LLC focus on large-format, customized gantry systems for the specific needs of aerospace and shipbuilding.
Friction stir welding is a solid-state joining process using a non-consumable rotating tool to generate intense frictional heat. It plasticizes materials below their melting point, creating high-integrity joints in aluminum alloys without requiring filler metals. Integrated machine systems lead the product category, aligning with automation trends in aerospace and automotive factories. Within technology, conventional friction stir is the standard, but refill friction stir variants are growing in applications like consumer electronics that demand a flawless surface.
ISO 25239 provides a critical quality and qualification framework for friction stir welding procedures, influencing global adoption. Regulations from the EPA concerning vehicle efficiency and China's MIIT promoting electric vehicle production indirectly support demand for FSW in lightweighting. Vendor success depends on developing specialized tool geometries and process controls for joining next-generation high-strength alloys and dissimilar materials.
Market Dynamics
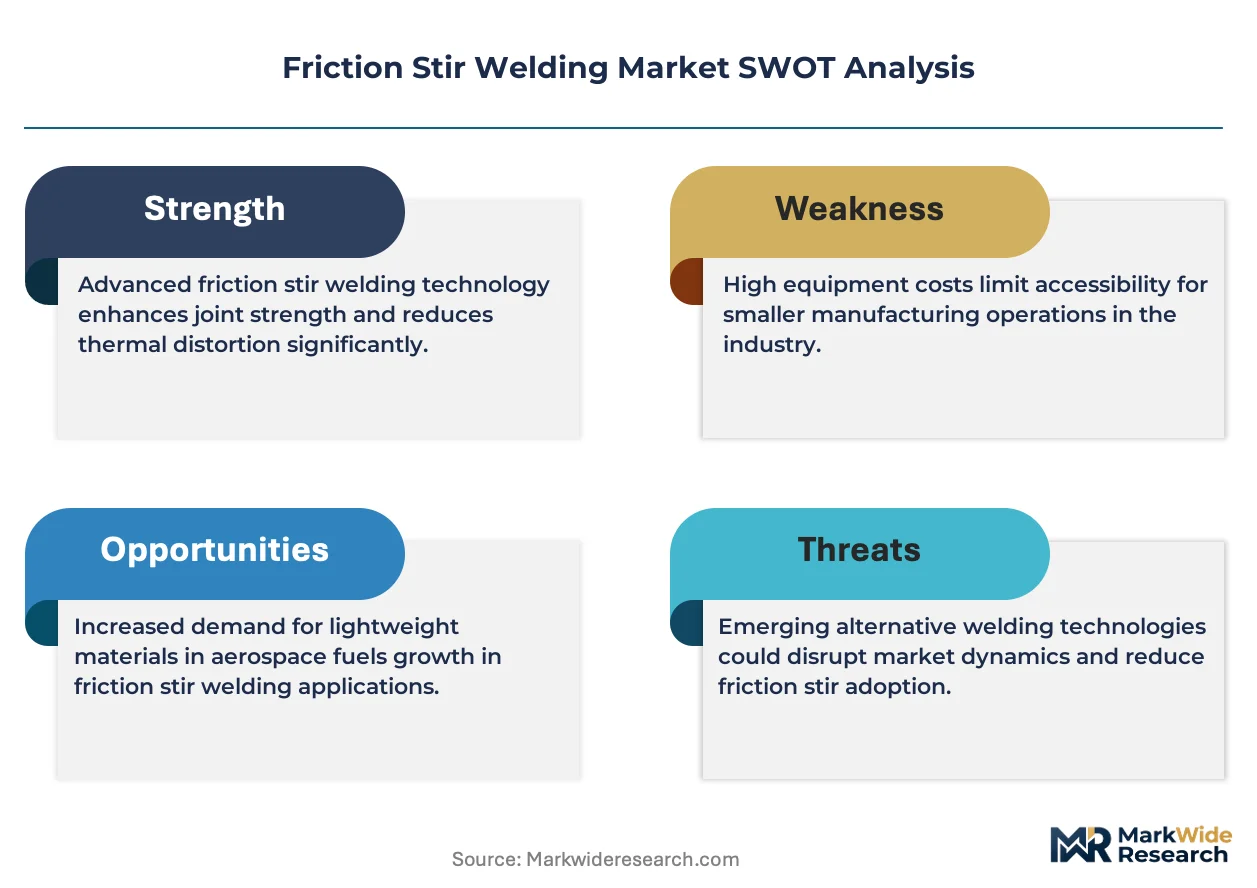
The central dynamic is the intensified push for lightweighting, driven by stringent fuel economy and emissions regulations in the automotive and aerospace sectors. This pressure elevates friction stir welding's value proposition for joining advanced aluminum alloys without compromising structural integrity.
Growth Catalysts
- Aerospace Directives:Airworthiness directives from the FAA and EASA for fatigue-critical structures expand the need for high-integrity solid-state joints, favoring FSW over traditional fusion welding.
- EV Production Mandates:Policies from China's MIIT promoting electric vehicle manufacturing directly stimulate demand for FSW equipment used in producing lightweight aluminum battery trays and enclosures.
- Quality Standardization:The ISO 25239 framework provides a global qualification path, de-risking adoption for high-reliability applications and facilitating broader industrial acceptance.
Market Restraints
- High Capital Outlay:The significant initial investment required for integrated robotic or gantry-based FSW systems is a barrier for small-to-medium enterprises compared to conventional welding equipment.
- Geometric Limitations:The process is less suited for complex three-dimensional contours and tight-radius curves, restricting its use in certain component designs compared to laser beam welding.
- Process Speed:Conventional FSW often has lower linear welding speeds than fusion processes like MIG or laser welding, challenging throughput in high-volume automotive production.
Strategic Opportunities
- Consumer Electronics:Refill friction stir variants offer a flawless surface finish, creating opportunities in the manufacturing of aluminum casings for laptops, tablets, and smartphones where aesthetics are paramount.
- AI-Powered Process Control:Integrating machine learning algorithms with real-time sensor data for adaptive control of tool rotation and force can optimize weld quality for dissimilar and next-generation alloys.
- Shipbuilding Applications:The technology presents an opportunity for joining large, flat aluminum panels used in the construction of high-speed ferries, naval vessels, and liquefied natural gas carriers.
Industry Challenges
- Specialized Skill Gaps:A shortage of welding engineers and machine operators with the requisite expertise in FSW process parameter development, tool design, and robotic programming hinders effective implementation.
- Complex Qualification Procedures:Navigating the extensive testing and documentation required by standards like ISO 25239 for procedure and personnel qualification is time-consuming and costly.
- Tooling Wear and Cost:The high cost and limited lifespan of specialized tool materials for welding high-strength steels or metal matrix composites is a key operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Friction Stir Welding Market |
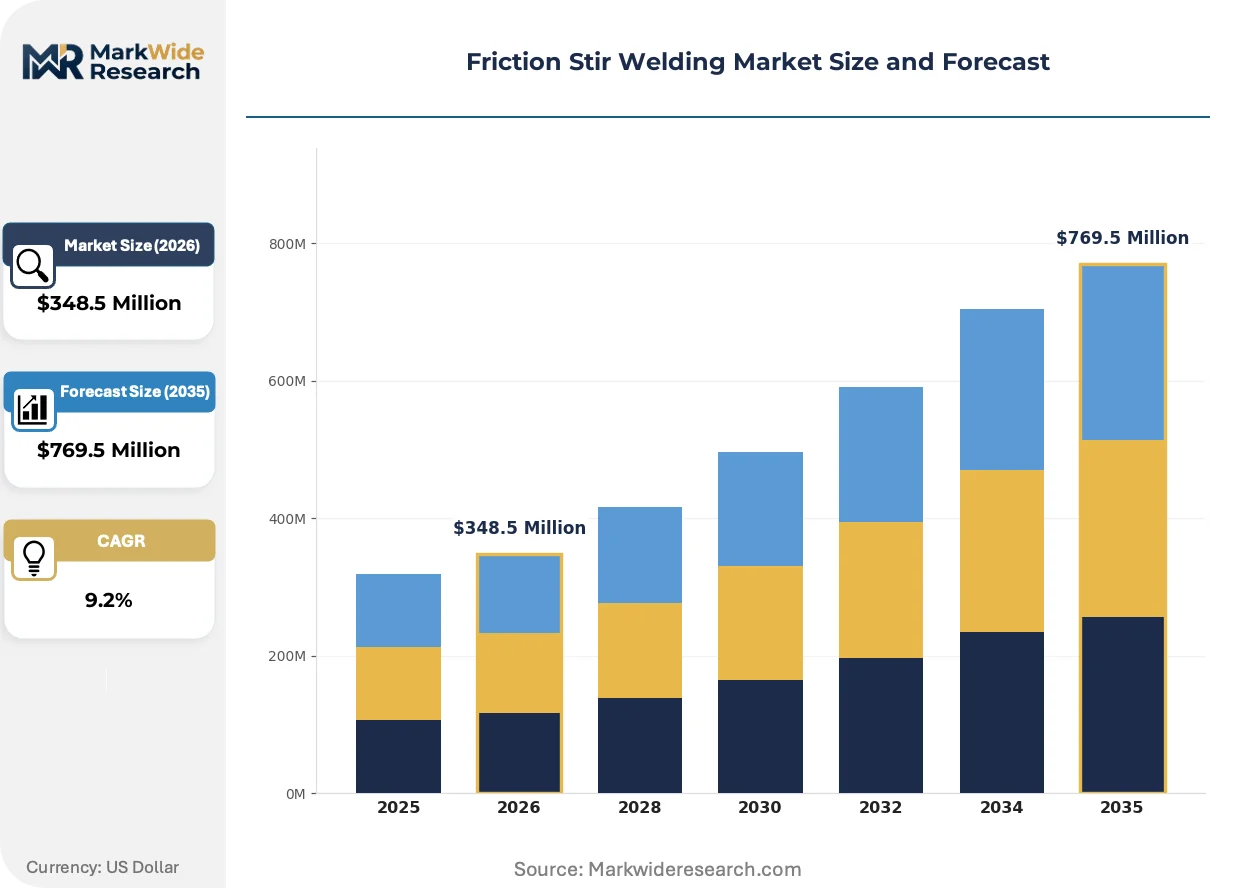
| Market Size in 2026 | $348.5 Million |
| Market Size in 2035 | $769.5 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Tool, Stationary Tool, Integrated Machine, Portable Machine Technology: Conventional Friction Stir, Bobbin Tool, Refill Friction Stir, Friction Bit Welding Application: Aerospace Components, Shipbuilding, Railroad Manufacturing, Consumer Electronics Assembly End User: Shipbuilders, Aircraft Manufacturers, Rail Operators, Electronics Assemblers |
| Companies Covered | Beijing FSW Technology Co. Ltd., Grenzebach Maschinenbau GmbH, KUKA AG, Yamazaki Mazak Corp., PaR Systems LLC, The Lincoln Electric Co., FOOKE GmbH, Hitachi High-Technologies Corporation, Bond Technologies, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Friction Stir Welding Market Strategic Shifts & Innovations
Automation and data integration are transforming friction stir welding from a specialized joining technique into a digitally controlled manufacturing process. This evolution is driven by the need for repeatable, high-quality joints in mass production environments like automotive and aerospace.
Robotic FSW systems combine a multi-axis industrial robot with a compact welding head, offering greater flexibility than traditional gantry machines. The automotive and general fabrication sectors are rapidly adopting these systems for complex welding paths. This development is modularizing the FSW equipment supply chain, enabling users to create customized, cost-effective work cells.
The European Union's stringent CO2 emission performance standards for new vehicles directly incentivize aggressive lightweighting strategies. This regulatory pressure compels automakers to utilize more aluminum alloys for vehicle bodies, battery enclosures, and structural components. Consequently, the automotive segment is accelerating investment in FSW lines to meet both performance targets and production volumes.
A procurement shift is emerging, with companies opting for specialized FSW contract manufacturing services for initial prototyping and low-volume production runs. This model bypasses the high capital expenditure and lengthy qualification of an in-house machine, disrupting traditional equipment sales channels. This service-based approach is most prominent in the aerospace and medical device industries.
Friction Stir Welding Market Segmentation
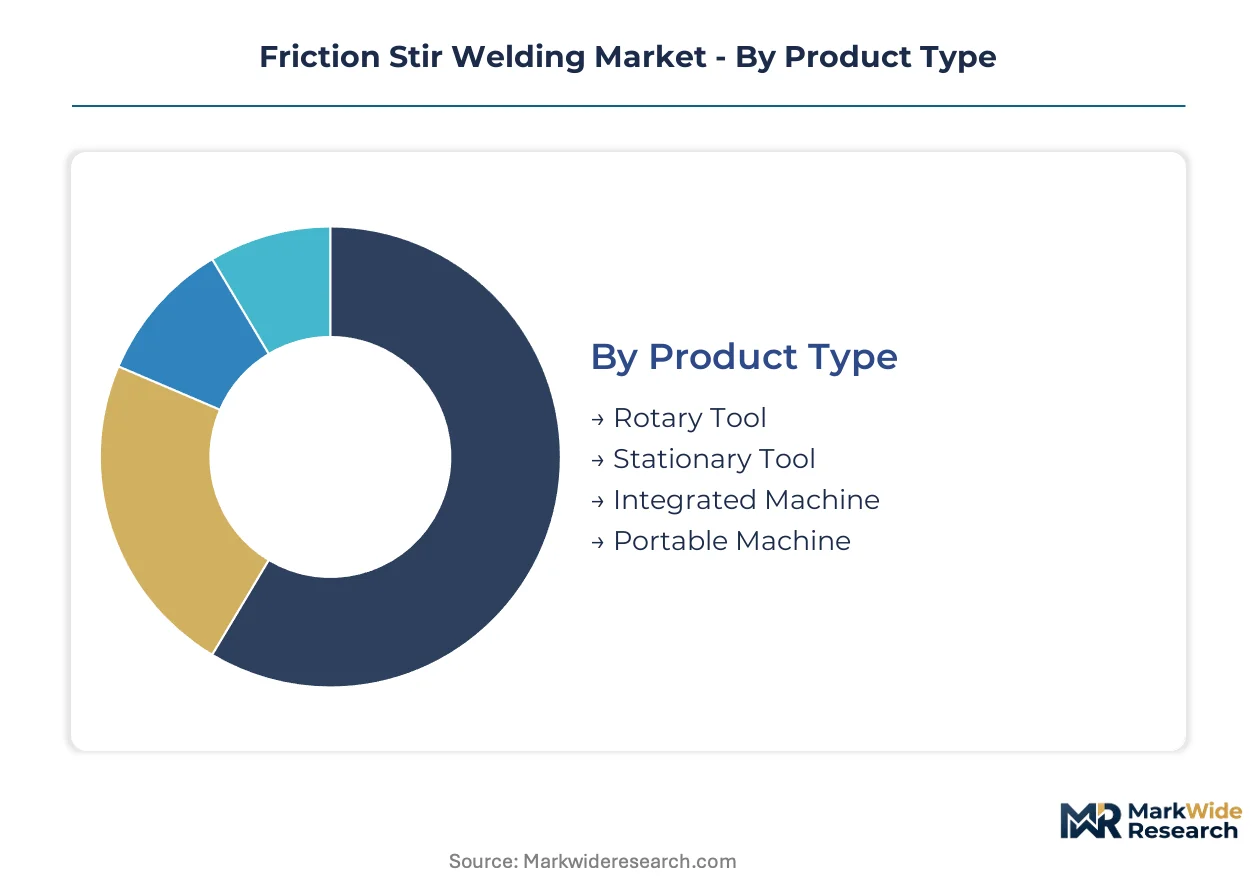
The Friction Stir Welding market is segmented to provide a granular understanding of the diverse product offerings, technological advancements, specific applications, and distinct end-user requirements. This segmentation highlights the varying demands and adoption patterns across different industrial sectors for solid-state joining solutions.
Product Type:
Buyers in the friction stir welding market differentiate their product type choices based on the required level of automation, workpiece size, and production flexibility.
- Integrated Machine:These systems combine the FSW head with multi-axis robotics or gantry structures, providing comprehensive automation for production lines. Demand concentrates in Germany's automotive industry and China's advanced manufacturing clusters, driven by the need for high throughput and repeatable quality.
- Rotary Tool:This segment comprises the fundamental non-consumable rotating pin and shoulder tool, generating frictional heat for plasticizing materials. Aircraft manufacturers and shipbuilding yards drive demand for these tools, enabling high-integrity joints in large aluminum structures.
- Stationary Tool:Stationary tools are designed for specific, fixed applications, often integrated into custom production jigs for consistent, repetitive welds.
- Portable Machine:Portable FSW machines offer on-site welding capabilities for repair or small-scale fabrication, appealing to specialized maintenance operations.
Integrated Machine leads volumes today; Portable Machine is gaining share fastest.
Technology:
Technology choices are often dictated by the specific application's material requirements, joint geometry, and surface finish expectations.
- Conventional Friction Stir:This standard FSW method uses a single rotating pin tool to create a solid-state weld below the material's melting point. Aerospace component manufacturing in the US and Europe heavily relies on this technology for joining fatigue-critical aluminum structures.
- Refill Friction Stir:Refill FSW variants employ a two-piece tool system where a moving shoulder refills the keyhole left by the pin, creating a flawless surface finish. Consumer electronics assembly in Asia, especially for aluminum casings, drives demand for this aesthetically superior process.
- Bobbin Tool:Bobbin tools feature two shoulders, allowing for simultaneous welding from both sides of the joint, improving heat distribution and reducing distortion.
- Friction Bit Welding:Friction bit welding is a specialized variant suitable for spot welding applications, offering localized joining without complex clamping.
Conventional Friction Stir technology maintains its foundational role, while Refill Friction Stir exhibits the steepest expansion trajectory.
Application:
The primary application areas for friction stir welding are distinguished by the customer's operational scale, regulatory environment, and material requirements.
- Aerospace Components:FSW is critical for joining lightweight aluminum alloys in aircraft structures, including wings, fuselages, and fuel tanks, meeting stringent FAA and EASA airworthiness directives. Aircraft manufacturers in Europe and the US prioritize FSW for its high-integrity, fatigue-resistant joints.
- Shipbuilding:This application involves welding large aluminum panels for high-speed ferries, naval vessels, and LNG carriers, benefiting from FSW's ability to create strong, distortion-free seams. European shipyards and Asian naval contractors are increasingly adopting FSW for its efficiency and quality in marine construction.
- Railroad Manufacturing:FSW facilitates the construction of lightweight aluminum train carriages and components, contributing to improved fuel efficiency and reduced operational costs.
- Consumer Electronics Assembly:FSW is used for joining aluminum casings in laptops, tablets, and smartphones, providing aesthetic appeal and structural integrity without filler materials.
Aerospace Components contribute the strongest revenue today, with Shipbuilding also showing significant growth.
End User:
End-user segments are characterized by their varying levels of FSW technology adoption and the maturity of their FSW integration into production processes.
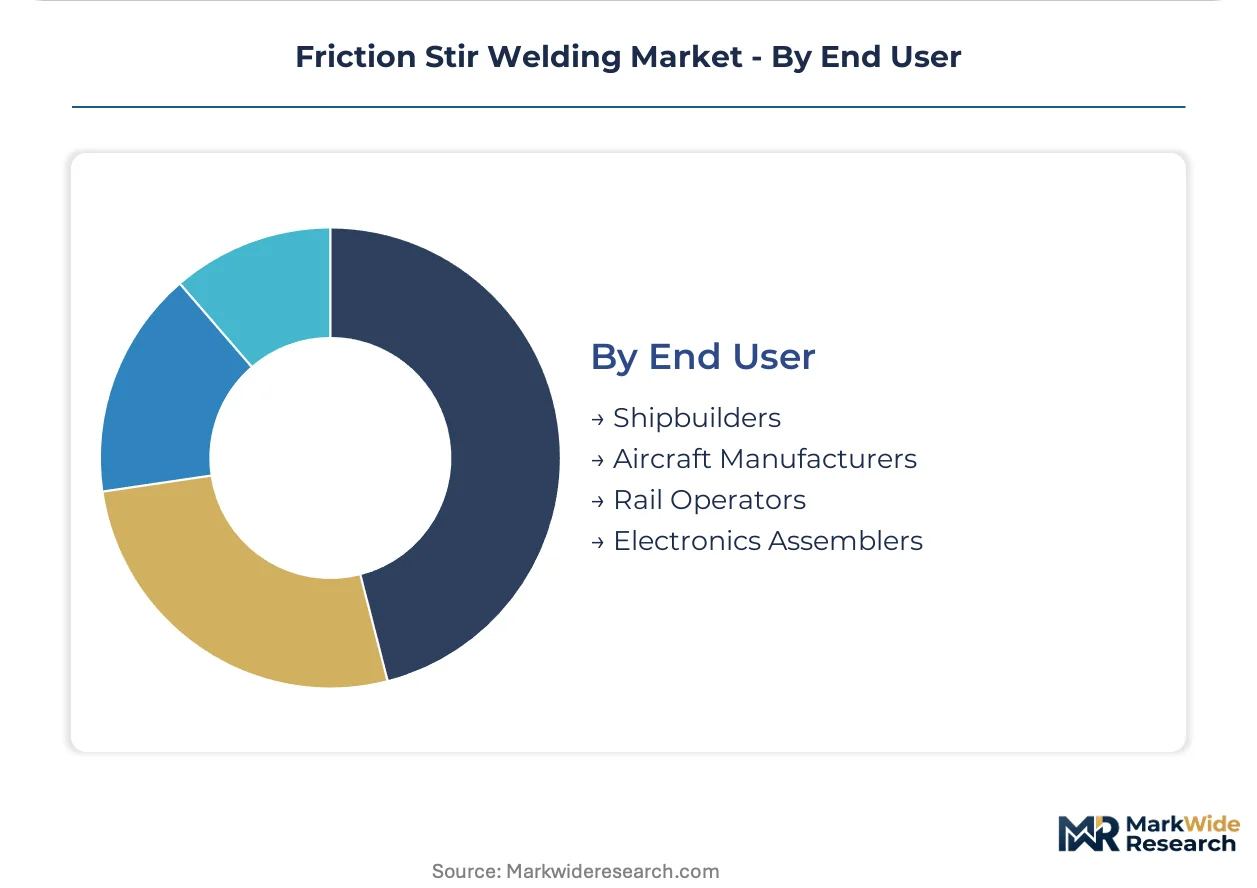
- Aircraft Manufacturers:These users demand FSW for critical structural components, driven by stringent safety regulations and the continuous push for lightweighting in commercial and military aviation. Major manufacturers in the US and France are expanding FSW lines for next-generation aircraft.
- Shipbuilders:Shipbuilders utilize FSW for constructing large aluminum superstructures and hulls, aiming for reduced weight, improved stability, and enhanced fuel efficiency in maritime vessels. European and South Korean shipyards are leading the integration of FSW for large-scale panel joining.
- Rail Operators:Rail operators benefit from FSW in the production of lighter, more energy-efficient rolling stock, enhancing passenger comfort and reducing maintenance.
- Electronics Assemblers:These users adopt FSW for high-volume production of consumer device casings, valuing the process for its clean finish and ability to join thin-gauge materials.
Aircraft Manufacturers command the highest value proposition, while Electronics Assemblers are rapidly scaling their FSW integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Friction Stir Welding market leverages specialized engineering talent concentrated in advanced manufacturing hubs. This expertise drives innovation in solid-state joining processes for critical applications. Such skilled workforces anchor regional growth across key industrial sectors.
United States
Demand for FSW in the United States stems from its robust aerospace components sector and the need for high-integrity joints. FAA airworthiness directives for fatigue-critical structures mandate reliable welding solutions. Major aircraft manufacturers in Seattle and Wichita expand FSW lines for next-generation aircraft production.
Germany
Germany's automotive industry drives significant FSW adoption, particularly for lightweighting initiatives in electric vehicle battery trays. The EU's stringent CO2 emission performance standards compel automakers to integrate advanced joining techniques. Automotive clusters in Bavaria and Baden-Württemberg lead investment in FSW systems for high-volume production.
China
China's advanced manufacturing clusters stimulate FSW demand for both electric vehicle production and general industrial applications. The MIIT promotes electric vehicle manufacturing, directly supporting FSW equipment for lightweight aluminum structures. Industrial zones in the Yangtze River Delta and Pearl River Delta rapidly scale FSW integration.
Japan
Japanese manufacturers utilize FSW for high-speed rail components and specialized automotive applications, seeking enhanced structural integrity. METI initiatives supporting advanced materials and manufacturing processes encourage FSW adoption. Industrial centers in Chubu and Kansai focus on integrating FSW for precision engineering and efficiency.
France
French aerospace companies increasingly adopt FSW for critical aircraft structures, requiring superior joint quality and reduced weight. EASA regulations for fatigue-critical components reinforce the demand for solid-state joining technologies. Toulouse, a major aerospace hub, sees expanded FSW implementation for commercial and military aircraft.
Friction Stir Welding Market Key Industry Players
The competitive structure tilts toward a blend of specialized machinery providers and broader automation solution integrators. The market exhibits a tiered structure, with established industrial giants alongside niche specialists offering tailored solutions for high-reliability applications. Strategic archetypes include comprehensive automation solution providers, custom large-format gantry system fabricators, and dedicated FSW tool developers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and address diverse application needs across aerospace and automotive sectors.
Specialists in integrated FSW systems include Grenzebach Maschinenbau GmbH, a German-based company known for large-format, customized gantry systems. PaR Systems LLC, an American firm, also occupies this segment, focusing on specific aerospace and shipbuilding needs. KUKA AG, a German automation provider, represents the broader industrial robotics archetype, leveraging its expertise to offer integrated FSW solutions for automotive production lines. These entities collectively shape the offering landscape for advanced friction stir welding.
| Leading Market Players |
|---|
| Beijing FSW Technology Co. Ltd. |
| Grenzebach Maschinenbau GmbH |
| KUKA AG |
| Yamazaki Mazak Corp. |
| PaR Systems LLC |
| The Lincoln Electric Co. |
| FOOKE GmbH |
| Hitachi High-Technologies Corporation |
| Bond Technologies, LLC. |
Cost & Logistics Intelligence
Aluminum commodity prices directly influence the cost of raw materials for friction stir welding equipment and the components it processes. This impact cascades through the supply chain, affecting pricing tiers for integrated systems and specialized tools.
Pricing Analysis
Project-based pricing dominates for large, customized integrated FSW systems, while rotary tools often follow a per-unit transactional model. Price differentiation stems from customization levels for gantry systems and the rigorous ISO 25239 certification required for aerospace applications. Pricing pressure stems from the lower capital outlay of conventional welding equipment, particularly for small-to-medium enterprises. Large aircraft manufacturers and automotive OEMs exhibit lower price sensitivity due to the critical performance gains from FSW.
Supply Chain Analysis
Specialized tool material supply primarily draws from advanced manufacturing hubs in Germany, Japan, and the United States. Key raw material dependencies include high-strength alloys for tools and precision components for robotic and gantry systems. A structural risk involves single-source vulnerability for niche tool geometries, impacting lead times and costs. Distribution for integrated FSW systems typically runs through direct sales channels from equipment manufacturers to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Friction Stir Welding market presents a clear margin-expansion story, driven by the critical need for lightweighting and high-integrity joints in aerospace and automotive. This enables premium pricing for solutions that deliver superior performance and meet stringent regulatory standards.
For Market Incumbents: Extend research and development into joining next-generation high-strength alloys and dissimilar materials to maintain technological leadership. This counters the threat from alternative joining processes like advanced laser welding and expands the addressable market. Invest in vertical integration for specialized tool production to mitigate supply chain risks and control costs. Capacity additions in key regions like Germany and China can serve growing automotive and EV battery tray production.
For New Entrants and Emerging Players: Online platforms for FSW service providers offer a viable go-to-market angle, bypassing high capital expenditure for end-users. Target underpenetrated segments such as small-scale repair operations or consumer electronics assembly, which value refill friction stir's aesthetic finish. Offer modular, cost-effective robotic FSW systems for general fabrication, reducing the barrier to entry for smaller manufacturers. Focus on developing specialized tooling for unique applications where traditional FSW faces geometric limitations.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized FSW tool developers and software firms focused on AI-powered process control. The market demonstrates long-term viability, underpinned by persistent lightweighting mandates in aerospace and electric vehicle production over the next decade. Acquisition targets should include companies with proprietary tool geometries or advanced real-time monitoring capabilities. A critical signal to watch is the accelerated adoption of FSW in shipbuilding applications for large aluminum panel joining.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Process Control | Enhances weld quality and adaptability for new materials, reducing qualification time for aerospace components. |
| Expand FSW Contract Manufacturing | Addresses high capital outlay concerns for SMEs and supports prototyping in the medical device industry. |
| Invest in Refill FSW Variants | Captures opportunities in consumer electronics assembly for flawless surface finishes on aluminum casings. |
| Geographic Expansion into China | Aligns with MIIT mandates for EV production and the rapidly scaling manufacturing clusters. |
| Vertical Integration of Tool Production | Secures critical supply of specialized tool materials and improves cost control for integrated system providers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market perspective. Primary research involved discussions with aerospace engineers, automotive production managers, FSW equipment designers, and shipyard procurement leads. Secondary validation drew from FAA airworthiness directives, ISO 25239 standards, MIIT reports, and publicly available company filings. This approach ensured robust bottom-up and top-down triangulation of market data.
Historical market data from comparable periods anchored the forecast window, providing a robust baseline for future projections. The analytical framework modeled market dynamics across product type, technology, application, end user, and regional manufacturing clusters. Compound annual growth rates were derived through a sophisticated regression analysis, integrating industry-specific forecast inputs. These inputs included global electric vehicle production targets and projected commercial aircraft build rates across the modeling period.
The model assumes a particular technology adoption path; alternative pathways for advanced laser welding or adhesive bonding would alter the outlook. Forecasts reflect documented assumptions regarding regulatory stability and raw material availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Industrial Nailers Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Pressure Washer Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Excavator Augers Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Overhead Cranes Market