
 Fitness Tracker Market | 2026-2036
Fitness Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness Tracker Market Intelligence
Manufacturing capacity in Southeast Asia, particularly Vietnam and Thailand, is shifting to accommodate higher-end smartwatch production over basic wristbands. Apple Inc. leverages its closed ecosystem to dominate the premium segment with advanced health features and clinical study partnerships. Garmin Ltd. specializes in devices for dedicated athletes and outdoor enthusiasts, building a loyal user base through superior GPS and battery life. Samsung Electronics Co. competes across multiple price points, integrating its trackers with a wide array of its own consumer electronics.
A fitness tracker is a wearable electronic device that monitors and records fitness-related metrics. These devices incorporate components like multi-axis accelerometers and optical photoplethysmography (PPG) sensors to track activity, sleep, and physiological data. The smartwatch product type captures significant value share from simpler wristbands due to expanded functionality. Within applications, personal fitness and sleep monitoring represent mature segments, while remote monitoring for seniors’ wellness is an emerging high-growth area.
Data privacy regulations like Europe's GDPR and the US HIPAA framework govern how user information is collected and managed. Concurrently, electronics compliance standards such as the FCC's rules in the United States and CE marking in the EU mandate testing for device safety and emissions. Future competitive advantage will depend on navigating the complex pathways for medical-grade device certification and software classifications.
Market Dynamics
The convergence of consumer wellness gadgets with regulated medical monitoring is the central force defining the market. This creates a fundamental tension between rapid, software-driven innovation and the slower, more rigorous validation pathways required for clinical-grade health applications.
Growth Catalysts
- Corporate Wellness Adoption:Enterprise health programs in markets like the United States subsidize devices for employees, creating a large-scale, recurring B2B sales channel independent of direct consumer purchasing cycles.
- Advanced Sensor Integration:The commercialization of non-invasive technologies, such as optical sensors for blood oxygen and pilots for glucose monitoring, unlocks new preventative health use cases and expands the user base.
- Emerging Market Affluence:A rising middle class in countries like India and China is creating new, high-volume demand for premium-tier devices with advanced features, moving beyond basic activity tracking.
Market Restraints
- Data Privacy Compliance Burden:Navigating disparate regulations like Europe's GDPR and the US HIPAA framework adds significant development cost and complexity, slowing the release of new software features.
- Battery Life Limitations:The inclusion of power-intensive components like continuous PPG sensors and GPS modules creates a persistent engineering trade-off against device size, weight, and multi-day usage expectations.
- Smartwatch Cannibalization:Feature-rich smartwatches are absorbing the functions of basic fitness wristbands, forcing manufacturers to either compete in the more complex smartwatch segment or exit the market.
Strategic Opportunities
- Geriatric Remote Monitoring:Tailoring devices with features like fall detection and passive monitoring for seniors’ wellness opens a high-growth application in partnership with home care agencies and healthcare systems.
- Medical Device Certification:Securing regulatory clearance from bodies like the FDA or the EU's MDR for features like ECG or atrial fibrillation detection allows for premium pricing and clinical integration.
- Subscription-Based Software Services:Moving beyond one-time hardware sales to offer recurring revenue services for advanced analytics, personalized coaching, or premium health reports provides a stable income stream.
Industry Challenges
- Complex Certification Pathways:The lengthy and costly process of obtaining medical-grade software classifications from national regulators like Germany's BfArM or China's NMPA creates a high barrier to entry for new competitors.
- Supply Chain Retooling:Shifting manufacturing lines in Southeast Asia from high-volume, low-margin wristbands to complex, higher-end smartwatches requires significant capital investment in new equipment and workforce training.
- Data Interoperability:A lack of universal standards for integrating fitness tracker data with diverse electronic health record (EHR) systems hinders the seamless use of this information in clinical settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness Tracker Market |
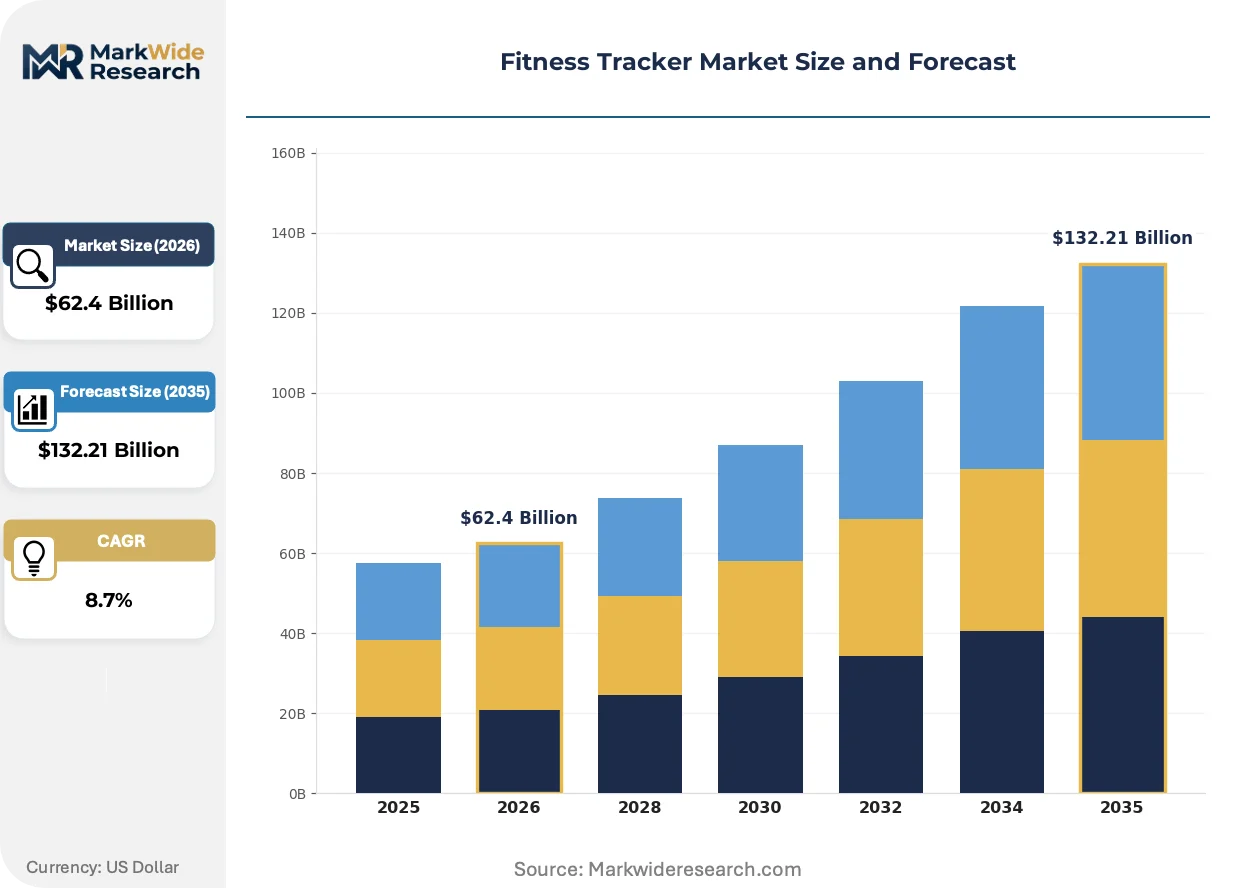
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wristband, Smartwatch, Clip-on, Chest Strap, Smart Ring Technology: Accelerometer, Gyroscope, Optical Sensor, GPS, Heart Rate Monitor, Temperature Sensor Application: Personal Fitness, Athlete Training, Weight Management, Sleep Monitoring, Seniors’ Wellness End User: Individual Consumers, Sports Clubs, Fitness Trainers, Corporate Wellness Programs, Rehabilitation Centers |
| Companies Covered | Apple Inc., Garmin Ltd., Samsung Electronics Co., Fitbit Inc., Huawei Technologies Co., Xiaomi Corporation, Fossil Group Inc., Nike Inc., Google Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness Tracker Market Strategic Shifts & Innovations
The evolution from a simple activity counter to a personalized health diagnostics hub defines the current product trajectory. This transformation is driven by fusing powerful sensors with sophisticated software algorithms to interpret physiological data.
Advanced Sensor Fusion
Multi-sensor fusion combines inputs from accelerometers, photoplethysmography, and temperature sensors to generate holistic health insights. Adoption is accelerating among health-conscious consumers and within corporate wellness programs seeking richer population data. This synthesis of multiple data streams into a single, cohesive health score is consolidating the device's role as a primary user interface for personal health management.
Software as a Medical Device Regulation
Heightened scrutiny from global regulators is reclassifying certain software features as a medical device (SaMD). This shift, visible in frameworks from the US FDA and Europe's MDR, requires manufacturers to provide clinical validation for algorithms claiming to detect conditions like sleep apnea or arrhythmias. The premium smartwatch segment is most affected, creating a clear market split between wellness gadgets and clinically validated health monitors.
Shift to B2B2C Health Channels
Consumer purchasing patterns are evolving from purely direct-to-consumer retail toward provider-led distribution. This change disrupts traditional channels as health insurers and corporate employers become key intermediaries, offering subsidized devices to members and employees. This model is most prominent in the United States, where payers use device data to manage population health and incentivize preventative behaviors.
Fitness Tracker Market Segmentation
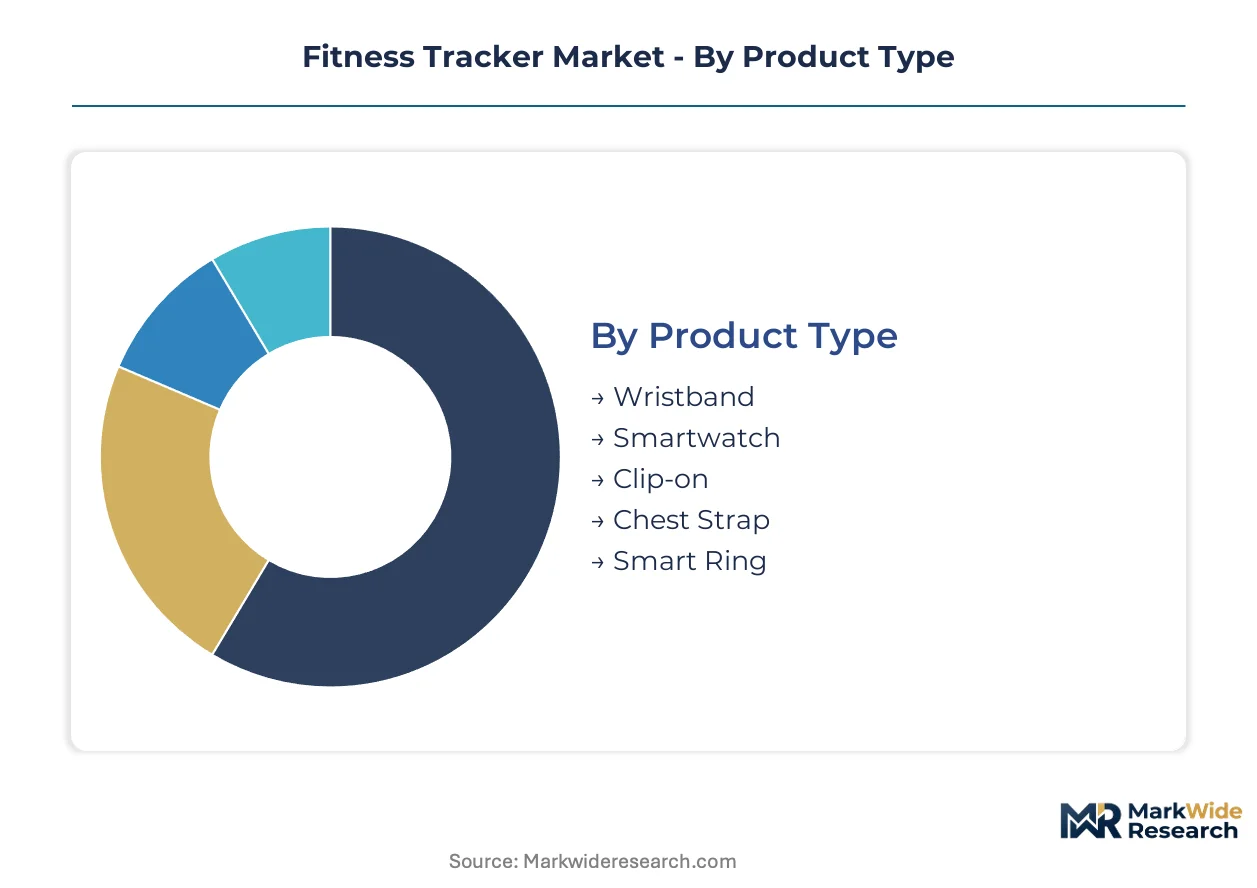
Market segmentation provides a granular view of the fitness tracker landscape, revealing how diverse product types, embedded technologies, specific applications, and distinct end-user groups contribute to the overall market structure. Understanding these divisions helps stakeholders identify key growth areas and tailor product development to meet evolving consumer and enterprise demands.
Product Type:
The product type segmentation differentiates devices based on their form factor and how deeply they integrate into daily wear versus specialized use cases.
- Smartwatch:These devices offer expanded functionality beyond basic tracking, often including communication features and app ecosystems. Smartwatches capture significant value share due to their versatility and advanced health monitoring capabilities.
- Wristband:Simpler, often more affordable devices primarily focused on activity and sleep tracking. The wristband segment faces cannibalization from feature-rich smartwatches but maintains a high volume of basic adoption.
- Clip-on:Designed for discrete wear, these trackers are often used for step counting and basic activity monitoring without being visible on the wrist.
- Chest Strap:Specialized devices providing highly accurate heart rate data, primarily favored by athletes for intense training and performance monitoring.
- Smart Ring:A nascent form factor offering discreet physiological data collection, often focusing on sleep, recovery, and basic activity metrics.
Wristband leads volumes today; Smartwatch is gaining share fastest.
Technology:
This category delineates the market by the core sensor technologies that enable data collection, reflecting advancements in physiological measurement capabilities.
Pricing differentiation within the technology segment often reflects the complexity and accuracy of the embedded sensors.
- Optical Sensor:Utilizes photoplethysmography (PPG) for non-invasive heart rate, blood oxygen, and increasingly, experimental glucose monitoring. These sensors are central to advanced health monitoring features in premium devices.
- Accelerometer:A fundamental component in all fitness trackers, measuring motion, steps, and activity levels across multiple axes. Accelerometers provide the basis for basic activity tracking and sleep pattern analysis.
- Gyroscope:Works in conjunction with accelerometers to provide more precise motion sensing, enhancing accuracy for specific activities and posture analysis.
- GPS:Integrated for precise location tracking, essential for outdoor activities like running, cycling, and hiking to measure distance and speed.
- Heart Rate Monitor:Dedicated sensors, often optical or electrical, for continuous or on-demand heart rate measurement, crucial for exercise intensity and cardiovascular health.
- Temperature Sensor:Emerging in newer devices to track body temperature fluctuations, supporting insights into sleep quality, illness, and female reproductive health.
Accelerometer technology maintains the largest installed base; Optical Sensor technology is experiencing the steepest expansion trajectory.
Application:
The application segment illustrates the diverse use cases for fitness trackers, ranging from general wellness to specialized health management.
Demand for specific applications varies significantly by consumer demographic and health objectives.
- Personal Fitness:The broadest application, encompassing general activity tracking, calorie counting, and motivation for a healthy lifestyle among individual consumers.
- Seniors’ Wellness:An emerging high-growth area focusing on features like fall detection, passive monitoring, and remote health insights for older adults. This application often involves integration with healthcare systems.
- Athlete Training:Tailored for dedicated athletes, this application focuses on performance metrics, recovery tracking, and advanced physiological data for optimizing sports performance.
- Weight Management:Involves tracking calorie intake and expenditure, often integrating with diet apps to support weight loss or gain goals.
- Sleep Monitoring:Utilizes sensors to analyze sleep stages, duration, and quality, providing insights into rest patterns and potential sleep disorders.
Personal Fitness drives the majority of current device usage; Seniors’ Wellness is expanding most quickly.
End User:
This segmentation highlights the different consumer and institutional groups adopting fitness trackers, influencing distribution channels and product features.
Customer type influences both device procurement models and the specific features prioritized in product design.
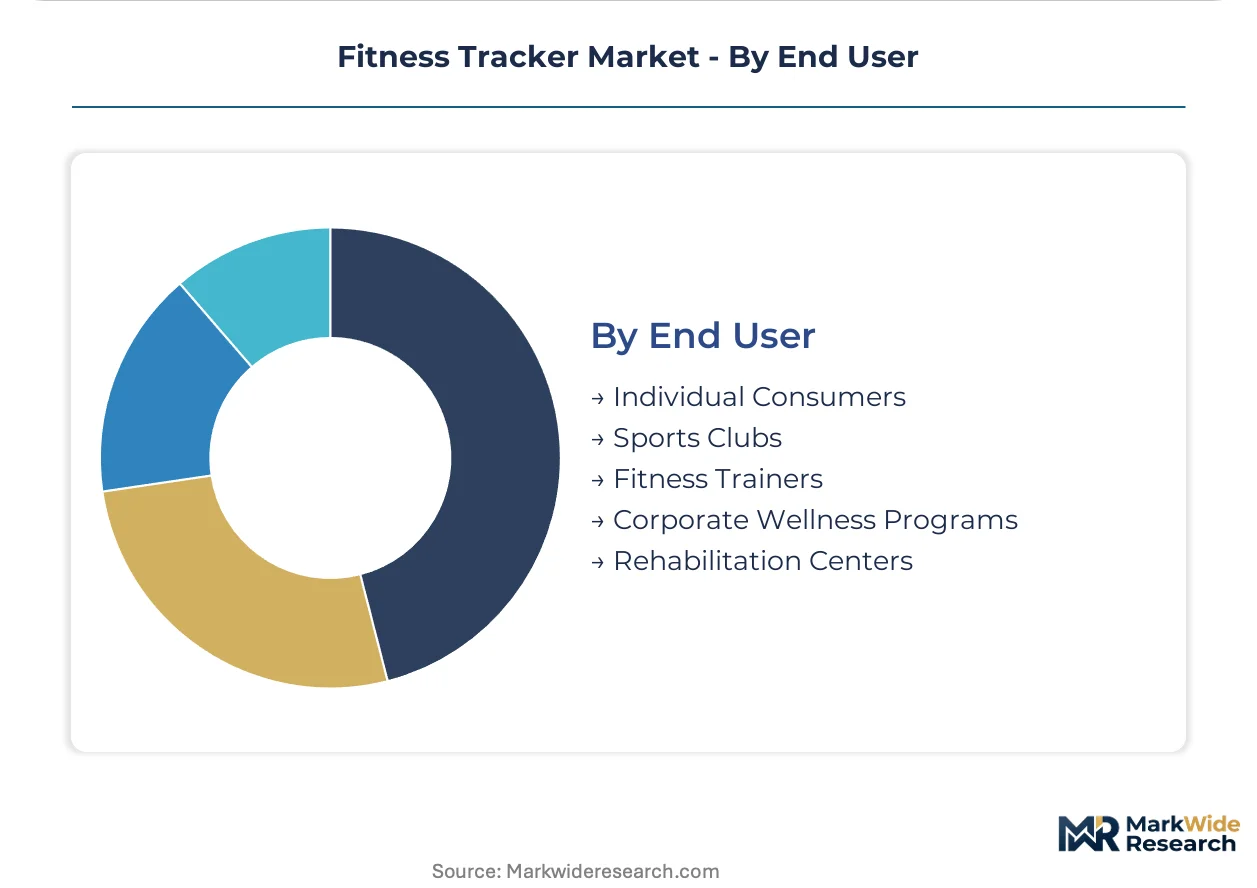
- Individual Consumers:The largest end-user group, purchasing devices for personal health, fitness, and wellness management.
- Corporate Wellness Programs:Enterprises subsidize or provide trackers to employees as part of health initiatives, aiming to improve workforce health and reduce healthcare costs.
- Sports Clubs:Utilize trackers for members to monitor performance, track progress, and offer personalized coaching within a structured environment.
- Fitness Trainers:Employ devices to track client progress, monitor workout intensity, and provide data-driven coaching and accountability.
- Rehabilitation Centers:Integrate trackers into patient recovery plans to monitor activity levels, sleep patterns, and adherence to physical therapy regimens.
Individual Consumers represent the largest purchasing segment; Corporate Wellness Programs are demonstrating significant market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regulatory landscape for fitness trackers creates a geographic arbitrage, where manufacturing capacity shifts to regions with lower compliance costs, while high-value medical-grade device development concentrates in stricter regulatory environments. This dynamic influences both production locations and market penetration strategies across different countries.
United States
Corporate wellness programs and individual consumer health consciousness drive demand for advanced fitness trackers across the United States. The HIPAA framework mandates strict data privacy, influencing how user health information is managed and secured by device manufacturers. Silicon Valley remains a hub for sensor innovation and software development, with companies frequently engaging with the FDA for medical device certifications.
China
A rapidly expanding affluent consumer base in China fuels demand for premium fitness trackers with advanced features. The NMPA's stringent regulations for medical devices impact the classification and market entry of health-monitoring wearables. Major technology companies in Shenzhen and Beijing are investing heavily in domestic R&D to meet local demand and navigate complex compliance pathways.
Germany
Strong consumer demand for health and wellness devices, alongside robust corporate health initiatives, characterizes the German market. CE marking and Europe's MDR framework govern device safety and clinical validation, setting high standards for manufacturers. Munich and Berlin are emerging centers for health tech innovation, attracting startups focused on clinically validated wearable solutions.
India
Rising disposable incomes and government initiatives promoting digital health are increasing the adoption of fitness trackers in India. The BIS (Bureau of Indian Standards) sets product quality and safety standards, impacting device imports and local manufacturing. Bengaluru's tech ecosystem supports software development for health applications, integrating trackers with local wellness platforms.
Vietnam
Manufacturing capacity in Vietnam is increasingly accommodating higher-end smartwatch production, driven by competitive labor costs and established supply chains. The Ministry of Health regulates medical devices, influencing the types of health features that can be produced or sold within the country. Industrial zones around Hanoi and Ho Chi Minh City are attracting significant foreign investment for electronics assembly and component manufacturing.
Fitness Tracker Market Key Industry Players
United States producers anchor one tier, focusing on premium devices and software ecosystems, while East Asian specialists hold significant market share in high-volume manufacturing and multi-price point strategies. The market exhibits a tiered structure, with distinct segments for premium, mid-range, and basic offerings. Device manufacturers are increasingly engaging in strategic partnerships to integrate health data and pursuing portfolio diversification to address various end-user needs.
On the premium-tier vector, Apple Inc. and Garmin Ltd. exemplify companies leveraging brand loyalty and specialized features to command higher price points. Apple Inc. anchors the high-end consumer segment with its integrated ecosystem and advanced health features. Garmin Ltd. represents the specialized athlete market, building a loyal user base through superior GPS and battery life. Samsung Electronics Co. occupies a position across multiple price points, integrating its trackers with its broad consumer electronics portfolio.
| Leading Market Players |
|---|
| Apple Inc. |
| Garmin Ltd. |
| Samsung Electronics Co. |
| Fitbit Inc. |
| Huawei Technologies Co. |
| Xiaomi Corporation |
| Fossil Group Inc. |
| Nike Inc. |
| Google Inc. |
| Others |
Cost & Logistics Intelligence
Corporate wellness program adoption, particularly in the United States, creates a consistent B2B demand, which influences manufacturers to prioritize stable, high-volume supply contracts and tiered pricing models for enterprise clients.
Pricing Analysis
Retailer markups significantly influence consumer-facing prices for fitness trackers. The dominant pricing model is transactional, with premium-mid-economy pricing differentiation based on feature sets and brand perception. Pricing softness reflects intense competition in the basic wristband segment from smartwatches. Individual consumers represent the most price-sensitive segment, while corporate wellness programs demonstrate lower price sensitivity due to subsidized device costs.
Supply Chain Analysis
Critical sensor components, such as optical PPG sensors and multi-axis accelerometers, draw heavily from specialized electronics manufacturers. Geographic supply concentration for these components centers on China, South Korea, and Taiwan. Raw material dependencies include rare earth metals for sensors and advanced polymers for device casings. Single-source vulnerability for specific high-performance sensors poses a structural supply chain risk. Distribution runs through both direct-to-consumer online channels and established consumer electronics retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fitness tracker market presents a geographic arbitrage opportunity, as lower manufacturing costs in Vietnam contrast with higher regulatory compliance expenses in the United States for medical-grade devices.
For Market Incumbents: Anticipate further consolidation within the premium smartwatch segment through strategic acquisitions of specialized software firms. Leverage existing clinical study partnerships to achieve medical device certifications from bodies like the US FDA or Europe's MDR. This defends market share against emerging health-focused startups and reinforces brand trust among healthcare professionals. Invest in advanced sensor R&D to maintain technological leadership against evolving competitive threats.
For New Entrants and Emerging Players: A significant price-point gap exists between basic wristbands and advanced smartwatches, offering an entry point. Target the seniors’ wellness application with tailored devices offering fall detection and passive monitoring. This segment is under-penetrated and offers partnership opportunities with home care agencies. A subscription-based software service model provides a stable revenue stream and a clear go-to-market angle for specialized health insights.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software developers and sensor technology firms possessing unique intellectual property. Long-term viability favors entities capable of navigating complex medical device certification pathways. An acquisition target archetype includes mid-cap companies with clinically validated algorithms for specific health conditions. The signal to watch is the increasing integration of fitness tracker data into electronic health record (EHR) systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Medical Device Certification (e.g., FDA, MDR) | Regulatory clearance from bodies like the US FDA enables premium pricing and clinical integration for advanced health features. |
| Expand Subscription-Based Software Services | Moving beyond hardware sales to recurring revenue services for analytics creates stable income streams and enhances customer loyalty. |
| Invest in Advanced Non-Invasive Sensor R&D | Commercialization of technologies like non-invasive glucose monitoring unlocks new preventative health use cases and expands the user base. |
| Form B2B2C Partnerships with Healthcare Systems | Provider-led distribution through health insurers and corporate employers offers subsidized devices and manages population health. |
| Optimize Manufacturing Footprint in Southeast Asia | Shifting production lines to regions like Vietnam or Thailand accommodates higher-end smartwatch demand while managing cost structures. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. Primary research involved in-depth interviews with device manufacturers, healthcare system administrators, corporate wellness program managers, and sensor technology developers. Secondary validation drew from industry association reports, government regulatory filings, and academic research papers. The analysis employed both bottom-up market sizing and top-down market validation.
Granular modeling segmented the market by product type, technology, application, and end-user. The analytical framework incorporated historical data trends and projected future market trajectories across the modeling period. Compound annual growth rates were derived from a sophisticated statistical model considering market dynamics and technological advancements. Key industry-specific forecast inputs included sensor commercialization timelines and regulatory approval rates for new health features.
Caveats apply where rapid sensor innovation or evolving medical device regulations could materially shift the outlook. Forecasts reflect assumptions regarding technological adoption rates and consumer purchasing behavior. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
North America Wearable Sensors Market