
 Wearable Fitness Technology Market | 2026-2036
Wearable Fitness Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Fitness Technology Market Outlook
A capital-intensity divergence between in-house semiconductor fabrication and outsourced component assembly is rotating competitive advantage toward vertically integrated players. Apple Inc. leverages custom silicon design to sustain hardware-software margins that competitors struggle to match. Samsung Electronics anchors display and memory supply chains internally, while Garmin Ltd. specializes in GPS-dominant outdoor segments where precision engineering commands pricing power.
Wearable fitness technology encompasses body-worn electronic devices integrating biosensors, microprocessors, and wireless transceivers to capture physiological metrics in real time, typically operating at 2.4 GHz Bluetooth frequencies with accelerometer sampling rates exceeding 100 Hz for motion fidelity. Smartwatches lead product-type revenue pools due to multipurpose utility spanning payments and notifications, while smart clothing represents the fastest-growing segment as conductive fiber integration matures. Fitness enthusiasts dominate end-user volume, though clinical patients generate superior per-unit margins through reimbursable remote monitoring applications.
FDA 510(k) clearance requirements constrain medical-adjacent feature claims in the United States, while EU MDR and CE marking obligations extend compliance burdens for European market access. ISO 13485 quality management standards increasingly serve as de facto procurement prerequisites for enterprise wellness contracts. Stakeholders must monitor regulatory reclassification risks as blood glucose and blood pressure monitoring capabilities blur the consumer-medical device boundary.
Market Dynamics
The wearable fitness technology market is experiencing a structural compression between consumer-grade feature expansion and medical-grade regulatory capture, as biosensor capabilities advance faster than FDA 510(k) clearance frameworks can accommodate.
Growth Catalysts
- Employer wellness procurement:North American corporations are mandating wearable enrollment for health insurance premium reductions, creating institutional demand pools that individual consumer marketing cannot replicate.
- FDA breakthrough device designation:Expedited review pathways for continuous glucose monitoring and blood pressure wearables are accelerating clinical validation timelines for manufacturers pursuing reimbursable indications.
- Conductive textile manufacturing:Smart clothing production lines in China and Vietnam are achieving cost parity with traditional athletic apparel, eliminating the historic price barrier to fabric-integrated sensors.
Market Restraints
- Semiconductor foundry concentration:Advanced biosensor ASIC fabrication depends on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity, creating single-source vulnerability for specialized motion and optical sensing chips.
- EU MDR compliance burden:Medical-adjacent feature claims in European markets now require notified body intervention and clinical evidence dossiers that add 18-24 months to product launch schedules.
- Lithium-polymer cell volatility:Battery energy density requirements for multi-day wearables expose manufacturers to cobalt and lithium carbonate price swings that compress hardware margins unpredictably.
Strategic Opportunities
- Remote patient monitoring reimbursement:United States Medicare CPT codes 99453-99458 now cover wearable-derived physiological data review, opening B2B2C channels through health systems and accountable care organizations.
- India PLI scheme for electronics:Production-linked incentives for wearable manufacturing are attracting component suppliers to set up assembly operations serving domestic price-sensitive demand and export markets.
- AI inference at the edge:On-device machine learning for arrhythmia detection and fall prediction is converging with ultra-low-power neural accelerators from ARM and Qualcomm, enabling real-time clinical alerts without cloud dependency.
Industry Challenges
- Biomedical algorithm validation:FDA insists on prospective clinical trials for diagnostic features, forcing engineering teams to recruit thousands of participants and sustain multi-year regulatory burn rates.
- Interoperability fragmentation:Health data exchange between proprietary wearable platforms and electronic health record systems requires expensive HL7 FHIR integration work that delays enterprise contract closures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Fitness Technology Market |
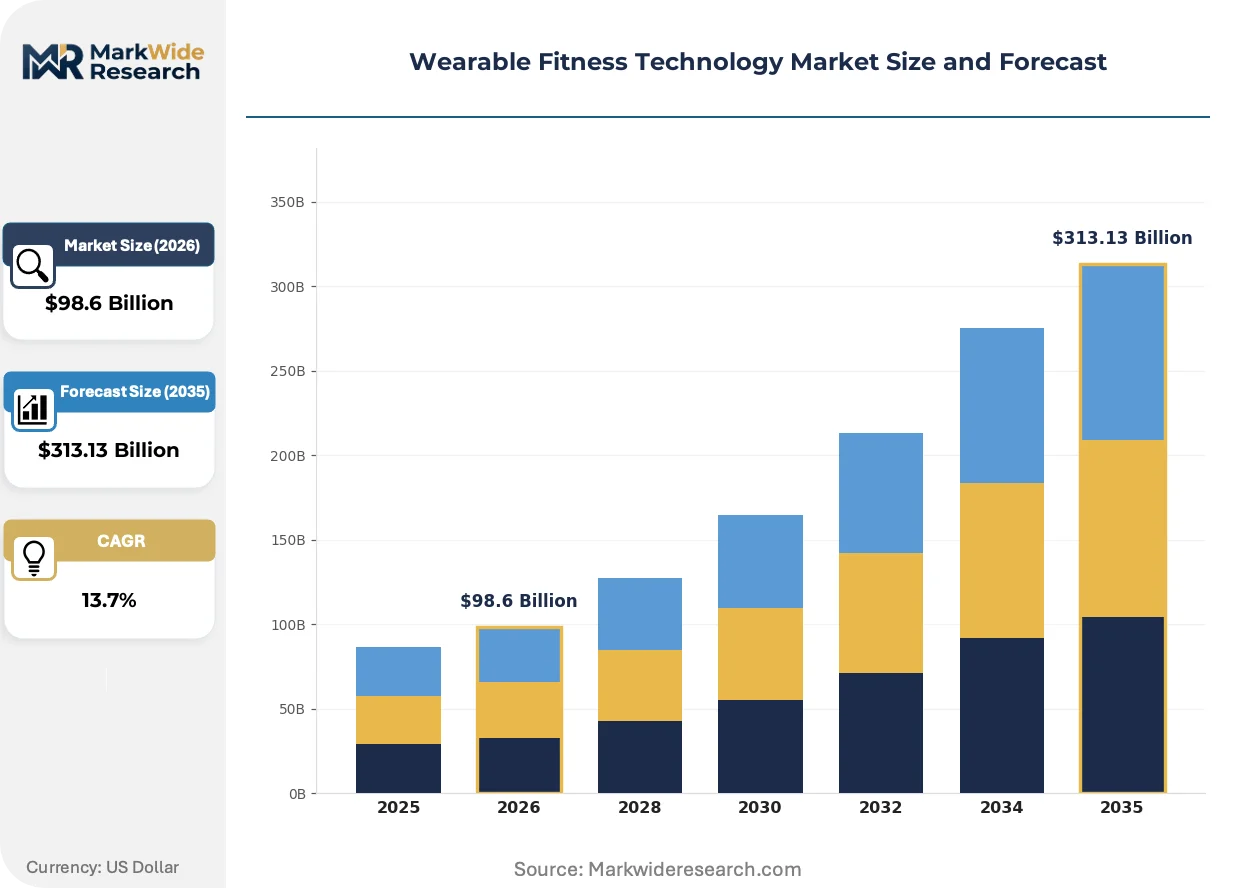
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $313.13 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Clothing, Heart Rate Monitors Technology: Bluetooth, Wi-Fi, NFC, GPS End User: Fitness Enthusiasts, Health-Conscious Consumers, Professional Athletes, Clinical Patients Application: Heart Rate Monitoring, Activity Tracking, Sleep Analysis, Calorie Tracking |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Fitbit, Huawei Technologies, Xiaomi Corporation, Whoop, Polar Electro, Amazfit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Fitness Technology Market Strategic Shifts
Sensor miniaturization and algorithmic sophistication are collapsing the functional boundary between lifestyle accessories and clinical monitoring devices, forcing manufacturers to choose positioning strategies before regulatory reclassification renders hybrid models nonviable.
Photoplethysmography with multi-wavelength LED arrays is decomposing the market for standalone pulse oximeters and single-lead ECG devices. Fitness enthusiasts and early-stage cardiac patients now access continuous SpO2 and atrial fibrillation detection through wrist-worn form factors that cost one-tenth of hospital-grade alternatives. This convergence is compressing addressable markets for dedicated medical device manufacturers while expanding reimbursable remote monitoring categories.
FDA's 2023 guidance on software as a medical device is tightening predicate device pathways for algorithm-based diagnostics, requiring manufacturers to submit locked algorithm versions rather than continuous learning models. The industrial consequence is a freeze in over-the-air update capabilities for cleared features, forcing firms to choose between clinical validation rigor and consumer software agility. Blood pressure estimation algorithms face the strictest scrutiny, with Omron and Samsung pursuing separate 510(k) pathways that establish divergent evidentiary standards.
Enterprise procurement departments are consolidating wearable vendor relationships from fragmented wellness stipend programs to single-source national contracts. Self-insured employers in the United States are replacing individual device subsidies with biometric data licensing agreements that aggregate employee health feeds for predictive risk modeling. This shift concentrates purchasing power among three to five large carriers, compressing vendor margins and privileging platforms with established HIPAA business associate agreements and SOC 2 Type II certifications.
Wearable Fitness Technology Market Segmentation
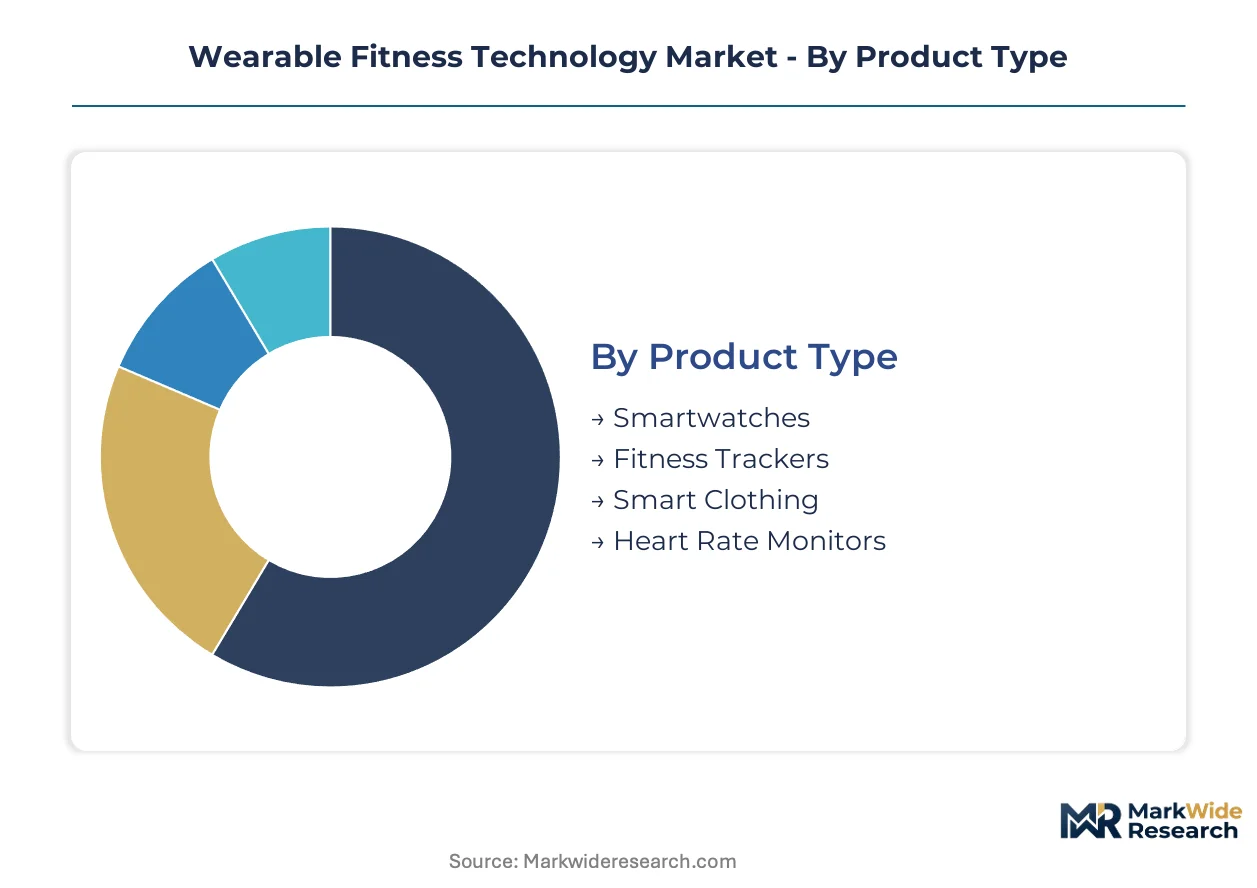
Wearable fitness technology segmentation reveals how margin pools concentrate in multipurpose form factors and reimbursable clinical applications. Manufacturers optimize portfolio mix across these dimensions to capture hardware-software recurring revenue versus one-time device sales.
Product Type:
Smartwatches command the highest per-unit margins through ecosystem lock-in and payment integration, while smart clothing offers the steepest margin expansion trajectory as conductive fiber costs decline.
- Smartwatches:Multipurpose wrist-worn computers integrating AMOLED displays, optical heart rate sensors, and NFC payment chips at 2.4 GHz Bluetooth frequencies. Demand concentrates among United States urban professionals seeking notification consolidation and contactless transactions, with Apple and Samsung capturing premium positioning through custom silicon design.
- Smart Clothing:Conductive fiber-integrated athletic apparel embedding textile electrodes and stretch sensors for biomechanical measurement. European performance sports teams and rehabilitation clinics in Germany are driving adoption as fabric-integrated ECG achieves medical-grade signal fidelity without wrist-worn constriction.
- Fitness Trackers:Dedicated activity bands with accelerometer sampling above 100 Hz and 7-day battery life, targeting price-sensitive Asian markets through Xiaomi and Huawei distribution.
- Heart Rate Monitors:Chest-worn electrode belts and optical arm bands delivering laboratory-accurate pulse measurement for triathletes and cardiac rehabilitation programs.
The dominant share belongs to Smartwatches, while Smart Clothing is closing the gap fastest.
Technology:
Wireless protocol selection determines power budget allocation and use-case enablement across indoor fitness, outdoor navigation, and contactless payment scenarios.
- Bluetooth:Dominant 2.4 GHz protocol for smartphone pairing and audio streaming, with BLE 5.3 enabling multi-year coin-cell operation in ring and patch form factors. United States gym chains mandate Bluetooth compatibility for equipment-integrated workout tracking.
- GPS:Multi-constellation satellite positioning (GPS, GLONASS, Galileo) for pace and distance calculation without smartphone tethering. Garmin dominates outdoor recreation demand in Colorado trail systems and Swiss alpine tourism through dual-frequency L1/L5 reception.
- Wi-Fi:High-bandwidth connectivity for music streaming and firmware updates in premium smartwatches, consuming 3-5x the power budget of Bluetooth alternatives.
- NFC:Secure element integration for transit and payment authentication, with Visa and Mastercard certification requirements adding 6-9 months to product development cycles.
Bluetooth anchors volume deployment, though GPS-equipped devices generate superior average selling prices in outdoor segments.
End User:
Customer archetype segmentation separates lifestyle purchasers from clinical populations with reimbursable monitoring needs and distinct regulatory pathways.
- Fitness Enthusiasts:Recreational athletes tracking workout intensity, recovery metrics, and training load through third-party apps like Strava and TrainingPeaks. This segment drives 70%+ of unit volume through Amazon and direct-to-consumer channels.
- Clinical Patients:Cardiac, diabetic, and hypertensive populations prescribed wearable monitoring for remote physiological surveillance. United States Medicare CPT reimbursement codes 99453-99458 now cover physician review of wearable-derived data, creating institutional procurement channels through health systems.
- Health-Conscious Consumers:Wellness-focused individuals monitoring sleep stages, stress indicators, and activity trends without specific athletic or medical objectives.
- Professional Athletes:Olympic and professional team members requiring HRV-guided load management and GPS-tracked positional analytics for tactical analysis.
Clinical Patients deliver the highest per-unit lifetime value through recurring data review fees, while Fitness Enthusiasts dominate absolute shipment volumes.
Application:
Functional use-case segmentation aligns sensor configuration with specific physiological measurement requirements and algorithm validation standards.
- Heart Rate Monitoring:Photoplethysmography and electrode-based pulse detection for training zone management and arrhythmia screening. FDA 510(k) clearance for atrial fibrillation detection has concentrated clinical-grade offerings from Apple and AliveCor in United States cardiology practices.
- Sleep Analysis:Multi-sensor fusion of accelerometer, optical heart rate, and SpO2 for sleep stage classification and apnea screening. ResMed and Withings pursue separate regulatory pathways for medical sleep disorder diagnosis versus consumer wellness positioning.
- Activity Tracking:Step counting, distance estimation, and active calorie burn through accelerometer and gyroscope fusion, forming the baseline feature set across all price tiers.
- Calorie Tracking:Metabolic estimation combining heart rate variability, accelerometer-derived movement intensity, and user-reported nutritional intake through app integration.
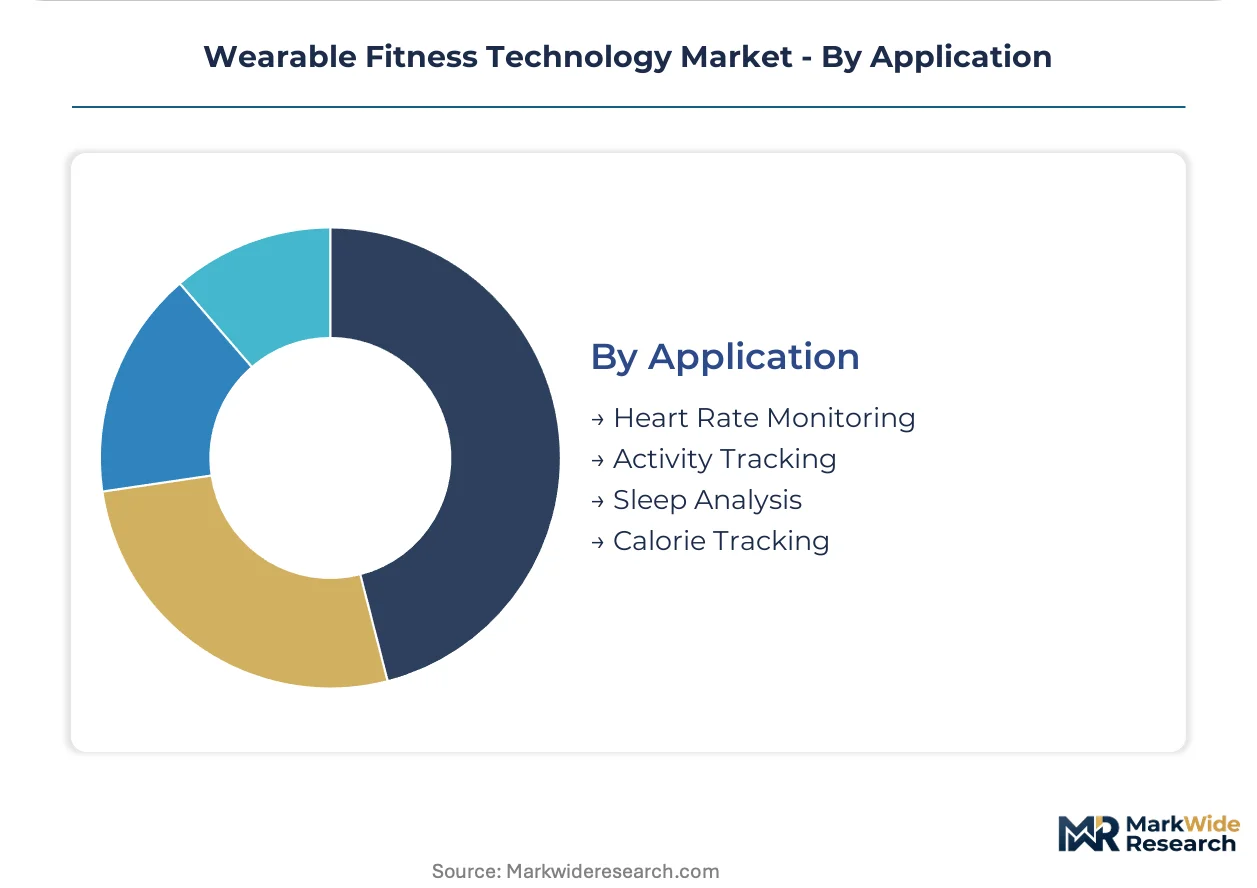
Heart Rate Monitoring captures the largest addressable market across consumer and clinical domains, with Sleep Analysis expanding most quickly as apnea screening gains reimbursement coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium device pricing in the United States commands triple the hardware margins achievable in Chinese domestic markets, creating a trans-Pacific profit asymmetry that shapes manufacturer portfolio allocation.
United States
Self-insured employers in Minnesota and Texas are mandating wearable enrollment for health insurance premium reductions, generating institutional demand pools. FDA 510(k) clearance requirements constrain medical-adjacent feature claims, tightening quality benchmarks for blood glucose monitoring capabilities. The Boston-Cambridge corridor concentrates algorithm development talent for arrhythmia detection and fall prediction software.
China
Domestic brands leverage Shenzhen manufacturing clusters to achieve cost parity with traditional athletic apparel in smart clothing segments. NMPA regulatory pathways for medical-grade wearables are tightening quality benchmarks as blood pressure monitoring capabilities advance. The Yangtze River Delta anchors conductive fiber production lines serving both domestic price-sensitive demand and export markets.
Germany
EU MDR compliance obligations extend clinical evidence requirements for European market access, adding months to product launch schedules. Performance sports teams and rehabilitation clinics in Bavaria drive adoption of fabric-integrated ECG achieving medical-grade signal fidelity. The Munich-Stuttgart industrial corridor hosts precision engineering specialists commanding pricing power in GPS-dominant outdoor segments.
India
Production-linked incentives for wearable manufacturing are attracting component suppliers to set up assembly operations serving domestic demand. BIS quality standards increasingly serve as procurement prerequisites for enterprise wellness contracts. The Karnataka-Telangana electronics corridor concentrates final assembly capacity for fitness trackers targeting price-sensitive Asian markets.
Japan
METI industrial policy supports ultra-low-power neural accelerator integration for on-device machine learning applications. PMDA regulatory scrutiny of software as a medical device is tightening predicate pathways for algorithm-based diagnostics. The Tokyo-Osaka technology corridor concentrates photoplethysmography sensor miniaturization expertise for multi-wavelength LED arrays.
Wearable Fitness Technology Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure where custom silicon designers capture premium margins while assembly specialists dominate volume shipments. The market exhibits tiered concentration: ecosystem-integrated technology conglomerates control high-end multipurpose devices, specialized outdoor engineering firms anchor precision GPS segments, and component-integrated electronics assemblers serve price-tiered emerging markets. Three strategic archetypes define positioning: vertically integrated platform owners, precision sensor specialists, and scale-driven hardware commoditizers. Competitive moves concentrate on M&A for algorithm talent acquisition and strategic partnerships for health system data integration.
Among ecosystem-integrated technology conglomerates, Apple Inc. and Samsung Electronics occupy positions defined by captive silicon design and display supply chain control. Garmin Ltd. exemplifies the precision sensor specialist archetype through GPS-dominant outdoor positioning. These three anchors illustrate how hardware-software margin sustainability depends on architectural control over core components rather than assembly scale alone.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Fitbit |
| Huawei Technologies |
| Xiaomi Corporation |
| Whoop |
| Polar Electro |
| Amazfit |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwan Semiconductor Manufacturing and Samsung Foundry lock in both advanced biosensor ASIC supply and cost visibility for wearable OEMs pursuing FDA 510(k) clearance pathways. These arrangements insulate premium smartwatch manufacturers from spot-market volatility in 7nm and 5nm foundry capacity while forcing price discipline on mid-tier fitness tracker assemblers excluded from allocation priority.
Pricing Analysis
The customization-premium spread separates configured-to-order medical-grade wearables from standard consumer devices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification status and ISO 13485 quality management adherence. Price differentiation stems from clinical validation burden and brand ecosystem lock-in. Cost compression in the economy tier intensifies because Xiaomi and Huawei drive component standardization in Asian markets. Fitness enthusiasts exhibit highest price sensitivity through Amazon channel comparison shopping, while clinical patients accept premium positioning for reimbursable remote monitoring indications.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy for lithium-polymer cells and cobalt-dependent cathode materials given commodity price volatility. Manufacturing concentrates in China, Vietnam, and Taiwan, with Shenzhen clusters handling final assembly and Yangtze River Delta anchoring conductive fiber production. Raw material dependencies include rare earth magnets for haptic motors, gallium arsenide for photoplethysmography LEDs, and lithium carbonate for energy-dense batteries. Single-source vulnerability pervades advanced biosensor ASIC fabrication. Distribution runs through enterprise wellness procurement departments consolidating vendor relationships and direct-to-consumer channels for fitness enthusiast volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable fitness technology is approaching a platform-economics inflection where interoperability standards and health data liquidity determine competitive survival. HL7 FHIR integration capabilities and HIPAA business associate agreements now separate viable ecosystem players from stranded hardware vendors.
For Market Incumbents: Shield ecosystem margins by accelerating FDA 510(k) clearances for blood pressure and glucose monitoring features before regulatory reclassification tightens predicate pathways. Deepen backward integration into custom silicon design to deny competitors cost parity in neural accelerator integration. Prioritize SOC 2 Type II certification investments to defend enterprise wellness contract concentration against emerging cloud-native entrants.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable regulatory pathway for algorithm-based diagnostics targeting cardiac arrhythmia detection. Target India's PLI scheme manufacturing incentives to achieve cost structures competitive with Shenzhen incumbents in fitness tracker segments. Pursue B2B2C go-to-market angles through accountable care organizations seeking reimbursable remote patient monitoring CPT code coverage.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform owners with captive silicon design and established health system data integration pipelines. Long-term viability favors manufacturers bridging consumer hardware agility with clinical validation rigor across the analysis window. Algorithm talent acquisition in the Boston-Cambridge corridor signals inflection when portfolio companies achieve FDA 510(k) clearances for multi-wavelength photoplethysmography diagnostics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks Medicare CPT reimbursement codes 99453-99458 for physician data review revenue streams. |
| Custom Silicon Design Investment | Captures hardware-software margins that outsourced ASIC competitors cannot replicate at scale. |
| Health System Partnership | Secures HIPAA business associate agreements required for enterprise wellness contract consolidation. |
| Conductive Textile Manufacturing Scale-Up | Achieves cost parity with traditional athletic apparel as China and Vietnam production lines mature. |
| AI Edge Inference Integration | Enables real-time arrhythmia alerts without cloud dependency using ARM and Qualcomm neural accelerators. |
Study Parameters
The analysis maps smartwatch, smart clothing, fitness tracker, and heart rate monitor sub-sectors, each validated through interviews with wearable engineering directors, FDA regulatory affairs consultants, hospital GPO contracts managers, and enterprise wellness procurement officers. Primary fieldwork combined with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, and SEC 10-K hardware margin disclosures established baseline metrics. Bottom-up shipment estimates triangulated against top-down addressable market sizing across product type, technology protocol, end user archetype, and application segmentation.
Consistency checks validated volume and value outputs against hyperscaler wearable partnership announcements, foundry capacity utilization reports, and health system remote monitoring procurement databases. The analytical framework modeled product form factor, wireless protocol selection, end user clinical versus lifestyle positioning, and reimbursable application status across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic healthcare expenditure trends and semiconductor foundry capex cycles. Forecast inputs incorporated employer wellness mandate penetration rates and FDA software as medical device guidance evolution.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) review timelines and continued Medicare CPT code coverage for wearable-derived data; material deviation in regulatory reclassification velocity or reimbursement policy would warrant model refresh. Revision becomes warranted when EU MDR notified body capacity constraints or Taiwan semiconductor supply disruptions cross thresholds affecting product launch schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Smart Fitness Watches Market