
 Thermal Comfort Wearables Market | 2026-2036
Thermal Comfort Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Comfort Wearables Market Insights
Aftermarket battery replacement and component refurbishment is fragmenting as third-party suppliers erode OEM service margins. Columbia Sportswear Company leverages its apparel supply chain to control heated jacket distribution through outdoor retail channels. Milwaukee Tool anchors the professional trades segment with battery-compatible heated workwear integrated into its power tool ecosystem. Makita Corporation competes on similar logic, extending its lithium-ion platform into thermal gloves and vests for construction users.
Thermal comfort wearables comprise garments and accessories engineered with embedded heating or cooling elements, phase change materials, or thermoelectric modules to maintain stable microclimates against skin surfaces, typically operating between 10°C and 50°C depending on application. Their primary commercial purpose centers on preventing cold stress and heat exhaustion in occupational settings while enhancing athletic endurance and recreational comfort. Heated jackets lead product type revenue due to universal applicability across climates and user groups, while smart fabrics represent the fastest-expanding technology segment as textile-integrated sensors enable real-time temperature modulation. Cooling vests command premium pricing in military and emergency services applications where physiological monitoring intersects with operational safety requirements.
FDA oversight applies to wearables making therapeutic claims, while OSHA mandates govern employer-provision of protective gear for thermal hazard exposure in US workplaces. The EU Green Deal and REACH chemical standards constrain phase change material sourcing, pushing manufacturers toward bio-based paraffin alternatives and recycled polyester substrates. Stakeholders must monitor battery chemistry regulations and end-of-life textile directives as compliance costs reshape supplier economics and product design priorities across both consumer and industrial channels.
Market Dynamics
Phase change material innovations and battery efficiency improvements are compressing product development cycles while fragmenting supply chain control between textile manufacturers and electronics integrators.
Growth Catalysts
- OSHA thermal hazard mandates:Employer-provision requirements for protective gear in US workplaces drive bulk procurement across construction and logistics sectors.
- Construction labor expansion:Site workers in extreme climate zones generate sustained demand for heated jackets and cooling vests as standard equipment.
- Lithium-ion platform convergence:Power tool manufacturers extend battery ecosystems into thermal workwear, reducing adoption friction for professional trades.
Market Restraints
- REACH chemical constraints:EU Green Deal standards limit paraffin-based phase change material sourcing, forcing costly bio-based alternative development.
- Battery chemistry volatility:Lithium cell supply concentrates in East Asian refining corridors, exposing manufacturers to input cost swings and export control risks.
- Therapeutic claim boundaries:FDA oversight restricts marketing language for wearables crossing into medical temperature management, constraining premium positioning.
Strategic Opportunities
- Smart fabric integration:Textile-embedded sensors enable real-time microclimate modulation, opening military and emergency services procurement channels.
- Aftermarket service unbundling:Third-party battery replacement and component refurbishment create new margin pools outside OEM control.
- Athletic endurance applications:Marathon and ultra-endurance events adopt cooling vests for pre-race core temperature regulation.
Industry Challenges
- Cross-functional talent scarcity:Product development requires simultaneous expertise in textile engineering, thermal physics, and power electronics.
- End-of-life compliance costs:EU textile directives mandate recycled polyester substrates and battery disposal protocols, reshaping supplier economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Comfort Wearables Market |
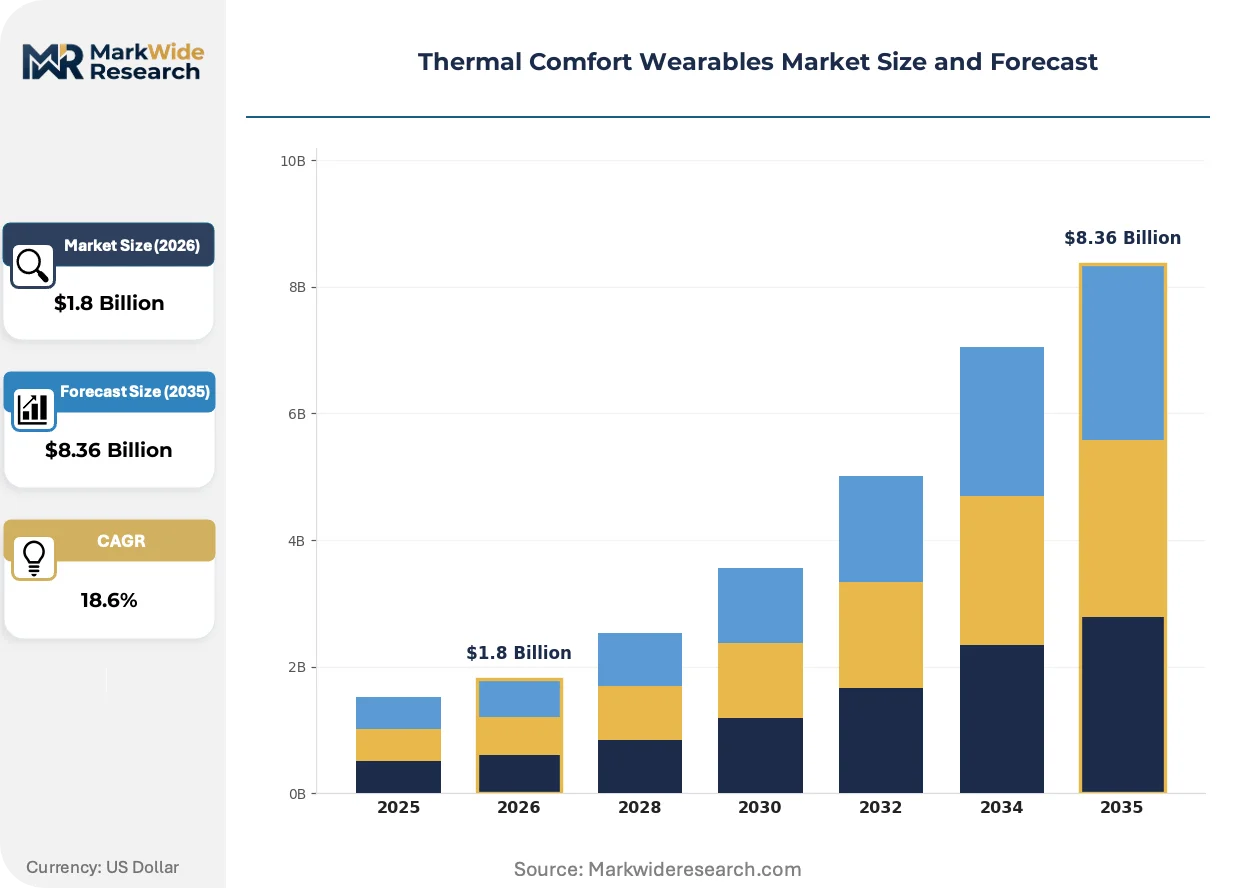
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heated Jackets, Cooling Vests, Thermal Gloves, Insulated Socks, Temperature Regulating Hats Technology: Phase Change Materials, Electric Heating, Thermoelectric Cooling, Smart Fabrics, Nanotechnology Application: Outdoor Sports, Construction Sites, Military Operations, Emergency Services, Adventure Tourism End User: Athletes, Safety Personnel, Defense Agencies, Travel Enthusiasts, Field Engineers |
| Companies Covered | Columbia Sportswear Company, Milwaukee Tool, Sony Thermo Technology Inc., Makita Corporation, TechNiche LLC, Glacier Tek, AlphaCool Products, Nike, Embr Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Comfort Wearables Market Trends and Innovations
Textile-integrated electronics and bio-based material substitutions are collapsing the boundary between functional apparel and powered equipment, forcing new partnerships across historically separate supply chains.
Smart fabric architectures embedding thermoelectric modules and conductive thread networks are digitizing garment temperature control. Military and first responder units in the United States and Germany pilot these systems for mission-critical thermal stability. Real-time biometric feedback loops compress decision latency for wearers operating in variable exposure conditions.
REACH chemical standards and EU Green Deal bio-content thresholds are accelerating paraffin alternative development. Manufacturers reformulate phase change materials around vegetable-derived esters and recycled polymer carriers. Military and emergency services cooling vest suppliers absorb the steepest compliance costs due to performance certification requirements.
Direct-to-trade procurement through power tool retail networks is displacing traditional outdoor apparel distribution for professional heated workwear. Construction contractors purchase heated jackets alongside cordless drills at industrial supply outlets. This channel migration concentrates in North American and Australian markets where trade loyalty programs anchor purchasing behavior.
Thermal Comfort Wearables Market Segmentation
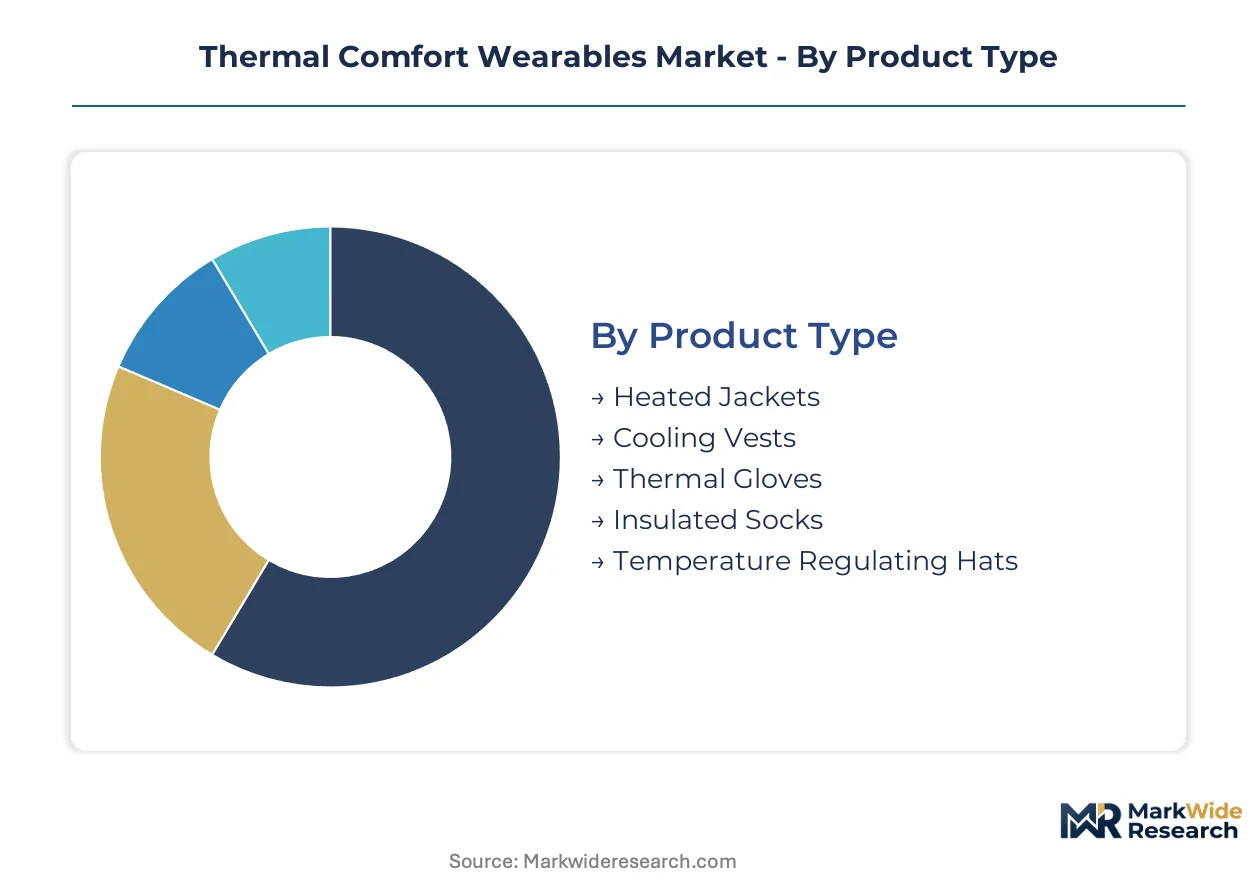
Thermal comfort wearables fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices lock in manufacturing partnerships, while application and end-user segments dictate channel strategy and pricing power.
Product Type:
Cost tier differentiation separates professional-grade equipment from recreational accessories, with battery integration and material certification driving price stratification.
- Heated Jackets:Carbon fiber heating elements woven into water-resistant shells deliver core warmth across variable climates. Demand concentrates among construction contractors in the United States where OSHA cold stress mandates require employer provision. Lithium-ion compatibility with power tool ecosystems reduces adoption friction for trades professionals.
- Cooling Vests:Phase change material inserts or thermoelectric modules maintain stable core temperatures in extreme heat exposure. Military and emergency services procurement in Germany and Australia commands premium pricing due to physiological monitoring requirements and mission-critical certification standards.
- Thermal Gloves:Dexterity-preserving heating circuits target precision work in sub-zero environments. Field engineers in oil and gas operations represent the primary adopter base.
- Insulated Socks:Battery-powered toe warming elements address peripheral circulation challenges. Adventure tourism operators in alpine regions bulk-purchase for guided expedition clients.
- Temperature Regulating Hats:Lightweight PCM liners or resistive heating bands manage cranial heat loss. Marathon and ultra-endurance athletes adopt for pre-race core temperature modulation.
Heated jackets hold installed capacity. Cooling vests are rotating up the share rankings.
Technology:
Application requirements determine technology selection, with passive systems dominating cost-sensitive recreational segments and active systems penetrating professional and military channels.
- Phase Change Materials:Bio-based paraffin or vegetable-derived esters absorb and release latent heat at defined temperature thresholds. EU Green Deal REACH constraints force manufacturers toward recycled polymer carriers, elevating compliance costs for suppliers serving European defense agencies.
- Smart Fabrics:Textile-embedded sensors and conductive thread networks enable real-time microclimate modulation. United States and German military pilot programs drive the steepest expansion trajectory for biometric feedback-integrated garments.
- Electric Heating:Resistive wire or carbon fiber elements powered by rechargeable lithium cells. Construction trades procurement through power tool retail networks anchors volume.
- Thermoelectric Cooling:Peltier modules actively transfer heat away from skin surfaces. Emergency services applications in Australia and Saudi Arabia absorb premium pricing for certified performance.
- Nanotechnology:Graphene or carbon nanotube coatings enhance thermal conductivity and moisture management. Athletic apparel brands experiment with limited production runs.
Phase change materials anchor current deployment. Smart fabrics are climbing the fastest in procurement priority.
Application:
Volume concentration tracks climate exposure severity and regulatory enforcement intensity across occupational and recreational domains.
- Construction Sites:Employer-mandated protective gear against cold stress and heat exhaustion drives bulk procurement. United States OSHA enforcement and Canadian provincial labor codes standardize heated jacket and cooling vest provision.
- Military Operations:Mission-critical thermal stability requirements command the highest performance specifications. German Bundeswehr and United States Department of Defense pilot smart fabric architectures with real-time biometric feedback.
- Outdoor Sports:Recreational skiing, snowmobiling, and hunting applications prioritize battery life and weather resistance. North American and Japanese outdoor retail channels dominate distribution.
- Emergency Services:Firefighters and search-and-rescue units require cooling vests with rapid donning capability and decontamination durability. Australian and Saudi Arabian civil defense agencies lead procurement.
- Adventure Tourism:Guided expeditions in polar and high-altitude regions rent heated accessories to clients. Antarctic tour operators and Himalayan trekking companies represent concentrated demand.
Construction sites hold installed capacity. Military operations are rotating up the share rankings.
End User:
Customer type segmentation separates institutional procurement with compliance requirements from individual purchasing driven by performance or comfort preferences.
- Defense Agencies:National military organizations specify certified thermal management systems with integrated physiological monitoring. German and United States defense procurement offices mandate smart fabric pilot programs.
- Safety Personnel:Employer-provisioned protective gear for construction, logistics, and utility workers. United States OSHA guidelines and Australian state-level regulations enforce thermal hazard protection.
- Athletes:Individual and team purchases for training and competition temperature regulation. Marathon and ultra-endurance communities in Japan and Germany adopt pre-cooling vests.
- Field Engineers:Oil and gas, telecommunications, and renewable energy technicians operating in remote climate extremes. Canadian oil sands and Saudi Arabian solar installations generate concentrated demand.
- Travel Enthusiasts:Recreational consumers purchasing through outdoor retail and direct-to-consumer channels. Alpine tourism regions in Switzerland and Austria drive seasonal spikes.
Defense agencies hold installed capacity. Safety personnel are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States procurement centers on OSHA-mandated employer provision for construction trades, while German demand tracks military smart fabric pilots and EU regulatory compliance costs. Japanese adoption concentrates in athletic pre-cooling applications.
United States
Construction contractors and logistics operators drive volume through employer-mandated cold stress protection. OSHA thermal hazard guidelines enforce bulk procurement of heated jackets and cooling vests across federally regulated workplaces. Industrial supply clusters in Chicago and Houston anchor distribution through power tool retail networks.
Germany
Bundeswehr defense procurement and REACH chemical compliance reshape supplier economics simultaneously. EU Green Deal bio-content thresholds force phase change material reformulation toward vegetable-derived esters. Smart fabric pilot programs in Bavaria and North Rhine-Westphalia integrate real-time biometric feedback for military field trials.
Japan
Marathon and ultra-endurance athletic communities adopt pre-cooling vests for core temperature regulation before competition. METI standards govern battery chemistry and textile-integrated electronics safety certification. Manufacturing concentration in the Kanto region around Tokyo supports precision textile-electronics integration for wearable thermal systems.
Australia
Emergency services and civil defense agencies in Queensland and Western Australia command premium pricing for certified cooling vest performance. State-level occupational safety regulations parallel OSHA frameworks for outdoor worker thermal protection. Mining operations in the Pilbara generate concentrated demand for heat exhaustion prevention equipment.
Saudi Arabia
Solar installation field engineers and construction supervisors operating in extreme desert heat absorb thermoelectric cooling vest premiums. The national renewable energy program under Vision 2030 expands outdoor infrastructure workforce exposure hours. Eastern Province industrial cities including Jubail and Dammam concentrate procurement for petrochemical and energy sector thermal protection.
Thermal Comfort Wearables Market Competitive Landscape
Capability concentration sits with textile-electronics integrators; scale advantage sits with power tool manufacturers extending battery ecosystems. The market structures around three tiers: outdoor apparel brands with heated product lines, professional tool companies leveraging lithium-ion platform convergence, and specialty thermal technology developers. Dominant competitive moves include backward integration into phase change material sourcing and strategic partnerships between garment manufacturers and battery cell suppliers.
Among power tool ecosystem extenders, Milwaukee Tool and Makita Corporation exemplify the platform convergence archetype. Columbia Sportswear Company occupies a position representing outdoor apparel channel control. These three anchors illustrate how battery compatibility and retail distribution access determine competitive positioning across professional and consumer segments.
| Leading Market Players |
|---|
| Columbia Sportswear Company |
| Milwaukee Tool |
| Sony Thermo Technology Inc. |
| Makita Corporation |
| TechNiche LLC |
| Glacier Tek |
| AlphaCool Products |
| Nike |
| Embr Labs |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Los Angeles container rates compress margin structures for battery cell importers while amplifying price spreads between OEM-certified and third-party refurbished thermal wearables. East Asian lithium refining concentration feeds into tiered procurement costs that separate defense agency buyers from construction contractors.
Pricing Analysis
Long-term offtake agreements dominate defense and emergency services procurement, insulating premium-tier suppliers from spot market volatility in battery raw materials. Pricing stratifies across certified performance tiers, with FDA-cleared therapeutic claims and OSHA compliance documentation commanding substantial premiums over recreational-grade alternatives. Cost compression in the aftermarket refurbishment segment is intensifying because third-party battery suppliers erode OEM service margins. Construction contractors exhibit the highest price sensitivity, while military procurement offices absorb premiums for integrated biometric monitoring.
Supply Chain Analysis
Export control regimes on advanced battery chemistries and thermoelectric modules constrain flows from South Korea and Japan to non-allied defense customers. China, South Korea, and Taiwan concentrate lithium cell and PCM substrate manufacturing, creating single-source vulnerability for European manufacturers facing REACH compliance deadlines. Raw material dependencies center on cobalt sulfate, bio-based paraffin esters, and conductive textile substrates. Distribution runs through power tool retail networks for professional trades and outdoor apparel channels for recreational consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermal comfort wearables market sits in early-cycle recovery as construction labor expansion and lithium-ion platform convergence reactivate employer procurement budgets.
For Market Incumbents: Pre-empt aftermarket fragmentation by capturing battery replacement revenue through subscription service models and authorized refurbishment networks. Power tool ecosystem extenders should deepen captive supply of phase change materials to offset REACH-driven input cost inflation. Incumbents must defend against smart fabric specialists by accelerating textile-electronics integration partnerships. For New Entrants and Emerging Players: Saudi Arabian solar installation corridors and Australian Pilbara mining operations represent underpenetrated white-space for thermoelectric cooling vest deployment. Athletic pre-cooling applications in Japanese marathon communities offer lower certification barriers than defense procurement channels. New entrants should pursue direct-to-trade distribution through industrial supply cooperatives rather than competing for outdoor retail shelf space. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified apparel conglomerates with dormant heated outerwear lines lacking battery ecosystem integration. Long-term viability hinges on regulatory compliance capabilities spanning FDA therapeutic claims and EU textile end-of-life directives. Investors should monitor Bundeswehr and United States Department of Defense smart fabric pilot program expansion as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based PCM Sourcing | EU Green Deal compliance costs force captive supply of vegetable-derived ester alternatives to paraffin. |
| Power Tool Retail Network Expansion | Milwaukee Tool and Makita demonstrate that battery ecosystem convergence anchors professional trades loyalty. |
| Smart Fabric Architecture Development | German military pilot programs validate real-time biometric feedback as a mission-critical procurement criterion. |
| Aftermarket Service Platform Launch | Third-party battery replacement erodes OEM margins; authorized refurbishment recaptures recurring revenue pools. |
| Defense Certification Investment | United States Department of Defense and Bundeswehr mandates create insulated premium pricing tiers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with heated apparel product managers, lithium-ion battery procurement leads at power tool manufacturers, textile-electronics integration engineers, and defense agency contracting officers. Secondary validation drew from OSHA enforcement databases, EU REACH substance restriction updates, FDA 510(k) clearance filings, and customs trade records for battery cell imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical procurement volumes and disclosed defense contract awards anchored the analytical framework. Segmentation dimensions modeled include product type, heating or cooling technology, application environment, and end-user procurement authority. CAGRs were derived from fitted growth curves applied to validated baseline estimates. Industry-specific forecast inputs incorporated construction labor force projections and lithium cell capacity expansion announcements.
Practitioners should monitor battery chemistry export control expansions and EU textile directive implementation timelines for early signals of supply cost displacement. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and power tool ecosystem platform stability. Material shifts in defense procurement prioritization away from smart fabric pilots would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market