
 Global Weight Management Devices Market | 2026-2036
Global Weight Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Weight Management Devices Market Foresight
Clinical-grade accuracy tiers are redrawing competitive boundaries in weight management hardware. Medtronic leverages its regulatory heritage to anchor premium positioning in medical-validated segments. Johnson Health Technology sustains manufacturing scale across commercial fitness channels. Technogym SpA differentiates through integrated software-hardware ecosystems serving luxury wellness clubs.
Weight management devices encompass instruments that measure, monitor, or modulate body mass metrics through electromechanical or biochemical sensing, typically employing bioelectrical impedance analysis with frequencies between 1 kHz and 1 MHz to estimate fat-free mass and total body water. These systems serve commercial fitness operators, clinical weight-loss programs, and individual consumers pursuing quantified health outcomes. Wearable trackers and body composition scales occupy the largest installed base, while smart clothing represents the fastest-expanding margin pool due to sensor miniaturization and textile integration costs. Fitness tracking and weight loss applications generate the highest volume, though posture correction is gaining traction among corporate wellness contracts seeking musculoskeletal risk reduction.
FDA 510(k) requirements, EU MDR classification for active therapeutic devices, and China's NMPA digital health standards collectively elevate barriers for new entrants lacking clinical validation resources. The EU AI Act introduces additional scrutiny for algorithmic body-composition recommendations, reshaping product development roadmaps for connected devices. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as these determine whether medical-grade devices penetrate home settings or remain confined to institutional channels.
Market Dynamics
Clinical validation requirements from FDA, EU MDR, and China's NMPA are forcing manufacturers to restructure R&D budgets toward medical-grade accuracy tiers rather than consumer-grade feature expansion.
Growth Catalysts
- Employer wellness mandates:Large corporations in the United States are expanding procurement of connected body composition analyzers as part of musculoskeletal risk reduction programs.
- EU AI Act compliance pathways:Algorithmic body-composition recommendation engines are receiving regulatory clarity that accelerates product development roadmaps for connected device vendors.
- Sensor miniaturization:Advances in textile-integrated bioelectrical impedance sensors are unlocking smart clothing applications across commercial fitness channels.
Market Restraints
- Clinical validation costs:Multi-site trials required for FDA 510(k) clearance consume 18-24 months and strain mid-cap development budgets.
- Semiconductor supply concentration:Precision analog front-end chips for impedance measurement depend on Taiwanese foundry capacity subject to geopolitical disruption.
- Reimbursement code fragmentation:Remote patient monitoring billing codes vary across German, French, and Italian healthcare systems, blocking standardized go-to-market strategies.
Strategic Opportunities
- Posture correction applications:Corporate wellness contracts in Germany are expanding beyond weight metrics to include spinal alignment monitoring through integrated sensor arrays.
- Home medical-grade penetration:Evolving CPT codes for remote patient monitoring in the United States create reimbursement pathways for clinical-validated devices outside institutional settings.
- AI-hardware convergence:Machine learning models trained on longitudinal body-composition datasets are enabling predictive metabolic health alerts that differentiate premium device tiers.
Industry Challenges
- Multidisciplinary talent scarcity:Firmware engineers with expertise in both electrochemical sensing and wireless health data protocols command premium compensation that compresses margin structures.
- Legacy system integration:Hospital electronic health record architectures in China require custom HL7 FHIR middleware development that extends deployment timelines.
- Cross-border certification parallelism:Simultaneous FDA, EU MDR, and NMPA submissions demand redundant documentation workflows that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Weight Management Devices Market |
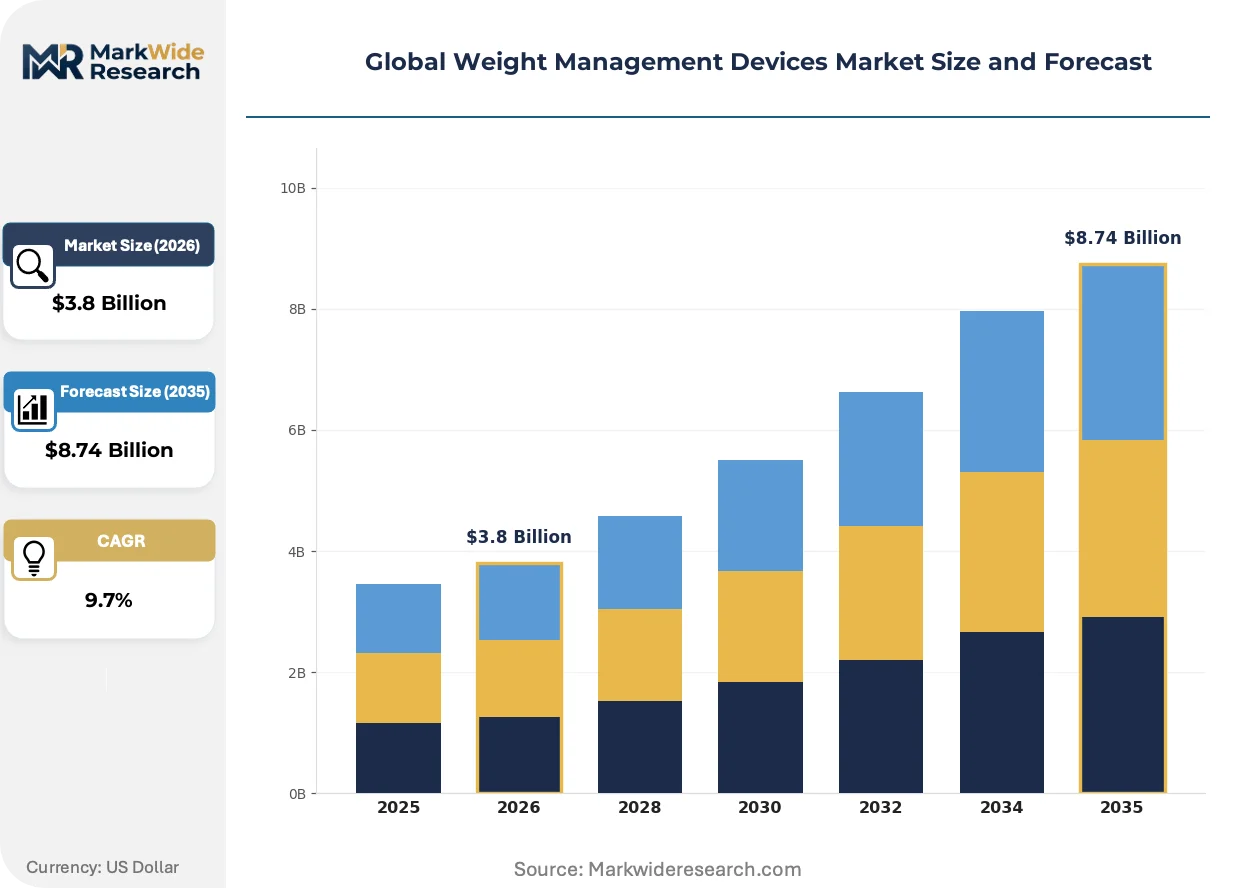
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Trackers, Body Composition Scales, Smart Clothing, Fitness Bands, Nutritional Monitors Technology: Bioelectrical Impedance Analysis, Accelerometer Sensors, Heart Rate Monitoring, Infrared Sensors, Optical Sensors Application: Weight Loss, Muscle Gain, Fitness Tracking, Posture Correction, Lifestyle Management End User: Fitness Centers, Home Users, Corporate Wellness Programs, Sports Coaches, Weight Loss Clinics |
| Companies Covered | Life Fitness, Johnson Health Technology, Fitness World, Olympus Corporation, Medtronic, Technogym SpA, Brunswick Corporation, Amer Sports, Cybex International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Weight Management Devices Market Shifts & Advancements
Bioelectrical impedance analysis architectures are fragmenting into divergent accuracy-performance tiers that reshape competitive boundaries between medical and consumer device categories.
Multi-frequency impedance spectroscopy is bifurcating the hardware landscape. Devices operating between 1 kHz and 1 MHz now separate into clinical-grade systems with segmental analysis capabilities and simplified consumer units with whole-body estimation only. Hospital-based metabolic clinics in the United States are adopting the former for bariatric surgery preparation protocols. The technology gap is compressing mid-market vendors unable to fund dual certification tracks.
EU MDR classification rules for active therapeutic devices are tightening post-market surveillance obligations. Manufacturers must now submit periodic safety update reports that include real-world algorithm performance data. Connected body composition scales with diagnostic recommendations fall under Class IIa scrutiny, forcing software-hardware vendors to restructure quality management systems ahead of 2027 renewal deadlines.
Corporate wellness buyers are unbundling device procurement from bundled service contracts. Large employers in Germany now source hardware through IT procurement channels while separately contracting data analytics vendors for population health dashboards. Fitness operators resist this disintermediation by developing proprietary software ecosystems that lock body-composition data within branded platforms. The tension is most visible in China, where employer-sponsored fitness ecosystems are negotiating direct device OEM relationships that bypass traditional commercial distribution.
Global Weight Management Devices Market Segmentation
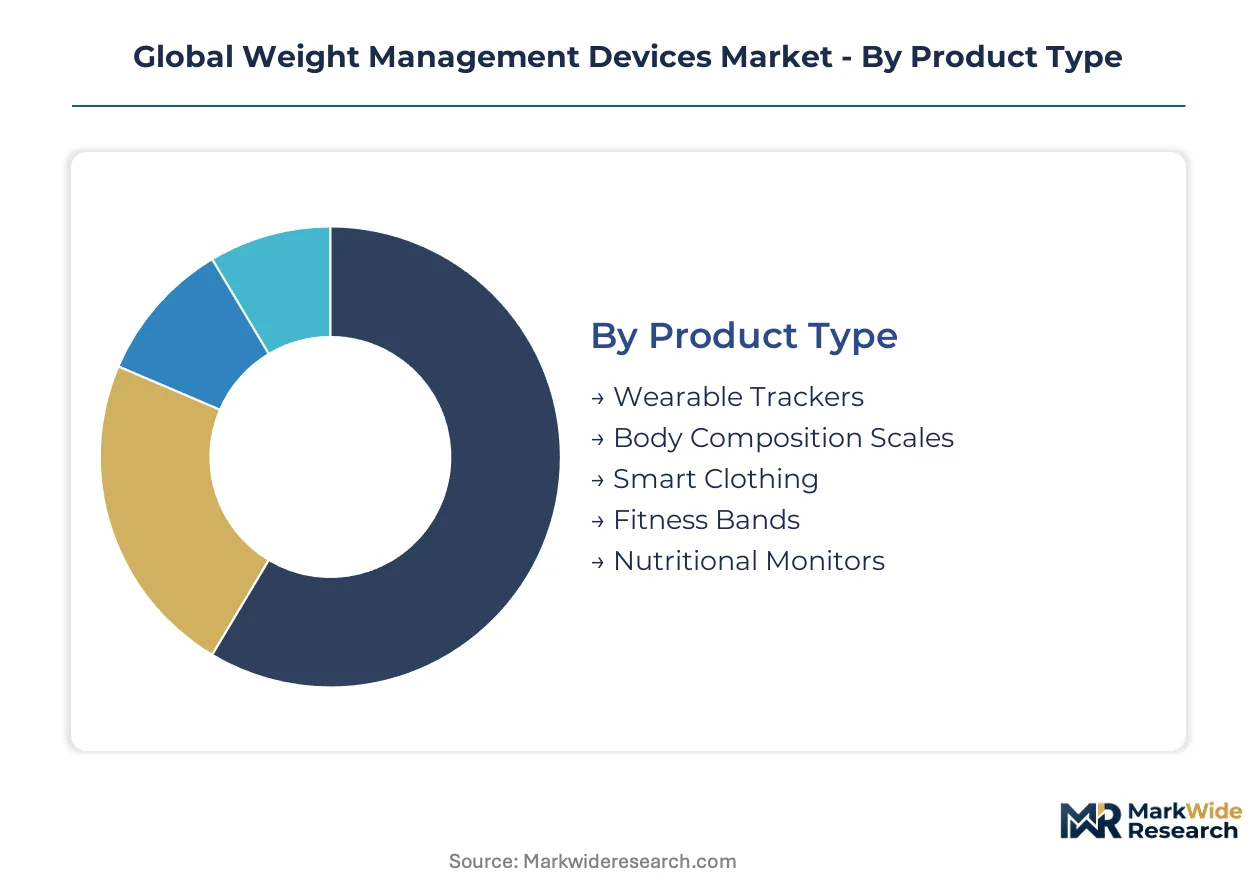
Segmentation in weight management devices reveals distinct procurement patterns across clinical and consumer channels. Technology tiers and application specificity determine pricing power, while end-user concentration shapes geographic deployment strategies.
Product Type:
Domestic demand concentrates in wearable trackers and body composition scales across United States, China, and Germany. Smart clothing and nutritional monitors follow export-led distribution patterns through commercial fitness OEM channels.
- Wearable Trackers:Wrist-worn devices integrating accelerometer and optical heart rate sensors for continuous activity monitoring. Demand clusters among corporate wellness programs in the United States seeking population-level metabolic data aggregation.
- Body Composition Scales:Platform-based systems employing multi-frequency bioelectrical impedance analysis between 1 kHz and 1 MHz for segmental fat-free mass estimation. German fitness centers and home users in China drive procurement volume for connected models with smartphone integration.
- Smart Clothing:Textile-integrated sensor arrays measuring biometrics through fabric electrodes. Emerging applications target posture correction contracts in German corporate wellness markets.
- Fitness Bands:Simplified wrist-worn accelerometers without advanced biometric sensing. Price-sensitive home users in China represent the primary addressable base.
- Nutritional Monitors:Handheld or countertop devices estimating caloric content through optical spectroscopy. Limited deployment currently restricted to premium weight loss clinics in the United States.
Wearable trackers command the established base. The steepest expansion runs through smart clothing.
Technology:
Cost stratification separates clinical-grade multi-frequency systems from consumer single-frequency units. Medical-validated tiers command 3-4x manufacturing overhead due to precision analog front-end requirements.
- Bioelectrical Impedance Analysis:Electrochemical tissue characterization using alternating current injection at 1-1000 kHz. FDA 510(k) clearance pathways in the United States and EU MDR Class IIa classification impose validation burdens that compress mid-market vendor margins.
- Accelerometer Sensors:MEMS-based motion detection for step counting and activity classification. Volume manufacturing in Taiwanese foundries supplies fitness bands and entry-level wearables across all major markets.
- Heart Rate Monitoring:Photoplethysmography through green LED optical sensors. Pervasive integration into wearable trackers drives commoditization pressure on standalone units.
- Infrared Sensors:Thermal emission detection for non-contact temperature and metabolic estimation. Niche deployment in nutritional monitors awaiting clinical validation.
- Optical Sensors:Multi-wavelength light absorption measurement for blood oxygen and perfusion metrics. Regulatory scrutiny from China's NMPA digital health standards limits algorithmic diagnostic claims.
Bioelectrical impedance analysis anchors medical-grade revenue. Accelerometer sensors are climbing the fastest on volume scale.
Application:
Customer type determines feature bundling. Fitness tracking applications support hardware-software ecosystem plays, while posture correction enables premium pricing through musculoskeletal risk reduction value propositions.
- Weight Loss:Caloric deficit monitoring through integrated body composition and activity tracking. Weight loss clinics in the United States and Germany specify medical-grade accuracy tiers for bariatric surgery preparation protocols.
- Muscle Gain:Protein metabolism tracking and resistance training load quantification. Sports coaches in China represent a concentrated early-adopter segment for segmental muscle mass analyzers.
- Fitness Tracking:General activity quantification spanning steps, distance, and energy expenditure. Corporate wellness programs across all three core markets standardize on this application for population health dashboards.
- Posture Correction:Spinal alignment monitoring through accelerometer arrays or smart clothing strain sensors. German employer mandates for musculoskeletal risk reduction are accelerating procurement.
- Lifestyle Management:Holistic wellness aggregation combining sleep, stress, and metabolic metrics. Home users in China demonstrate highest engagement with all-in-one platform approaches.
Fitness tracking commands the established base. Posture correction is gaining share fastest through corporate wellness channel expansion.
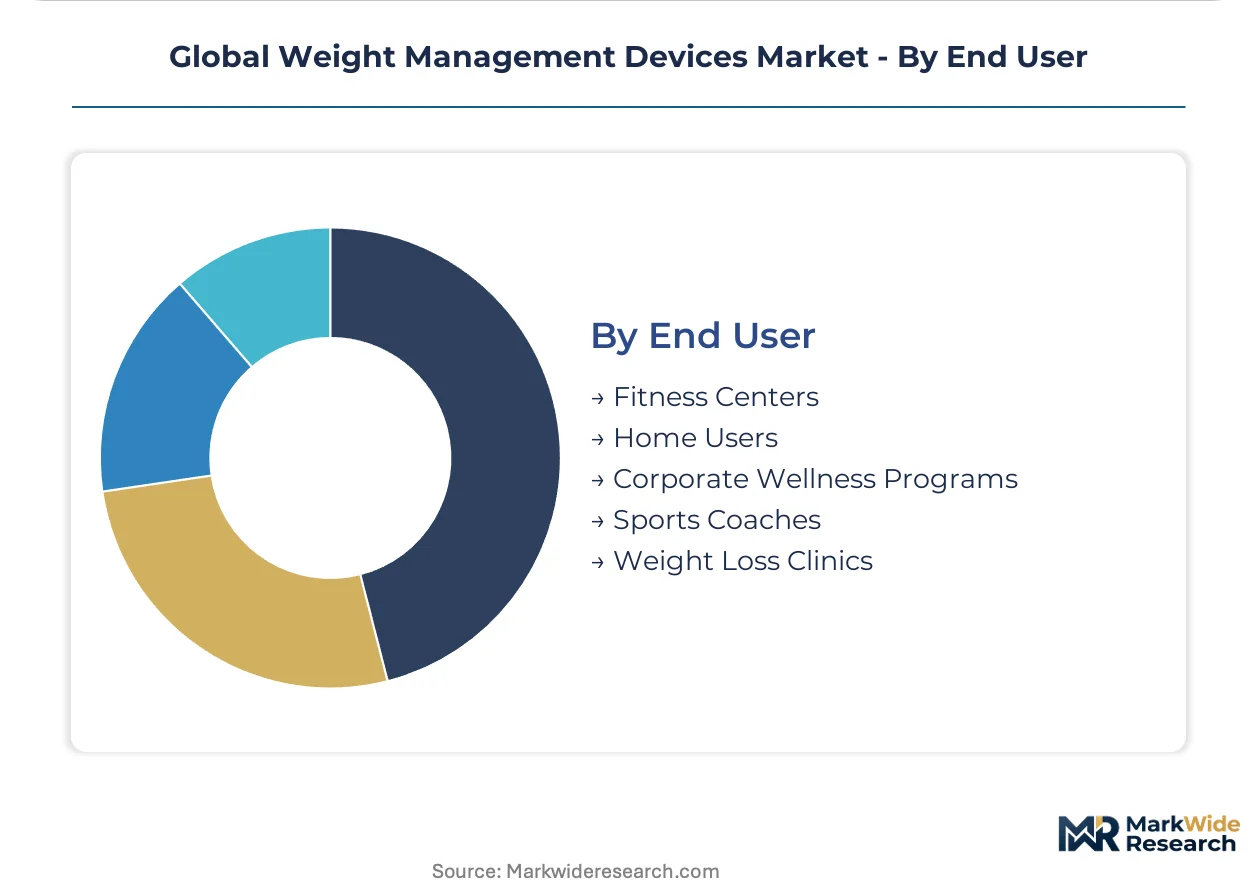
End User:
Channel structure fragments between institutional procurement with clinical validation requirements and direct-to-consumer retail with feature-competitive positioning.
- Fitness Centers:Commercial operators requiring durable hardware with centralized data management. Technogym and Johnson Health Technology serve this channel with integrated software-hardware ecosystems.
- Home Users:Individual consumers purchasing through retail or e-commerce. Price sensitivity concentrates demand in simplified body composition scales and fitness bands.
- Corporate Wellness Programs:Employer-sponsored health initiatives with population analytics requirements. United States and Germany lead procurement of connected analyzers for metabolic risk stratification.
- Sports Coaches:Individual practitioners and team staff seeking athlete-specific monitoring. Niche volume with premium pricing for segmental analysis capabilities.
- Weight Loss Clinics:Medical facilities requiring FDA 510(k) or EU MDR clearance for diagnostic use. Medtronic leverages regulatory heritage to anchor this highest-accuracy tier.
Home users command the established base. Corporate wellness programs are expanding most quickly through employer mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, China, and Germany generate net imports of precision analog components while exporting finished body composition systems to adjacent markets. Trade flows concentrate through Shenzhen, Hamburg, and Los Angeles logistics corridors.
United States
Employer-sponsored fitness ecosystems drive procurement of connected analyzers for metabolic risk stratification. FDA 510(k) clearance pathways tighten clinical validation requirements for bioelectrical impedance devices. Hospital-based metabolic clinics in Houston and Phoenix adopt segmental analysis systems for bariatric surgery preparation protocols.
Germany
Corporate wellness mandates expand procurement beyond weight metrics to posture correction applications. EU MDR classification rules impose Class IIa scrutiny on connected scales with diagnostic recommendations. Industrial clusters in Bavaria and North Rhine-Westphalia host precision sensor manufacturers serving medical-grade accuracy tiers.
China
Home users demonstrate highest engagement with integrated platform approaches combining sleep, stress, and metabolic metrics. NMPA digital health standards limit algorithmic diagnostic claims for optical sensor systems. Yangtze River Delta manufacturing bases supply accelerometer-based fitness bands for price-sensitive domestic demand.
Japan
Sports coaches represent concentrated early adopters for segmental muscle mass analyzers tracking protein metabolism. METI standards guide wireless health data protocol integration in connected devices. Kansai region precision electronics suppliers serve textile-integrated sensor arrays for smart clothing applications.
United Kingdom
Commercial fitness operators source hardware through IT procurement channels while separately contracting data analytics vendors. GDPR compliance requirements reshape data governance for population health dashboards. London-based wellness technology integrators deploy connected analyzers within employer-sponsored programs.
Global Weight Management Devices Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification depth and manufacturing scale dimensions. Market structure fragments into three tiers: medical-validated incumbents with FDA heritage, commercial fitness OEMs with integrated software ecosystems, and component-scale fabricators supplying private-label brands. Dominant competitive moves include M&A for regulatory asset acquisition and strategic partnerships for sensor technology licensing.
Within the medical-validated tier, Medtronic and Olympus Corporation anchor premium positioning through regulatory heritage. Johnson Health Technology and Technogym SpA occupy the commercial fitness channel with integrated software-hardware ecosystems. Life Fitness and Brunswick Corporation exemplify scale-driven manufacturing archetypes serving institutional procurement channels.
| Leading Market Players |
|---|
| Life Fitness |
| Johnson Health Technology |
| Fitness World |
| Olympus Corporation |
| Medtronic |
| Technogym SpA |
| Brunswick Corporation |
| Amer Sports |
| Cybex International |
| Others |
Supply & Pricing Matrix
Precision analog front-end chips replacing discrete component assemblies simultaneously concentrates supply geography in Taiwanese foundries and compresses pricing economics for mid-tier body composition scale manufacturers. This substitution dynamic forces vendors to absorb margin pressure or migrate toward medical-grade certification tiers where pricing power persists.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation separates FDA 510(k)-cleared clinical systems from consumer-grade fitness trackers and unbranded private-label imports. Pricing pressure stems from semiconductor cost volatility and foundry capacity constraints. Corporate wellness programs demonstrate lowest price sensitivity due to population health ROI mandates, while home users in China drive commoditization at the economy tier.
Supply Chain Analysis
Taiwan Strait logistics chokepoints expose precision analog chip flows to geopolitical disruption risk. Manufacturing concentration centers on Taiwan for impedance measurement semiconductors, China for accelerometer MEMS fabrication, and Germany for textile-integrated sensor arrays. Raw material dependencies span rare earth elements for magnetic sensors, medical-grade conductive textiles, and lithium-ion cells for wearable power systems. Distribution runs through Shenzhen electronics corridors, Hamburg industrial logistics hubs, and Los Angeles port complexes serving North American wellness program procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The weight management devices market sits in early-cycle expansion as employer-sponsored fitness ecosystems accelerate connected analyzer penetration beyond traditional clinical boundaries. Corporate mandate proliferation in the United States and Germany creates a structural tailwind for medical-validated hardware adoption.
For Market Incumbents: Fortify regulatory asset portfolios through simultaneous FDA 510(k), EU MDR, and NMPA submission pipelines to preempt mid-cap challengers. Deepen backward integration into precision analog semiconductor sourcing to offset Taiwanese foundry concentration risk. Prioritize software-hardware ecosystem lock-in through proprietary data analytics platforms that resist employer unbundling trends.
For New Entrants and Emerging Players: Posture correction analytics for German corporate musculoskeletal risk programs represents an under-served service layer where incumbents lack specialized algorithmic depth. Target this application white-space through textile-integrated sensor partnerships with Bavarian industrial clusters. Pursue direct OEM relationships with Chinese employer-sponsored fitness ecosystems that bypass traditional commercial distribution channels.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated specialists with dual certification capabilities. Long-term viability over the next decade hinges on regulatory asset accumulation rather than feature innovation velocity. Monitor EU AI Act implementation timelines as the critical inflection signal for algorithmic body-composition recommendation engine viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Medical-grade accuracy tier unlocks hospital-based metabolic clinic procurement in Houston and Phoenix. |
| EU MDR Class IIa Certification | Post-market surveillance compliance enables connected scale deployment across German corporate wellness mandates. |
| Textile Sensor Partnership | Bavarian precision electronics integration accelerates smart clothing applications for posture correction contracts. |
| Software Companion Development | Proprietary data platforms resist employer unbundling of hardware from analytics procurement channels. |
| Reimbursement Strategy | Remote patient monitoring CPT code alignment penetrates home settings beyond institutional channels. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and corporate wellness program directors anchored the qualitative base for this study. Primary interview findings triangulated against FDA 510(k) filing databases, EU MDR notified body submission records, NMPA digital health registration data, and CMS remote patient monitoring billing code documentation. Bottom-up installed base estimates and top-down macroeconomic drivers converged through iterative validation across stakeholder inputs.
Sensitivity analysis frameworks tested volume and value outputs across product type, technology tier, application specificity, and end-user channel segmentation throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory milestone impacts. Modeled inputs included employer mandate proliferation rates, semiconductor foundry capacity utilization, and evolving reimbursement code coverage for clinical-validated devices.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR Class IIa classification, and NMPA digital health standards; material policy shifts would require re-modeling. Specific risks span EU AI Act algorithmic scrutiny intensity, Taiwan Strait logistics disruption, and German CPT code fragmentation across federal state healthcare systems. Practitioners should keep alternative scenarios live as employer-sponsored fitness ecosystem contract structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
United States Wearable Sensors Market