
 Fitness Tracker for Heart Rate Market | 2026-2036
Fitness Tracker for Heart Rate Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness Tracker for Heart Rate Market Insights
Southeast Asia is tilting toward electronics assembly expansion as regional governments attract wearable device manufacturing. Apple Inc. leverages vertical integration across sensor design and software ecosystems to dominate premium positioning. Garmin Ltd. anchors its competitive stance in GPS-integrated sports performance segments with specialized hardware. Xiaomi Technology competes through manufacturing scale that compresses unit costs for fitness band distribution.
A fitness tracker for heart rate is a wearable biosensing device that employs photoplethysmography or electrical cardiography to detect pulse intervals, typically operating at sampling rates between 100 and 512 Hz for clinical-grade accuracy, with primary commercial purpose of enabling users and clinicians to monitor cardiac load, recovery metrics, and arrhythmia indicators during rest or exertion. Smartwatch form factors capture the dominant margin pool as consumers consolidate devices and demand cellular connectivity alongside cardiac metrics. Optical sensor technology leads shipment volumes due to lower manufacturing complexity, though ECG monitoring segments attract premium pricing from healthcare channel buyers seeking diagnostic-grade data streams.
FDA 510(k) requirements govern ECG-enabled wearables in the United States, while the EU Medical Device Regulation reclassifies certain continuous heart rate monitors as Class IIa devices, tightening clinical validation obligations for market access. China's NMPA implements distinct registration pathways for imported versus domestic wearable medical devices, creating variable approval timelines that shape regional launch sequencing. Stakeholders must monitor evolving reimbursement codes for remote cardiac monitoring as payors determine which sensor data streams qualify for clinical compensation.
Market Dynamics
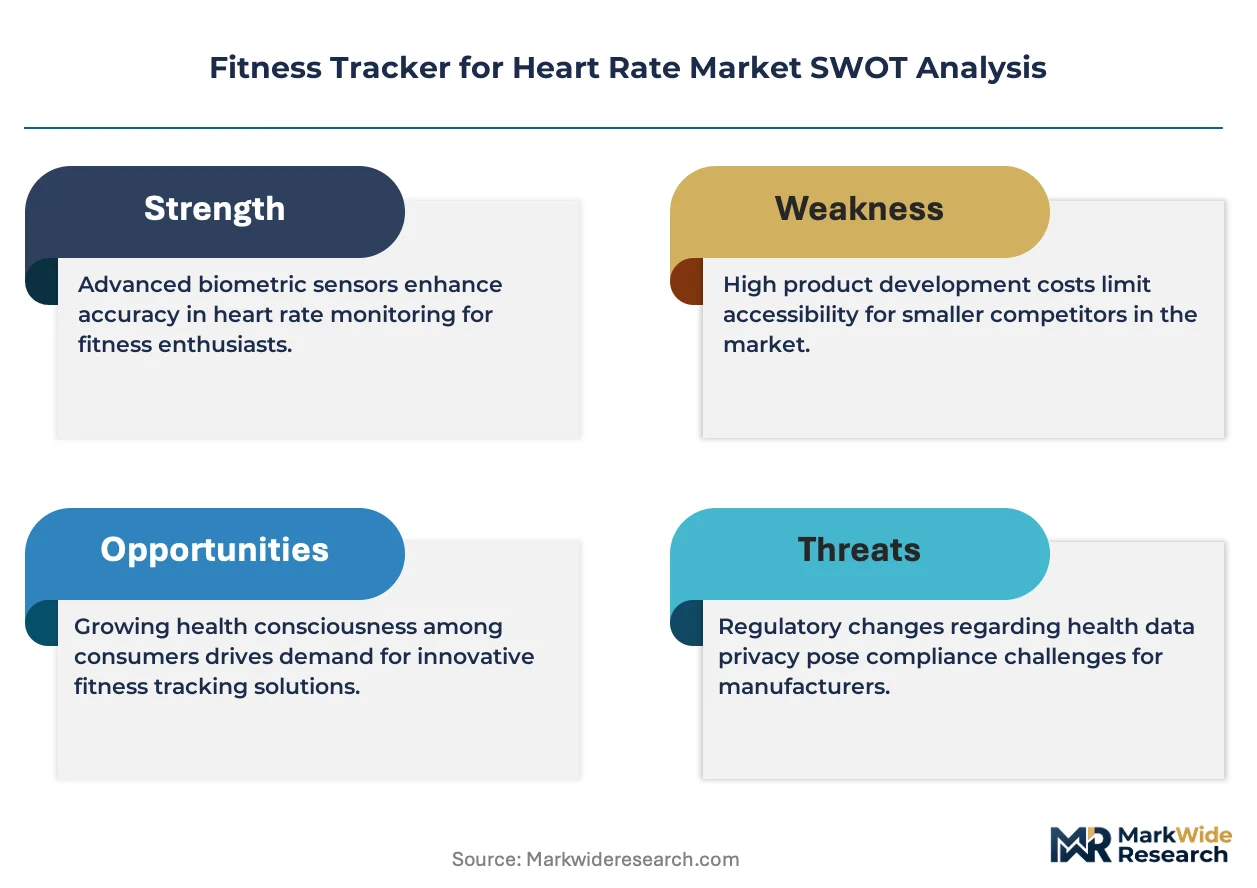
FDA 510(k) clearance timelines for ECG-enabled wearables are compressing product development cycles while EU MDR reclassification tightens clinical validation burdens, forcing manufacturers to bifurcate their hardware architectures between consumer and medical-grade variants.
Growth Catalysts
- Employer wellness mandates:Large US corporations now subsidize continuous cardiac monitoring for workforce risk reduction, expanding B2B procurement channels beyond traditional retail.
- Photoplethysmography miniaturization:Advances in optical sensor packaging enable sub-millimeter form factors that integrate into jewelry and apparel accessories.
- China's dual carbon goals:Domestic manufacturing incentives accelerate regional supply chain consolidation for battery and sensor module production.
Market Restraints
- Optical sensor accuracy limitations:Skin tone variation and motion artifact interference constrain clinical-grade reliability across diverse patient populations.
- Lithium-polymer supply concentration:Battery cell production clusters in East Asia expose manufacturers to geopolitical logistics disruption and input cost volatility.
- FDA software-as-medical-device scrutiny:Algorithm updates for arrhythmia detection trigger supplemental review pathways that extend commercialization timelines.
Strategic Opportunities
- Remote patient monitoring reimbursement:US CMS evaluation of new CPT codes for ambulatory cardiac data creates prospective payment streams for hospital system deployments.
- India's PLI scheme for wearables:Production-linked incentives attract assembly capacity for export-oriented fitness band manufacturing serving Middle Eastern and African markets.
- AI-ECG convergence:On-device inference engines enable real-time atrial fibrillation screening without cloud connectivity, reducing latency for acute event detection.
Industry Challenges
- Biomedical signal processing expertise scarcity:The intersection of hardware engineering and clinical algorithm development commands premium talent compensation in competitive labor markets.
- Multi-regulatory certification parallelism:Simultaneous FDA, NMPA, and EU MDR submissions require duplicative clinical trials that strain R&D budgets.
- Legacy EHR integration complexity:Proprietary data formats from wearable devices demand custom API development for seamless hospital workflow incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness Tracker for Heart Rate Market |
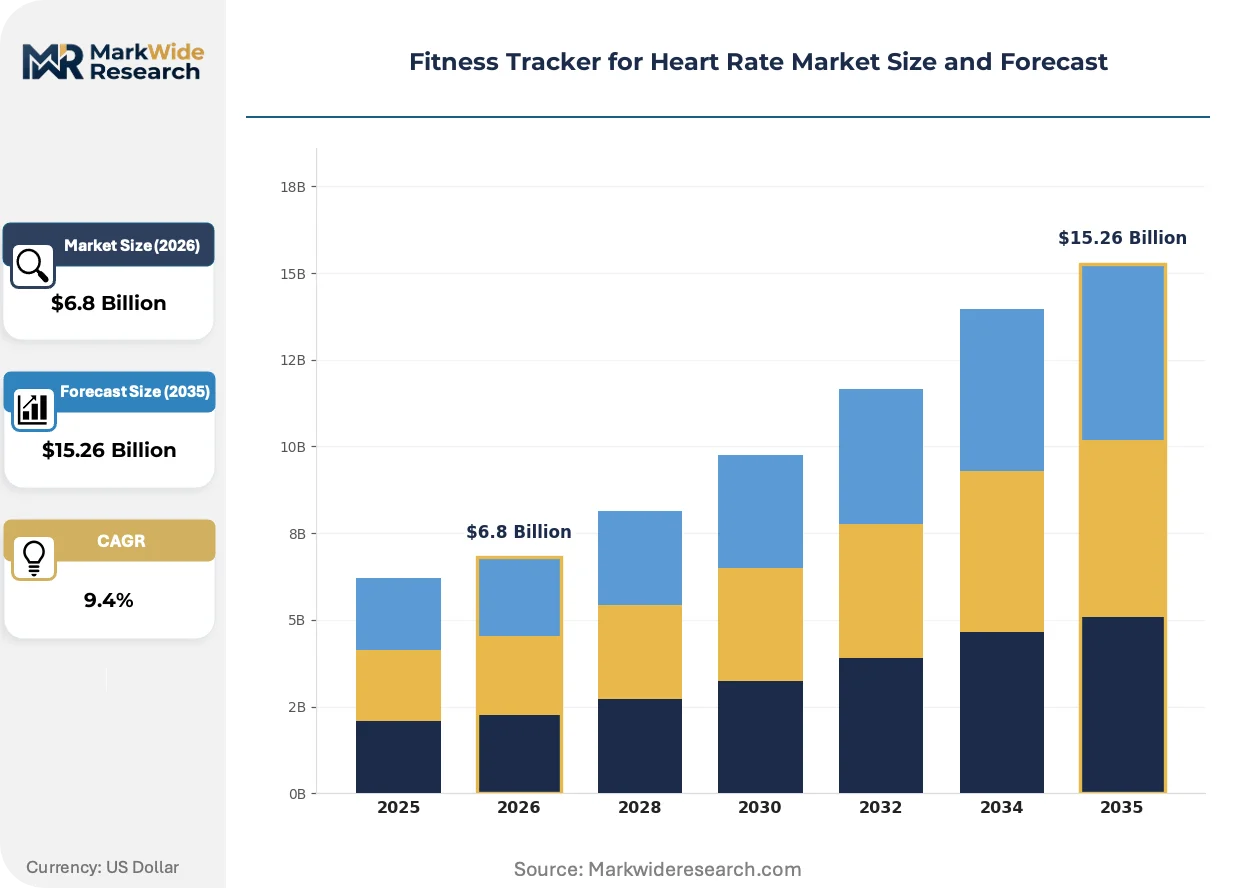
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wristband, Chest Strap, Smartwatch, Fitness Band Technology: Optical Sensor, ECG Monitoring, Bluetooth, NFC End User: Athletes, Fitness Enthusiasts, Casual Users, Healthcare Professionals Application: Cardiovascular Health, Sports Performance, Wellness Tracking, Health Monitoring |
| Companies Covered | Apple Inc., Garmin Ltd., Google Inc., Samsung Electronics, Fitbit Inc., Huawei Technologies, Xiaomi Technology, Polar Electro, WHOOP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness Tracker for Heart Rate Market Trends and Innovations
Convergence between consumer wellness positioning and clinical diagnostic capability is dissolving traditional category boundaries, with hardware architectures now designed for dual-use certification from inception rather than retrofit.
Multi-wavelength photoplethysmography is collapsing the performance gap between optical and electrical cardiography for resting heart rate variability measurement. Cardiac rehabilitation centers in Germany and the United States are piloting these sensors for post-surgical recovery protocols. The technology is collapsing the addressable market for dedicated Holter monitors by capturing equivalent diagnostic fidelity at one-tenth the hardware cost.
EU MDR Class IIa reclassification for continuous heart rate monitors mandates notified body involvement for clinical validation documentation. Manufacturers must now maintain post-market surveillance systems that track real-world performance across diverse demographic cohorts. The regulation most acutely affects smartwatch vendors seeking CE marking for ECG functionality, driving consolidation of regulatory affairs functions among mid-tier competitors.
Hospital procurement departments are unbundling device acquisition from data analytics subscriptions, treating cardiac monitoring hardware as capital equipment while negotiating separate SaaS contracts for population health dashboards. This bifurcation disrupts traditional bundled pricing models that subsidized sensor costs through multi-year service agreements. The shift is most pronounced in US health systems responding to tightened capital expenditure controls and value-based care contracting requirements.
Fitness Tracker for Heart Rate Market Segmentation
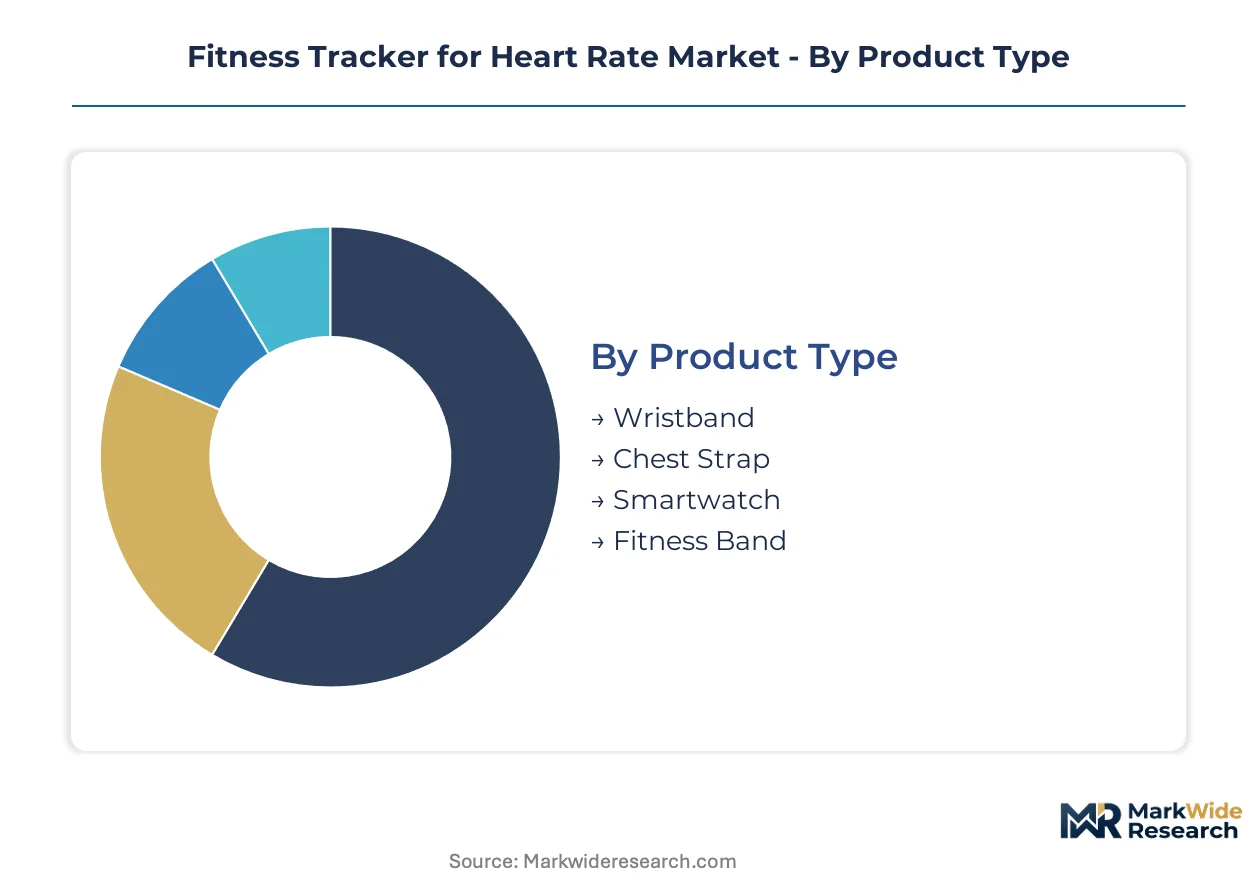
Heart rate tracking hardware fragments across wearable form factors, sensor modalities, and user sophistication levels. Procurement patterns diverge sharply between consumer wellness channels and clinical diagnostic deployments, forcing manufacturers to architect dual-use certification strategies from product inception.
Product Type:
Form factor selection maps directly to use-case intensity and data fidelity requirements across consumer and medical channels.
- Smartwatch:Dominant margin pool where cellular connectivity consolidates multiple wearable functions into single-device ownership. Hospital systems in the United States and Germany prioritize these for remote patient monitoring programs where ECG-grade data streams justify premium hardware subsidies through prospective reimbursement codes.
- Fitness Band:Volume leader in employer wellness mandates and entry-level consumer segments. Xiaomi Technology compresses unit costs through manufacturing scale, enabling mass distribution across price-sensitive markets in China and India where procurement concentrates on sub-premium hardware.
- Wristband:Specialized form factor targeting dedicated athletic training with extended battery life.
- Chest Strap:Highest electrical signal fidelity for competitive sports and clinical validation studies.
The dominant share belongs to Smartwatch, while Fitness Band is closing the gap fastest.
Technology:
Sensor architecture determines certification pathway complexity and pricing tier placement.
- Optical Sensor:Photoplethysmography dominates shipment volumes through manufacturing simplicity and sub-millimeter packaging advances. Multi-wavelength variants now capture heart rate variability fidelity approaching electrical cardiography, collapsing addressable demand for dedicated Holter monitors in German and US cardiac rehabilitation centers.
- ECG Monitoring:Electrical cardiography commands premium positioning from healthcare channel buyers seeking diagnostic-grade data streams for arrhythmia detection. FDA 510(k) clearance timelines compress development cycles while EU MDR Class IIa reclassification tightens clinical validation burdens, bifurcating hardware architectures between consumer and medical-grade variants.
- Bluetooth:Standard wireless protocol enabling smartphone ecosystem integration.
- NFC:Contactless connectivity supporting payment and access control convergence.
Optical Sensor retains volume leadership, though ECG Monitoring exhibits the steepest expansion trajectory as clinical reimbursement frameworks mature.
End User:
User sophistication stratifies procurement channels and feature prioritization.
- Healthcare Professionals:Demand FDA-cleared or NMPA-registered devices with documented clinical validation for diagnostic workflows. Hospital procurement departments unbundle hardware acquisition from analytics subscriptions, treating cardiac monitoring devices as capital equipment while negotiating separate SaaS contracts for population health dashboards.
- Athletes:GPS-integrated sports performance tracking drives specialized hardware requirements with waterproofing and extended battery specifications.
- Fitness Enthusiasts:Intermediate segment seeking advanced metrics without clinical certification overhead.
- Casual Users:Basic wellness monitoring with minimal technical configuration requirements.
Healthcare Professionals command premium pricing, while Athletes segment is expanding most quickly through specialized sports technology retail channels.
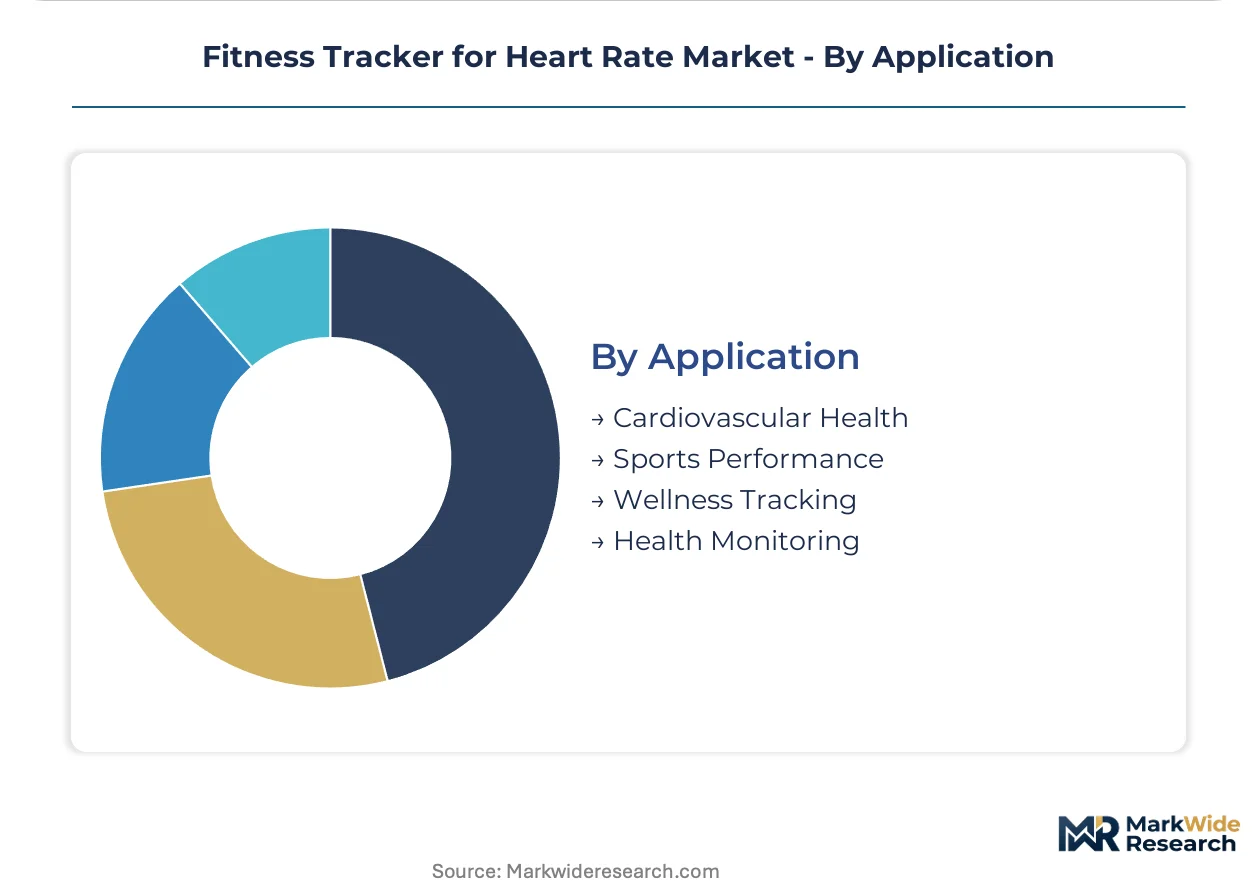
Application:
Functional purpose determines regulatory jurisdiction and reimbursement eligibility.
- Cardiovascular Health:Clinical-grade arrhythmia screening and cardiac load assessment requiring medical device registration. AI-ECG convergence enables on-device atrial fibrillation detection without cloud connectivity, reducing latency for acute event response in hospital system deployments.
- Sports Performance:GPS-integrated training analytics with recovery metrics for competitive athletes. Garmin Ltd. anchors positioning here through specialized hardware and first-party software ecosystems.
- Wellness Tracking:General consumer health awareness without diagnostic claims.
- Health Monitoring:Preventive screening for aging populations in employer wellness programs.
Cardiovascular Health captures highest revenue per unit, while Sports Performance is gaining share fastest through premium hardware attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex anchors Asia-Pacific electronics distribution for wearable biosensors, processing over 25 million TEU annually and enabling rapid component consolidation for heart rate tracker assembly lines.
United States
Employer wellness mandates from Fortune 500 corporations drive B2B procurement of continuous cardiac monitoring devices. FDA 510(k) clearance pathways for ECG-enabled wearables compress product development cycles while tightening clinical validation requirements. The Boston-Cambridge corridor concentrates algorithm development talent for biomedical signal processing.
China
Dual carbon goals accelerate domestic manufacturing incentives for battery and sensor module production. NMPA implements distinct registration pathways for imported versus domestic wearable medical devices, creating variable approval timelines. The Yangtze River Delta hosts precision optical sensor fabrication clusters serving global fitness band supply chains.
Germany
Cardiac rehabilitation centers expand adoption of continuous monitoring devices for post-surgical recovery protocols. EU MDR Class IIa reclassification mandates notified body involvement for clinical validation documentation. Bavaria's medical technology corridor integrates wearable data streams into hospital EHR systems.
India
Production-linked incentive schemes attract assembly capacity for export-oriented fitness band manufacturing. CDSCO regulatory frameworks evolve for wearable medical device classification. Tamil Nadu and Karnataka electronics manufacturing zones scale photoplethysmography module output for Middle Eastern and African distribution.
Japan
Aging demographics accelerate preventive cardiac monitoring procurement through employer and municipal health programs. PMDA consultation pathways guide wearable ECG device classification for home-use diagnostics. The Kanto region concentrates precision component sourcing for sub-millimeter optical sensor packaging.
Fitness Tracker for Heart Rate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from sensor miniaturization and algorithm licensing. The vendor base concentrates around three tiers: premium ecosystem providers with vertical hardware-software control, mid-market scale manufacturers optimizing unit economics, and specialized sports performance boutiques. Strategic archetypes include full-stack platform owners, optical sensor component suppliers, and clinical-grade certification specialists. Dominant competitive moves encompass backward integration into captive sensor production and geographic diversification of final assembly to mitigate tariff exposure.
Within the premium ecosystem tier, Apple Inc. and Samsung Electronics exemplify platform integrators that consolidate cellular connectivity, cardiac metrics, and software services into unified device ownership models. Garmin Ltd. occupies a specialized position in GPS-integrated sports performance segments. Xiaomi Technology represents the scale-driven archetype, compressing manufacturing costs for mass-market fitness band distribution across price-sensitive Asian and emerging markets. These three company types collectively illustrate the strategic divergence between margin capture through ecosystem lock-in versus volume penetration through manufacturing efficiency.
| Leading Market Players |
|---|
| Apple Inc. |
| Garmin Ltd. |
| Google Inc. |
| Samsung Electronics |
| Fitbit Inc. |
| Huawei Technologies |
| Xiaomi Technology |
| Polar Electro |
| WHOOP |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer supply concentration in East Asia exposes manufacturers to geopolitical logistics disruption that determines both pricing tier spreads and supply chain shape, compressing margins in economy fitness bands while premium ECG-enabled wearables absorb input volatility through clinical-grade certification premiums.
Pricing Analysis
Volume-discount tiering structures separate FDA-cleared medical devices from consumer wellness bands, with certification grade and manufacturing scale driving price differentiation between premium smartwatch ecosystems and mass-market fitness bands. Pricing pressure stems from Xiaomi Technology's manufacturing scale compressing unit costs for optical sensor bands, while healthcare procurement departments unbundle hardware from SaaS analytics subscriptions. Employer wellness mandates show lowest price sensitivity, whereas casual consumer segments in India and Southeast Asia exhibit acute cost consciousness.
Supply Chain Analysis
Upstream feedstock for photoplethysmography modules draws from precision optical sensor fabrication clusters in China's Yangtze River Delta, lithium-polymer cell production in South Korea and Japan, and semiconductor packaging in Taiwan. Raw material dependencies center on rare-earth phosphors for LED emitters, CMOS image sensors, and cobalt-nickel battery cathodes. Single-source vulnerability concentrates in sub-millimeter optical sensor packaging, where Japanese component suppliers dominate. Distribution runs through Shenzhen port consolidation for Asia-Pacific assembly, with direct-to-health-system contracting gaining share in US and German hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities exceed hardware growth in this market, with population health analytics subscriptions and remote patient monitoring reimbursement frameworks expanding faster than sensor unit shipments.
For Market Incumbents: Harden regulatory certification portfolios against EU MDR Class IIa reclassification by investing in notified body relationships and post-market surveillance infrastructure. Deepen backward integration into captive optical sensor production to mitigate East Asia battery supply concentration risks. Control hospital procurement channels through EHR integration APIs that lock in SaaS renewal streams. For New Entrants and Emerging Players: India's PLI scheme for wearables offers white-space assembly capacity for export-oriented fitness bands serving Middle Eastern and African markets. CDSCO regulatory frameworks remain less stringent than FDA or NMPA pathways, enabling faster commercialization for non-diagnostic wellness devices. Target cardiac rehabilitation centers in Germany with multi-wavelength photoplethysmography sensors priced at Holter monitor cost fractions. For Investors and Strategic Acquirers: The market sits at a reimbursement-validation phase that favors clinical-grade certification specialists over pure consumer wellness brands. Long-term viability hinges on FDA 510(k) clearance portfolios and CMS CPT code eligibility for ambulatory cardiac data. Watch for AI-ECG convergence enabling on-device arrhythmia detection without cloud connectivity as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | ECG-enabled wearables require FDA clearance for diagnostic claims in US hospital systems. |
| CE Marking Pathway | EU MDR Class IIa reclassification mandates notified body involvement for cardiac monitors. |
| Hospital System Partnership | US health systems unbundle hardware procurement from population health SaaS contracts. |
| Software Companion Development | AI-ECG inference engines enable real-time atrial fibrillation screening without cloud latency. |
| Reimbursement Strategy | CMS evaluation of new CPT codes creates prospective payment streams for remote monitoring. |
Research Methodology
A spread of perspectives from biomedical signal processing engineers, hospital procurement managers, regulatory affairs specialists at wearable device manufacturers, and cardiac rehabilitation clinicians converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) filings, NMPA registration databases, EU MDR notified body documentation, and hospital GPO contract records. Bottom-up shipment estimates triangulated against top-down reimbursement code analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including form factor, sensor modality, certification grade, and end-user sophistication. CAGRs derived from clinician adoption curves for continuous monitoring and employer wellness mandate expansion rates. Forecast inputs incorporated optical sensor miniaturization cost curves and lithium-polymer supply elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or East Asia logistics disruption would shift the trajectory. Forecasts reflect documented assumptions about reimbursement code finalization timelines and regulatory clearance velocity. Material shifts in FDA software-as-medical-device scrutiny intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Swim Watches Market