
 Swim Watches Market | 2026-2036
Swim Watches Market Size, Share, and Industry Trends Forecast 2026-2036
Swim Watches Market Analysis
Sensor miniaturization is fragmenting the swim watch technology stack into modular architectures where GPS, heart rate, and stroke-recognition modules deploy independently. Garmin Ltd. leverages its proprietary satellite chipset ecosystem to dominate open-water tracking accuracy. Apple Inc. sustains ecosystem lock-in through seamless HealthKit integration across pool and open-water modes. COROS Wearables Inc. specializes in extended battery architectures that appeal to ultramarathon swimmers and triathletes.
A swim watch is a wrist-worn instrument engineered with pressure-rated seals, accelerometer arrays, and optical photoplethysmography sensors to quantify stroke count, lap splits, and cardiovascular load during aquatic exercise. Smartwatches capture the dominant margin pool as multi-sport versatility justifies premium pricing, while GPS Watches represent the fastest-expanding category as open-water triathlon participation climbs. Fitness Trackers occupy the volume tier through Xiaomi Corporation and Huawei Technologies, though heart rate monitoring accuracy underwater remains a technical differentiator.
FCC certification governs radio transmission standards for GPS and Bluetooth connectivity in US-bound units, while EU Green Deal battery directives constrain cell chemistry selection and end-of-life recovery obligations for European markets. REACH compliance adds material disclosure burdens on silicone strap and polymer housing suppliers. Stakeholders must monitor evolving water resistance testing protocols and decide whether to absorb certification costs or narrow geographic distribution.
Market Dynamics
Sensor miniaturization is collapsing the traditional integrated watch architecture into modular component ecosystems, forcing manufacturers to choose between proprietary vertical stacks or third-party module integration.
Growth Catalysts
- Triathlon Training Expansion:Endurance sports programs in Australia and coastal California are standardizing GPS-enabled stroke analytics as mandatory equipment for program enrollment.
- EU Green Deal Battery Directives:End-of-life recovery obligations are accelerating closed-loop cell chemistry innovation among European suppliers seeking regulatory pre-approval.
- Open-Water Swimming Culture:Coastal municipalities in Queensland and Western Australia are subsidizing premium unit procurement through public health initiatives targeting cardiovascular intervention.
Market Restraints
- Lithium Supply Concentration:Cell cathode material sourcing depends on concentrated refining capacity in the Democratic Republic of Congo and Chilean lithium triangle, exposing manufacturers to geopolitical supply interruptions.
- Optical Heart Rate Limitations:Photoplethysmography signal degradation underwater remains unresolved for dark-skin pigmentation and high-turbidity environments, constraining addressable demographic penetration.
- REACH Compliance Burden:Silicone strap polymer disclosure requirements impose documentation costs that disproportionately burden sub-scale manufacturers lacking dedicated regulatory affairs functions.
Strategic Opportunities
- India PLI Scheme Alignment:Domestic assembly incentives for wearables are attracting module suppliers to establish Bengaluru and Chennai manufacturing nodes for regional distribution.
- HealthKit Integration Standards:Cross-platform biometric data portability mandates are creating white space for middleware vendors specializing in stroke-recognition algorithm licensing.
- Direct-to-Club Distribution:Triathlon and masters swimming clubs in Sydney and Melbourne are bypassing retail channels through volume procurement contracts with manufacturer field sales teams.
Industry Challenges
- Pressure-Rating Certification Timelines:ISO 22810 water resistance testing protocols require 14-18 week validation cycles that delay product launches and compress effective selling seasons.
- RF Engineering Talent Scarcity:GPS antenna optimization for aquatic environments demands specialized microwave engineering expertise concentrated among defense-sector alumni in San Diego and Adelaide.
- Legacy Pool Infrastructure Integration:Municipal timing systems in older Australian aquatic centers operate on proprietary protocols that resist Bluetooth Low Energy handshake standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swim Watches Market |
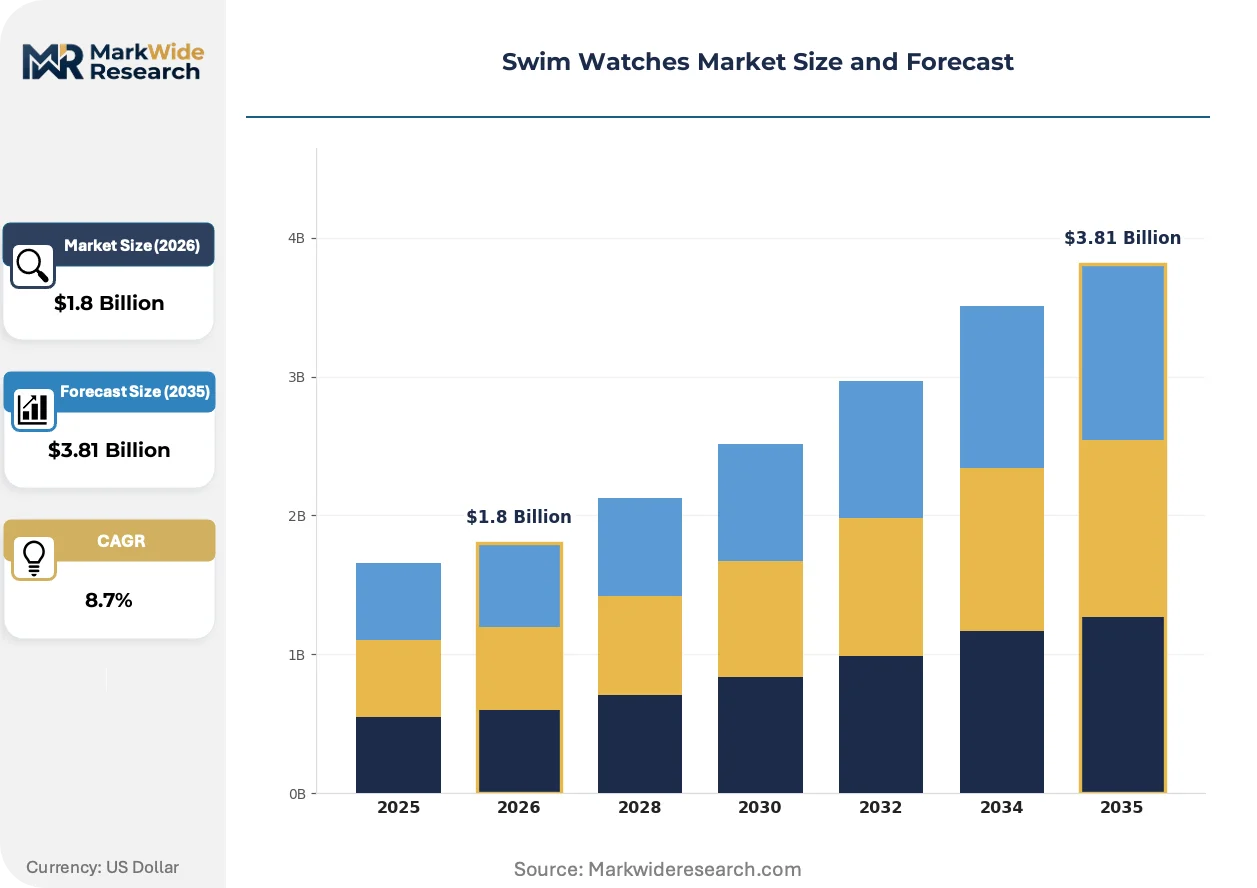
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, GPS Watches, Classic Watches Feature: Water Resistance, Heart Rate Monitoring, Swim Tracking, GPS Navigation End User: Professional Athletes, Casual Swimmers, Coaches, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Stores, Others |
| Companies Covered | Garmin Ltd., Apple Inc., Samsung Electronics, Xiaomi Corporation, Huawei Technologies, Zepp Health Corporation, Polar Electro Oy, COROS Wearables Inc., Suunto Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swim Watches Market Emerging Trajectories
Modular sensor architectures are fragmenting competitive advantage away from integrated hardware design toward algorithmic differentiation and data interoperability standards.
Photoplethysmography array miniaturization is collapsing the optical heart rate module into sub-millimeter form factors that detach from mainboard assemblies. Ultramarathon swimmers and ice-mile specialists in Tasmania and Scotland are adopting these disposable sensor pods for multi-day events. This modularity is collapsing warranty liability structures and enabling subscription-based sensor replacement revenue models.
REACH SVHC candidate list expansions are forcing silicone strap reformulation toward bio-based polysiloxane alternatives. German compounders in Leverkusen and Ludwigshafen are scaling pilot production of sugarcane-derived elastomers that satisfy ECHA disclosure thresholds. Pool chemical resistance testing now dominates material qualification timelines for European-bound units.
Aggregated stroke data monetization is displacing hardware margin as the primary value capture mechanism. Masters swimming leagues in Perth and Gold Coast are licensing anonymized technique datasets to sports science researchers and insurance actuaries. This behavioral pivot concentrates buyer power among data-aggregating platforms and erodes manufacturer direct customer relationships.
Swim Watches Market Segmentation
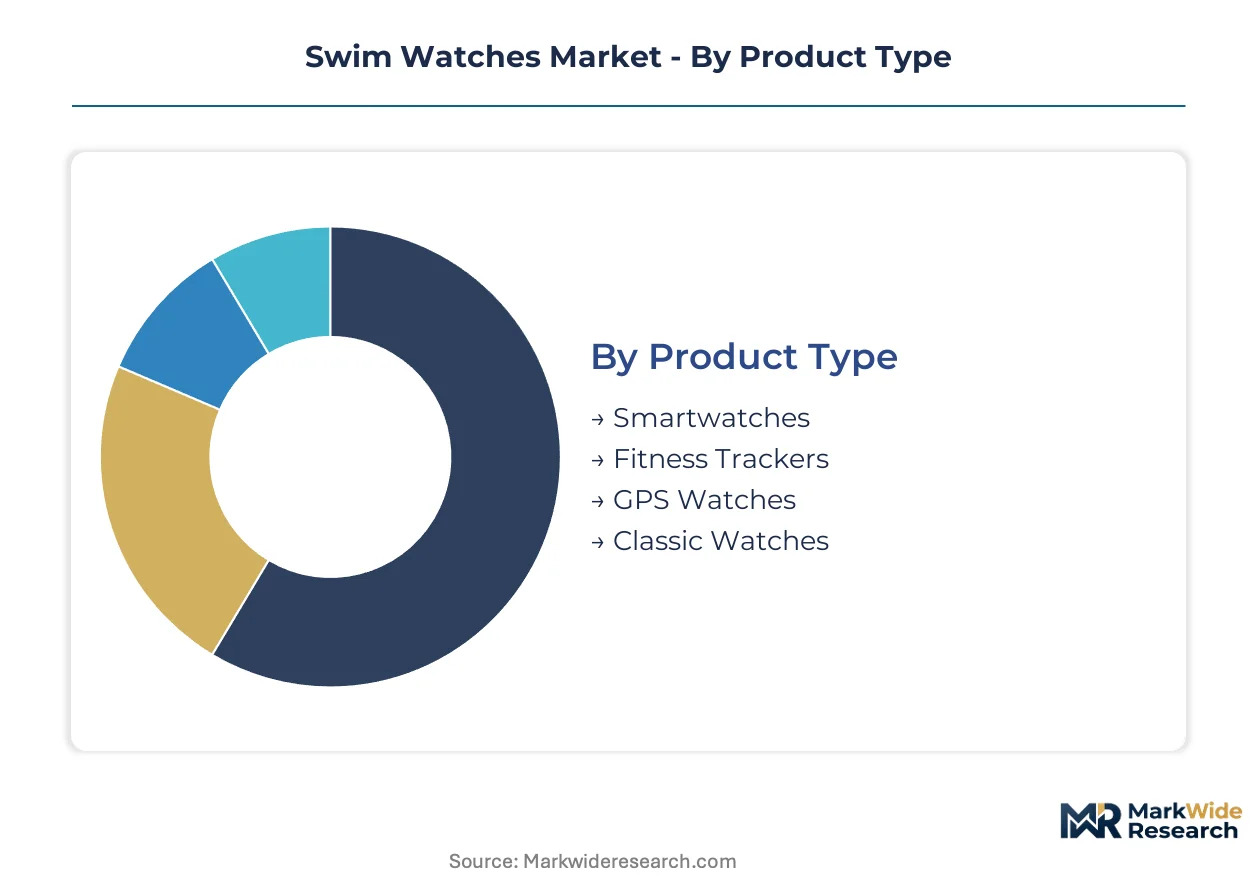
Swim watch procurement patterns diverge sharply between aquatic discipline specialization and multi-sport versatility, forcing manufacturers to calibrate feature bundling against price elasticity curves. Segmentation clarity determines whether vendors capture volume through fitness tracker simplicity or margin through GPS-enabled triathlon precision.
Product Type:
Use-case spectrum spans casual lap counting to open-water navigation, with battery architecture and sensor density defining tier boundaries.
- Smartwatches:Multi-sport wrist computers integrate cellular connectivity, third-party app ecosystems, and contactless payment. Triathlon training programs in Australia and coastal California mandate these units for stroke analytics enrollment, justifying premium positioning through HealthKit interoperability.
- GPS Watches:Dedicated satellite-receiver architectures prioritize open-water tracking accuracy over smart features. Ultramarathon swimmers and ice-mile specialists in Tasmania adopt these for multi-day battery endurance, with procurement concentrated through direct-to-club contracts bypassing retail markup.
- Fitness Trackers:Accelerometer-based units from Xiaomi Corporation and Huawei Technologies dominate volume tiers through sub-$100 positioning. Municipal health initiatives in Queensland subsidize bulk procurement for cardiovascular intervention programs.
- Classic Watches:Analog-digital hybrids with basic lap counters serve masters swimming leagues prioritizing simplicity over data density. Legacy pool infrastructure in older Australian aquatic centers resists Bluetooth handshake protocols, preserving demand for non-connected alternatives.
The dominant share belongs to Smartwatches, while GPS Watches are gaining share fastest through triathlon standardization.
Feature:
Cost tier stratification reflects certification burden and sensor miniaturization investment, with premium features commanding 3-4x entry-level pricing.
- Water Resistance:ISO 22810 pressure-rated seals define baseline market entry, requiring 14-18 week validation cycles that compress selling seasons. Manufacturers absorb certification costs or narrow distribution to avoid timeline risk.
- Heart Rate Monitoring:Photoplethysmography arrays face signal degradation underwater for dark-skin pigmentation and high-turbidity environments, constraining addressable demographic penetration despite clinical demand from cardiac rehabilitation programs.
- Swim Tracking:Stroke-recognition algorithms differentiate through proprietary accelerometer pattern libraries. Middleware vendors license technique datasets to sports science researchers and insurance actuaries, displacing hardware margin as primary value capture.
- GPS Navigation:Proprietary satellite chipset ecosystems from Garmin Ltd. dominate open-water accuracy benchmarks. FCC certification governs US-bound radio transmission standards, while EU Green Deal directives constrain European component sourcing strategies.
Water Resistance anchors baseline procurement, though GPS Navigation carries the steepest expansion trajectory as coastal swimming culture spreads.
End User:
Customer type determines feature prioritization, with professional demands driving modular sensor architectures and casual users accepting integrated simplicity.
- Professional Athletes:Olympic and elite-tier swimmers demand detachable photoplethysmography pods for multi-day events, enabling subscription-based sensor replacement revenue models that collapse traditional warranty structures.
- Casual Swimmers:Lap-counting accuracy and pool chemical resistance dominate purchase criteria. REACH SVHC compliance burdens silicone strap suppliers, forcing bio-based polysiloxane reformulation from German compounders in Leverkusen.
- Coaches:Aggregated stroke data monetization concentrates buyer power among platform vendors licensing anonymized technique datasets to researchers. Direct manufacturer relationships erode as data intermediaries capture value.
- Fitness Enthusiasts:Cross-training versatility justifies premium smartwatch investment. HealthKit integration standards create white space for algorithmic differentiation beyond hardware specifications.
Professional Athletes command highest per-unit spend, while Fitness Enthusiasts represent the broadest volume base.
Distribution Channel:
Channel selection reflects geographic concentration of swimming culture and procurement centralization through institutional buyers.
- Online Retail:Direct-to-consumer platforms capture standard-tier volume through comparison-shopping transparency. Xiaomi Corporation and Huawei Technologies leverage domestic e-commerce dominance in India PLI scheme alignment zones.
- Specialty Stores:Triathlon-focused retailers in Sydney and Melbourne provide fitting services and stroke-analysis demonstrations. Field sales teams bypass these intermediaries through volume procurement contracts with masters swimming clubs.
- Sporting Goods Stores:Mass-market chains stock fitness tracker inventory for seasonal swimming surges. Pool chemical resistance testing extends material qualification timelines for European-bound units.
- Others:Municipal subsidy programs in Queensland and Western Australia distribute premium units through public health channels, circumventing traditional retail entirely.
Online Retail holds volume leadership, though Specialty Stores are expanding fastest through triathlon club procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Triathlon clubs and municipal health programs concentrate procurement power in coastal markets with established open-water swimming cultures. Geographic demand patterns reflect regulatory subsidy alignment and endurance sports infrastructure density rather than population scale.
Australia
Masters swimming leagues in Sydney and Melbourne drive premium smartwatch procurement through direct-to-club contracts bypassing retail channels. TGA medical device classification governs photoplethysmography accuracy claims for cardiac rehabilitation programs. The Gold Coast-Tweed Heads corridor anchors open-water triathlon training density with municipal subsidy programs targeting cardiovascular intervention.
United States
Coastal California endurance programs mandate GPS-enabled stroke analytics for program enrollment, compressing price elasticity for triathlon-focused vendors. FCC certification timelines for satellite chipset integration extend 14-18 weeks, delaying product launches and compressing effective selling seasons. San Diego hosts concentrated RF engineering talent pools drawn from defense-sector alumni specializing in aquatic GPS antenna optimization.
Germany
REACH SVHC disclosure requirements impose silicone strap reformulation costs that burden sub-scale manufacturers lacking dedicated regulatory affairs functions. EU Green Deal battery directives accelerate closed-loop cell chemistry innovation among Leverkusen and Ludwigshafen compounders scaling sugarcane-derived polysiloxane alternatives. Bavarian specialty retailers provide stroke-analysis fitting services for triathlon club procurement centralization.
India
Domestic assembly incentives under the PLI scheme attract module suppliers establishing Bengaluru and Chennai manufacturing nodes for regional distribution. BIS certification for water resistance ratings creates compliance bottlenecks for imported units. Tamil Nadu's electronics manufacturing clusters concentrate fitness tracker volume production for price-sensitive municipal health initiatives.
United Kingdom
HealthKit interoperability mandates from NHS digital health programs create white space for middleware vendors specializing in stroke-recognition algorithm licensing. ECHA disclosure thresholds for pool chemical resistance testing extend material qualification timelines for European-bound units. London-Southeast triathlon clubs aggregate anonymized technique datasets for sports science research licensing.
Swim Watches Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around three strategic archetypes: ecosystem-locked technology conglomerates, precision-focused endurance specialists, and volume-driven component integrators. Dominant competitive moves include strategic partnerships with triathlon federations for equipment standardization and backward integration into proprietary satellite chipset ecosystems.
Within the ecosystem-locked tier, Apple Inc. and Samsung Electronics anchor positions through health platform interoperability mandates. Garmin Ltd. exemplifies the precision-specialist archetype with proprietary GPS architectures. Xiaomi Corporation sits within the volume-integrator tier leveraging domestic manufacturing scale for sub-$100 positioning.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Apple Inc. |
| Samsung Electronics |
| Xiaomi Corporation |
| Huawei Technologies |
| Zepp Health Corporation |
| Polar Electro Oy |
| COROS Wearables Inc. |
| Suunto Oy |
| Others |
Supply Flow & Price Mechanics
Leverkusen's sugarcane-derived polysiloxane compounders anchor European strap material supply, with their pilot-scale capacity constraints transmitting directly into premium-tier pricing power for REACH-compliant configurations. Battery cell chemistry selection under EU Green Deal directives concentrates sourcing leverage among Ludwigshafen suppliers, forcing manufacturers to absorb certification costs or abandon continental distribution.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate cell procurement agreements, with cathode material pass-through clauses protecting European compounders from volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22810-certified GPS units from basic fitness trackers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the fitness tracker tier intensifies because Xiaomi Corporation and Huawei Technologies leverage domestic manufacturing scale. Casual swimmers in Queensland municipal programs exhibit highest price sensitivity; professional athletes purchasing detachable sensor pods show least elasticity.
Supply Chain Analysis
Upstream feedstock for optical photoplethysmography arrays draws from Taiwanese semiconductor foundries and German precision optics clusters, with sensor miniaturization driving sub-millimeter form factor specialization. Lithium refining capacity rests on Chilean salar operations and DRC cobalt processing, creating concentrated geopolitical exposure. Single-source vulnerability in satellite chipset supply from San Diego defense-sector alumni constrains GPS-enabled unit expansion. Distribution runs through direct-to-club contracts in Sydney and Melbourne, bypassing traditional retail markup for triathlon procurement centralization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
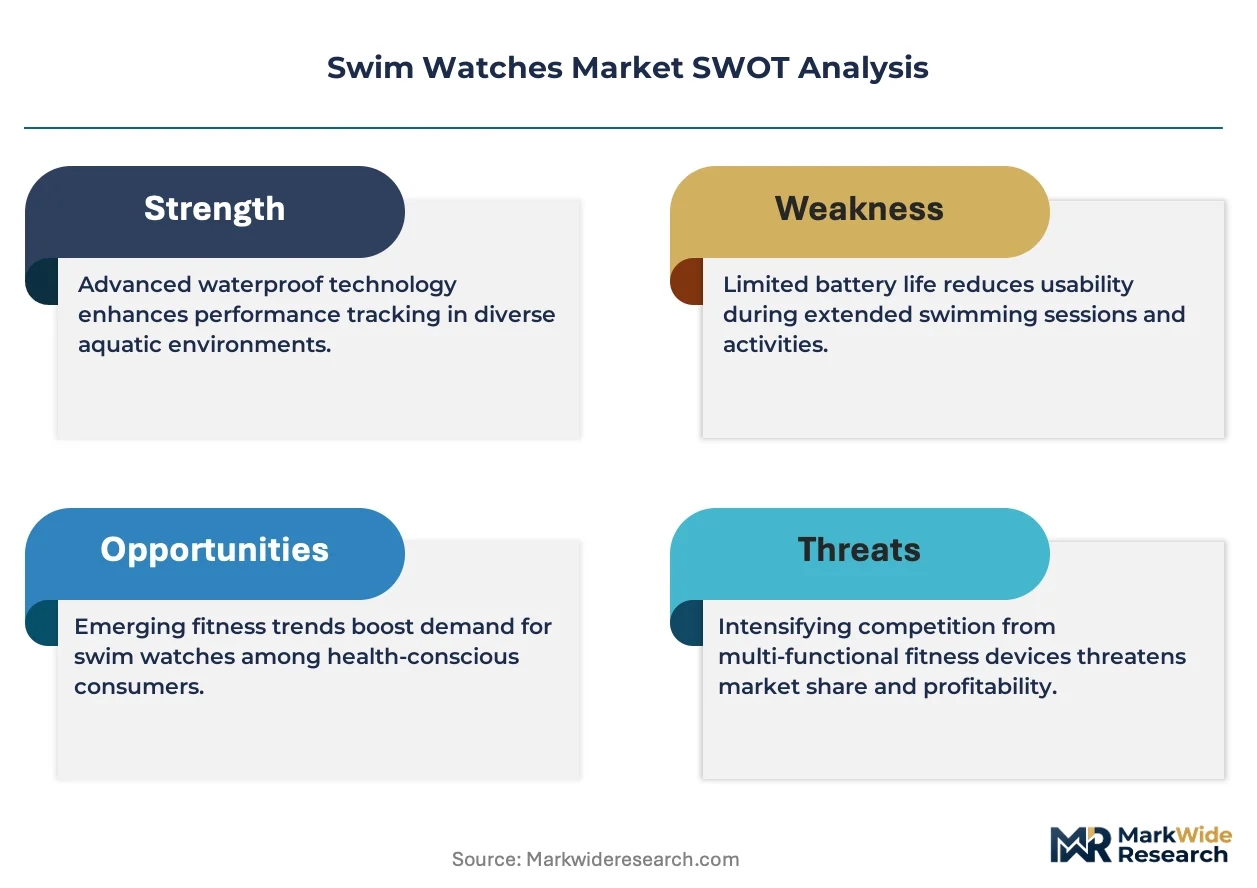
Smartphone-native health platforms pose acute substitution threat to dedicated swim watch hardware, compelling incumbents to defend through data interoperability moats rather than sensor specifications alone.
For Market Incumbents: Pre-empt platform disintermediation by deepening HealthKit integration standards and capturing stroke-recognition algorithm IP through exclusive licensing with Australian masters swimming leagues. Backward integration into proprietary satellite chipset ecosystems, following Garmin Ltd.'s defense of open-water accuracy benchmarks, insulates against RF engineering talent scarcity in San Diego and Adelaide clusters. For New Entrants and Emerging Players: Build out middleware specialization in stroke-recognition algorithm licensing, exploiting white space created by NHS digital health interoperability mandates in the United Kingdom. India's PLI scheme alignment zones offer the most penetrable geography for domestic assembly cost positioning, with Bengaluru module suppliers enabling regional distribution without BIS certification bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a data-aggregation play because anonymized technique dataset monetization displaces hardware margin as primary value capture, concentrating buyer power among platform intermediaries. Acquisition targets should display exclusive triathlon federation partnerships and captive sensor pod replacement revenue streams. Watch for inflection where municipal subsidy programs in Queensland and Western Australia shift from volume procurement to outcomes-based contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Satellite Chipset Development | Garmin Ltd.'s defense of open-water accuracy benchmarks creates insurmountable tracking precision gaps for module-integrating competitors. |
| HealthKit Integration Deepening | Apple Inc.'s ecosystem lock-in through seamless biometric data portability raises switching costs for triathlon program enrollment. |
| Direct-to-Club Distribution Bypass | Sydney and Melbourne field sales teams capture volume procurement contracts, eroding specialty retailer margin capture. |
| Disposable Sensor Pod Subscription | Ultramarathon swimmers in Tasmania adopt replacement revenue models that collapse traditional warranty liability structures. |
| REACH-Compliant Bio-Based Reformulation | German compounders in Leverkusen scale sugarcane-derived polysiloxane to satisfy ECHA disclosure thresholds for European-bound units. |
Methodological Framework
The analysis maps smartwatch, GPS watch, fitness tracker, and classic watch sub-sectors, each validated through triathlon club procurement officers, municipal health program administrators, RF engineering specialists, and silicone strap compounders. Primary interviews with these stakeholders combined with secondary validation against FCC certification filings, ECHA SVHC candidate list updates, TGA medical device classifications, and Australian municipal subsidy program disclosures. Bottom-up unit shipment estimates triangulated against top-down expenditure flows from endurance sports program budgets.
Assumptions held fixed include EU Green Deal battery directive compliance timelines and ISO 22810 water resistance testing protocol durations; varied assumptions spanned lithium supply disruption scenarios and HealthKit interoperability mandate adoption rates. The projection horizon spans product type, feature tier, end user category, and distribution channel dimensions, with CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated triathlon program standardization velocity and optical heart rate accuracy improvement curves for dark-skin pigmentation environments.
Stress conditions across lithium carbonate price volatility, REACH SVHC list expansion timing, and RF engineering talent migration patterns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers including sudden geopolitical supply interruptions or breakthrough photoplethysmography signal processing advances. Cross-checking against Australian Bureau of Statistics participation data in organized endurance sports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Wearable Band Market