
 United States Wearable Sensors Market | 2026-2036
United States Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wearable Sensors Market Analytics
The biomedical engineering talent pool is rotating toward software-defined sensor architectures, tightening supply of hardware-focused analog designers. Texas Instruments Incorporated anchors domestic fabrication of ultra-low-power analog front-ends for photoplethysmography. Analog Devices, Inc. competes through precision inertial measurement units optimized for fall-detection algorithms. Apple Inc. dominates consumer-grade health monitoring through proprietary optical sensor stacks integrated with its wearable ecosystem.
United States wearable sensors are electromechanical transducers, typically incorporating MEMS accelerometers, optical emitters at green and infrared wavelengths, and skin-conductance electrodes within hermetic polymer packages rated for IP68 submersion. These devices convert physiological and kinematic signals into digital data streams for real-time health assessment and longitudinal biometric trending. Smartwatches command the largest product-type revenue pool, while health monitors capture the fastest expansion as Medicare reimbursement codes expand for remote therapeutic monitoring. Bluetooth technology leads connectivity shipments, though NFC is gaining share in clinical settings where paired device authentication matters.
FDA Class II 510(k) clearances shape product development timelines and clinical claims for heart-rate variability and blood-oxygen saturation features. FCC Part 15 rules govern radio-frequency emissions from Wi-Fi and GPS-enabled wearables, constraining antenna design and battery placement. Stakeholders must monitor whether CMS expands reimbursable CPT codes for continuous glucose monitoring and arrhythmia detection, as this determines the addressable clinical market versus pure consumer retail.
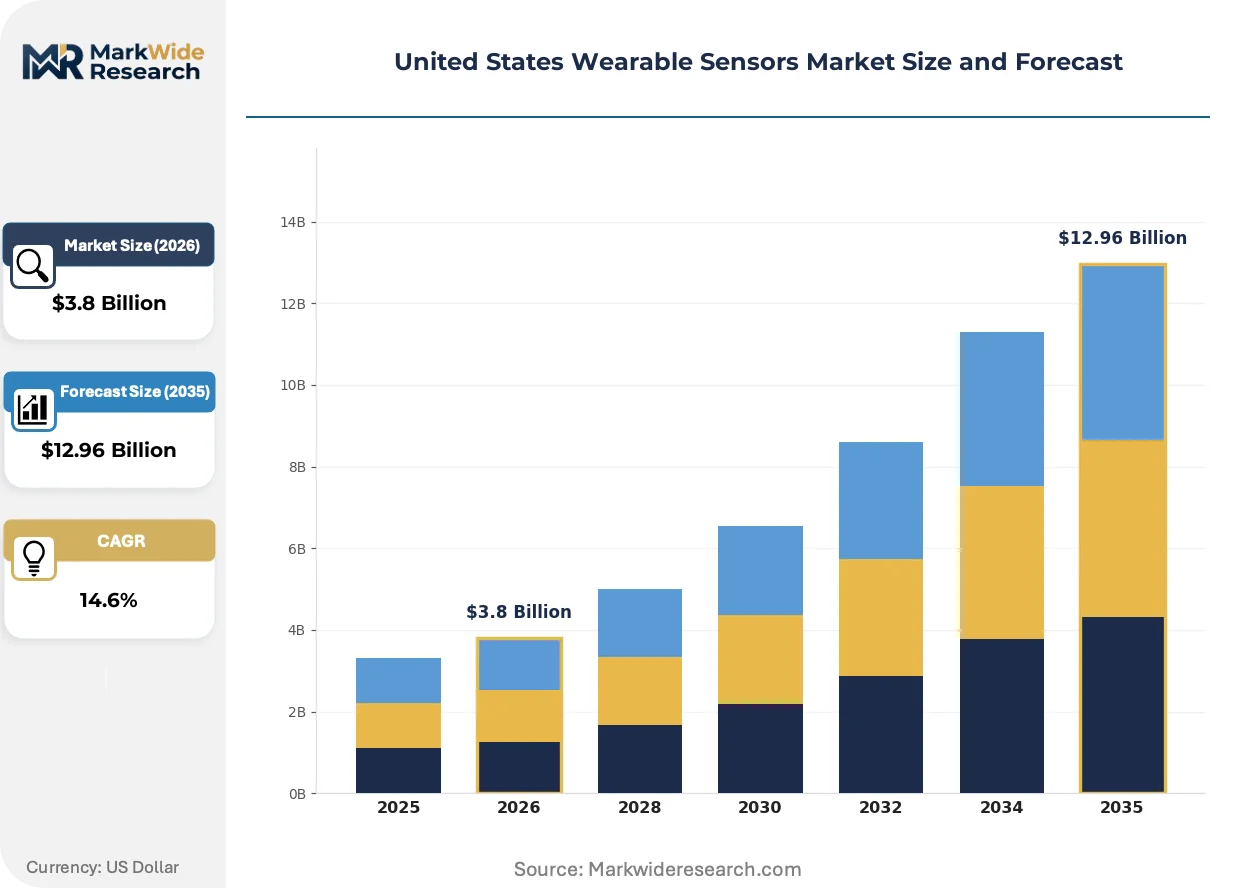
Market Dynamics
Medicare reimbursement expansion for remote therapeutic monitoring codes is pulling clinical-grade wearables from consumer retail into reimbursable care pathways, restructuring how vendors position sensor accuracy claims and FDA clearance strategies.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined Class II clearances for photoplethysmography-based arrhythmia detection are compressing time-to-clinical-market from 18 months to under 12 months for qualified submissions.
- CMS CPT Code Expansion:New reimbursable categories for continuous glucose monitoring and blood pressure remote monitoring are converting out-of-pocket consumer purchases into billable clinical services.
- Silicon Valley Biomedical Talent Migration:Software-defined sensor architecture expertise is concentrating in California's Bay Area, creating dense ecosystems for rapid prototyping of multi-modal health monitors.
Market Restraints
- Analog Design Talent Scarcity:Domestic universities are graduating fewer hardware-focused analog circuit designers as curricula pivot toward digital signal processing and machine learning.
- MEMS Foundry Concentration:Domestic fabrication of ultra-low-power accelerometers relies on a limited number of specialized foundries, creating single-source vulnerability for high-volume wearable contracts.
- Battery Energy Density Plateau:Lithium-polymer cell chemistry improvements have slowed, constraining multi-day continuous monitoring without device bulk increases that compromise wearability.
Strategic Opportunities
- Texas Medical Center Integration:Houston's hospital networks are piloting direct-to-clinic sensor provisioning models that bypass traditional retail distribution.
- AI-Edge Convergence:On-device machine learning inference is enabling real-time anomaly detection without cloud latency, opening continuous cardiac monitoring applications previously restricted to Holter patches.
- NFC Clinical Authentication:Near-field pairing protocols are penetrating hospital systems where paired-device identity verification reduces data integrity risks in multi-patient wards.
Industry Challenges
- FDA Quality System Regulation Compliance:Design history file documentation requirements for Class II submissions demand specialized regulatory affairs personnel that smaller sensor vendors struggle to recruit.
- Multi-Sensor Fusion Calibration:Synchronizing optical, inertial, and bioimpedance signals within tight power budgets requires rare cross-functional expertise spanning photonics, MEMS, and analog design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wearable Sensors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors Technology: Bluetooth, NFC, Wi-Fi, GPS End User: Healthcare Providers, Fitness Enthusiasts, Elderly Users, Athletes Application: Health Monitoring, Fitness Tracking, Sleep Analysis, Stress Management |
| Companies Covered | Panasonic Corporation, Apple Inc., STMicroelectronics, Garmin Ltd., Samsung Electronics, Infineon Technologies AG, Texas Instruments Incorporated, Fitbit Inc., Analog Devices, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wearable Sensors Market Evolving Landscape
Sensor architectures are fragmenting into modular subsystems that separate optical front-ends from digital processing, enabling faster iteration cycles and specialized vendor ecosystems.
Photoplethysmography is decomposing into discrete emitter-detector modules and separate analog-to-digital converter chips. Wearable OEMs in the fitness tracker segment are adopting these disaggregated components to customize wavelength combinations for specific biomarkers. This decomposition is compressing hardware development cycles from 24 months to 14 months while expanding the supplier base beyond integrated stack providers.
FDA's evolving enforcement discretion policy for general wellness devices versus regulated medical devices is creating clearer guardrails for marketing claims. Manufacturers are recalibrating promotional language to avoid 510(k) triggers while preserving clinical credibility. The heart-rate variability feature category is most affected, with vendors removing diagnostic terminology from consumer packaging while maintaining identical hardware specifications.
Hospital procurement departments are consolidating wearable sensor purchasing through group purchasing organizations, displacing individual clinic purchasing autonomy. Cardiology departments within integrated delivery networks are standardizing on single-vendor remote monitoring platforms to simplify EHR integration. This concentration is most visible in the Midwest, where Catholic health systems and academic medical centers dominate regional market formation.
United States Wearable Sensors Market Segmentation
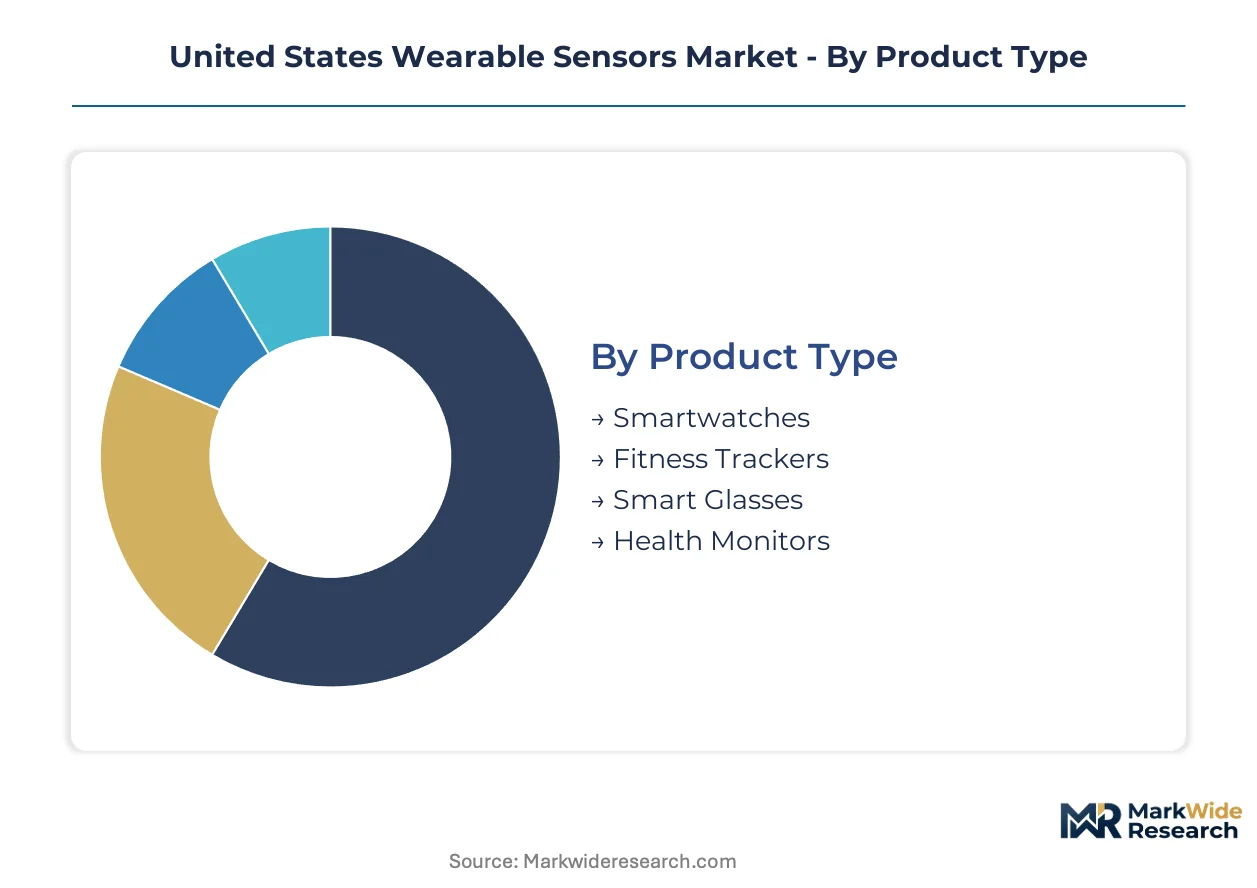
Segmentation reveals how FDA reimbursement pathways and consumer retail channels are diverging hardware specifications and pricing architectures across the United States wearable sensors landscape. Each dimension carries distinct regulatory exposure and margin profiles that reshape vendor positioning strategies.
Product Type:
Smartwatches face intensifying substitution pressure from dedicated health monitors as Medicare reimbursement codes expand, forcing feature convergence or clinical-grade certification pivots.
- Smartwatches:Multi-modal sensor arrays integrate photoplethysmography, MEMS accelerometry, and skin-temperature sensing within sealed polymer housings rated for continuous wrist-wear. Demand concentrates in California's consumer electronics retail channels and employer wellness program procurement, constrained by battery energy density plateaus that limit multi-day cardiac monitoring without daily charging cycles.
- Health Monitors:FDA Class II 510(k)-cleared devices prioritize arrhythmia detection accuracy and clinical data integrity over consumer aesthetics. Texas Medical Center pilot programs and Medicare Advantage plan provisioning are pulling these devices from direct-to-consumer retail into reimbursable care pathways, restructuring vendor go-to-market investments toward regulatory affairs and hospital procurement relationships.
- Fitness Trackers:Simplified optical heart-rate modules and step-counting accelerometers target gym-chain partnerships and corporate wellness subsidies.
- Smart Glasses:Optical waveguide displays with integrated gaze-tracking sensors serve industrial field-service applications and specialized healthcare training scenarios.
Smartwatches retain volume leadership; health monitors hold the steepest expansion curve.
Technology:
Connectivity choices segment by power budget constraints and clinical authentication requirements, with hospital procurement departments prioritizing paired-device identity verification protocols.
- Bluetooth:Low-energy 5.3 protocols dominate consumer shipment volumes, enabling sub-milliwatt continuous data streaming to paired smartphones. Fitness tracker OEMs in Silicon Valley specify Nordic Semiconductor and Texas Instruments radio stacks, though FCC Part 15 antenna placement rules constrain industrial design flexibility and battery positioning.
- NFC:Near-field pairing protocols penetrate Midwest integrated delivery networks where Catholic health systems and academic medical centers mandate device authentication before EHR data transmission. The 13.56 MHz frequency band supports encrypted patient identity verification without cloud latency, reducing data integrity risks in multi-patient cardiology wards.
- Wi-Fi:Direct-to-router connectivity enables standalone health monitors that bypass smartphone intermediaries for elderly user segments with limited mobile device adoption.
- GPS:Multi-constellation positioning supports outdoor athlete performance analytics and emergency response location services for elderly fall-detection applications.
Bluetooth dominates shipment volumes; NFC gains share fastest in clinical authentication deployments.
End User:
Customer type segmentation tracks reimbursement eligibility and out-of-pocket price sensitivity, with healthcare provider procurement consolidating through group purchasing organizations.
- Healthcare Providers:Cardiology departments within integrated delivery networks standardize on single-vendor remote monitoring platforms to simplify Epic and Cerner EHR integration. FDA Quality System Regulation compliance demands specialized design history file documentation that smaller sensor vendors struggle to staff, concentrating contract awards on established Class II clearance holders.
- Elderly Users:Medicare reimbursement expansion for remote therapeutic monitoring codes converts continuous glucose monitoring and blood pressure tracking from retail purchases into billable clinical services. Fall-detection algorithm accuracy and one-touch emergency response activation drive purchasing decisions for adult children selecting devices for aging parents.
- Fitness Enthusiasts:Gym subscription bundles and employer wellness incentives subsidize device acquisition, with churn risk concentrated in January-March subscription renewal cycles.
- Athletes:VO2 max estimation and recovery metrics from optical heart-rate variability support training load optimization for amateur endurance competitors.
Healthcare providers command the highest average selling prices; elderly users represent the fastest volume expansion as CMS coding expands.
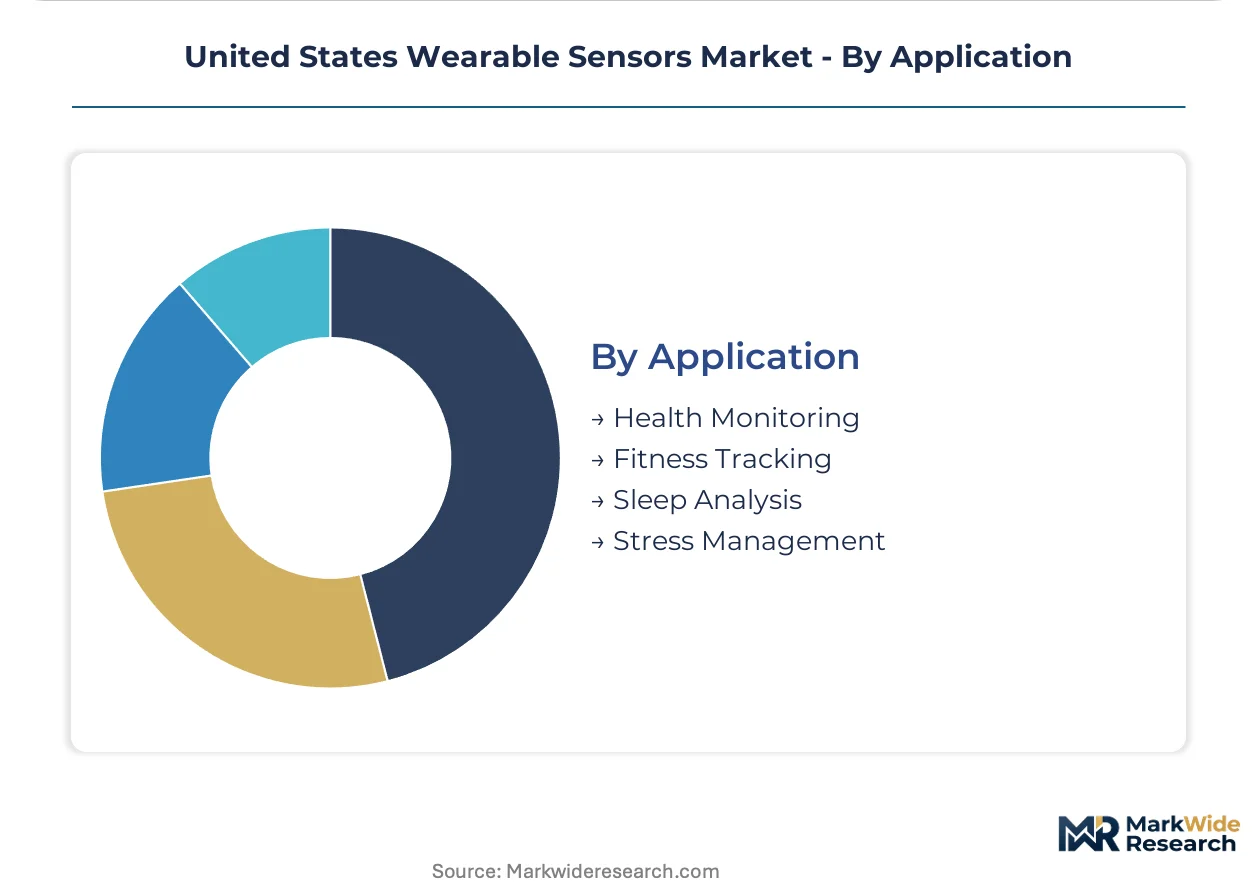
Application:
Use-case segmentation determines sensor fusion complexity and regulatory classification, with diagnostic claim language triggering FDA 510(k) submission requirements.
- Health Monitoring:Multi-sensor fusion of optical, inertial, and bioimpedance signals enables real-time cardiac anomaly detection without cloud latency. On-device machine learning inference at the edge opens continuous monitoring applications previously restricted to prescription Holter patches, though synchronizing signal streams within tight power budgets demands rare cross-functional expertise spanning photonics, MEMS, and analog design.
- Fitness Tracking:Simplified step counting and calorie estimation algorithms face commoditization pressure from smartphone-native accelerometry, forcing wearable OEMs to differentiate through social platform integration and coaching subscription services.
- Sleep Analysis:Photoplethysmography-derived SpO2 and heart-rate variability metrics support apnea screening claims that skirt FDA enforcement discretion boundaries for general wellness devices.
- Stress Management:Galvanic skin response electrodes and guided breathing biofeedback target corporate wellness program procurement and mindfulness application partnerships.
Health monitoring captures premium pricing tiers; fitness tracking faces the steepest substitution pressure from smartphone sensors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Silicon Valley and Texas Medical Center deploy wearable sensors for fundamentally different use cases than retail consumers elsewhere, with clinical reimbursement pathways pulling hardware toward FDA-regulated specifications rather than consumer aesthetics.
California
Silicon Valley biomedical engineering talent concentrates in software-defined sensor architectures, tightening supply of hardware-focused analog designers. FDA 510(k) clearance pathways for Class II medical devices accelerate through Palo Alto regulatory consulting clusters. Apple Inc. anchors proprietary optical sensor stacks in Cupertino, dominating consumer-grade health monitoring through integrated wearable ecosystems.
Texas
Houston's hospital networks pilot direct-to-clinic sensor provisioning models that bypass traditional retail distribution entirely. Medicare reimbursement expansion for remote therapeutic monitoring codes converts continuous glucose monitoring into billable clinical services across Texas Medical Center cardiology departments. Dallas-Fort Worth MEMS foundry capacity supports ultra-low-power accelerometer fabrication for high-volume wearable contracts.
Massachusetts
Greater Boston's academic medical centers standardize on single-vendor remote monitoring platforms to simplify Epic EHR integration. FDA Quality System Regulation compliance demands specialized design history file documentation that concentrates contract awards on established Class II clearance holders. Cambridge analog design expertise supports precision inertial measurement units optimized for fall-detection algorithms.
Minnesota
Midwest integrated delivery networks consolidate wearable sensor purchasing through group purchasing organizations, displacing individual clinic purchasing autonomy. Catholic health systems mandate NFC device authentication before EHR data transmission in multi-patient cardiology wards. Minneapolis-Saint Paul procurement departments prioritize paired-device identity verification protocols for hospital system deployments.
North Carolina
Research Triangle Park anchors clinical trial infrastructure for photoplethysmography-based arrhythmia detection validation. Medicare Advantage plan provisioning pulls FDA-cleared health monitors from direct-to-consumer retail into reimbursable care pathways. Durham regulatory affairs specialists compress 510(k) submission timelines from 18 months to under 12 months for qualified submissions.
United States Wearable Sensors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consumer electronics conglomerates and precision analog semiconductor fabricators occupying distinct competitive vectors. The upper tier commands proprietary optical sensor stacks and MEMS fabrication capacity, while mid-tier specialists concentrate on discrete emitter-detector modules and analog-to-digital converter chips. Two strategic archetypes dominate: vertically integrated wearable OEMs with captive health ecosystems, and component suppliers licensing sensor architectures across multiple device categories. Competitive moves center on FDA clearance portfolio expansion and hospital procurement relationship cultivation.
Among integrated consumer technology leaders, Apple Inc. exemplifies the ecosystem-anchored archetype through proprietary hardware-software integration. Texas Instruments Incorporated and Analog Devices, Inc. occupy positions within the precision analog semiconductor tier, supplying ultra-low-power front-ends and inertial measurement units to wearable OEMs across multiple end-use segments. These three represent distinct competitive vectors: captive ecosystem control, discrete component supply, and multi-modal sensor fusion expertise.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Apple Inc. |
| STMicroelectronics |
| Garmin Ltd. |
| Samsung Electronics |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Fitbit Inc. |
| Analog Devices, Inc. |
| Others |
Value Network & Pricing Analysis
MEMS foundry utilization rates above 85% in Texas and California concentrate bargaining power among analog semiconductor fabricators serving FDA-cleared wearable OEMs, establishing price floors that resist commoditization despite consumer-tier sensor erosion. Scale advantages in photoplethysmography front-end production entrench tiered pricing architectures that separate clinical-grade reimbursement-eligible devices from retail fitness trackers.
Pricing Analysis
Long-term offtake contracts between hospital procurement departments and Class II 510(k) clearance holders dominate clinical-grade sensor pricing, insulating premium tiers from spot-market volatility in consumer retail. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA certification status and EHR integration depth, with Medicare reimbursement eligibility commanding substantial premiums over out-of-pocket fitness devices. Cost compression in consumer-grade optical modules intensifies as smartphone-native accelerometry substitutes basic step-counting wearables. Employer wellness programs exhibit highest price sensitivity, while integrated delivery networks prioritize clinical data integrity over per-unit procurement costs.
Supply Chain Analysis
Strait of Malacca transit vulnerability for lithium-polymer cell shipments from South Korean and Japanese battery suppliers creates chokepoint exposure for multi-day continuous monitoring devices. Taiwan and South Korea anchor wafer fabrication for ultra-low-power analog-to-digital converters, while domestic Texas and California foundries handle MEMS accelerometer integration. Indium gallium arsenide photodetectors and hermetic polymer packaging materials draw from Japanese and German specialty chemical suppliers. Single-source vulnerability concentrates in FDA-qualified cleanroom assembly facilities. Distribution runs through group purchasing organizations for hospital deployments and direct-to-consumer e-commerce for retail fitness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA Quality System Regulation compliance creates defensive moats that concentrate contract awards on established clearance holders, with switching costs locking hospital procurement into validated remote monitoring platforms.
For Market Incumbents: Shield market position by deepening captive supply of photoplethysmography optical stacks through backward integration into emitter-detector module fabrication, neutralizing emerging fabless sensor vendors. Expand capacity addition in Texas MEMS foundry corridors to secure high-volume wearable contracts against analog design talent scarcity. Prioritize hospital procurement relationship cultivation through dedicated regulatory affairs staffing that smaller competitors cannot replicate. For New Entrants and Emerging Players: FDA 510(k) streamlined review pathways for qualified photoplethysmography submissions offer fastest market entry for arrhythmia detection claims, compressing regulatory timelines versus de novo classification routes. Medicare Advantage plan provisioning in Texas Medical Center and Research Triangle Park pilot zones represents most penetrable geography for direct-to-clinic bypass of retail distribution. Pursue white-label partnerships with established Class II clearance holders to access hospital procurement channels without full QSR infrastructure investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wearable OEMs with FDA-cleared health monitors embedded in Medicare reimbursement codes, generating predictable cash flows from hospital system contracts rather than discretionary consumer purchases. Acquisition target archetype: mid-tier specialists with discrete analog-to-digital converter chip portfolios and existing 510(k) clearances for multi-sensor fusion devices. Watch CMS CPT code expansion for continuous glucose monitoring and blood pressure remote monitoring as inflection signal for clinical market addressability versus pure consumer retail.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined Class II clearances compress time-to-clinical-market for photoplethysmography-based arrhythmia detection. |
| Hospital System Partnership | Direct-to-clinic provisioning models through Texas Medical Center bypass traditional retail distribution entirely. |
| Software Companion Development | Epic and Cerner EHR integration requirements drive standardization on single-vendor remote monitoring platforms. |
| Reimbursement Strategy | CMS CPT code expansion converts out-of-pocket consumer purchases into billable clinical services for elderly users. |
| Backward Integration into Optical Modules | Captive supply of emitter-detector components secures margin position against fabless competitor encroachment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, and hospital procurement contract disclosures. Primary interviews engaged biomedical engineering directors, hospital GPO contracts managers, FDA regulatory affairs specialists, and MEMS foundry operations executives. Secondary validation drew from FCC Part 15 equipment authorization records, SEC 10-K filings of analog semiconductor suppliers, and integrated delivery network standardization announcements. Bottom-up shipment estimates from component suppliers triangulate against top-down reimbursement code utilization data.
Segmentation dimensions modeled span product type, connectivity technology, end user archetype, and application across the analysis window. Analytical framework derives CAGRs from Medicare reimbursement expansion trajectories, FDA clearance pipeline velocity, and analog design talent supply constraints. Forecast inputs incorporate MEMS foundry capacity utilization trends and hospital procurement consolidation patterns through group purchasing organizations.
The analysis sits within stated boundaries; outcomes outside sustained CMS coding expansion or FDA enforcement discretion stability would require recalibration. Forecasts reflect assumptions regarding Medicare Advantage plan adoption rates and clinical-grade sensor accuracy validation timelines. Practitioners should keep alternative scenarios live as reimbursement policy and analog semiconductor capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Sports Technology Market