
 Global Smart Wearable Fitness and Sports Devices Market | 2026-2036
Global Smart Wearable Fitness and Sports Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Wearable Fitness and Sports Devices Market Outlook
The EU Green Deal is hardening battery sustainability requirements for consumer electronics, forcing manufacturers to redesign power architectures and supply chains. Apple sustains premium positioning through proprietary silicon integration and health ecosystem lock-in. Garmin Ltd. dominates aviation-grade GPS heritage translated into multisport watch precision. Xiaomi Corporation leverages vertical manufacturing scale to compress price points in emerging markets.
Smart wearable fitness and sports devices integrate microelectromechanical sensors, photoplethysmography optical engines, and low-energy wireless chipsets into wrist-worn or body-mounted form factors for continuous physiological monitoring and activity quantification. Fitness Trackers anchor volume shipments through stripped-down feature sets targeting price-sensitive Health-Conscious Consumers, while Smartwatches capture margin pools via app ecosystem monetization and clinical-grade sensor arrays. Sensor Technology represents the fastest-advancing dimension, with SpO2 and body temperature modules migrating from premium tiers toward mid-range hardware.
FDA clearance pathways for atrial fibrillation detection and ECG functionality shape product roadmaps for US-bound devices, while EU MDR and REACH compliance govern battery chemistry disclosures and biocompatibility testing for European market access. China's NMPA and GB standards mandate electromagnetic compatibility certification and data localization for connected health peripherals. Stakeholders must monitor whether clinical validation requirements expand beyond cardiovascular indicators into metabolic and respiratory biomarkers.
Market Dynamics
Sensor module production concentrates in China's Guangdong manufacturing cluster, creating supply-side leverage that ripples through pricing architecture and R&D cadence for wrist-worn physiological monitors.
Growth Catalysts
- EU Green Deal battery mandates:Sustainability disclosure requirements for consumer electronics are accelerating circular design investments and recycled material sourcing across power architecture engineering.
- Enterprise wellness subsidies:Fortune 500 employers are expanding device reimbursement programs, converting employee health benefits into predictable B2B procurement channels for fitness tracker OEMs.
- Photoplethysmography optical engines:Continuous SpO2 and heart rate monitoring capabilities are migrating from premium hardware tiers toward mid-range fitness bands, democratizing clinical-grade biomarker access.
Market Restraints
- Lithium-polymer cell volatility:Cobalt and lithium carbonate spot price swings compress hardware margins and complicate long-term cost forecasting for battery-dependent form factors.
- Guangdong sensor concentration:Microelectromechanical systems fabrication clusters in Shenzhen and Dongguan create single-point-of-failure exposure for global module supply.
- FDA 510(k) pathway duration:Cardiovascular algorithm validation timelines for atrial fibrillation detection extend product launch windows by 18-24 months versus consumer-grade feature releases.
Strategic Opportunities
- India PLI scheme incentives:Production-linked subsidies for electronics manufacturing are attracting assembly capacity shifts from coastal China to Noida and Sri City corridors.
- Remote patient monitoring convergence:Post-acute care reimbursement codes for continuous physiological surveillance are creating clinical trial partnerships between wearable OEMs and hospital systems.
- Direct-to-consumer subscription services:Fitness content and coaching bundles are displacing retail margin capture with recurring revenue streams attached to hardware ecosystems.
Industry Challenges
- Biocompatibility testing backlog:EU MDR skin contact material certification queues are delaying European market entry for new elastomer and adhesive formulations.
- RF antenna integration complexity:Multiband cellular and satellite positioning coexistence in compact wrist-worn enclosures demands specialized electromagnetic simulation talent that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Wearable Fitness and Sports Devices Market |
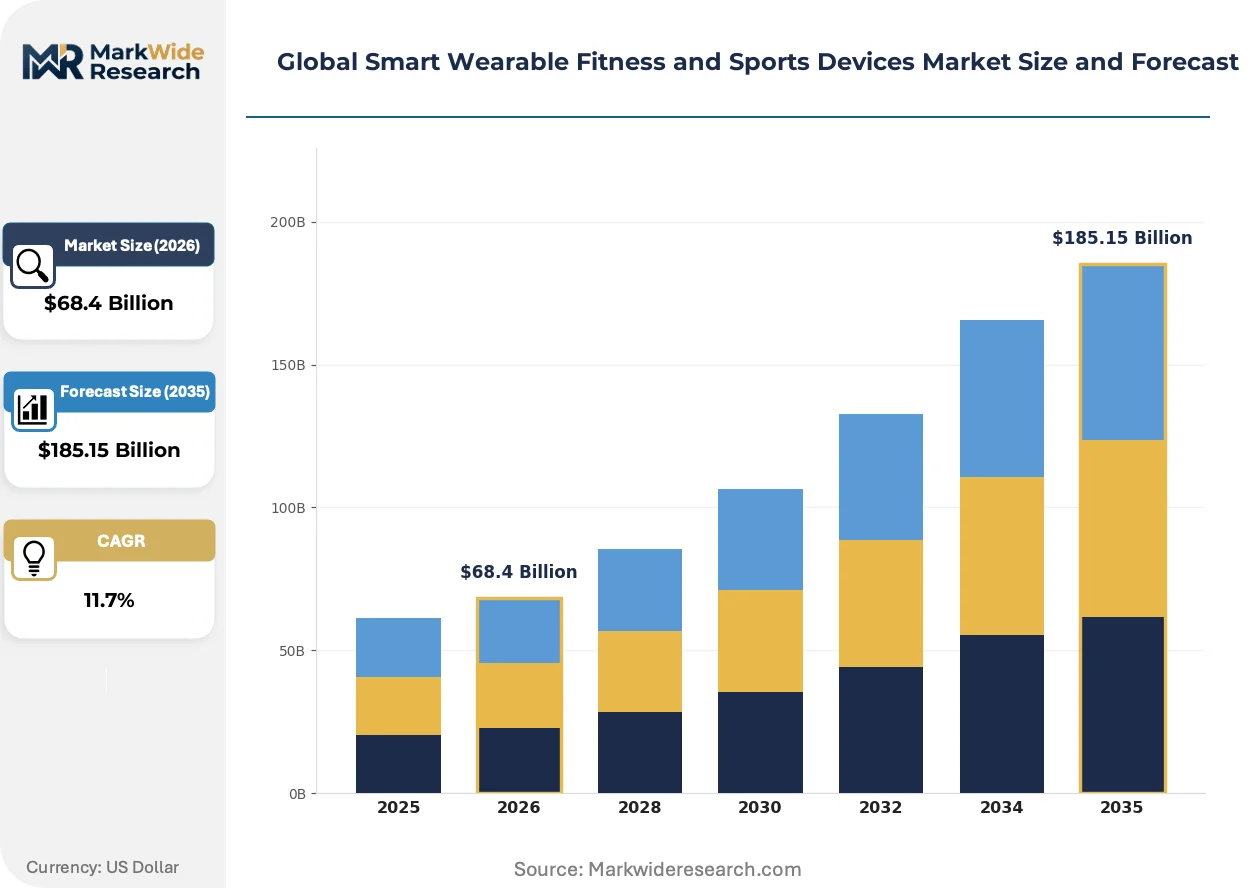
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors Technology: Bluetooth, NFC, Wi-Fi, Sensor Technology End User: Athletes, Fitness Enthusiasts, Casual Users, Health-Conscious Consumers Application: Health Monitoring, Activity Tracking, Performance Analysis, Sleep Tracking |
| Companies Covered | Garmin Ltd., Xiaomi Corporation, Apple, Polar Electro, Amazfit, Samsung Electronics, Huawei Technologies, Whoop, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Wearable Fitness and Sports Devices Market Strategic Shifts
Clinical-grade sensor arrays are migrating downmarket while regulatory frameworks harden around battery chemistry and data governance, compressing product development cycles and reshaping competitive differentiation vectors.
Photoplethysmography with multi-wavelength LED arrays is expanding into core temperature estimation and hydration status inference. Marathon training programs and high-altitude expedition operators are adopting these modules faster than general fitness demographics. The technology is expanding into premium smartwatch positioning while forcing mid-tier vendors to accelerate optical engine refresh cycles.
EU MDR biocompatibility testing and REACH substance disclosure mandates are hardening material selection protocols for skin-contact wearables. Manufacturers must now document full chemical composition of elastomer bands and adhesive substrates before CE marking approval. European-bound product lines are responding with accelerated substitution of phthalate-laden polymers for bio-based thermoplastic alternatives.
Employer-sponsored wellness procurement is displacing individual retail purchase as the dominant volume channel for fitness tracker shipments. Benefits administrators at self-insured corporations are consolidating vendor selection through centralized RFP processes. This pattern is most visible in United States metropolitan markets where healthcare cost containment drives biometric surveillance adoption.
Global Smart Wearable Fitness and Sports Devices Market Segmentation
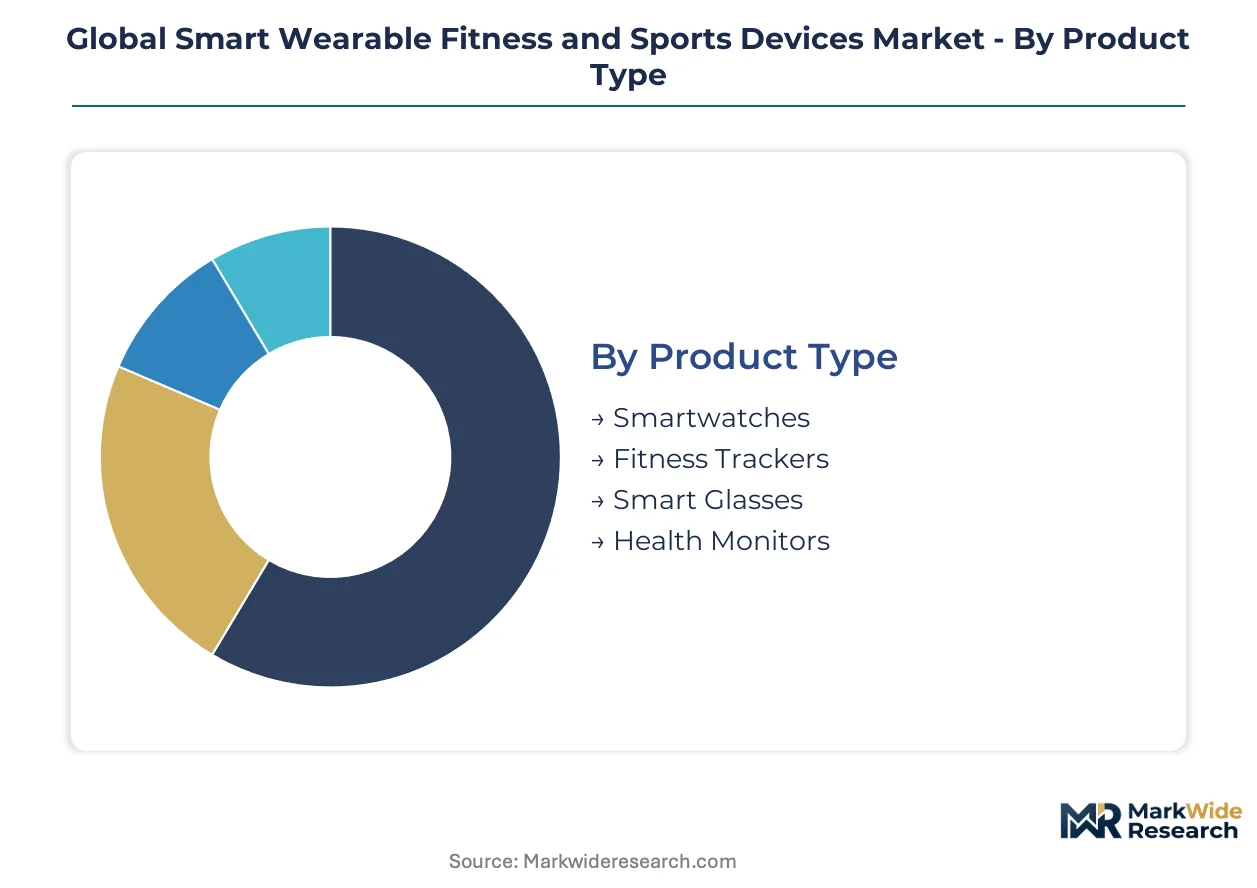
Product architecture in wearable fitness devices splits between modular component ecosystems and vertically integrated proprietary stacks. Segmentation reveals where hardware margin pools concentrate versus where volume shipments accumulate.
Product Type:
Standardization versus customization tension runs deepest in form factor design, where wrist-worn devices face diverging paths toward clinical certification or consumer simplicity.
- Smartwatches:Full-featured wrist-worn computers integrate app ecosystems, cellular connectivity, and FDA-cleared ECG algorithms. Demand concentrates among employer wellness programs in the United States seeking biometric surveillance for healthcare cost containment.
- Fitness Trackers:Stripped-down physiological monitors prioritize battery longevity and price accessibility over computational breadth. Volume shipments flow toward India's emerging middle class through Xiaomi's vertical manufacturing scale and localized distribution.
- Smart Glasses:Optical see-through displays with gesture and voice interfaces remain experimental for sports applications. Early adoption clusters around cycling and running demographics in Germany testing heads-up performance metrics.
- Health Monitors:Dedicated single-purpose devices target chronic condition management with prescription-grade sensor validation. Regulatory clearance timelines through FDA and NMPA channels constrain product refresh cadence.
Most installed capacity flows through Fitness Trackers. Expansion is steepest in Smartwatches.
Technology:
Wireless protocol selection determines interoperability boundaries and power budget allocation across device tiers.
- Bluetooth:Low-energy 5.3 stacks dominate wrist-to-smartphone data pipelines, with codec efficiency improvements extending battery endurance for continuous heart rate streaming.
- NFC:Contactless payment tokenization and gym equipment pairing drive integration into mid-tier hardware, particularly in Japan's transit-integrated wearable ecosystem.
- Wi-Fi:Direct cloud synchronization bypasses smartphone tethering for music streaming and firmware updates, consuming disproportionate board space and antenna complexity.
- Sensor Technology:Photoplethysmography optical engines and microelectromechanical accelerometers constitute the fastest-advancing dimension, with SpO2 modules migrating from premium tiers toward mid-range fitness bands manufactured in Guangdong.
Bluetooth dominates connection volume. Sensor Technology commands the steepest R&D investment trajectory.
End User:
User sophistication gradients separate clinical-grade feature demand from lifestyle-oriented aesthetics prioritization.
- Athletes:Professional and semi-professional competitors require lactate threshold estimation, running power metrics, and recovery scoring validated against laboratory reference equipment.
- Fitness Enthusiasts:Structured training plan adherence and social leaderboard engagement drive subscription attach rates for coaching platforms.
- Casual Users:Notification mirroring and step counting satisfy baseline utility expectations with minimal sensor calibration demands.
- Health-Conscious Consumers:Preventive monitoring motivations align with atrial fibrillation screening and sleep apnea detection features cleared through FDA 510(k) pathways.
Health-Conscious Consumers generate the fastest-growing demand segment. Athletes sustain premium pricing power.
Application:
Functional use case segmentation maps directly to reimbursement code eligibility and enterprise procurement justification.
- Health Monitoring:Continuous glucose inference, blood pressure estimation, and arrhythmia detection push hardware toward clinical validation requirements.
- Activity Tracking:Step counting, distance measurement, and calorie estimation anchor baseline feature sets across all price tiers.
- Performance Analysis:VO2 max estimation, training load balance, and race time prediction algorithms differentiate premium multisport watches.
- Sleep Tracking:Sleep stage classification and respiratory disturbance index scoring drive overnight wear compliance and band material biocompatibility scrutiny under EU MDR.
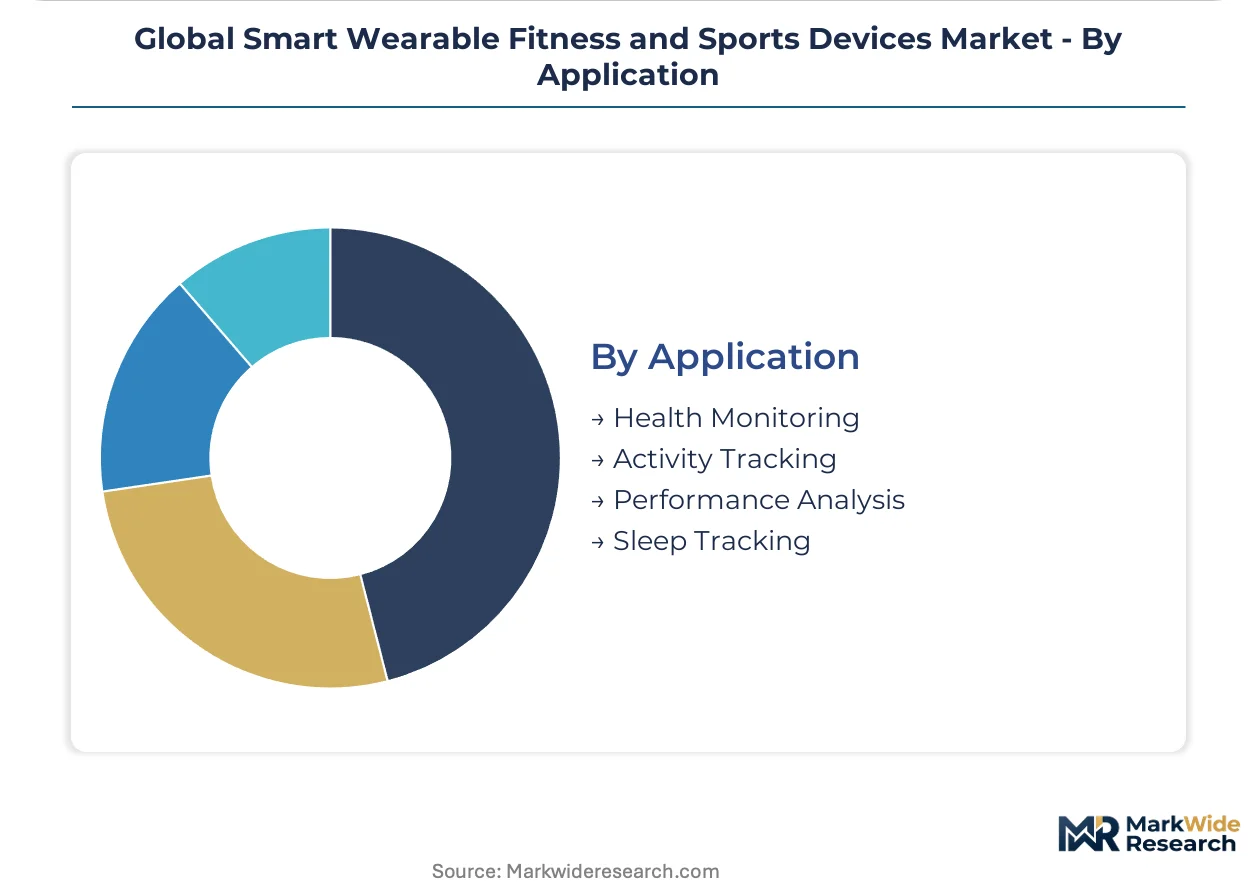
Activity Tracking captures the largest installed base. Health Monitoring faces the steepest regulatory compliance expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wrist-worn physiological monitoring originated in Finnish university laboratories during the 1970s before migrating to Silicon Valley venture capital and Shenzhen manufacturing scale. Today's demand geography reflects this lineage: Nordic sensor algorithm heritage, American health ecosystem monetization, and Chinese component production dominance.
United States
Employer-sponsored wellness procurement and FDA-cleared ECG reimbursement codes drive enterprise volume. The FDA 510(k) pathway for atrial fibrillation detection algorithms extends validation timelines but secures premium pricing for cleared devices. Greater Boston anchors health-tech venture formation alongside Minneapolis-based precision manufacturing heritage.
China
Guangdong Province concentrates microelectromechanical systems fabrication and photoplethysmography optical engine assembly. NMPA electromagnetic compatibility certification and GB standards data localization requirements govern connected health peripheral market access. Shenzhen and Dongguan sensor module clusters supply global OEMs with compressed lead times.
Germany
Marathon training programs and high-altitude expedition operators adopt multi-wavelength LED core temperature estimation faster than general fitness demographics. EU MDR biocompatibility testing and REACH substance disclosure mandates harden elastomer band material protocols. Bavaria's precision engineering heritage translates into cycling and running heads-up display experimentation.
India
PLI scheme production-linked subsidies attract assembly capacity shifts from coastal China to Noida and Sri City corridors. Price-sensitive Health-Conscious Consumers drive fitness tracker volume through localized distribution networks. DGFT electronics import policy adjustments shape component sourcing strategies for domestic manufacturing.
Japan
Transit-integrated NFC wearable ecosystems and METI energy efficiency standards shape hardware design constraints. Aging demographic preventive monitoring motivations align with sleep apnea detection feature demand. Kanto region precision component suppliers feed optical engine specifications for premium tier products.
Global Smart Wearable Fitness and Sports Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across sensor calibration depth and clinical validation investment. The vendor base stratifies into three tiers: vertically integrated proprietary silicon architects, aviation-grade GPS heritage specialists, and manufacturing-scale price compressors. Strategic differentiation centers on FDA clearance velocity, optical engine refresh cadence, and employer wellness procurement channel penetration. Dominant competitive moves include circular design investments responding to EU Green Deal mandates and India PLI scheme assembly relocation.
Within the proprietary ecosystem tier, Apple exemplifies silicon integration and health data lock-in strategies. Garmin Ltd. anchors aviation-precision GPS heritage translated into multisport watch positioning. Xiaomi Corporation occupies the manufacturing-scale end, leveraging Guangdong vertical production to compress price points in emerging market expansion. These three archetypes represent the dominant competitive vectors: ecosystem captivity, technical precision heritage, and cost-engineered volume.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Xiaomi Corporation |
| Apple |
| Polar Electro |
| Amazfit |
| Samsung Electronics |
| Huawei Technologies |
| Whoop |
| Fitbit |
| Others |
Value Chain & Pricing Dynamics
Vertically integrated technology conglomerates anchored in Shenzhen and Cupertino exert asymmetric pricing discipline through captive silicon design and optical engine fabrication, compressing margin capture for modular assemblers while sustaining premium tiers through FDA-cleared algorithm exclusivity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies according to clinical certification depth and sensor array sophistication. Premium tiers command separation through FDA 510(k) ECG clearance and SpO2 validation, while economy segments face acute price sensitivity among India's emerging middle class. Cost compression in mid-range fitness bands is intensifying because Guangdong manufacturing scale enables module cost reduction.
Supply Chain Analysis
FDA and EU MDR biocompatibility certification gates constrain supplier qualification timelines for skin-contact elastomer and adhesive substrates. Microelectromechanical systems fabrication concentrates in China, South Korea, and Taiwan, with photoplethysmography optical engines drawing from lithium-polymer cell supply anchored in East Asian chemical processing. Single-source vulnerability pervades Guangdong sensor module clusters. Distribution runs through enterprise wellness procurement channels and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smart Wearable Fitness and Sports Devices Market functions as a stable compounder, with employer-sponsored wellness program expansion delivering predictable B2B procurement volume that insulates hardware shipments from consumer discretionary volatility.
For Market Incumbents: Lock in employer wellness procurement relationships through centralized benefits administrator contracts before emerging OEMs secure RFP eligibility. Accelerate backward integration into photoplethysmography optical engine fabrication to defend margin position against Guangdong cost compressors. Prioritize FDA 510(k) pathway velocity for atrial fibrillation algorithm expansion. For New Entrants and Emerging Players: Begin with India PLI scheme assembly qualification to bypass Guangdong supply concentration and access price-sensitive fitness tracker demand through localized distribution. Target health-conscious consumer segments in Germany and Japan where EU MDR and METI compliance requirements deter low-investment competitors. Pursue direct-to-consumer subscription bundling to escape retail margin compression. For Investors and Strategic Acquirers: Valuations sit cheapest among modular assemblers lacking proprietary sensor calibration IP and clinical validation infrastructure. Long-term viability across the analysis window favors OEMs with FDA-cleared algorithm portfolios and employer channel penetration. Watch FDA expansion of clearance pathways into metabolic and respiratory biomarkers as inflection signal for premium tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Atrial fibrillation and ECG algorithm validation secures premium pricing in US employer wellness channels. |
| Backward Integration into Optical Engines | In-house photoplethysmography module production reduces Guangdong supplier dependency and compresses bill-of-materials cost. |
| EU MDR Biocompatibility Certification | REACH-compliant elastomer substitution accelerates European market entry before testing backlog extends. |
| India PLI Assembly Relocation | Production-linked subsidies attract capacity shifts from Shenzhen to Noida corridors for emerging market cost positioning. |
| Direct-to-Consumer Subscription Launch | Fitness coaching bundles displace retail margin capture with recurring revenue streams attached to hardware ecosystems. |
Study Parameters
Direct dialogue with wearable OEM product managers, employer benefits administrators, FDA regulatory consultants, Guangdong sensor module suppliers, and hospital biomedical engineering directors grounded qualitative assessment. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submissions, NMPA electromagnetic compatibility filings, and enterprise wellness procurement RFP documents. Bottom-up shipment modeling and top-down health expenditure allocation triangulated market sizing.
Unit economics and installed base projections across the analysis window segmented by product architecture, wireless protocol, end-user sophistication, and application reimbursement eligibility. CAGRs derived from historical shipment trajectories, employer subsidy expansion curves, and regulatory clearance velocity assumptions. Forecast inputs incorporated India PLI scheme capacity buildout schedules and EU Green Deal battery chemistry compliance cost pass-through.
Several conditions sit outside the modeled scope, including lithium carbonate spot price volatility, geopolitical disruption of Taiwan semiconductor supply, and FDA acceleration of metabolic biomarker clearance timelines. Forecasts reflect documented assumptions regarding employer wellness program adoption elasticity and clinical validation cost trajectories. A model refresh is warranted upon material change in FDA regulatory expansion patterns or India PLI scheme subsidy duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Sports Technology Market