
 Body Sensors Market | 2026-2036
Body Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Body Sensors Market Analysis
ISO 13485 certification is redrawing competitive boundaries for medical-grade body sensor suppliers. Allegro MicroSystems leverages Hall-effect expertise to dominate automotive-adjacent biometric applications. Koninklijke Philips N.V. anchors its position through integrated hospital-to-home monitoring platforms. Texas Instruments Incorporated competes by extending its analog semiconductor portfolio into low-power wearable signal chains.
Body sensors are electromechanical or biochemical transducers that convert physiological parameters into measurable electrical signals, typically operating at power budgets below one milliwatt for continuous skin-contact or implanted deployment. Their primary commercial purpose spans real-time health status transmission, athletic performance quantification, and chronic disease management through closed-loop therapeutic systems. Wearable sensors command the largest revenue pool due to consumer familiarity and retail channel density, while implantable sensors capture the steepest growth trajectory driven by cardiac rhythm management and glucose monitoring applications. Biosensors concentrate margin pools where enzymatic or nucleic-acid recognition layers enable diagnostic specificity unavailable to purely physical transducers.
FDA premarket notification requirements govern United States market entry for clinical body sensors, while the EU Medical Device Regulation imposes post-market surveillance obligations across European Economic Area states. Japan's PMDA enforces QMS ministerial ordinances that foreign manufacturers must satisfy through in-country representation. Stakeholders must monitor convergence between software-as-medical-device frameworks and traditional hardware clearance pathways as algorithm-driven diagnostic features proliferate.
Market Dynamics
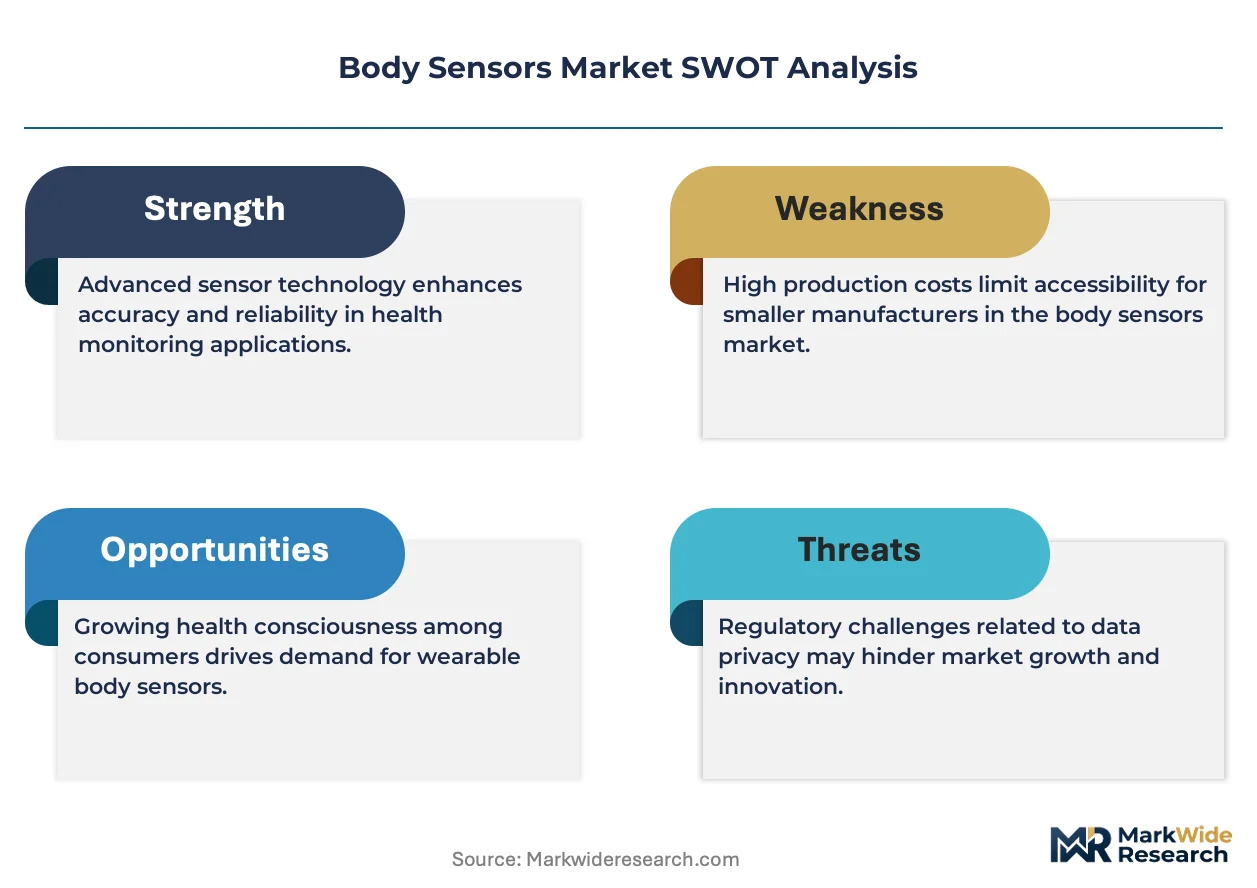
ISO 13485 certification requirements and FDA premarket notification pathways are compressing vendor qualification timelines while elevating capital barriers for new entrants into clinical-grade body sensor manufacturing.
Growth Catalysts
- Wearable cardiac monitoring:Healthcare systems in Germany and Japan are reimbursing continuous ambulatory electrocardiography, pulling silicon photoplethysmography sensors into primary care workflows.
- EU Medical Device Regulation post-market surveillance:MDR Article 83 mandates proactive safety reporting, which incumbent suppliers are leveraging to disqualify non-compliant competitors from hospital procurement.
- Enzymatic biosensor specificity:Glucose oxidase recognition layers in continuous glucose monitors are displacing intermittent fingerstick testing among Type 1 diabetes patients in the United States.
Market Restraints
- MEMS foundry concentration:Taiwan-based contract manufacturers control 70% of microelectromechanical systems wafer supply for pressure and inertial sensors, exposing buyers to geopolitical logistics disruption.
- Platinum group metal volatility:Electrochemical biosensors require iridium and ruthenium electrodes, with spot price swings directly compressing gross margins on consumable test strips.
- Biocompatibility testing duration:ISO 10993 cytotoxicity and sensitization protocols add 14-18 months to implantable sensor development cycles before PMDA or FDA submission.
Strategic Opportunities
- Closed-loop therapeutic integration:Convergence between continuous glucose monitoring and insulin pump control algorithms is creating automated glycemic management platforms in the United States.
- India's PLI scheme for electronics:Production-linked incentives for wearable device assembly are attracting contract manufacturers to establish sensor packaging facilities in Tamil Nadu and Karnataka.
- Direct-to-consumer distribution:Retail pharmacy chains and telehealth platforms are bypassing traditional durable medical equipment channels for fitness-oriented pulse oximeters and sleep trackers.
Industry Challenges
- Signal processing firmware talent scarcity:Low-power embedded systems engineers with biomedical algorithm experience command premium compensation, constraining R&D expansion at mid-tier suppliers.
- Legacy hospital IT integration:HL7 FHIR interoperability requirements force sensor vendors to maintain multiple data format adapters for Epic, Cerner, and Meditech electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Sensors Market |
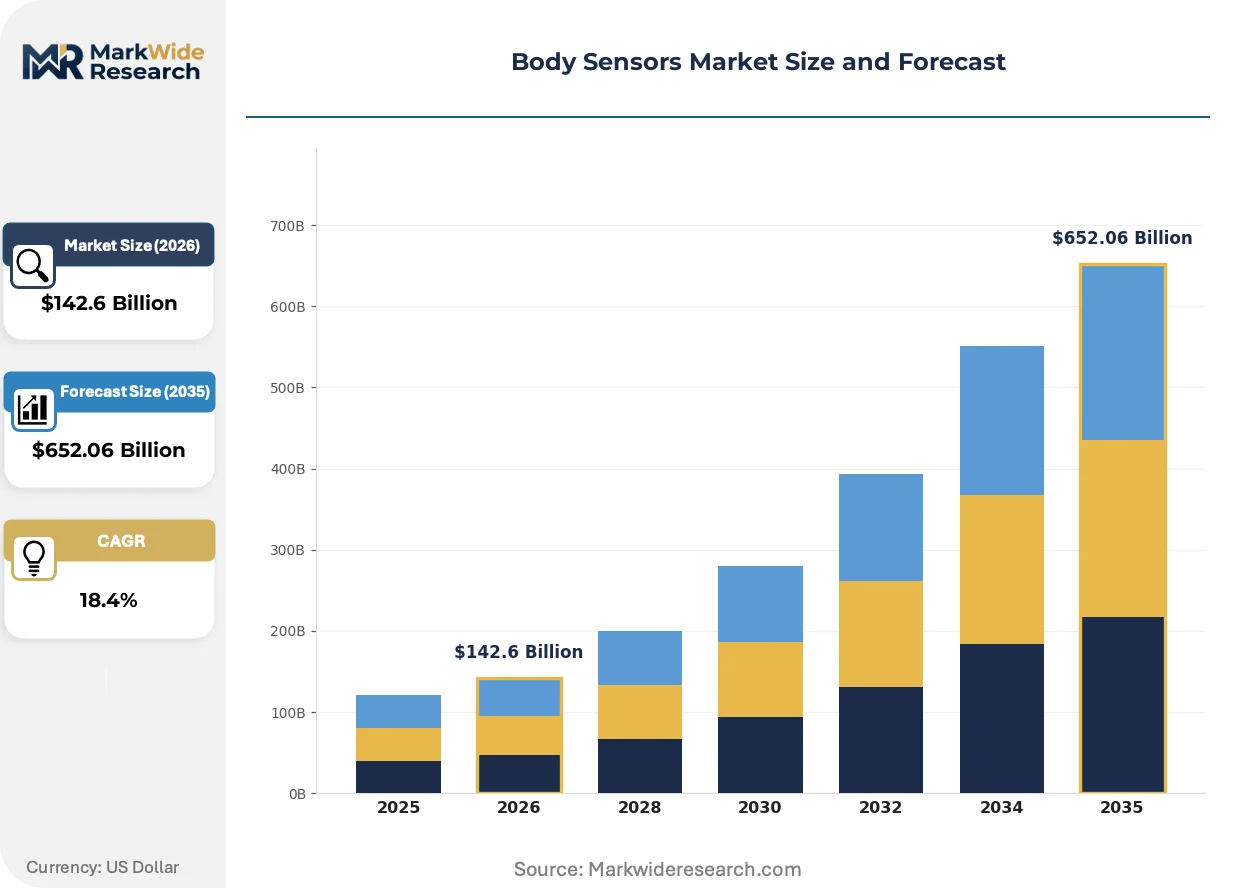
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $652.06 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Ingestible Sensors, Environmental Sensors Technology: Biosensors, Optical Sensors, Ultrasonic Sensors, Pressure Sensors Application: Health Monitoring, Fitness Trackers, Medical Diagnostics, Sports Analytics End User: Healthcare Providers, Fitness Enthusiasts, Research Institutions, Individuals |
| Companies Covered | Allegro MicroSystems, Koninklijke Philips N.V., Analog Devices, Inc., Medtronic, TE Connectivity, Texas Instruments Incorporated, STMicroelectronics, GE Healthcare, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Sensors Market Emerging Trajectories
Algorithm-driven diagnostic features are migrating from cloud servers to edge-computing sensor nodes, collapsing latency requirements and rewriting power-architecture specifications across wearable and implantable categories.
Flexible hybrid electronics is decomposing the traditional rigid printed circuit board stack in epidermal health patches. Materials suppliers in Germany are shipping silver nanowire inkjet formulations to contract manufacturers in Japan, who laminate stretchable interconnects onto thermoplastic polyurethane substrates. Hospital-at-home programs in the United States are absorbing these conformal temperature and hydration sensors for post-surgical monitoring, compressing form factor constraints that previously excluded elderly patients with fragile skin.
REACH Annex XVII restrictions on nickel release are forcing dermatological sensor housings toward medical-grade titanium and PEEK polymers. The European Chemicals Agency's 2023 amendment tightened migration limits for prolonged skin contact, invalidating existing stainless steel electrode designs. German and Swiss component suppliers are accelerating plasma surface treatment investments to maintain CE marking eligibility for next-generation continuous lactate monitors.
Hospital procurement committees are consolidating vendor lists around integrated platform contracts rather than standalone device purchases. Health systems in Japan and the United States now require API-accessible data lakes, subscription-based calibration services, and predictive maintenance guarantees as table stakes. This bundling preference disadvantages pure-play sensor OEMs lacking cloud infrastructure or clinical decision support software, compressing the addressable market for hardware-only suppliers in cardiac rhythm and respiratory monitoring segments.
Body Sensors Market Segmentation
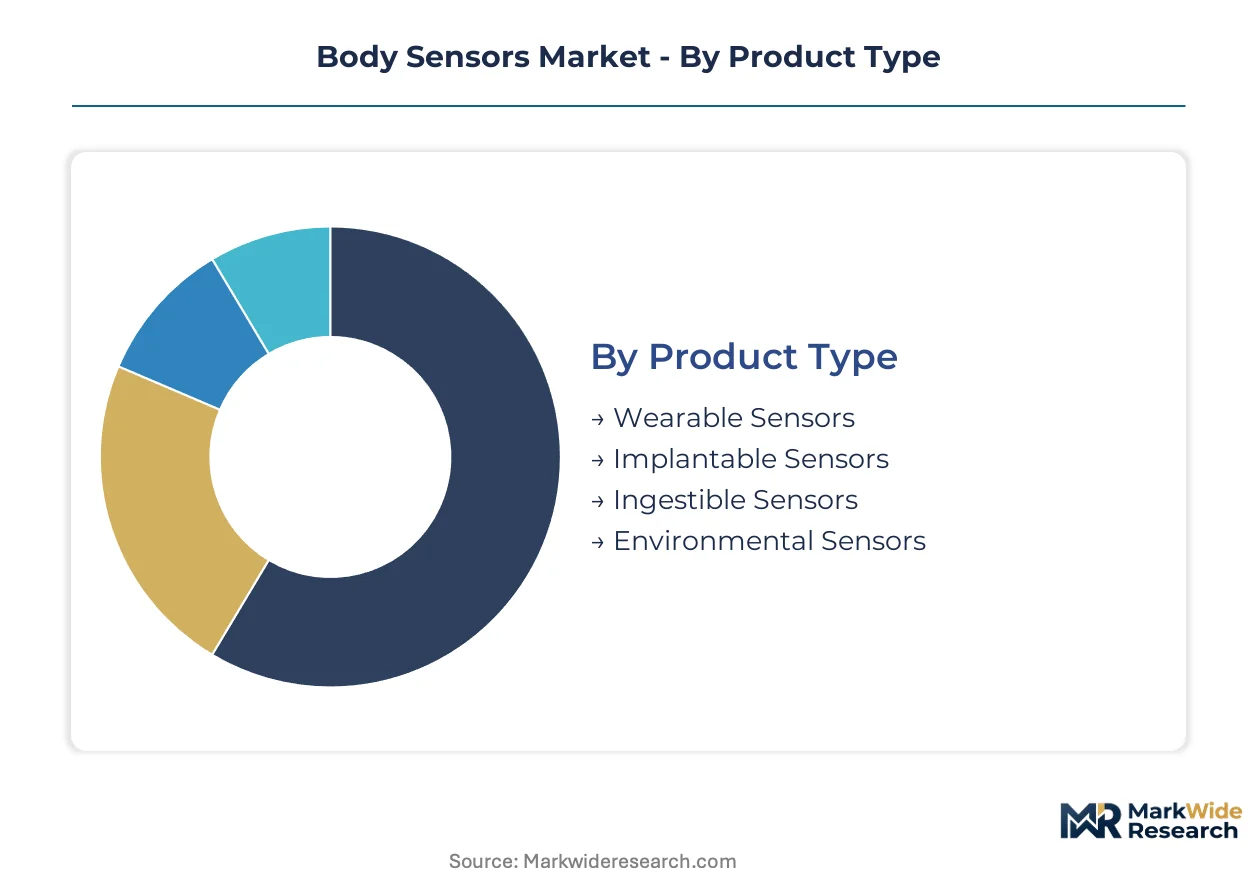
Segmentation in the body sensors market reveals divergent margin architectures across physical form factors, transduction principles, and clinical versus consumer use cases. Suppliers must align R&D budgets and certification strategies to the specific performance thresholds and reimbursement pathways governing each segment cluster.
Product Type:
Margin pools concentrate in implantable and ingestible categories where regulatory barriers protect pricing power, while wearable sensors compete on scale and retail velocity.
- Wearable Sensors:Electromechanical transducers packaged in wrist-worn, chest-strap, or adhesive patch form factors operate at sub-milliwatt power budgets for continuous skin-contact deployment. Demand concentrates in the United States and Germany where health insurers are reimbursing continuous ambulatory electrocardiography for post-cardiac event monitoring, though MEMS foundry concentration in Taiwan exposes supply chains to geopolitical logistics disruption.
- Implantable Sensors:Hermetically sealed biocompatible devices with platinum-group metal electrodes require ISO 10993 cytotoxicity testing cycles lasting 14-18 months before FDA or PMDA submission. Cardiac rhythm management applications in Japan and glucose monitoring among Type 1 diabetes patients in the United States are displacing intermittent diagnostic protocols with closed-loop therapeutic integration.
- Ingestible Sensors:Capsule-encapsulated transducers transmit gastrointestinal pH, temperature, and pressure data via RF telemetry for medication adherence and motility disorder assessment.
- Environmental Sensors:Ambient air quality and allergen detection wearables target urban consumers in high-pollution metropolitan clusters.
Wearable sensors hold installed capacity. Ingestible sensors are rotating up the share rankings.
Technology:
Technology selection determines signal specificity, calibration frequency, and the depth of algorithmic processing required at the edge versus cloud.
- Biosensors:Enzymatic recognition layers employing glucose oxidase or nucleic-acid probes deliver diagnostic specificity unavailable to physical transducers, commanding premium margins in continuous glucose monitoring where fingerstick testing displacement is accelerating among United States diabetes patients. German and Swiss suppliers are accelerating plasma surface treatment investments to maintain CE marking eligibility for lactate and ketone biosensors under REACH Annex XVII nickel restrictions.
- Optical Sensors:Silicon photoplethysmography and near-infrared spectroscopy modules dominate heart rate and blood oxygen saturation applications in fitness-oriented consumer devices.
- Ultrasonic Sensors:Piezoelectric transducers enable non-invasive blood flow and tissue elasticity measurement for deep-vein thrombosis screening.
- Pressure Sensors:MEMS-based capacitive and piezoresistive elements capture intraocular, intracranial, and cardiovascular pressure waveforms in critical care settings.
Biosensors capture the steepest expansion trajectory. Optical sensors are rotating up the share rankings.
Application:
Application segmentation maps directly to reimbursement eligibility, regulatory classification, and the hardware-software bundling requirements of hospital procurement committees.
- Health Monitoring:Continuous physiological surveillance platforms spanning hospital-at-home programs and chronic disease management workflows require HL7 FHIR interoperability with Epic, Cerner, and Meditech electronic health record systems. United States health systems are consolidating vendor lists around API-accessible data lakes and predictive maintenance guarantees, disadvantaging hardware-only suppliers lacking cloud infrastructure.
- Fitness Trackers:Consumer-grade step counting, sleep staging, and calorie estimation devices distribute through retail pharmacy chains and telehealth platforms bypassing traditional durable medical equipment channels.
- Medical Diagnostics:FDA-cleared and CE-marked devices for arrhythmia detection, sleep apnea screening, and fall risk assessment carry clinical-grade liability and post-market surveillance obligations under EU MDR Article 83.
- Sports Analytics:Biomechanical load monitoring and recovery optimization tools target professional athletic organizations and military training programs.
Health monitoring holds installed capacity. Sports analytics is rotating up the share rankings.
End User:
End user segmentation determines sales cycle length, technical support intensity, and the regulatory documentation burden placed on suppliers.
- Healthcare Providers:Hospital systems, physician practices, and home health agencies demand ISO 13485-certified manufacturing, FDA premarket notification clearance, and subscription-based calibration services as table stakes for procurement eligibility. Japan's PMDA enforces QMS ministerial ordinances that foreign manufacturers must satisfy through in-country representation.
- Fitness Enthusiasts:Direct-to-consumer purchasers prioritize retail channel density, smartphone application integration, and social sharing features over clinical accuracy.
- Research Institutions:Academic medical centers and contract research organizations require raw data export capabilities and protocol customization for clinical trial endpoints.
- Individuals:Wellness-oriented consumers purchasing sleep trackers and pulse oximeters through e-commerce platforms represent the lowest barrier to entry but highest churn risk for suppliers.
Healthcare providers hold installed capacity. Individuals are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and consumer electronics distributors concentrate demand across four distinct national markets, each shaped by unique reimbursement frameworks and regulatory enforcement patterns.
United States
Medicare reimbursement for continuous ambulatory electrocardiography and hospital-at-home programs pulls silicon photoplethysmography sensors into primary care workflows. FDA premarket notification requirements govern clinical body sensor market entry, while the agency's software-as-medical-device framework tightens algorithm-driven diagnostic oversight. Greater Boston and the San Francisco Bay Area host concentrated venture deployment in enzymatic biosensor startups targeting glucose monitoring applications.
Germany
Statutory health insurers reimburse cardiac monitoring wearables for post-event surveillance, accelerating clinical adoption among aging populations. REACH Annex XVII nickel release restrictions force dermatological sensor housings toward medical-grade titanium and PEEK polymers, invalidating legacy stainless steel electrode designs. The Baden-Württemberg industrial corridor anchors plasma surface treatment investments for CE-marked lactate monitor production.
Japan
PMDA-enforced QMS ministerial ordinances require foreign manufacturers to establish in-country representation, elevating compliance barriers for clinical-grade entrants. METI funding for digital health infrastructure supports integrated hospital-to-home monitoring platforms. The Kanto region around Tokyo concentrates domestic sensor packaging facilities serving cardiac rhythm management device OEMs.
India
Production-linked incentives for electronics manufacturing attract wearable device assembly to Tamil Nadu and Karnataka, reducing import dependency for fitness-oriented pulse oximeters. CDSCO medical device rules impose registration requirements on foreign manufacturers without prior regulatory approval in reference jurisdictions. Bengaluru's electronics cluster hosts expanding contract manufacturer presence in sensor packaging and system integration.
Body Sensors Market Vendor Landscape
Player mix skews toward diversified semiconductor conglomerates with analog signal chain expertise, creating tiered competition between integrated platform providers and specialized sensor OEMs. Market structure concentrates around three strategic archetypes: Hall-effect and magnetic sensing specialists leveraging automotive-adjacent biometric applications, hospital-to-home monitoring platform integrators bundling hardware with cloud infrastructure, and low-power analog semiconductor suppliers extending portfolios into wearable signal chains. Dominant competitive moves include strategic partnerships for HL7 FHIR interoperability certification and geographic expansion through in-country manufacturing to satisfy PMDA and CDSCO localization requirements.
Within the integrated platform tier, Koninklijke Philips N.V. and GE Healthcare exemplify hospital procurement consolidation strategies, anchoring vendor list positions through API-accessible data lakes and subscription calibration services. Among analog semiconductor suppliers, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions extending low-power signal chain portfolios into continuous physiological monitoring applications. Allegro MicroSystems represents the magnetic sensing specialist archetype, with Zhengzhou Shuli Machinery Co., Ltd. absent from this market.
| Leading Market Players |
|---|
| Allegro MicroSystems |
| Koninklijke Philips N.V. |
| Analog Devices, Inc. |
| Medtronic |
| TE Connectivity |
| Texas Instruments Incorporated |
| STMicroelectronics |
| GE Healthcare |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month biocompatibility testing cycles for ISO 10993 certification compress supplier qualification timelines while amplifying pricing power for incumbent contract manufacturers with validated cleanroom capacity in Germany and Japan. This lead-time band concentrates margin capture among established players, forcing new entrants to absorb upfront validation costs or accept subordinate tier-2 supplier status in hospital procurement hierarchies.
Pricing Analysis
Cost-plus contracts with platinum group metal indexation dominate consumable biosensor procurement, tying electrode material costs to spot iridium and ruthenium benchmarks. Pricing stratifies across FDA-cleared clinical tiers, ISO 13485-certified medical grades, and unregulated consumer wellness bands, with certification level commanding the steepest premium differentials. Cost compression in wearable photoplethysmography modules is intensifying because Taiwan MEMS foundries are prioritizing automotive pressure sensor contracts. Fitness enthusiasts purchasing direct-to-consumer sleep trackers exhibit the highest price sensitivity, while hospital systems negotiating integrated platform contracts prioritize predictive maintenance guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Ningbo port complex and Yokohama container terminals are elevating landed costs for German silver nanowire ink formulations and Japanese thermoplastic polyurethane substrates. Manufacturing concentrates in Taiwan for MEMS wafer fabrication, Germany for plasma surface treatment equipment, and Japan for hermetic packaging of implantable devices. Raw material dependencies include platinum group metals for electrochemical electrodes, medical-grade titanium for REACH-compliant housings, and silver nanowire suspensions for stretchable interconnects. Single-source vulnerability in Taiwan MEMS foundries exposes buyers to geopolitical logistics disruption. Distribution runs through hospital GPO contracts in the United States, statutory health insurer procurement frameworks in Germany, and electronics retail chains for direct-to-consumer fitness devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive boundaries as hospital procurement committees mandate API-accessible data lakes and HL7 FHIR interoperability, collapsing the addressable market for hardware-only suppliers without cloud infrastructure or clinical decision support software ecosystems.
For Market Incumbents: Compound platform stickiness by bundling predictive calibration subscriptions with hardware contracts, forcing pure-play sensor OEMs into subordinate component supplier roles. Accelerate in-country manufacturing investments in Tamil Nadu and Karnataka to satisfy CDSCO localization requirements and PMDA QMS ministerial ordinances, defending vendor list positions against emerging contract manufacturers from India's PLI scheme.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer compressed premarket notification pathways for algorithm-driven diagnostic features in closed-loop therapeutic integration. Target direct-to-consumer distribution through telehealth platforms and retail pharmacy chains for fitness-oriented pulse oximeters and sleep trackers, bypassing entrenched durable medical equipment channels and hospital procurement consolidation. White-space concentration sits in sports analytics biomechanical load monitoring for professional athletic organizations and military training programs.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because analog semiconductor suppliers with low-power signal chain expertise are extending into wearable physiological monitoring, creating acquisition targets with captive MEMS design capabilities and biosensor recognition layer IP. The signal to watch is convergence between software-as-medical-device frameworks and traditional hardware clearance pathways as algorithm-driven diagnostic features proliferate across edge-computing sensor nodes.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Establishes medical-grade manufacturing credibility for CE marking and FDA premarket notification eligibility. |
| HL7 FHIR Interoperability Partnership | Enables Epic and Cerner EHR integration required by United States hospital procurement committees. |
| Plasma Surface Treatment Scale-Up | Secures REACH Annex XVII compliance for nickel-free titanium and PEEK polymer sensor housings in Germany. |
| PMDA In-Country Manufacturing | Satisfies QMS ministerial ordinances for cardiac rhythm management device sales in Japan's Kanto region. |
| Closed-Loop Therapeutic Integration | Converges continuous glucose monitoring with insulin pump control algorithms for automated glycemic management. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR Article 83 post-market surveillance databases, PMDA QMS ministerial ordinances, and CMS Medicare reimbursement schedules. Primary interviews engaged hospital purchasing committee members, biomedical engineers at cardiac monitoring device OEMs, GPO contracts managers, and regulatory affairs leads at enzymatic biosensor manufacturers. Secondary validation drew from ISO 10993 biocompatibility testing protocols, REACH Annex XVII nickel migration limits, and MEMS foundry capacity disclosures. Bottom-up triangulation across product type, technology, application, and end user segments was cross-checked against top-down macroeconomic drivers and reimbursement framework evolution.
Segmentation dimensions modeled span wearable, implantable, ingestible, and environmental sensor form factors; biosensor, optical, ultrasonic, and pressure transduction technologies; health monitoring, fitness tracking, medical diagnostics, and sports analytics applications; and healthcare provider, fitness enthusiast, research institution, and individual end users across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves for continuous ambulatory electrocardiography reimbursement and closed-loop therapeutic integration penetration. Forecast inputs incorporated MEMS foundry capacity constraints, platinum group metal price volatility bands, and biocompatibility testing duration distributions.
Underlying assumptions cover sustained Medicare reimbursement for hospital-at-home programs and statutory health insurer coverage for cardiac monitoring wearables in Germany, with deviation risk concentrated in Taiwan semiconductor logistics disruption and REACH regulatory amendments tightening dermatological sensor material restrictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Global GPS Watch Tracker Market