
 GCC Running Gear Market | 2026-2036
GCC Running Gear Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Running Gear Market Intelligence
Advanced foam midsole technology is tilting toward energy-return formulations that reduce thermal degradation in Gulf climates. Nike leverages regional distribution hubs to sustain shelf presence across hypermarket chains. Adidas anchors its position through football-to-running cross-sell programs in Saudi Arabia and Qatar. Under Armour competes via heat-adaptive fabric R&D tailored to desert training conditions.
GCC running gear comprises performance-engineered footwear, moisture-wicking apparel, and hydration systems designed for high-temperature exertion, typically incorporating EVA or TPU midsoles with breathability ratings exceeding standard temperate-climate specifications; these products serve recreational joggers, competitive marathoners, and institutional fitness programs across six Gulf states. Shoes dominate absolute spend due to replacement cycles driven by abrasive desert terrain and heat-accelerated midsole compression. The accessories category captures rising attachment rates as consumers bundle GPS watches, compression sleeves, and electrolyte systems with core purchases. Online channels expand fastest among intermediate and advanced runners seeking direct-to-consumer customization and size-precision tools unavailable in conventional retail.
SASO enforces the Saudi Quality Mark Programme for imported athletic footwear, elevating compliance costs for non-certified suppliers while protecting domestic consumers from substandard heat-performance claims. The UAE's Ministry of Industry and Advanced Technology aligns with Gulf Standardization Organization benchmarks for textile flammability and chemical content, shaping procurement specifications for government-backed wellness initiatives. Stakeholders must monitor how Saudi Vision 2030 mass-participation targets and Qatar's post-World Cup sports infrastructure conversion reshape volume concentration and channel requirements across the six-nation bloc.
Market Dynamics
Marathon participation mandates under Saudi Vision 2030 and Qatar National Vision 2030 are reconfiguring demand concentration across the six-nation bloc, pulling inventory allocation toward temperature-controlled retail clusters in Riyadh and Doha while compressing traditional distributor timelines.
Growth Catalysts
- Mass-participation targets:Saudi Vision 2030 and Qatar National Vision 2030 mandate government-backed marathon programs that expand the addressable runner base beyond elite athletes into recreational segments.
- SASO Quality Mark Programme:The Saudi Standards, Metrology and Quality Organization enforces heat-performance certification for imported athletic footwear, filtering substandard imports and elevating consumer trust in certified products.
- EVA-TPU formulation advances:Energy-return midsole compounds with enhanced thermal stability reduce compression set degradation in ambient temperatures exceeding 40°C, extending product lifecycle in Gulf conditions.
Market Restraints
- Petrochemical input volatility:TPU and EVA resin prices fluctuate with crude oil derivatives, squeezing margin predictability for midsole manufacturers serving price-sensitive distribution tiers.
- Retail concentration in Dubai and Riyadh:Branded retail clusters dominate shelf access, creating barrier-to-entry effects for emerging suppliers lacking hypermarket chain relationships.
- Substitution from football:Adidas and regional competitors prioritize football-to-running cross-sell programs that capture athletic footwear spend before runners specialize.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These markets lack dedicated running retail infrastructure present in UAE and Saudi Arabia, creating first-mover advantage for direct-to-consumer platform entry.
- Post-World Cup sports infrastructure:Qatar's stadium conversion into community running facilities generates institutional procurement demand for hydration systems and performance apparel.
- Online customization platforms:Size-precision tools and heat-adaptive fabric configurators bypass conventional retail constraints, capturing intermediate runners seeking technical specificity unavailable in physical channels.
Industry Challenges
- SASO certification timelines:Heat-performance testing protocols for midsole materials extend product launch cycles by four to six months compared to temperate-climate markets.
- Desert terrain abrasion:Outsole compound development requires specialized rubber formulations that increase R&D capex intensity relative to standard road-running specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Running Gear Market |
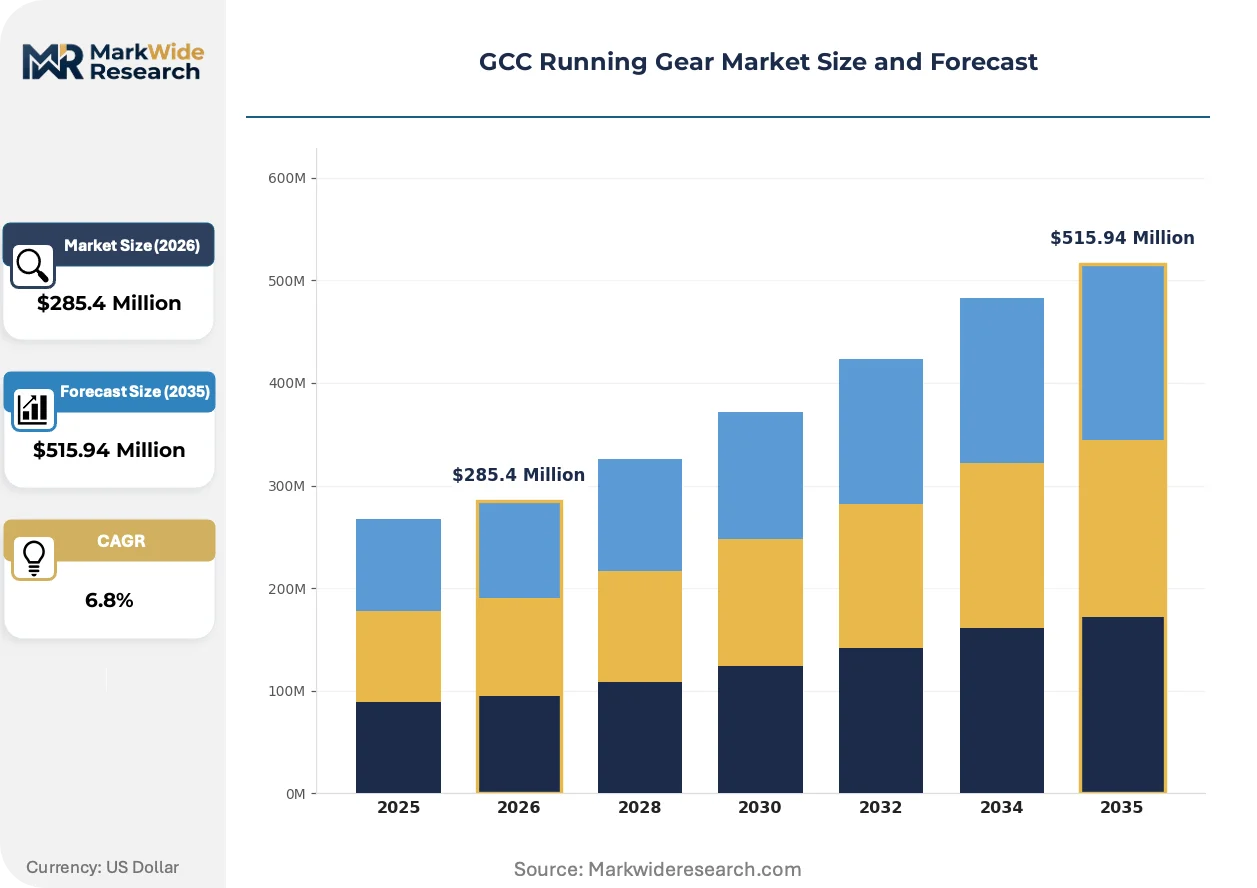
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoes, Apparel, Accessories, Hydration Gear Gender: Men, Women, Unisex, Kids Activity Level: Beginner, Intermediate, Advanced, Professional Distribution Channel: Online, Retail, Specialty Stores, Events |
| Companies Covered | Nike, Adidas, Puma, Under Armour, ASICS, New Balance, Skechers USA, Hoka One, Saucony, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Running Gear Market Strategic Shifts & Innovations
Digital fitting technology and climate-adaptive material science are compressing the traditional retail-to-runner relationship, while regulatory certification requirements reshape competitive entry barriers across the Gulf Cooperation Council states.
Energy-return foam formulations with graphene-doped TPU structures are virtualizing the traditional midsole replacement cycle by extending compression resilience in ambient temperatures exceeding standard temperate specifications. Competitive marathoners in Dubai and Riyadh are adopting these compounds at accelerated rates. This virtualization is compressing inventory turnover expectations for distributors still stocking conventional EVA-based product lines.
The UAE Ministry of Industry and Advanced Technology alignment with Gulf Standardization Organization textile flammability benchmarks is forcing apparel suppliers to reformulate synthetic moisture-wicking fabrics. Heat-adaptive fabric R&D investments are rising among technical suppliers seeking government-backed wellness initiative contracts. Running apparel procurement for institutional fitness programs now requires GSO-compliant certification documentation.
Intermediate and advanced runners are bypassing conventional retail through direct-to-consumer platforms offering size-precision scanning and climate-specific customization. Hypermarket chains in Saudi Arabia and Qatar are responding with dedicated running concept zones featuring technical staff training. This channel rotation is most visible in Dubai, where temperature-controlled indoor running facilities bundle membership with gear purchase incentives.
GCC Running Gear Market Segmentation
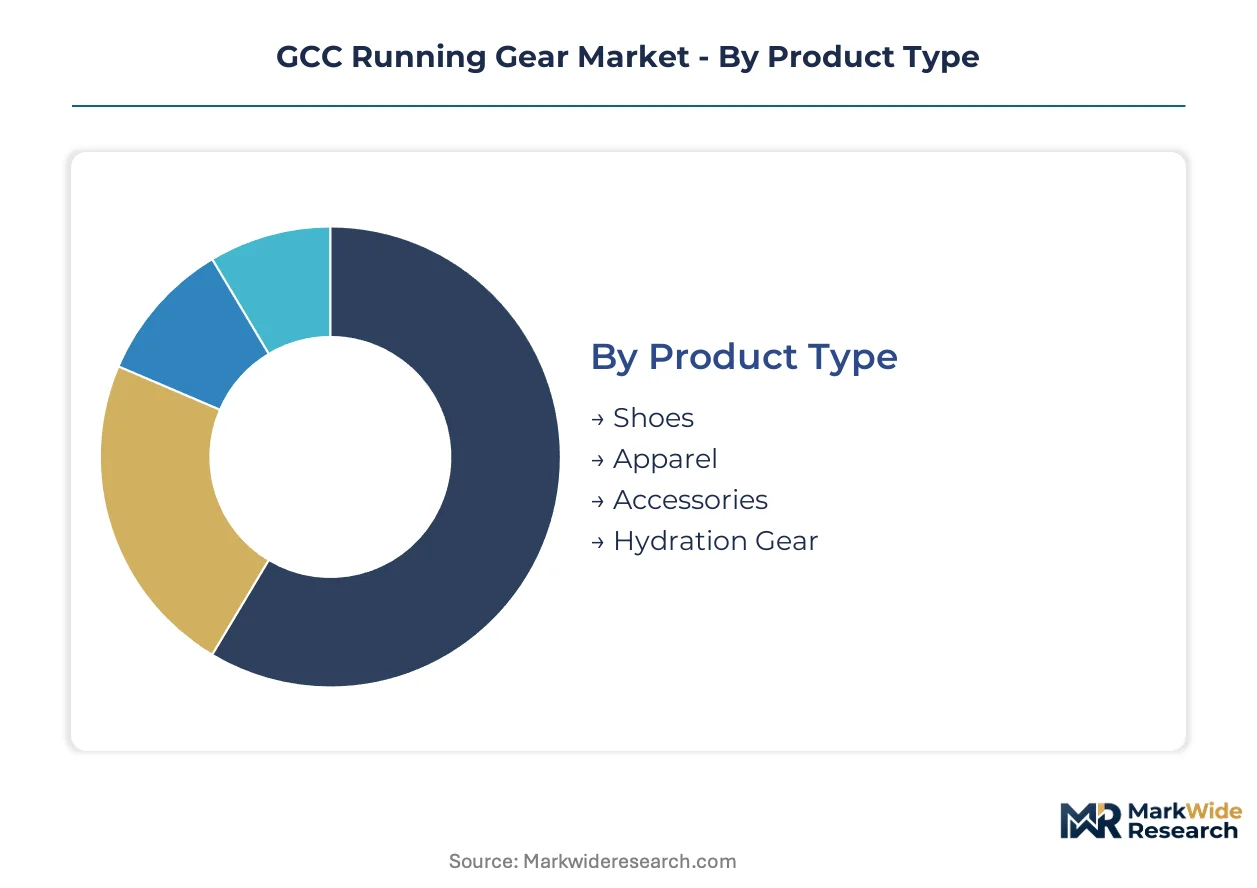
Segmentation in the GCC running gear market reveals distinct purchasing behaviors shaped by climate constraints, gender participation gaps in mass-participation programs, and channel preferences that diverge sharply between recreational joggers and competitive marathoners. Understanding these divisions enables inventory allocation that matches product specifications to thermal performance requirements and runner sophistication levels.
Product Type:
The use-case spectrum spans casual fitness walking through elite desert marathon racing, with each activity intensity demanding different material specifications and replacement cycles.
- Shoes:EVA and TPU midsole formulations engineered for thermal stability above 40°C ambient temperatures dominate procurement budgets. Replacement cycles compress in Riyadh and Dubai due to abrasive desert terrain and heat-accelerated compression set degradation.
- Apparel:Moisture-wicking synthetic fabrics with GSO-compliant flammability certifications capture institutional procurement contracts. Heat-adaptive R&D investments concentrate among suppliers seeking Saudi Vision 2030 wellness initiative tenders.
- Accessories:GPS watches, compression sleeves, and electrolyte systems post rising attachment rates at point of purchase across hypermarket chains.
- Hydration Gear:Insulated bottle systems and electrolyte delivery mechanisms address evaporative fluid loss rates exceeding temperate-climate benchmarks.
The dominant share belongs to Shoes, while Accessories is closing the gap fastest.
Gender:
Cost tier differentiation separates premium technical specifications from entry-level mass-participation products across gender lines.
- Men:Performance-engineered footwear with extended size runs and aggressive tread patterns serves the largest absolute participant base in government-backed marathon programs.
- Women:Technical apparel with heat-adaptive fabric configurations and precision-fit footwear addresses the fastest-expanding demographic under Saudi Vision 2030 female participation targets.
- Unisex:Standardized sizing and neutral colorways reduce inventory complexity for hypermarket chains stocking entry-level product lines.
- Kids:Growth-accommodating fit systems and school program procurement specifications drive institutional volume in Qatar's post-World Cup community facility conversions.
Men's products retain volume leadership, though Women's segment expansion is gaining share fastest.
Activity Level:
Customer type stratification determines technical specification intensity and channel access requirements.
- Beginner:Entry-level EVA midsole shoes and basic moisture-wicking apparel serve mass-participation program entrants with price-sensitive purchasing patterns.
- Intermediate:Energy-return foam formulations and climate-specific customization tools drive online platform migration away from conventional retail.
- Advanced:Graphene-doped TPU structures and precision hydration systems serve competitive marathoners in Dubai and Riyadh temperature-controlled facilities.
- Professional:Custom-molded specifications and sponsored athlete procurement contracts concentrate among elite competitors with direct manufacturer relationships.
Beginner-level products anchor absolute volume, while Intermediate-level purchasing is climbing the fastest.
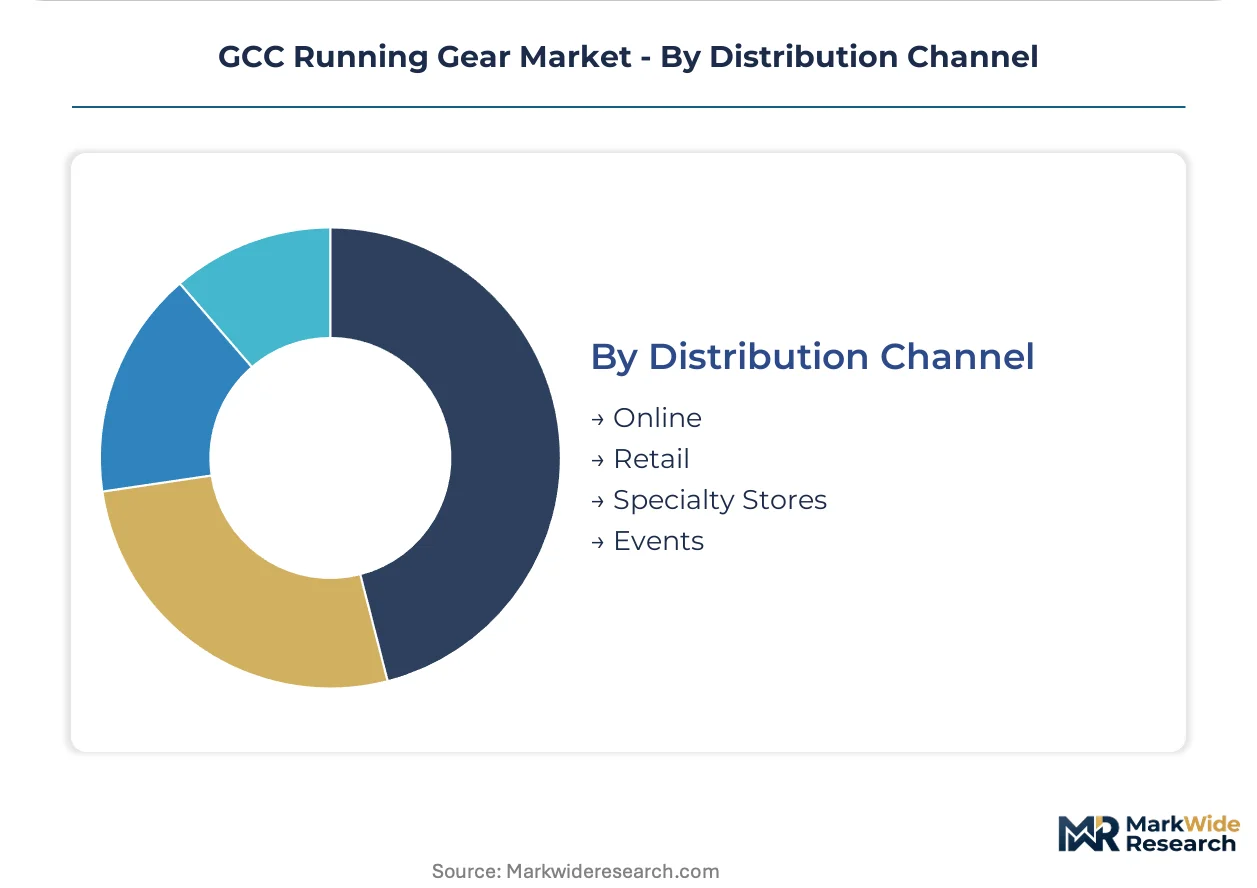
Distribution Channel:
Supply concentration in branded retail clusters creates barrier-to-entry effects for emerging suppliers lacking established relationships.
- Online:Size-precision scanning and climate-specific configurators capture intermediate and advanced runners seeking technical specificity unavailable in physical channels.
- Retail:Hypermarket chains in Saudi Arabia and Qatar deploy dedicated running concept zones with technical staff training to combat channel rotation.
- Specialty Stores:Temperature-controlled fitting environments and gait analysis services concentrate in Dubai and Riyadh retail clusters.
- Events:Marathon expo direct sales and sponsorship activation bundles generate concentrated volume around Saudi Vision 2030 and Qatar National Vision 2030 calendar dates.
Retail maintains the dominant position, though Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC running gear market exhibits a pronounced import dependency, with specialized footwear and technical apparel flowing predominantly from East Asian manufacturing centers into Saudi Arabia and the UAE, while re-export activity through Dubai's logistics hubs serves smaller Gulf markets with reduced direct procurement capabilities.
Saudi Arabia
Government-backed marathon programs under Vision 2030 are expanding the recreational runner base beyond elite athletes into mass-participation segments. SASO enforces the Saudi Quality Mark Programme for imported athletic footwear, filtering substandard heat-performance claims through extended certification timelines. Riyadh anchors demand concentration through temperature-controlled indoor running facilities and branded retail clusters.
United Arab Emirates
Dubai's logistics infrastructure enables re-export distribution throughout the smaller Gulf states while domestic consumption concentrates in hypermarket chains and specialty retail zones. The Ministry of Industry and Advanced Technology aligns with Gulf Standardization Organization benchmarks for textile flammability and chemical content. Temperature-controlled fitting environments and gait analysis services cluster in Dubai's branded retail districts.
Qatar
Post-World Cup stadium conversion into community running facilities is generating institutional procurement demand for hydration systems and performance apparel. Qatar National Vision 2030 mandates government-backed marathon programs that reshape volume concentration and channel requirements. Doha's emerging retail infrastructure is compressing traditional distributor timelines for inventory allocation.
Kuwait
Underpenetrated running retail infrastructure creates first-mover advantage for direct-to-consumer platform entry targeting intermediate runners seeking technical specificity. The national quality regulator maintains alignment with Gulf Standardization Organization benchmarks without the extended certification protocols enforced in Saudi Arabia. Kuwait City lacks the dedicated running concept zones present in Riyadh and Dubai.
Bahrain
Proximity to Saudi Arabia's eastern province enables cross-border procurement patterns that limit dedicated domestic retail development. The national standards body references Gulf Standardization Organization textile benchmarks without independent enforcement infrastructure. Manama's retail landscape concentrates on general athletic merchandise rather than climate-specific running specialization.
GCC Running Gear Market Key Industry Players
On the supply side, the industry is consolidating around multinational sportswear conglomerates with established Gulf distribution networks, while mid-tier specialists compete through technical differentiation in heat-adaptive materials. Three strategic archetypes dominate: scale-driven global brands with regional hub operations, technical specialists in desert-climate performance engineering, and value-oriented mass-market suppliers leveraging hypermarket channel access. Competitive moves center on football-to-running cross-sell program expansion and direct-to-consumer platform development bypassing traditional retail concentration.
Within the scale-driven tier, Nike and Adidas exemplify multinational conglomerates with established regional distribution infrastructure. Under Armour occupies a position among technical specialists emphasizing heat-adaptive fabric research and development. These three anchors illustrate the competitive tension between global brand recognition and climate-specific performance engineering that defines Gulf market positioning.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Puma |
| Under Armour |
| ASICS |
| New Balance |
| Skechers USA |
| Hoka One |
| Saucony |
| Others |
Cost & Logistics Intelligence
Dubai's logistics infrastructure anchors regional distribution capacity, compressing procurement timelines for hypermarket chains while concentrating pricing power among established suppliers with established hub operations. This geographic concentration shapes how thermal-performance footwear and climate-adaptive apparel flow through the six-nation bloc.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates SASO-certified heat-performance formulations from uncertified imports and generic mass-market alternatives. Pricing pressure stems from petrochemical input volatility affecting TPU and EVA resin costs, squeezing margin predictability for midsole manufacturers. Entry-level mass-participation program entrants exhibit highest price sensitivity, while competitive marathoners in temperature-controlled facilities demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Tariff exposure between East Asian manufacturing centers and Saudi Arabia dominates supply chain risk assessment for thermal-performance footwear imports. Production gravity centers on China, Vietnam, and South Korea for specialized midsole compounds and moisture-wicking textile formulations. Raw material dependencies include petroleum-derived TPU resins, synthetic fiber feedstocks, and graphene additive supplies. Single-source vulnerability concentrates in advanced energy-return foam formulations with limited qualified suppliers. Distribution runs through Dubai's re-export hubs into Riyadh and Doha retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
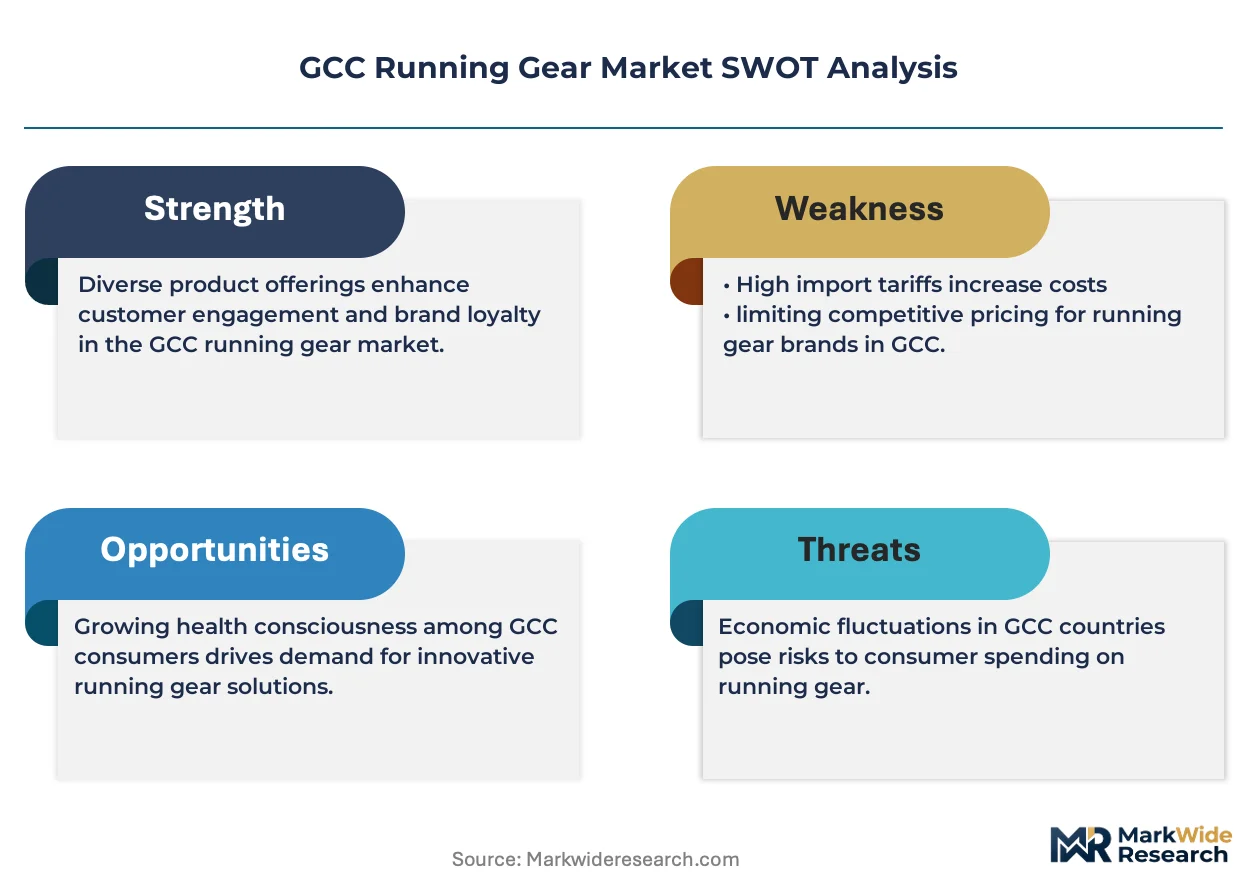
This market reads as a defensive-moat story anchored in regulatory entrenchment. SASO certification timelines and heat-performance testing protocols create structural barriers that protect incumbents with established compliance infrastructure.
For Market Incumbents: Entrench position through backward integration into specialized TPU compounding capabilities within the Gulf region, reducing petrochemical input volatility exposure. Deepen channel control by expanding dedicated running concept zones in hypermarket chains to combat online platform migration. Lock in institutional procurement contracts for Qatar's post-World Cup community facility conversions before competitive tendering intensifies. For New Entrants and Emerging Players: Establish a beachhead in Kuwait and Bahrain through direct-to-consumer platforms targeting intermediate runners seeking size-precision tools unavailable in conventional retail. Capture first-mover advantage in underpenetrated markets lacking the dedicated running infrastructure present in UAE and Saudi Arabia. Deploy climate-specific customization configurators as the primary go-to-market angle to bypass established retail concentration barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because certification entrenchment and heat-performance R&D capabilities compound competitive advantages over extended horizons. Acquisition targets should emphasize technical specialists with demonstrated SASO compliance track records and proprietary desert-climate material science. Monitor female participation rates under Saudi Vision 2030 as the critical inflection signal for demographic expansion and product mix rotation.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Heat-performance testing protocols from the Saudi Standards, Metrology and Quality Organization filter substandard imports and elevate compliant suppliers. |
| Direct-to-Consumer Platform Launch | Size-precision scanning and climate-specific configurators capture intermediate runners migrating away from hypermarket retail channels. |
| Desert-Climate R&D Partnership | Collaborations with technical textile laboratories accelerate heat-adaptive fabric development for government-backed wellness initiative tenders. |
| Post-World Cup Infrastructure Supply Agreement | Institutional procurement contracts for Qatar's stadium-to-community-facility conversions secure multi-year hydration system and apparel volume. |
| Regional TPU Compounding Capacity | In-house production of energy-return midsole materials reduces petrochemical input volatility and compresses launch timelines. |
Research Approach
Cross-validation between primary interviews with brand managers, category buyers at hypermarket chains, supply planners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from SASO certification databases, Gulf Standardization Organization textile benchmarks, customs and trade flow records, and SEC filings of multinational sportswear conglomerates. Bottom-up channel volume estimates and top-down macroeconomic sizing were reconciled through iterative triangulation.
Calibration against historical replacement cycle data and marathon participation trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, gender participation patterns, activity level sophistication, and distribution channel migration. CAGRs were derived from elasticity-adjusted demand curves incorporating temperature-controlled facility expansion and female participation targets. Forecast inputs included EVA-TPU formulation adoption curves and online platform penetration rates.
Stress conditions across petrochemical price volatility, certification timeline extensions, and desert terrain abrasion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding government-backed marathon program execution and post-World Cup infrastructure conversion schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Golf Club Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Running Gear Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
United States Archery Equipment Market