
 Pedometer Market | 2026-2036
Pedometer Market Size, Share, and Industry Trends Forecast 2026-2036
Pedometer Market Intelligence
The direct-to-consumer online retail channel is rewriting traditional distribution models for pedometers. Apple leverages its vast ecosystem to integrate step-counting functionalities into its smartwatches, capturing a significant user base. Garmin sustains its market position through specialized GPS-enabled devices targeting dedicated athletes. Fitbit, under Google, competes by offering a range of wearable devices focused on holistic health tracking and community features.
A pedometer is an electronic device that counts steps by detecting body motion, typically using a 3-axis accelerometer for enhanced accuracy. Its primary commercial purpose is to help individuals monitor and increase their physical activity levels. The market for wearable devices now subsumes much of the demand, eclipsing basic clip-on pedometer sales. Among end users, athletes prioritize GPS and Ant+ technology for performance metrics, while health-conscious individuals focus on smart pedometers with Bluetooth connectivity.
Market access depends on compliance with electronics regulations, including FCC Part 15 rules in the United States and CE marking requirements in the European Union. These standards govern radio frequency emissions and consumer safety, acting as critical gatekeepers for all manufacturers. Navigating the evolving landscape of data privacy, particularly regulations like Europe’s GDPR, will determine which device ecosystems earn long-term user trust and engagement.
Market Dynamics
The market's central dynamic is the functional absorption of step-counting into broader wearable technology ecosystems. This shift from dedicated, single-purpose devices to integrated smartwatch and fitness band functionalities redefines competitive boundaries and value propositions for manufacturers.
Growth Catalysts
- Corporate Wellness Programs:Adoption within corporate employee wellness initiatives, particularly in the United States and Germany, stimulates bulk purchasing of devices to encourage physical activity and potentially lower healthcare insurance premiums.
- Bluetooth Connectivity:The integration of low-energy Bluetooth technology enables seamless data synchronization with smartphone applications, enhancing user engagement through data visualization, trend analysis, and social sharing features that consumers now expect.
- Public Health Initiatives:Government-led health campaigns in countries like Germany and Japan, aimed at promoting active lifestyles among aging populations, create sustained demand for accessible and easy-to-use activity monitoring tools.
Market Restraints
- Smartwatch Cannibalization:The proliferation of smartwatches from consumer electronics giants, which include step-counting as a standard feature, erodes the market for basic, standalone pedometers that lack additional functionalities.
- Data Privacy Compliance:Navigating complex data privacy regulations, such as Europe’s GDPR, increases development costs and legal risks for manufacturers, particularly for devices that sync with cloud-based health platforms.
- Accelerometer Accuracy Limits:The reliance on accelerometers can lead to inaccuracies in step counting during non-walking activities like cycling or weight training, limiting the device's utility for users engaged in diverse fitness routines.
Strategic Opportunities
- Clinical Trial Integration:There is a significant opportunity in providing certified, medical-grade pedometers for use in clinical trials and remote patient monitoring, where data accuracy and reliability are paramount for pharmaceutical and healthcare providers.
- Emerging Economies:Targeting the growing health-conscious middle class in markets like India and Brazil with affordable, Bluetooth-enabled devices presents a substantial volume growth opportunity, bypassing the saturated high-end smartwatch segment.
- Sensor Fusion for Health Metrics:Combining step-counting with other sensors, such as for body temperature or hydration levels, in a single device offers a path to create more holistic personal health monitors for niche wellness markets.
Industry Challenges
- Electronics Certification Hurdles:Securing and maintaining compliance with radio frequency emission standards, such as FCC Part 15 in the US and CE marking in the EU, presents a continuous and costly operational challenge for all manufacturers.
- Component Sourcing Dependency:The reliance on a concentrated supply base for critical components like 3-axis accelerometers and microcontrollers creates vulnerability to supply chain disruptions and price volatility, impacting production schedules and margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedometer Market |
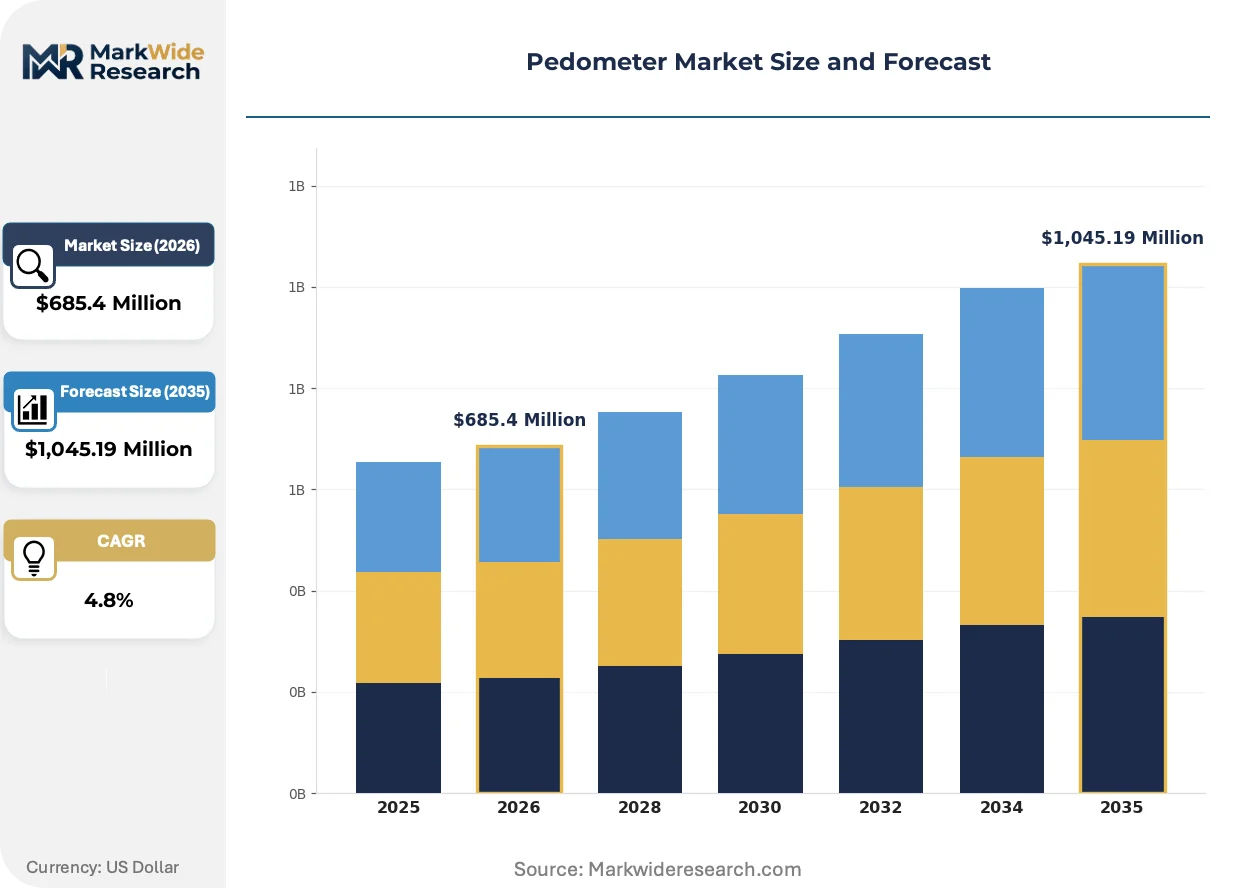
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pedometers, Basic Pedometers, Clip-On Pedometers, Wearable Devices Technology: Accelerometer, GPS, Bluetooth, Ant+ Technology End User: Fitness Enthusiasts, Health-Conscious Individuals, Athletes, Seniors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Fitness Centers |
| Companies Covered | Suunto, WHOOP, Fitbit, Amazfit, Google, Coros, Samsung, Garmin, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedometer Market Strategic Shifts & Innovations
Device evolution is defined by the transition from mere step quantification to comprehensive activity analysis. This movement reflects a deeper integration of sensor technology with sophisticated software algorithms to provide users with actionable health insights beyond simple motion detection.
GPS technology provides precise outdoor location, distance, and pace tracking, complementing accelerometer-based step counts. Serious athletes and outdoor enthusiasts rapidly adopt GPS-enabled wearables for detailed performance analysis. Consequently, the value proposition for premium pedometers is migrating from basic motion detection accuracy to providing sophisticated geospatial data for training optimization.
Europe's General Data Protection Regulation (GDPR) establishes stringent requirements for handling personal health information generated by wearables. This regulation is forcing manufacturers to implement robust data privacy frameworks, emphasizing user consent and transparency in their software ecosystems. Connected pedometer platforms are most affected, needing to invest in secure, compliant data architectures to operate within the EU.
A shift from one-time hardware transactions to subscription-based services for premium features is gaining momentum. This model supplements the initial device sale with recurring revenue from personalized coaching, advanced data analytics, and exclusive community content. The trend is most prominent among health-focused users in the United States, who value continuous engagement and guided wellness programs.
Pedometer Market Segmentation
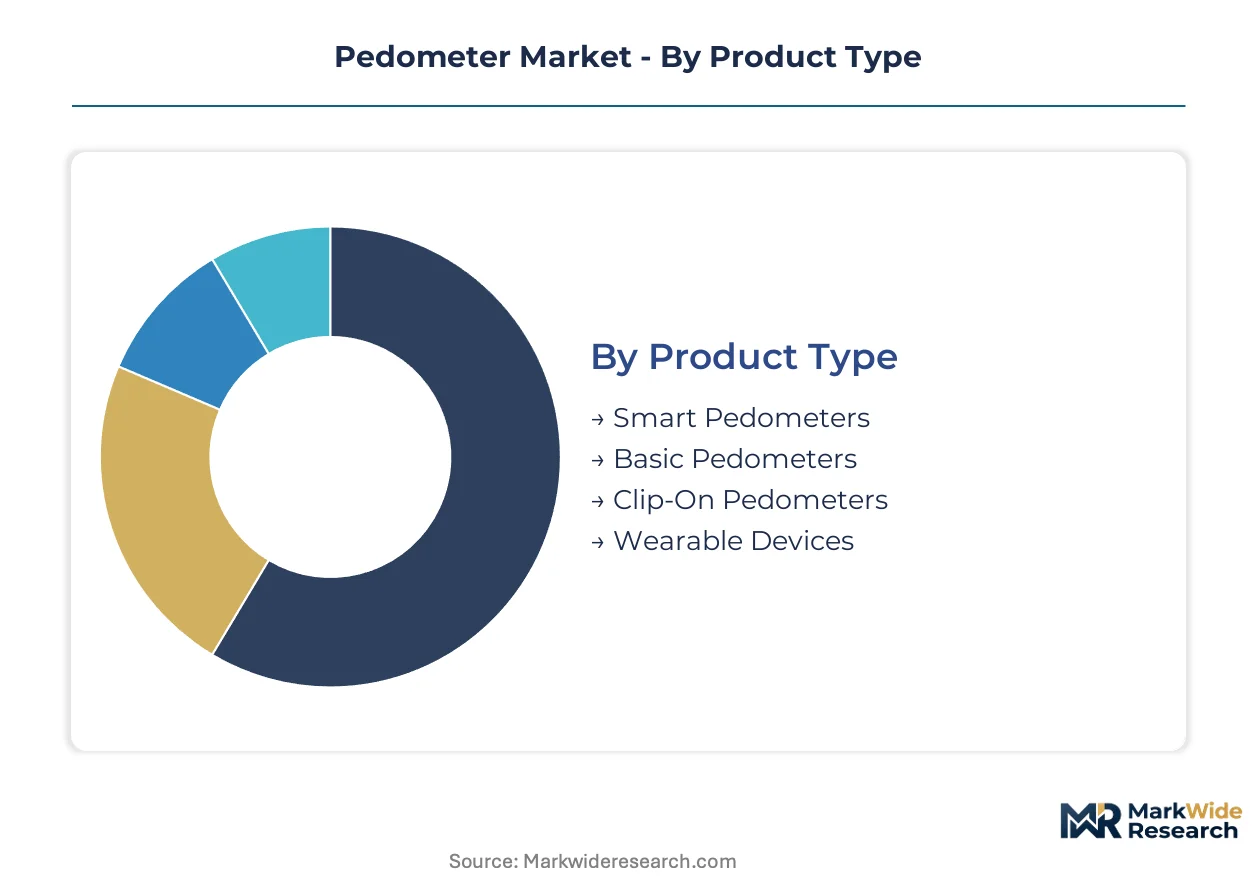
The pedometer market's segmentation provides a granular view of consumer preferences and technological advancements shaping product development and distribution strategies. Understanding these distinct segments allows manufacturers to tailor offerings to specific user needs, from basic step tracking to comprehensive health monitoring.
Product Type:
The pedometer market's product segmentation reflects a diverse use-case spectrum, ranging from fundamental step tracking to integrated health monitoring solutions.
- Wearable Devices:These devices integrate step-counting into broader health ecosystems, often including heart rate and sleep tracking, appealing to a wide user base. Demand concentrates in developed economies like the United States, driven by consumer preference for multi-functional gadgets.
- Smart Pedometers:These pedometers offer advanced connectivity, typically via Bluetooth, syncing data with smartphone applications for detailed analysis and enhanced user engagement. Corporate wellness programs in Germany stimulate bulk purchasing of these devices.
- Basic Pedometers:These devices provide fundamental step counting without advanced connectivity or additional health metrics, serving users with simple activity monitoring needs.
- Clip-On Pedometers:These traditional units attach to clothing, offering simple step quantification for users seeking a non-wearable, unobtrusive option.
The dominant share belongs to Wearable Devices, while Smart Pedometers are closing the gap fastest.
Technology:
Technology segmentation highlights the varying application focus, from core motion sensing to advanced data transmission and location services.
- Bluetooth:This low-energy wireless technology enables seamless data synchronization between pedometers and smartphone applications, enhancing user engagement through data visualization. Demand is strong across all health-conscious demographics, particularly in markets with high smartphone penetration.
- GPS:This technology provides precise outdoor location, distance, and pace tracking, complementing accelerometer data for detailed performance analysis. Athletes and outdoor enthusiasts in Europe prioritize GPS-enabled wearables for training optimization.
- Accelerometer:This 3-axis sensor detects body motion for step counting, forming the foundational technology for most pedometers.
- Ant+ Technology:This wireless protocol facilitates communication between fitness devices and sensors, primarily used by athletes for performance metrics and multi-device integration.
The most widespread adoption is seen in Accelerometer-based devices, with Bluetooth showing significant growth.
End User:
End-user segmentation differentiates consumers based on their primary motivation for activity tracking, from general well-being to competitive performance.
- Health-Conscious Individuals:These users seek devices for holistic health tracking, focusing on overall well-being, community features, and data visualization via connected platforms. Demand is particularly high in urban centers across the United States, driven by personal wellness trends.
- Athletes:This segment prioritizes advanced features like GPS and Ant+ technology for precise performance metrics, training optimization, and recovery monitoring. Germany's dedicated sports community represents a strong market for these specialized devices.
- Fitness Enthusiasts:This group uses pedometers to monitor and improve general physical activity levels and daily step counts, often integrating them into broader fitness routines.
- Seniors:This demographic benefits from accessible activity monitoring tools, often encouraged by public health initiatives in countries like Japan aimed at promoting active lifestyles.
While Health-Conscious Individuals represents the largest user base, Athletes exhibit strong demand for specialized functionalities.
Distribution Channel:
Distribution channel segmentation illustrates the primary market access points for pedometers, reflecting evolving consumer purchasing habits.
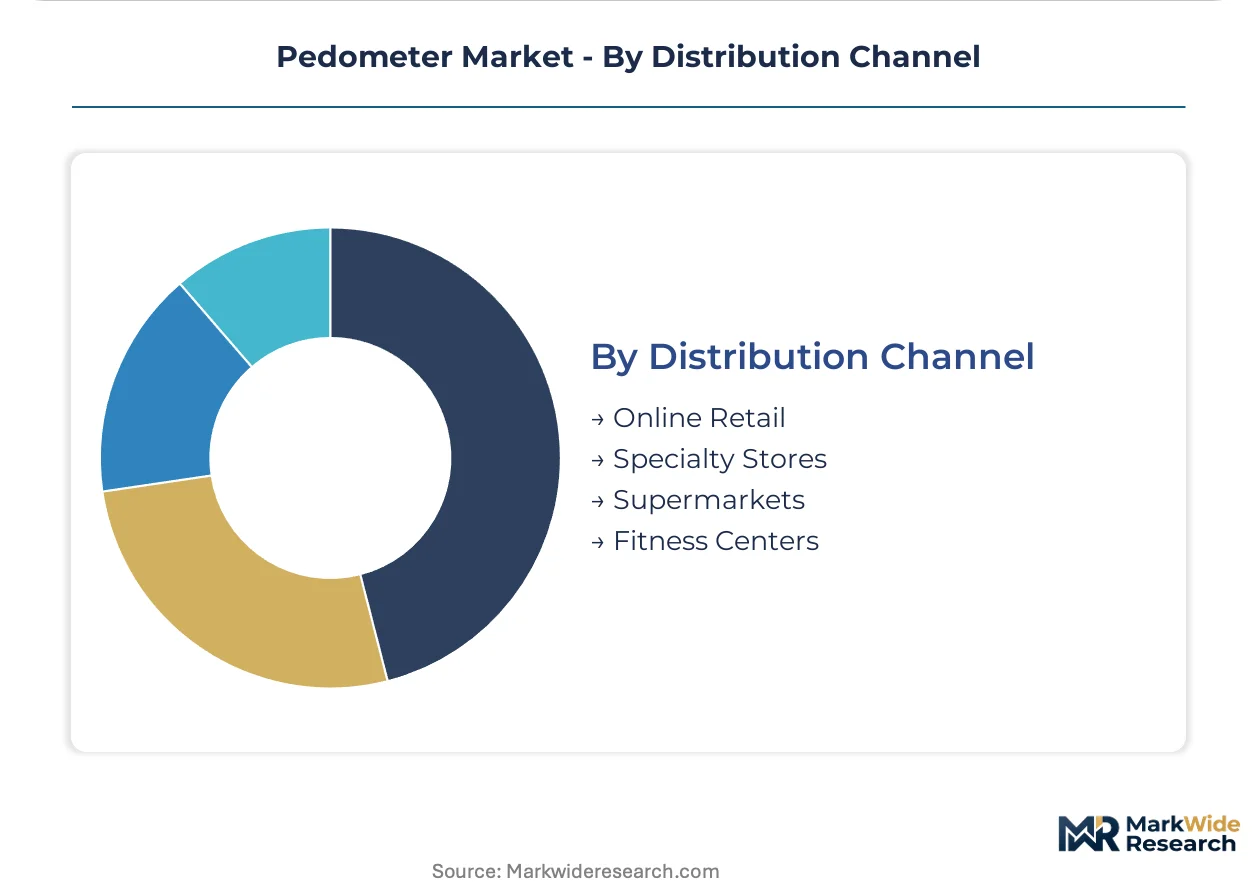
- Online Retail:This channel is rewriting traditional distribution models, offering direct-to-consumer sales and a wide product selection with competitive pricing. The United States and European markets show a strong preference for online purchases due to convenience.
- Specialty Stores:These outlets cater to dedicated athletes and fitness enthusiasts, providing expert advice and a curated selection of high-performance pedometers and wearables. Germany's robust sports retail sector supports this channel.
- Supermarkets:These mass-market retailers offer basic pedometers as impulse buys, targeting general consumers seeking simple activity trackers without advanced features.
- Fitness Centers:These venues may offer pedometers as part of membership packages or for sale, integrating them into wellness programs and encouraging member activity.
The shift towards Online Retail is evident, though Specialty Stores maintain importance for targeted sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health initiatives and corporate wellness programs drive pedometer market expansion across diverse geographies. Governments and employers recognize the value of activity monitoring tools in promoting healthier lifestyles and managing healthcare costs. Regulatory frameworks for electronics and data privacy also shape market access and product development in key regions.
United States
Corporate wellness programs and a strong health-conscious consumer base fuel demand for smart pedometers and integrated wearables. The Federal Communications Commission (FCC) Part 15 rules govern radio frequency emissions for these devices, ensuring market compliance. Silicon Valley and other tech hubs like Austin continue to innovate in wearable technology and connected health platforms.
Germany
Public health initiatives promoting physical activity among its aging population stimulate demand for accessible activity monitoring tools. CE marking requirements are mandatory for electronics sold in the European Union, including pedometers, ensuring product safety. Munich and Berlin are centers for medical technology and digital health startups that integrate pedometer functionalities.
Japan
Government-led health campaigns targeting an aging demographic create sustained demand for easy-to-use activity monitoring devices. Japan's Ministry of Economy, Trade and Industry (METI) oversees industrial standards, including those for consumer electronics. Tokyo and Kyoto host numerous electronics manufacturers and research institutions focused on health-tech innovation.
India
A rapidly expanding health-conscious middle class represents a significant growth opportunity for affordable, Bluetooth-enabled pedometers. The Bureau of Indian Standards (BIS) sets quality and safety standards for electronic goods, influencing market entry. Bangalore and Mumbai are emerging as hubs for digital health solutions and wearable technology development.
United Kingdom
High smartphone penetration and a growing interest in personal fitness apps support the adoption of connected pedometers. The UK Conformity Assessed (UKCA) marking ensures products meet British regulatory requirements for electronic devices. London's vibrant tech scene fosters companies developing integrated health and wellness platforms.
Pedometer Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with large technology conglomerates alongside specialized fitness brands. This market structure reflects the functional absorption of step-counting into broader wearable technology ecosystems. Strategic archetypes include diversified consumer electronics giants, dedicated fitness device manufacturers, and niche health monitoring solution providers. Portfolio diversification into holistic health tracking and strategic partnerships with software platforms represent dominant competitive moves.
Among technology giants and specialized device manufacturers, Apple and Google exemplify companies leveraging vast ecosystems to integrate step-counting into their smartwatches and health platforms. Garmin represents the archetype of a specialized brand, sustaining its market position through GPS-enabled devices targeting dedicated athletes. These companies navigate a landscape where product differentiation increasingly relies on software features, data analytics, and compliance with data privacy regulations like Europe’s GDPR.
| Leading Market Players |
|---|
| Suunto |
| WHOOP |
| Fitbit |
| Amazfit |
| Coros |
| Samsung |
| Garmin |
| Apple |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized sensor production drives component supplier behavior and influences final pedometer device pricing. This dynamic shapes the competitive landscape for both established manufacturers and new market entrants.
Pricing Analysis
Volume-discount tiering structures influence procurement for pedometers across various segments. The market primarily operates on a transactional model for devices, augmented by subscription-based services for advanced analytics and personalized coaching. Price differentiation stems from medical-grade certification and established brand reputation, with Apple and Garmin leveraging strong ecosystems. Pricing softness impacts basic pedometers due to smartwatch cannibalization. Seniors and consumers in emerging economies exhibit higher price sensitivity, while corporate wellness programs prioritize feature sets.
Supply Chain Analysis
Extended payment terms for key components characterize the pedometer supply chain, impacting smaller manufacturers. Component manufacturing concentrates in East Asia, particularly China, Taiwan, and South Korea, for critical elements like 3-axis accelerometers and microcontrollers. The industry relies heavily on a concentrated supply base, creating single-source vulnerability to disruptions. Downstream distribution primarily occurs through online retail channels, complemented by specialty stores catering to dedicated athletes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pedometer market presents a defensive-moat story, primarily driven by regulatory entrenchment for medical-grade devices. This creates significant barriers for new entrants.
For Market Incumbents: Build regulatory moats through investment in medical device certification for clinical trials and remote patient monitoring. Incumbents should expand their software ecosystems to counter smartwatch cannibalization from technology giants. Invest in R&D for sensor fusion to provide holistic health metrics, differentiating from basic step counters. This strategy defends against emerging entrants offering simplified, low-cost alternatives.
For New Entrants and Emerging Players: Affordable, Bluetooth-enabled devices for emerging economies like India and Brazil represent the most penetrable entry point. Focus on basic step counting with robust application integration for general fitness enthusiasts and health-conscious individuals. A direct-to-consumer online retail strategy enables rapid market access and avoids traditional distribution hurdles, targeting underserved populations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers offering subscription-based premium features and advanced data analytics. The long-term viability favors platforms with strong data privacy frameworks and certified medical applications, ensuring user trust. Target acquisition archetypes include specialized sensor technology firms or regional health-tech platforms with strong intellectual property. Watch for increasing clinical trial integration as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Integration | Secures data accuracy and reliability for pharmaceutical and healthcare providers. |
| Software Ecosystem Expansion | Enhances user engagement and retention against diversified tech giants. |
| Sensor Fusion Development | Creates more holistic personal health monitors for niche wellness markets. |
| Emerging Market Penetration | Captures volume growth from health-conscious middle classes in India and Brazil. |
| Data Privacy Framework Investment | Builds user trust and ensures compliance with regulations like GDPR. |
Research Approach
Initial hypotheses were tested against primary input from product development leads, corporate wellness program managers, sports medicine professionals, and regulatory compliance officers. This primary research was validated through extensive secondary data, including FCC filings, CE marking documentation, academic studies on activity tracking, and patent databases. A rigorous bottom-up and top-down triangulation approach ensured data consistency across the market.
Demand-supply balance models underpin the forecast framework across the analysis window. Segmentation dimensions including product type, technology, end user, distribution channel, and regional regulatory environment were integrated. Compound annual growth rates were derived from historical trends and projected market drivers. Key forecast inputs included global smartphone penetration rates and corporate wellness program enrollment figures.
Macroeconomic conditions sit as an overlay; deviation in global consumer spending or interest rates would shift the trajectory. Forecasts reflect current assumptions regarding component supply chain stability and evolving data privacy regulations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Australia Wearables Market