
 Wearable Fitness Tracker Market | 2026-2036
Wearable Fitness Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Fitness Tracker Market Intelligence
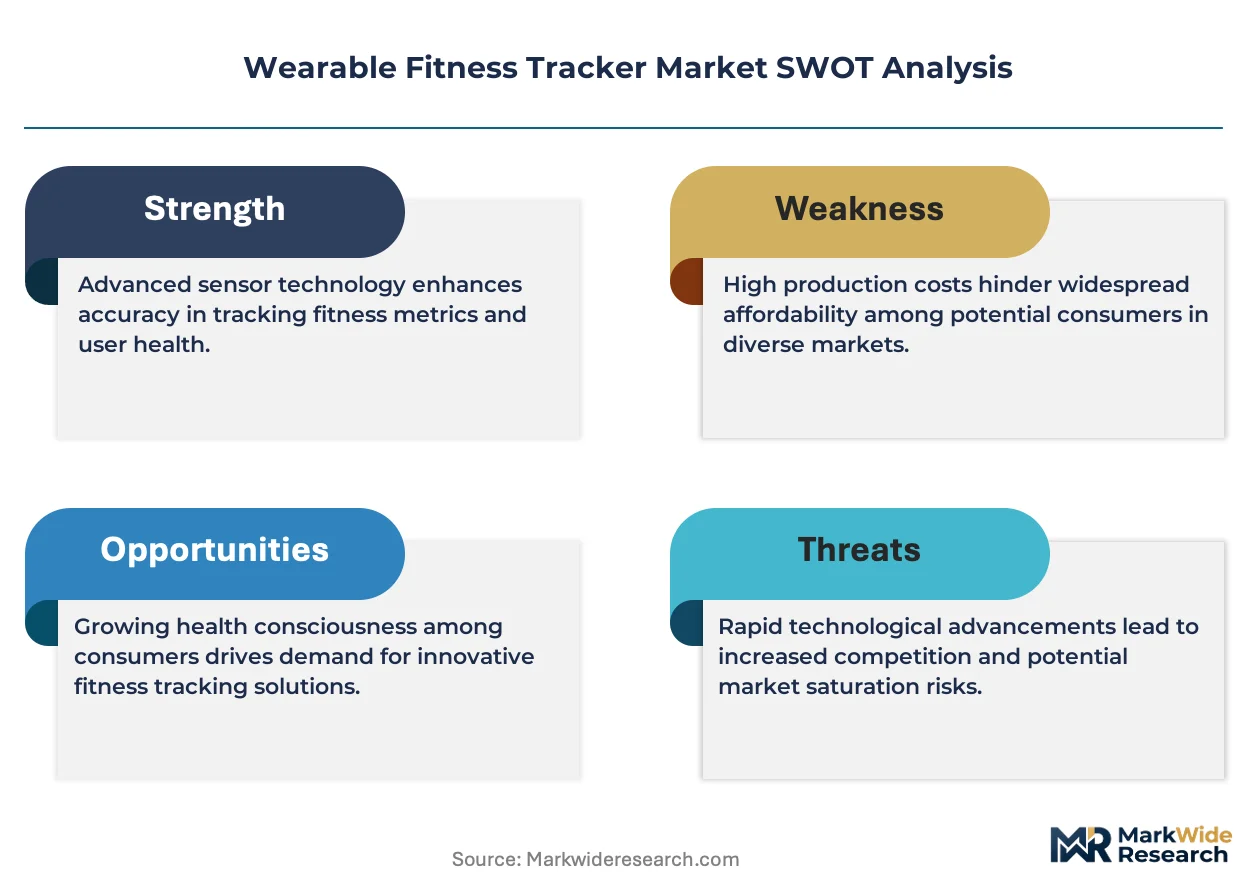
The integration of advanced biometric sensors for continuous health monitoring is rewriting product development priorities. This shift emphasizes medical-grade accuracy and long-term data tracking over simple activity counting. Apple leverages its vast ecosystem to dominate the premium smartwatch space. Garmin sustains its leadership in specialized GPS-enabled devices for athletes, while Oura differentiates with its focus on sleep and recovery analytics.
A wearable fitness tracker is an electronic device designed to monitor and record fitness-related metrics using sensors like 3-axis accelerometers and optical heart rate monitors. Its primary purpose is to provide users with data for tracking physical activity, sleep patterns, and other health indicators. Smartwatches represent the largest product type segment by value. However, applications like sleep monitoring and stress management are the fastest-growing categories, driving innovation in sensor technology.
Data privacy and device classification are key regulatory hurdles. The EU's GDPR imposes strict rules on handling personal health data collected by trackers. Concurrently, the US FDA scrutinizes devices that offer features like ECG or Afib detection, potentially classifying them as medical devices. Navigating the evolving boundary between consumer wellness and regulated diagnostics is a central strategic challenge for all vendors.
Market Dynamics
The convergence of consumer wellness gadgets with regulated medical monitoring equipment defines the market's central dynamic. This shift is driven by the integration of clinical-grade sensors, forcing manufacturers to navigate a complex path between feature innovation and stringent health data regulations.
Growth Catalysts
- Corporate Wellness Initiatives:The adoption of fitness trackers within corporate wellness programs to promote employee health and reduce insurance premiums provides a significant B2B sales channel and encourages daily user engagement.
- Advanced Sensor Integration:The incorporation of technologies like SpO2, ECG, and skin temperature sensors expands device utility beyond simple activity tracking, appealing to users seeking comprehensive health monitoring capabilities.
- Health Awareness in Emerging Economies:A rising, health-conscious middle class in countries like India and Brazil is creating strong demand for accessible personal health monitoring tools, expanding the consumer base.
Market Restraints
- Data Privacy and Security Concerns:Strict regulations like the EU's GDPR impose significant compliance burdens on handling sensitive personal health data, increasing operational costs and limiting data utilization strategies for vendors.
- Battery Life Limitations:The energy consumption of continuous monitoring sensors and bright displays remains a technical barrier, constraining the development of smaller form factors and impacting user convenience.
- Substitution by Smartphones:Increasingly sophisticated health tracking apps on smartphones, which leverage onboard sensors, present a low-cost substitute for basic activity monitoring, pressuring the entry-level tracker segment.
Strategic Opportunities
- Niche Application Development:There is an opportunity to create specialized devices and algorithms for underserved segments, such as remote patient monitoring for chronic conditions or performance analytics for specific sports.
- Mental Wellness Monitoring:Integrating sensors and software for tracking stress, mindfulness, and mental well-being through metrics like heart rate variability (HRV) opens a new, high-growth application category.
- Insurance and Healthcare Partnerships:Collaborating with insurance providers and healthcare systems to use wearable data for preventative care, risk assessment, and patient engagement can create new, stable revenue models.
Industry Challenges
- Medical Device Certification Pathways:Navigating the complex and lengthy approval processes of bodies like the US FDA and European regulators for features classified as medical diagnostics presents a major hurdle for product development timelines.
- Data Interoperability Standards:A lack of universal standards for data sharing between different wearable ecosystems, mobile apps, and electronic health records (EHRs) fragments the user experience and limits clinical utility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Fitness Tracker Market |
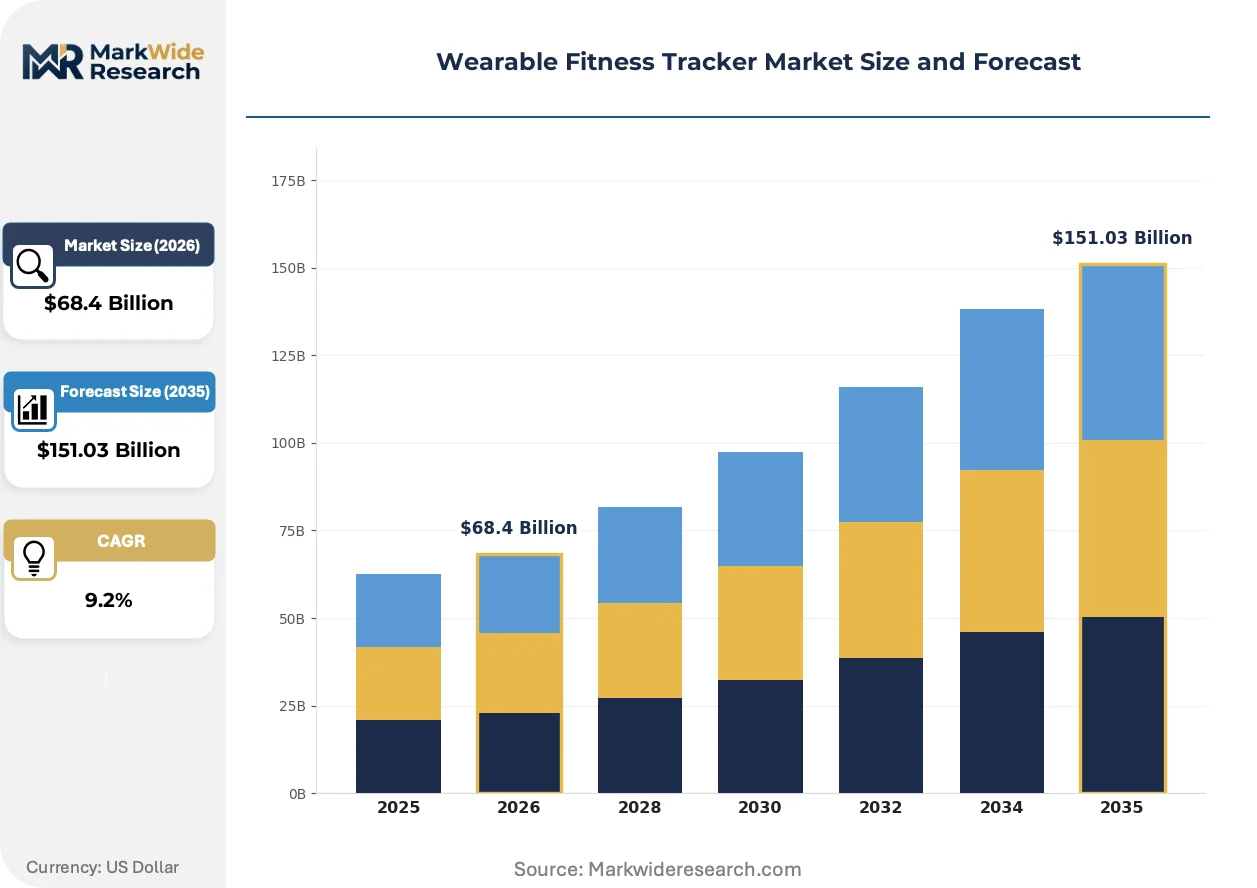
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $151.03 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
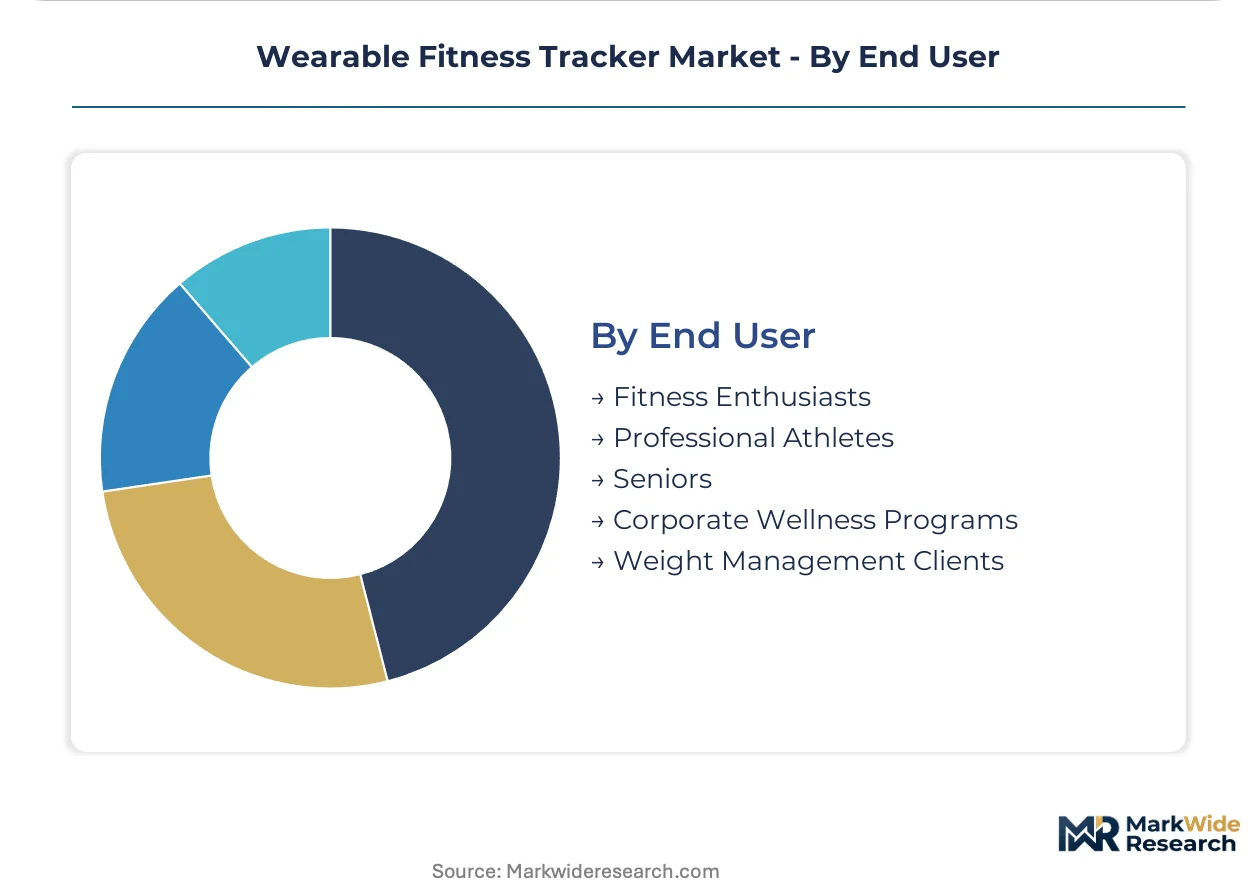
| Segmentation | Product Type: Smartwatches, Fitness Bands, Chest Straps, Clip-on Trackers, Ear-worn Devices Technology: Accelerometer, Gyroscope, Heart Rate Sensor, GPS, SpO2 Sensor, NFC Application: Activity Tracking, Sleep Monitoring, Stress Management, Heart Health, Calorie Counting, VO2 Max Estimation End User: Fitness Enthusiasts, Professional Athletes, Seniors, Corporate Wellness Programs, Weight Management Clients |
| Companies Covered | Samsung, Oura, Fitbit, Amazfit, Xiaomi, Garmin, Whoop, Huawei, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Fitness Tracker Market Strategic Shifts & Innovations
Product development is shifting from passive data collection toward proactive, personalized health management. This evolution transforms the wearable device from a simple tracker into an intelligent health companion, driven by software, advanced analytics, and new service models.
The development of non-invasive sensors for metrics like blood glucose and blood pressure is a primary focus of R&D. Consumers with chronic conditions and those focused on preventative health are driving demand for these next-generation capabilities. Progress in this area is rendering obsolete the need for separate, often invasive, medical devices for routine monitoring, integrating these functions directly into everyday wearables.
Regulatory frameworks are adapting to the rise of software as a medical device. The US FDA's Digital Health Software Precertification Program, for example, aims to streamline review for trusted developers, creating a faster pathway for new diagnostic features. This shift benefits established vendors with proven quality management systems, allowing them to accelerate the deployment of regulated functionalities like arrhythmia detection.
A notable behavioral change is the growing consumer acceptance of subscription-based services for advanced analytics. This model supplements the one-time hardware sale with recurring revenue by unlocking personalized coaching, in-depth health reports, and trend analysis. This trend is most visible in specialized applications like sleep and recovery optimization, where users pay for deeper insights derived from their biometric data.
Wearable Fitness Tracker Market Segmentation
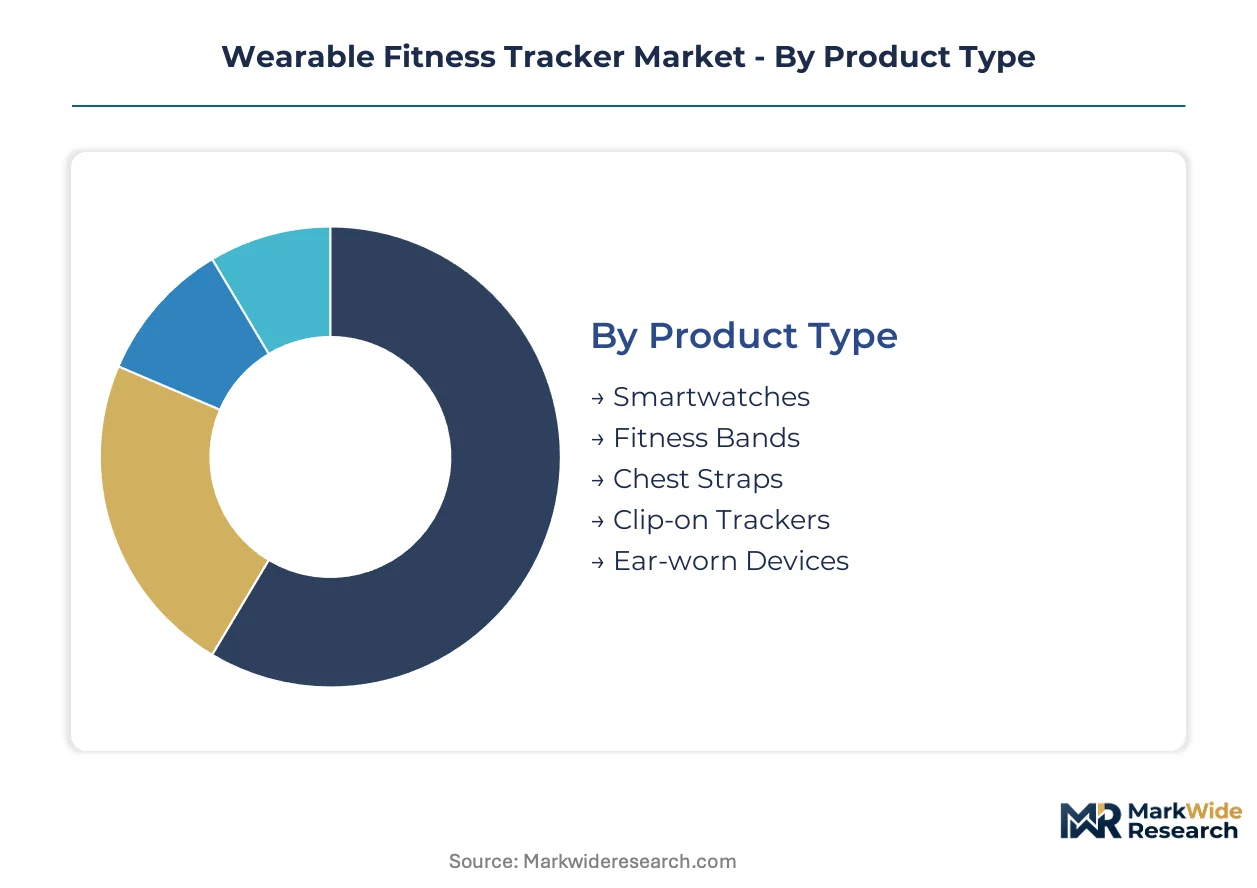
Understanding the distinct segments within the wearable fitness tracker market is crucial for strategic positioning and product development. Each category presents unique value propositions and addresses specific consumer needs, influencing market dynamics and competitive landscapes. Manufacturers must tailor their offerings to capture diverse user preferences and technological requirements.
Product Type:
After-sales service intensity varies significantly across product types, influencing customer loyalty and long-term revenue streams for manufacturers.
- Smartwatches:These advanced wrist-worn devices integrate comprehensive health tracking with communication and app functionalities. Demand concentrates in developed economies, driven by tech-savvy consumers seeking integrated digital lifestyles.
- Fitness Bands:Simpler, often screen-less or small-screen devices primarily focused on activity and sleep tracking. Emerging economies like India show strong demand for these accessible and cost-effective personal health monitoring tools.
- Chest Straps:Designed for highly accurate heart rate monitoring, these devices are typically used during intense physical activity. Professional athletes and serious fitness enthusiasts utilize these for precise performance data.
- Clip-on Trackers:These compact devices offer basic activity tracking and are often favored for their discreet wearability. Casual users seeking simple step counting find these an unobtrusive option.
- Ear-worn Devices:Integrating biometric sensors into headphones, these offer heart rate and activity tracking with audio functionality. Consumers value the convenience of combined entertainment and health monitoring.
Smartwatches holds the largest share; momentum sits with Ear-worn Devices.
Technology:
The cost tier of wearable fitness trackers is heavily influenced by the sophistication and integration of various sensor technologies.
- Heart Rate Sensor:Optical sensors measure blood flow changes to determine heart rate, a fundamental metric for fitness and health monitoring. This technology is essential for most modern wearable devices.
- SpO2 Sensor:This sensor measures blood oxygen saturation levels, offering insights into respiratory health and sleep quality. Clinical-grade SpO2 integration enhances device capabilities for advanced health monitoring.
- Accelerometer:A core sensor detecting motion and orientation, enabling step counting, activity recognition, and sleep pattern analysis. It forms the basis for basic activity tracking in all wearable devices.
- Gyroscope:Measures angular velocity and rotation, complementing accelerometers for more precise movement and gesture recognition. This sensor improves accuracy in sports tracking and fall detection.
- GPS:Integrated for precise location tracking, enabling distance, pace, and route mapping for outdoor activities. Athletes rely on GPS for detailed performance analytics during running and cycling.
- NFC:Near Field Communication allows for contactless payments and quick pairing with other devices. This feature enhances convenience for users in daily transactions and device interactions.
SpO2 Sensor technology is expanding most quickly, while Heart Rate Sensor maintains significant market presence.
Application:
The utility and market penetration of wearable fitness trackers are defined by their specific health and wellness application capabilities.
- Sleep Monitoring:Tracks sleep stages, duration, and quality, providing insights into recovery and rest patterns. Users increasingly seek advanced analytics for optimizing their sleep health.
- Stress Management:Utilizes heart rate variability (HRV) and other metrics to assess stress levels and guide relaxation techniques. This application category addresses a growing consumer focus on mental well-being.
- Activity Tracking:Records steps, distance, calories burned, and active minutes, serving as the foundational feature for most fitness trackers. This remains a primary driver for initial consumer adoption.
- Heart Health:Includes features like ECG and continuous heart rate monitoring for detecting arrhythmias and other cardiac conditions. The US FDA scrutinizes these devices for medical classification.
- Calorie Counting:Estimates energy expenditure based on activity levels and biometric data, aiding in weight management and fitness goals. This function supports users in maintaining dietary awareness.
- VO2 Max Estimation:Calculates the maximum oxygen uptake during exercise, indicating cardiovascular fitness levels. Professional athletes and serious fitness enthusiasts use this metric for performance assessment.
The Sleep Monitoring application category is gaining share fastest, with Activity Tracking representing a foundational utility.
End User:
Targeting specific end-user segments allows manufacturers to develop tailored features and marketing strategies for wearable fitness trackers.
- Corporate Wellness Programs:Businesses integrate trackers to promote employee health, reduce healthcare costs, and improve productivity. This B2B channel provides a stable sales pipeline for vendors.
- Seniors:This demographic utilizes trackers for health monitoring, fall detection, and emergency alerts. Preventative care and remote patient monitoring drive demand in this segment.
- Fitness Enthusiasts:Individuals committed to regular exercise use trackers for performance optimization, progress tracking, and motivation. They seek detailed metrics and advanced analytics.
- Professional Athletes:Elite sportspeople rely on specialized trackers for highly accurate performance data, recovery monitoring, and injury prevention. Garmin sustains leadership in this specialized niche.
- Weight Management Clients:Individuals focused on losing or maintaining weight use trackers to monitor calorie expenditure and activity levels. These users benefit from data-driven behavioral change support.
Corporate Wellness Programs shows the steepest expansion trajectory, while Fitness Enthusiasts secure a substantial user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wearable fitness trackers concentrates in health-conscious consumer segments across diverse geographies. Corporate wellness initiatives also drive B2B adoption, shaping regional market dynamics. Emerging economies exhibit strong interest in accessible personal health monitoring tools.
United States
The United States market showcases strong demand for advanced health monitoring features, especially ECG and Afib detection. The US FDA scrutinizes medical-grade functionalities, influencing product development pathways for vendors. Silicon Valley remains a hub for innovation, with numerous startups pushing sensor technology boundaries and software integrations.
India
India's burgeoning middle class drives significant demand for cost-effective fitness bands and basic activity trackers. The Bureau of Indian Standards (BIS) ensures product quality and safety for consumer electronics sold domestically. Bengaluru's tech ecosystem fosters local development, adapting devices for regional health needs and user preferences.
Germany
German consumers prioritize data privacy and robust health insights from their wearable devices. The EU's GDPR imposes strict regulations on personal health data handling, significantly impacting vendor compliance and operational strategies. Munich's medical technology cluster integrates wearables into broader digital health solutions and preventative care programs.
China
China's vast consumer base creates substantial demand for smartwatches and integrated health ecosystems. The National Medical Products Administration (NMPA) regulates devices with diagnostic capabilities, influencing market entry and product features. Shenzhen's manufacturing prowess supports rapid product iteration and scale for domestic brands and global players.
Japan
Japanese users seek sophisticated health tracking, particularly for sleep quality and stress management applications. The Ministry of Economy, Trade and Industry (METI) promotes digital health innovation and standardization across the consumer electronics sector. Tokyo's dense urban environment fosters demand for compact, feature-rich wearable designs that blend seamlessly into daily life.
Wearable Fitness Tracker Market Key Industry Players
Channel-controlling players compete with product-specialist players across the wearable fitness tracker market. The market exhibits a tiered structure, with premium smartwatches at one end and basic fitness bands at the other, catering to diverse consumer budgets. Strategic archetypes include integrated ecosystem providers, specialized athletic device manufacturers, and wellness-focused innovators. Portfolio diversification, often through advanced sensor integration, and strategic partnerships with healthcare providers are dominant competitive moves among market participants.
Integrated ecosystem providers like Apple exemplify market leadership in the premium smartwatch segment, leveraging extensive brand loyalty and seamless device integration. These players often occupy a position of broad consumer appeal, offering comprehensive digital lifestyle solutions. Specialized athletic device manufacturers such as Garmin anchor the niche for GPS-enabled trackers, catering to serious sports enthusiasts and professional athletes with robust performance data. Oura represents a wellness-focused innovator, concentrating on advanced sleep and recovery analytics to differentiate its offering and attract users prioritizing holistic health insights.
| Leading Market Players |
|---|
| Samsung |
| Oura |
| Fitbit |
| Amazfit |
| Xiaomi |
| Garmin |
| Whoop |
| Huawei |
| Apple |
| Others |
Cost & Logistics Intelligence
Shenzhen's manufacturing prowess influences global pricing for entry-level fitness trackers. Its high-volume production capabilities enable cost-effective device manufacturing, impacting consumer pricing across various markets.
Pricing Analysis
Cost-plus contracts with raw material indexation often define pricing for B2B bulk orders of wearable components. Brand premium and certification level, such as FDA-cleared features, drive price differentiation within the market. Pricing pressure stems from intense competition in the basic fitness band segment, particularly from Asian manufacturers. Consumers in emerging economies are most price-sensitive, while professional athletes prioritize feature sets over cost.
Supply Chain Analysis
Export control regimes, particularly those impacting semiconductor components, can limit the flow of advanced sensor technologies. China, Vietnam, and Malaysia are key manufacturing hubs for wearable device components. Semiconductor chips, specialized sensors, and rare earth elements for batteries are critical inputs. Geopolitical tensions and trade restrictions pose a structural risk, particularly for advanced sensor components. Distribution runs through a mix of e-commerce platforms, consumer electronics retailers, and B2B channels for corporate wellness programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable fitness tracker market is in an early-cycle expansion phase, driven by increasing health awareness in emerging economies. This creates opportunities for innovation and market penetration across diverse user segments.
For Market Incumbents: Harden existing ecosystem advantages by integrating medical-grade features and software. Invest in FDA certification pathways for advanced diagnostics to counter new entrant feature creep. Expand B2B partnerships with corporate wellness programs to secure stable revenue against smartphone substitution. Deepen R&D into non-invasive sensor technologies for long-term differentiation.
For New Entrants and Emerging Players: Pursue niche application development for underserved segments like remote patient monitoring for chronic conditions. The mental wellness monitoring category represents the most penetrable segment, leveraging HRV and stress analytics. Partner with specialized healthcare providers for clinical validation and go-to-market access. Focus on subscription-based service models to build recurring revenue streams beyond hardware sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized sensor developers and AI-driven analytics platforms with strong IP portfolios. Long-term viability rests on integrating wearables into preventative care and regulated diagnostics. Target acquisition profiles include firms with proven clinical-grade sensor technology or established healthcare system partnerships. The signal to watch is regulatory clarity on software as a medical device, which will accelerate market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introduce new wearables with non-invasive blood glucose monitoring capabilities. |
| Strategic Partnership | Collaborate with insurance providers to integrate wearable data for risk assessment. |
| Regulatory Approval Pathway | Secure FDA or CE marking for advanced diagnostic features like Afib detection. |
| Acquisition of Specialist Firm | Acquire a company with patented skin temperature sensing technology. |
| Platform Integration | Develop APIs for seamless data exchange with electronic health records (EHRs). |
Research Approach
Desk research of academic journals, patent filings, and regulatory guidelines preceded structured interviews with product development leads, health insurance executives, and medical device engineers. This approach combined primary insights with secondary validation. Bottom-up data collection and top-down market sizing informed the overall analysis.
Assumptions regarding sensor technology advancements and regulatory classifications were held constant over the projection horizon. The analytical framework modeled market growth across product types, applications, and end-user segments. CAGRs were derived from historical data trends and projected adoption rates. Key forecast inputs included consumer health spending and corporate wellness program enrollment.
Sensitivities concentrate around unforeseen regulatory changes regarding medical device classification and rapid shifts in core component pricing. Forecasts reflect assumptions documented at the time of analysis. Material shifts in data privacy legislation or critical sensor supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Wearable Sensors Market