
 North America Smart Watch Market | 2026-2036
North America Smart Watch Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Watch Market Analytics
Premium health-monitoring specifications is redrawing competitive boundaries in the North America smart watch landscape. Apple Inc. leverages its vertical integration across silicon and health software to sustain pricing power in clinical-grade wearables. Samsung Electronics Co., Ltd. anchors its position through diversified Android compatibility and manufacturing scale across North American retail channels. Garmin Ltd. specializes in GPS-dominant sports applications, occupying a defensible niche against generalist competitors.
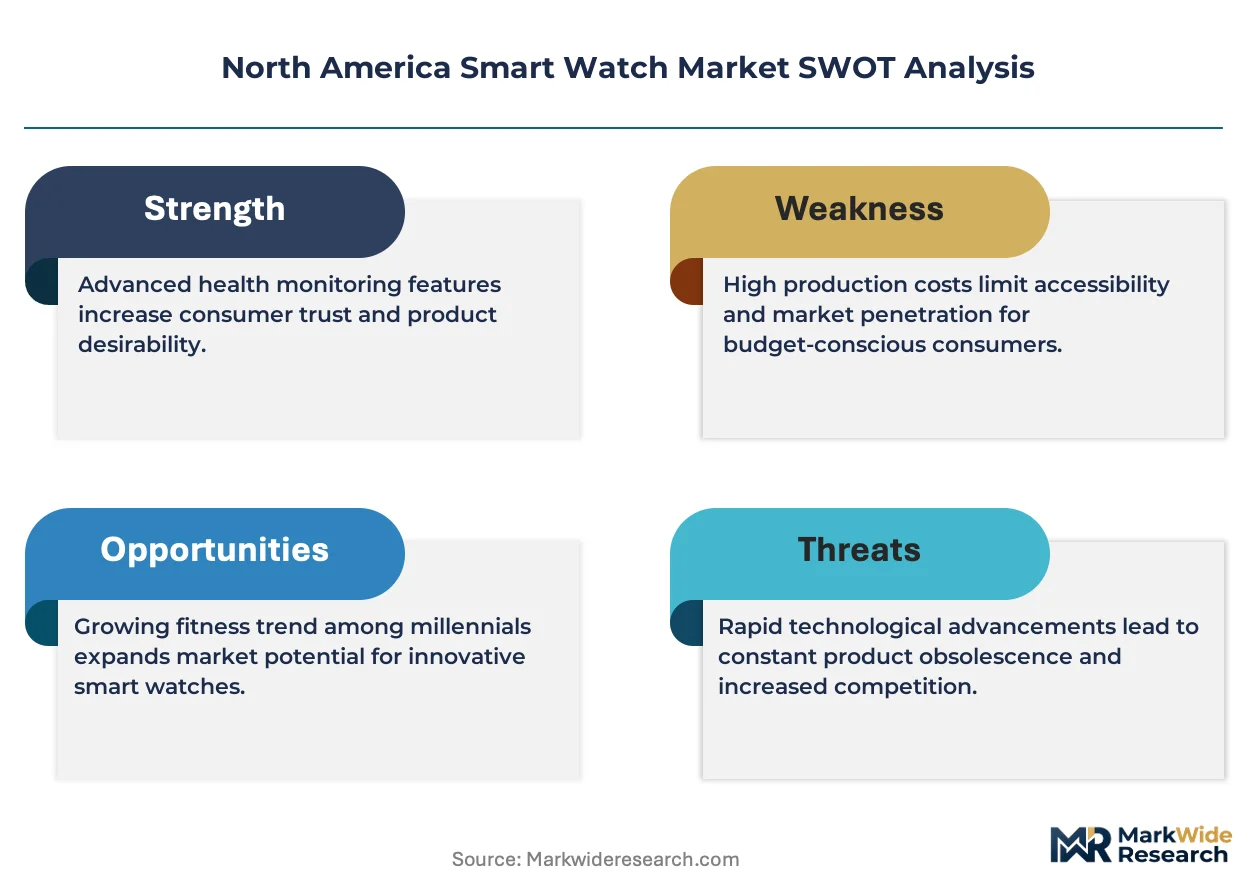
A smart watch is a wrist-worn computing device incorporating microprocessors, biometric sensors, wireless transceivers, and rechargeable power systems to deliver timekeeping, health monitoring, and notification functions. These devices typically integrate photoplethysmography sensors for heart rate detection, accelerometers for motion capture, and low-energy Bluetooth protocols for smartphone tethering, serving both consumer wellness and clinical remote monitoring objectives. Sports smartwatch configurations lead North American volume due to GPS tracking integration and extended battery architectures demanded by outdoor enthusiasts. Fitness tracker segments face margin compression as hybrid smartwatch designs absorb step-counting functionality at higher price points. NFC-enabled payment authentication is emerging as a technology differentiator, with contactless transit and retail integration expanding utility beyond health applications.
FDA regulates medical device claims for smart watches through its 510(k) premarket notification pathway, compelling manufacturers to validate algorithm accuracy before marketing cardiac arrhythmia detection features. FCC governs radio frequency emissions and wireless certification, while state-level privacy statutes in California and Illinois impose biometric data consent requirements that shape firmware design and cloud storage architectures. Stakeholders must monitor evolving FDA guidance on continuous glucose monitoring integration and state attorney general enforcement patterns around consumer health data monetization.
Market Dynamics
FDA's 510(k) premarket notification pathway for cardiac arrhythmia detection algorithms is forcing manufacturers to validate clinical-grade accuracy before commercializing health-monitoring features, compressing development timelines while elevating technical barriers to entry.
Growth Catalysts
- Remote patient monitoring expansion:Healthcare providers across the United States and Canada are scaling chronic disease management programs that reimburse wearable-derived biometric data, creating institutional demand for FDA-cleared devices.
- State biometric privacy statutes:California's Consumer Privacy Act and Illinois' Biometric Information Privacy Act mandate explicit consent frameworks, which device manufacturers are converting into competitive trust signals for enterprise wellness contracts.
- Photoplethysmography sensor maturation:Optical heart rate monitoring accuracy improvements are enabling clinical-grade arrhythmia detection without invasive hardware, expanding addressable use cases from fitness tracking to diagnostic support.
Market Restraints
- Advanced sensor input cost volatility:Specialized photodiodes and accelerometer MEMS fabrication depends on concentrated semiconductor foundry capacity, exposing margins to wafer pricing swings.
- Clinical validation timeline friction:FDA algorithm accuracy studies for arrhythmia detection require multi-thousand-patient cohorts, extending time-to-revenue for new health features by 18-24 months relative to consumer-grade launches.
- Smartphone tethering dependency:Core notification and data synchronization functions require persistent Bluetooth Low Energy connectivity, limiting standalone utility in connectivity-poor environments and constraining elderly adoption.
Strategic Opportunities
- Continuous glucose monitoring convergence:Non-invasive optical glucose sensing technology maturation offers pathway to diabetes management integration, opening reimbursement-eligible medical device positioning beyond fitness tracking.
- Enterprise wellness channel expansion:Self-insured employers in Texas and California are deploying device subsidies as preventive health investments, creating B2B procurement volumes with multi-year contract structures.
- Contactless payment utility extension:NFC transit and retail authentication integration in metropolitan transit authorities across the United States and Canada is expanding daily-use frequency beyond health-conscious consumer segments.
Industry Challenges
- Multidisciplinary hardware-software integration complexity:Clinical-grade wearable development requires simultaneous mastery of MEMS sensor physics, machine learning signal processing, and HIPAA-compliant cloud architecture, creating talent scarcity in cross-functional engineering teams.
- Legacy electronic health record interoperability:Hospital system data silos and proprietary API restrictions complicate seamless biometric data flow from wrist-worn devices to provider workflows, requiring costly custom integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Watch Market |
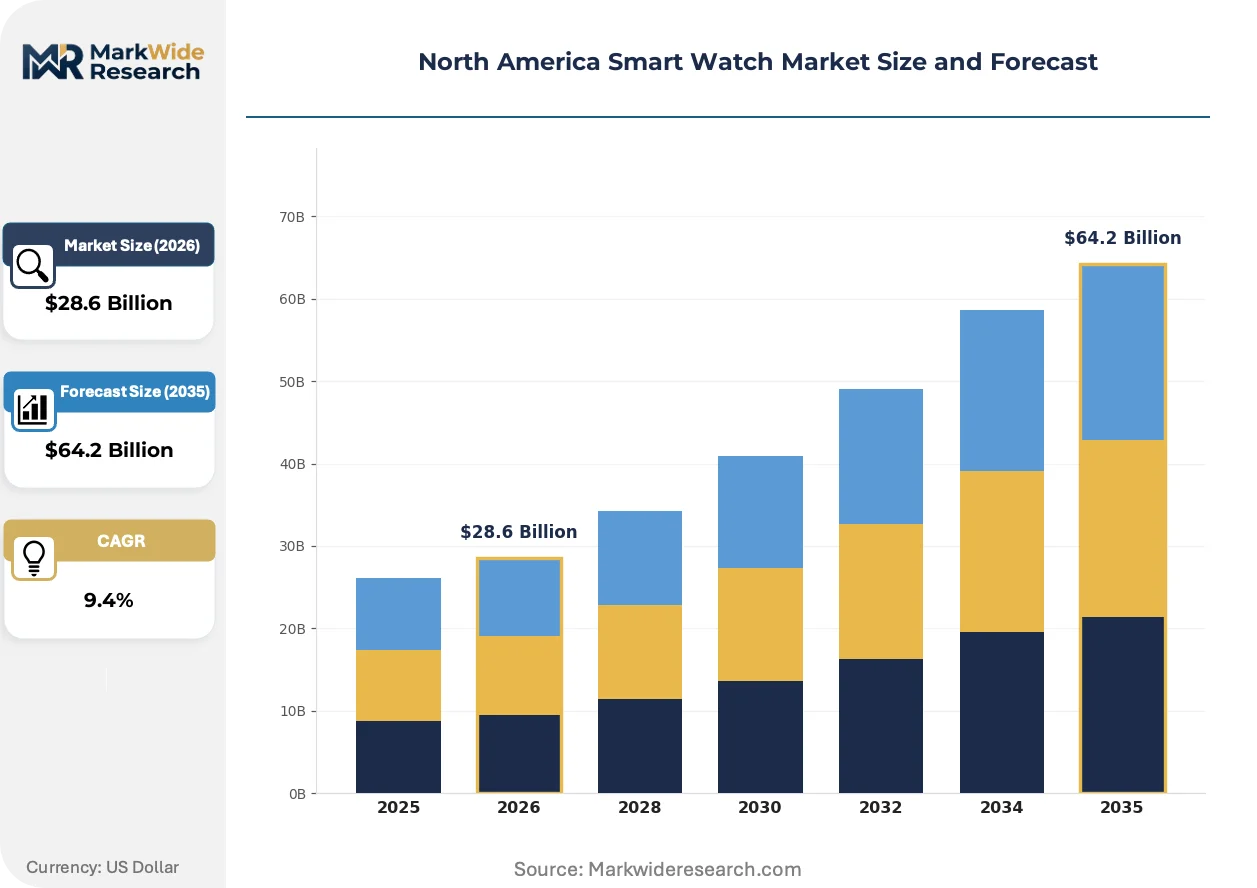
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracker, Luxury Watch, Hybrid Smartwatch, Sports Smartwatch Technology: Bluetooth, Wi-Fi, GPS, NFC Customer Type: Retail Consumers, Healthcare Providers, Tech Enthusiasts, Fitness Aficionados Feature: Heart Rate Monitoring, GPS Tracking, Sleep Tracking, Customizable Watch Faces |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Google LLC (Fitbit LLC), Garmin Ltd., Fossil Group, Inc., Huawei Technologies Co., Ltd., Withings S.A., Amazfit (Zepp Health Corporation), Polar Electro Oy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Watch Market Evolving Landscape
Clinical validation requirements and sensor fusion advances are elevating smart watches from consumer accessories to regulated medical devices, reshaping competitive priorities around algorithm accuracy and regulatory clearance velocity rather than hardware specifications alone.
Non-invasive optical glucose monitoring is supplanting intermittent fingerstick testing for preliminary diabetes screening applications. Self-insured employers and retail pharmacy clinics are piloting wrist-worn glucose trend monitoring for pre-diabetic employee populations. This convergence is compressing addressable market boundaries between consumer wellness and prescription medical device categories, forcing manufacturers to select regulatory pathways earlier in product development.
FDA's evolving guidance on continuous glucose monitoring integration is accelerating clinical trial investment requirements. Manufacturers must now demonstrate correlation accuracy against laboratory reference methods before marketing metabolic health features. Cardiac monitoring specialists and diabetes technology divisions within diversified health conglomerates are most affected, redirecting R&D budgets from hardware miniaturization toward algorithm validation infrastructure.
Enterprise wellness procurement is consolidating device selection authority within human resources and risk management functions rather than individual employee choice. Fortune 500 employers in California and Texas are negotiating volume purchasing agreements with single-vendor platforms that aggregate biometric data for population health analytics. This shift is displacing retail consumer choice with standardized fleet deployments, compressing brand loyalty dynamics and elevating data security and interoperability capabilities as primary selection criteria.
North America Smart Watch Market Segmentation
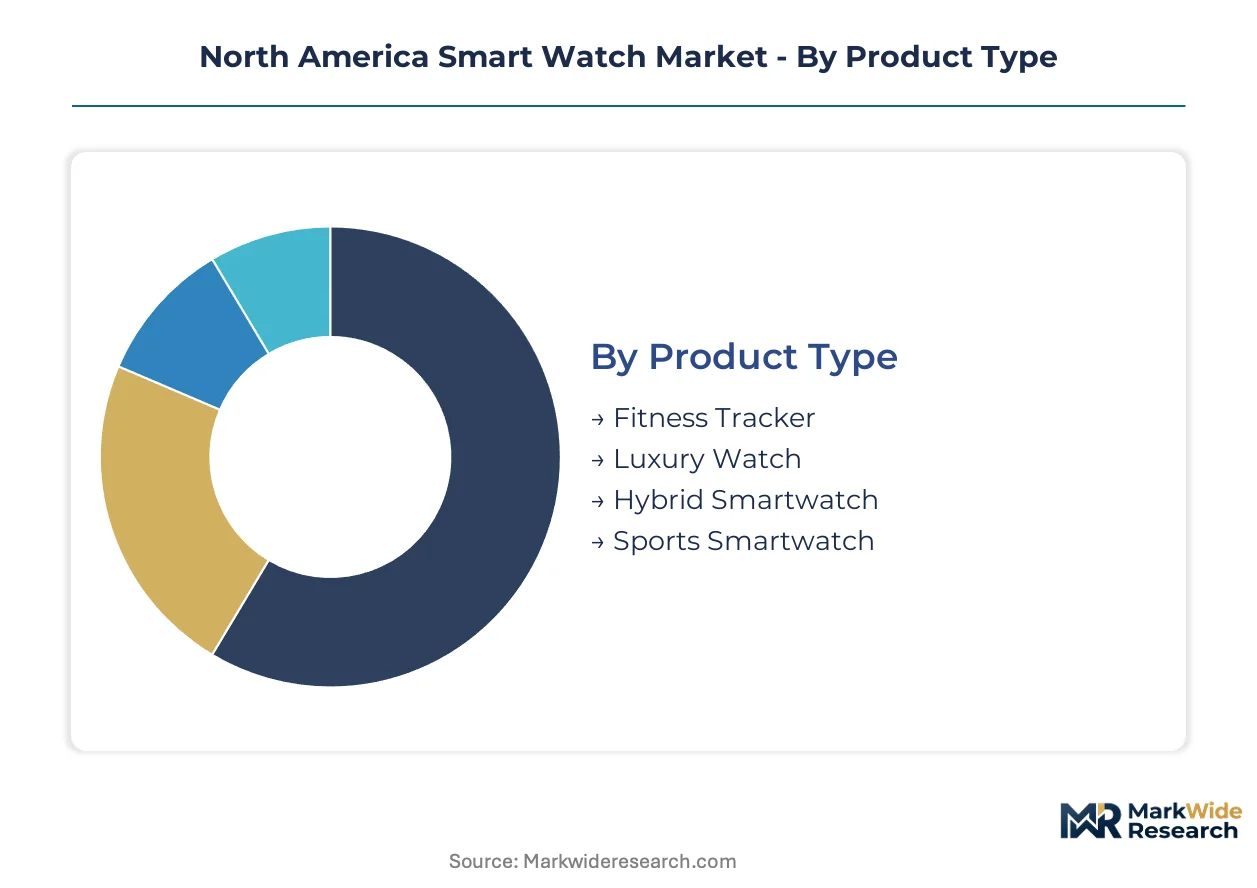
Channel configuration in North America smart watch distribution varies sharply by segment—sports and hybrid models dominate big-box retail, while healthcare-oriented devices flow through medical distributors and enterprise procurement. Understanding these pathway distinctions illuminates where margin pools concentrate and which specifications command pricing power.
Product Type:
Retail channel mix shifts dramatically across wrist-worn form factors, with sporting goods chains capturing outdoor-focused hardware and luxury boutiques preserving margin on premium materials.
- Sports Smartwatch:GPS-dominant architectures with extended battery systems serve hiking, cycling, and triathlon applications. Demand clusters in Colorado, Utah, and Pacific Northwest trail systems where outdoor recreation infrastructure supports year-round usage. REI and specialty running stores command disproportionate volume in this segment.
- Hybrid Smartwatch:Analog-digital fusion designs absorb basic fitness tracking while preserving traditional watch aesthetics. Corporate wellness programs in Texas and California subsidize these devices for white-collar workforces seeking notification utility without conspicuous technology signaling.
- Fitness Tracker:Stripped-down biometric bands face margin erosion as smartwatch functionality descends to lower price tiers. Pharmacy retail chains and employer gift programs remain primary distribution channels.
- Luxury Watch:Precious metal casings and heritage brand licensing target gift-giving occasions and status-conscious professionals. Authorized jewelers and direct-to-consumer flagship stores preserve exclusivity controls.
By volume, Sports Smartwatch leads. By growth pace, Hybrid Smartwatch is expanding most quickly.
Technology:
Component cost structures and certification requirements create tiered margin profiles across wireless connectivity standards.
- GPS:Multi-constellation satellite receivers enable route tracking without smartphone tethering, commanding premium positioning in outdoor recreation segments. FCC certification for radio frequency emissions adds fixed compliance overhead that favors high-volume manufacturers.
- NFC:Secure element integration for contactless transit and retail payment is penetrating metropolitan markets through partnerships with Chicago Transit Authority, Metropolitan Transportation Authority, and Vancouver TransLink. Transit authority procurement specifications are accelerating hardware standardization.
- Bluetooth:Low-energy protocols remain the baseline tethering standard, with firmware optimization for battery preservation now a primary competitive variable rather than hardware differentiation.
- Wi-Fi:Standalone connectivity for music streaming and emergency messaging appeals to cellular-averse users and parents purchasing for adolescent children, though battery drain limits active deployment.
Bluetooth dominates unit shipments. NFC-enabled configurations are gaining share fastest as transit integration expands.
Customer Type:
Procurement authority is migrating from individual consumers toward institutional buyers with population health analytics capabilities.
- Healthcare Providers:Hospital systems and accountable care organizations in Ontario and California are deploying FDA-cleared devices for remote patient monitoring reimbursement. Data interoperability with Epic and Cerner electronic health records is becoming a mandatory selection criterion.
- Retail Consumers:Individual purchasers remain the volume foundation, though brand loyalty is eroding as feature parity increases across Android and iOS ecosystems. Amazon and Best Buy capture the majority of transaction flow.
- Fitness Aficionados:Dedicated amateur athletes drive specification intensity in heart rate variability and training load metrics. Strava and TrainingPeaks software integration is now expected at premium price points.
- Tech Enthusiasts:Early adopters concentrate in Seattle, San Francisco, and Austin metro areas, providing initial demand signals for experimental features like non-invasive glucose sensing before mainstream diffusion.
Retail Consumers generate the largest addressable base. Healthcare Providers are climbing the fastest as reimbursement codes solidify.
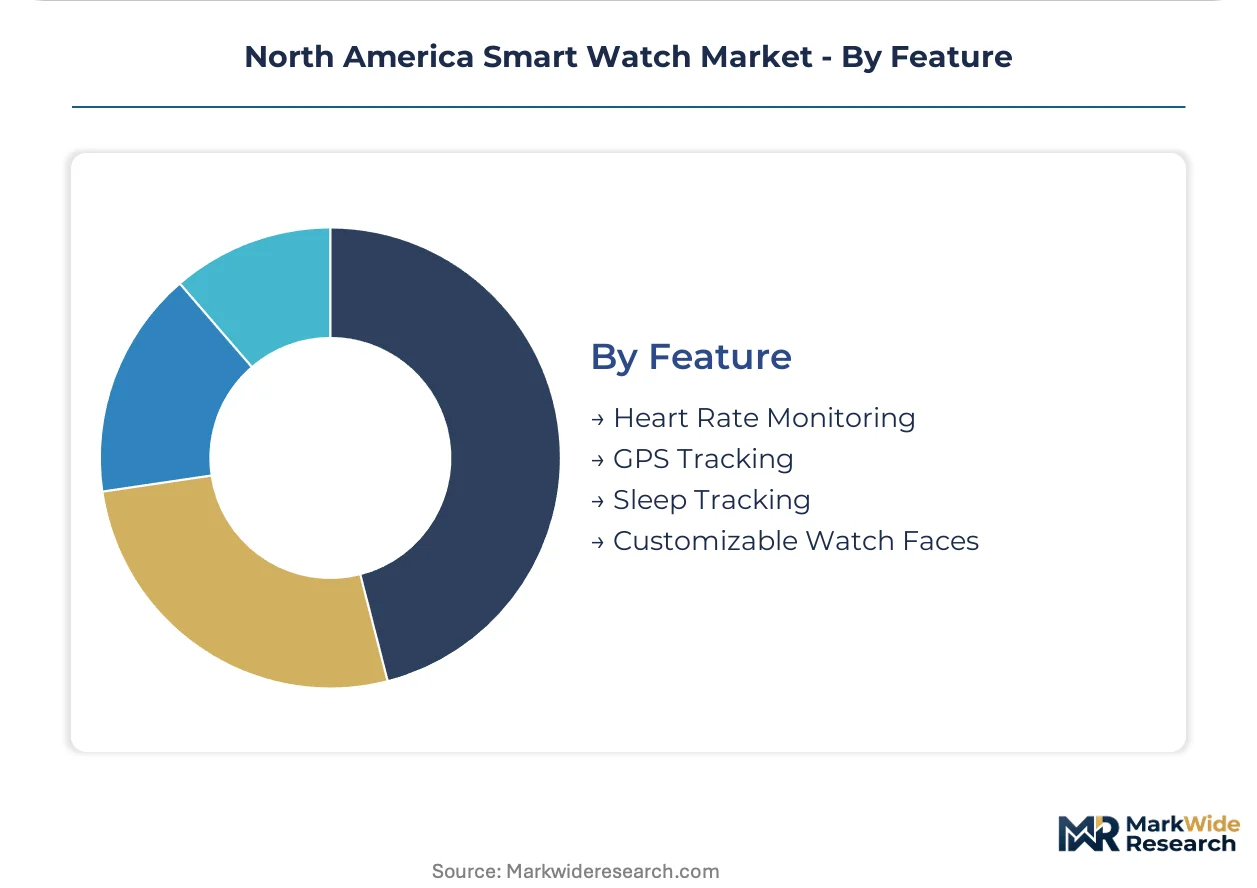
Feature:
Clinical validation status is fragmenting the feature landscape into consumer-grade and medical-grade tiers with divergent regulatory pathways.
- Heart Rate Monitoring:Photoplethysmography sensor accuracy improvements have enabled FDA 510(k) clearance for atrial fibrillation detection, creating a regulated premium tier separate from fitness-oriented implementations. Algorithm validation investments are concentrating capability among manufacturers with clinical trial infrastructure.
- GPS Tracking:Multi-band satellite reception and barometric altimeter fusion serve navigation reliability demands in backcountry environments where cellular coverage is absent. National park visitation patterns in Utah and Alaska correlate with regional demand concentration.
- Sleep Tracking:Respiratory rate and blood oxygen saturation derivatives are attracting employer wellness program interest for fatigue risk management in transportation and healthcare worker populations.
- Customizable Watch Faces:Software personalization retains user engagement and extends replacement cycles, with third-party developer ecosystems creating platform lock-in effects.
GPS Tracking appears in the highest unit volumes. Heart Rate Monitoring with FDA clearance is expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America smart watch trade flows reflect a net import position in finished devices offset by substantial semiconductor component exports from United States fabrication facilities. Cross-border supply chains integrate Canadian sensor module assembly with Mexican final assembly operations serving United States retail distribution.
United States
FDA 510(k) clearance velocity and enterprise wellness procurement drive institutional demand concentration. California's Consumer Privacy Act and Illinois' Biometric Information Privacy Act mandate explicit consent frameworks that shape firmware architecture. The San Francisco Bay Area and Austin metro clusters host health software engineering talent pools supporting clinical-grade algorithm development.
Canada
Provincial health system remote patient monitoring pilots in Ontario and British Columbia create reimbursement pathway demand for FDA-cleared devices. Health Canada medical device regulations align with FDA standards, accelerating cross-border product registration. Toronto and Vancouver concentrate digital health startup ecosystems developing wearable-integrated chronic disease management platforms.
Mexico
Manufacturing assembly operations in Baja California and Chihuahua serve United States retail fulfillment through nearshored production. IMMEX program maquiladora incentives attract component integration facilities for sensor module subassembly. Mexico City and Guadalajara metro areas emerge as Latin American market development hubs for Spanish-language health software localization.
North America Smart Watch Market Competitive Landscape
Listed leaders compete with private specialists across regulatory clearance velocity and health algorithm validation. The market structure concentrates capability among vertically integrated technology conglomerates with clinical trial infrastructure, while specialist manufacturers occupy defensible niches in GPS-dominant sports applications. Three archetypes dominate: silicon-health software integrators, diversified consumer electronics platforms, and precision navigation specialists. Competitive moves center on FDA 510(k) pathway acceleration and enterprise wellness contract consolidation.
Within the silicon-health software integrator tier, Apple Inc. exemplifies vertical control across semiconductor design and clinical-grade algorithm development. Samsung Electronics Co., Ltd. represents diversified platform scale spanning Android ecosystem compatibility and North American retail channel penetration. Garmin Ltd. occupies a position among precision navigation specialists, anchoring GPS-dominant sports applications against generalist competitors.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Google LLC (Fitbit LLC) |
| Garmin Ltd. |
| Fossil Group, Inc. |
| Huawei Technologies Co., Ltd. |
| Withings S.A. |
| Amazfit (Zepp Health Corporation) |
| Polar Electro Oy |
| Others |
Value Network & Pricing Analysis
Photoplethysmography sensor maturation is displacing invasive cardiac monitoring hardware, simultaneously shifting component sourcing from German precision-optics suppliers toward Taiwanese MEMS foundries and compressing bill-of-materials costs for clinical-grade wearable tiers. This substitution dynamic redistributes value capture from legacy medical-device component channels toward consumer-electronics scale manufacturers, eroding traditional pricing premiums for arrhythmia-detection features.
Pricing Analysis
Enterprise wellness buyers anchor pricing power in the North America smart watch market, commanding volume discounts through multi-year fleet deployments while retail consumers face premium-mid-economy pricing differentiation based on FDA clearance status and algorithm validation tier. Price differentiation rests on clinical-grade certification level versus consumer-grade fitness tracking, with photodiode sensor grade and HIPAA-compliant cloud architecture as secondary drivers. Cost compression in the fitness tracker tier is intensifying because hybrid smartwatch designs absorb step-counting functionality at higher price points. Self-insured employers demonstrate lowest price sensitivity due to preventive health ROI framing, while individual retail purchasers in pharmacy channels exhibit highest elasticity.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on the Shanghai-Los Angeles trade lane are elevating inbound logistics costs for semiconductor components destined for Mexican final assembly operations. Geographic supply concentrates in Taiwan for photodiode MEMS fabrication, South Korea for OLED display modules, and China for lithium-polymer battery cells. Raw material dependencies span rare-earth magnets for haptic motors, sapphire glass for premium watch faces, and medical-grade silicone for biometric sensor housings. Single-source vulnerability in Taiwanese foundry capacity for specialized photodiodes presents structural supply chain risk. Distribution runs through medical distributors for healthcare-oriented devices and big-box retail channels for sports and hybrid consumer models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America smart watch market is recovering from a cyclical trough driven by enterprise wellness procurement normalization following pandemic-era remote-monitoring surge spending. Healthcare provider reimbursement code expansion for wearable-derived biometric data provides the cyclical justification for sustained demand recovery.
For Market Incumbents: Shield algorithm validation capabilities through accelerated FDA 510(k) pathway investment, prioritizing atrial fibrillation and sleep apnea detection clearances before emerging entrants achieve clinical-grade parity. Consolidate enterprise wellness contract positions by embedding Epic and Cerner electronic health record interoperability as standard platform features, neutralizing specialist competitors lacking hospital system integration infrastructure. Capacity addition in Texas and California for health software engineering talent pools reinforces defensive moats against cross-functional engineering scarcity.
For New Entrants and Emerging Players: Remote patient monitoring data analytics services represent a service-layer gap where incumbents under-serve smaller accountable care organizations lacking in-house population health infrastructure. Target Ontario and British Columbia provincial health system pilots as the most penetrable geography, where Health Canada regulatory alignment with FDA standards accelerates cross-border product registration. A hospital system partnership go-to-market angle, offering turnkey chronic disease management platform integration, bypasses retail consumer brand loyalty barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision navigation specialists possessing GPS-dominant sports applications but lacking clinical-grade algorithm development infrastructure. Long-term viability over a five-to-ten year window favors manufacturers with demonstrated FDA clearance velocity and enterprise wellness contract consolidation momentum. Acquisition target archetype: mid-cap sports wearable specialists with established outdoor recreation distribution seeking clinical validation capability through health software engineering talent acquisition. The signal to watch is continuous glucose monitoring integration pilot outcomes with self-insured employers, indicating diabetes management category expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Clinical-grade algorithm clearance velocity separates premium-tier pricing from commodity fitness tracking. |
| Enterprise Wellness Contract Consolidation | Fortune 500 employers in Texas and California are standardizing fleet deployments with single-vendor platforms. |
| Electronic Health Record Interoperability Investment | Epic and Cerner API integration is becoming mandatory for hospital system procurement selection criteria. |
| Continuous Glucose Monitoring Convergence | Non-invasive optical glucose sensing pilots with self-insured employers signal diabetes management category expansion. |
| NFC Transit Authority Partnership Expansion | Chicago Transit Authority and Metropolitan Transportation Authority specifications accelerate hardware standardization for contactless payment utility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, Health Canada medical device registration records, and enterprise wellness procurement contract disclosures. Primary interviews engaged health software engineering directors, hospital biomedical equipment procurement committees, GPO contracts managers, and self-insured employer benefits executives. Secondary validation drew from FCC equipment authorization databases, state attorney general biometric privacy enforcement patterns, and customs import records for semiconductor component trade flows. Bottom-up demand modeling from healthcare provider reimbursement code analysis triangulates against top-down market sizing from retail channel shipment data.
Segmentation dimensions modeled include product type across sports smartwatch, hybrid smartwatch, fitness tracker, and luxury watch categories; technology tier across GPS, NFC, Bluetooth, and Wi-Fi connectivity standards; customer type spanning healthcare providers, retail consumers, fitness aficionados, and tech enthusiasts; and feature validation status separating FDA-cleared medical-grade from consumer-grade implementations. CAGRs were derived from regression analysis of historical reimbursement code expansion rates and enterprise wellness program adoption curves, cross-referenced against photoplethysmography sensor accuracy improvement trajectories and transit authority NFC integration timelines across the analysis window.
Forecasts assume regulatory continuity in FDA 510(k) pathway requirements and California Consumer Privacy Act enforcement patterns; material policy shifts such as expanded Medicare reimbursement for continuous glucose monitoring or preemptive federal biometric privacy legislation would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Smart Insole Market