
 Player Tracking System Market | 2026-2036
Player Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Player Tracking System Market Outlook
North American production capacity for precision positioning hardware is tilting toward Mexico's Guadalajara electronics corridor. Zebra Technologies leverages its RFID manufacturing scale to dominate stadium infrastructure contracts. Catapult Group International anchors its wearable device assembly in Australian facilities while sustaining R&D intensity through Melbourne-based biomechanics labs. KINEXON competes on ultra-wideband precision, positioning its sensor modules for basketball and ice hockey applications where GPS fails.
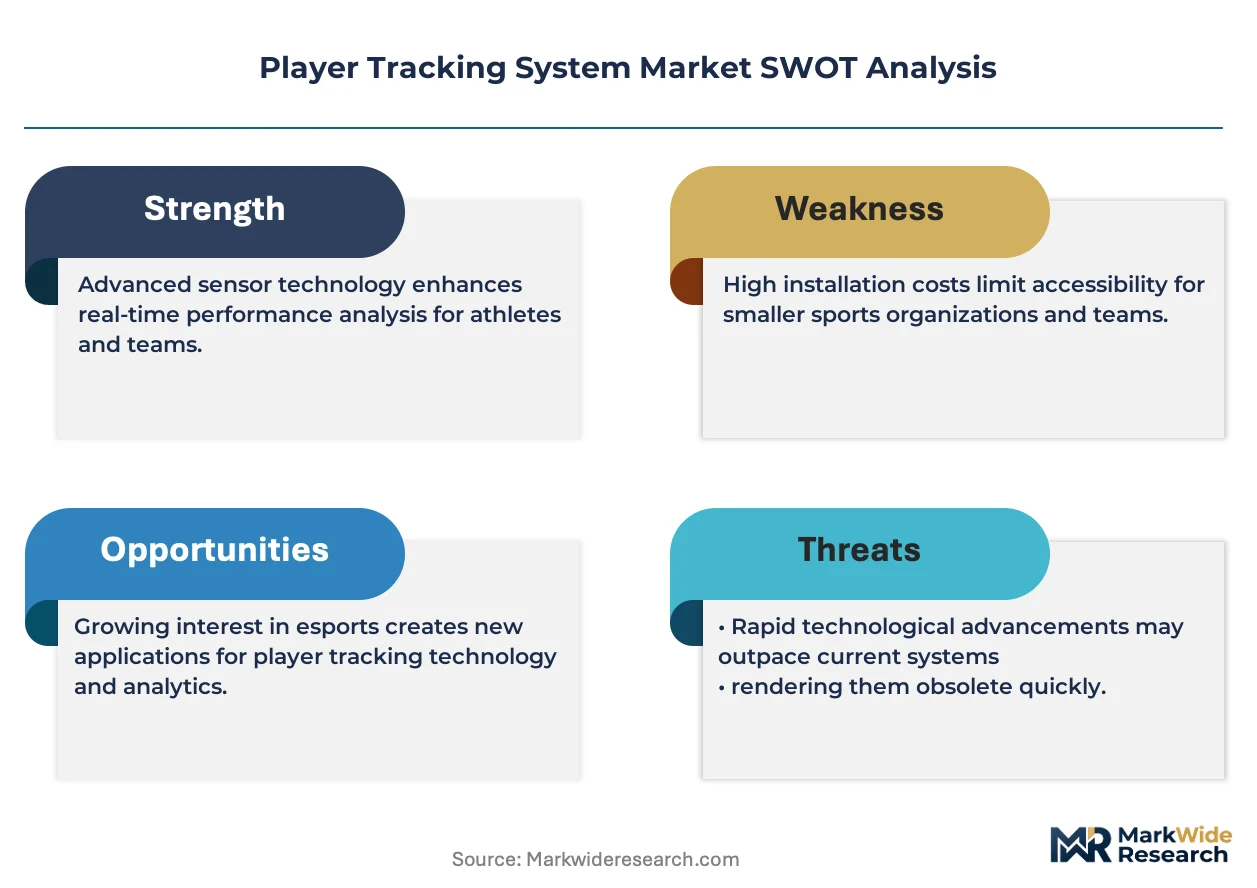
A player tracking system integrates spatial positioning hardware, motion sensors, and analytics software to capture athlete kinematics, tactical positioning, and physiological load metrics in real time, typically sampling at 10-100 Hz depending on sport velocity requirements. The technology serves professional coaching staffs seeking objective performance diagnostics and broadcast producers generating augmented viewer overlays. GPS technology leads outdoor team sports deployments while optical tracking dominates indoor arenas and television production workflows. Cloud-based deployment is expanding fastest among mid-tier academies seeking subscription access to elite-level analytics without capital expenditure. Injury prevention applications command premium pricing due to direct return-on-investment linkage through reduced player downtime.
FIFA's Quality Programme, the NFL's Player Health and Safety protocols, and NCAA training time restrictions collectively shape hardware certification requirements and data governance standards across competitive tiers. The EU AI Act introduces algorithmic transparency obligations for automated performance scoring systems deployed in European leagues. Stakeholders must monitor emerging biometric privacy legislation in US statehouses and European courts to anticipate consent architecture changes that could constrain data collection modalities.
Market Dynamics
FIFA's Quality Programme for Electronic Performance and Tracking Systems is compressing certification timelines for on-field wearable hardware. Bundesliga clubs in Germany operate the densest per-capita tracking infrastructure worldwide, creating a reference architecture that lower-tier leagues now replicate.
Growth Catalysts
- Bundesliga infrastructure density:German professional football clubs maintain the highest wearable sensor deployment rates per athlete globally, establishing operational templates for second-division and academy adoption.
- EU AI Act transparency mandates:Algorithmic scoring systems deployed in European leagues now face explainability requirements, accelerating vendor investment in interpretable performance models.
- Cloud-based subscription access:Mid-tier academies bypass capital expenditure barriers through software-as-a-service analytics platforms, expanding addressable demand beyond elite professional tiers.
Market Restraints
- Ultra-wideband module cost concentration:Precision positioning hardware relies on specialized semiconductor fabrication concentrated in East Asian foundries, exposing margins to input volatility.
- Biometric privacy legislative friction:US statehouses and European courts are advancing consent architecture requirements that could constrain real-time physiological data collection modalities.
- GPS signal failure in indoor environments:Basketball and ice hockey venues cannot deploy satellite-based tracking, forcing parallel infrastructure investment in optical or radio-frequency alternatives.
Strategic Opportunities
- NCAA training time restrictions:Collegiate athletic programs in the United States face mandated practice limits, creating demand for load management analytics that maximize performance within constrained windows.
- Convergence of RFID and computer vision:Stadium infrastructure vendors are integrating Zebra Technologies' radio-frequency hardware with optical tracking for redundant player positioning in broadcast productions.
- Injury prevention ROI linkage:Reduced player downtime translates directly to salary cap efficiency, allowing vendors to command premium pricing for predictive load monitoring tools.
Industry Challenges
- FIFA EPTS certification timelines:Hardware manufacturers face extended validation cycles for on-field wearable approval, delaying revenue recognition for new sensor form factors.
- Biomechanist talent scarcity:Melbourne-based R&D clusters compete for specialized human movement scientists capable of translating raw kinematic data into actionable coaching protocols.
- Legacy broadcast integration:Augmented reality overlay producers must reconcile real-time tracking feeds with existing television production workflows, creating technical interoperability demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Player Tracking System Market |
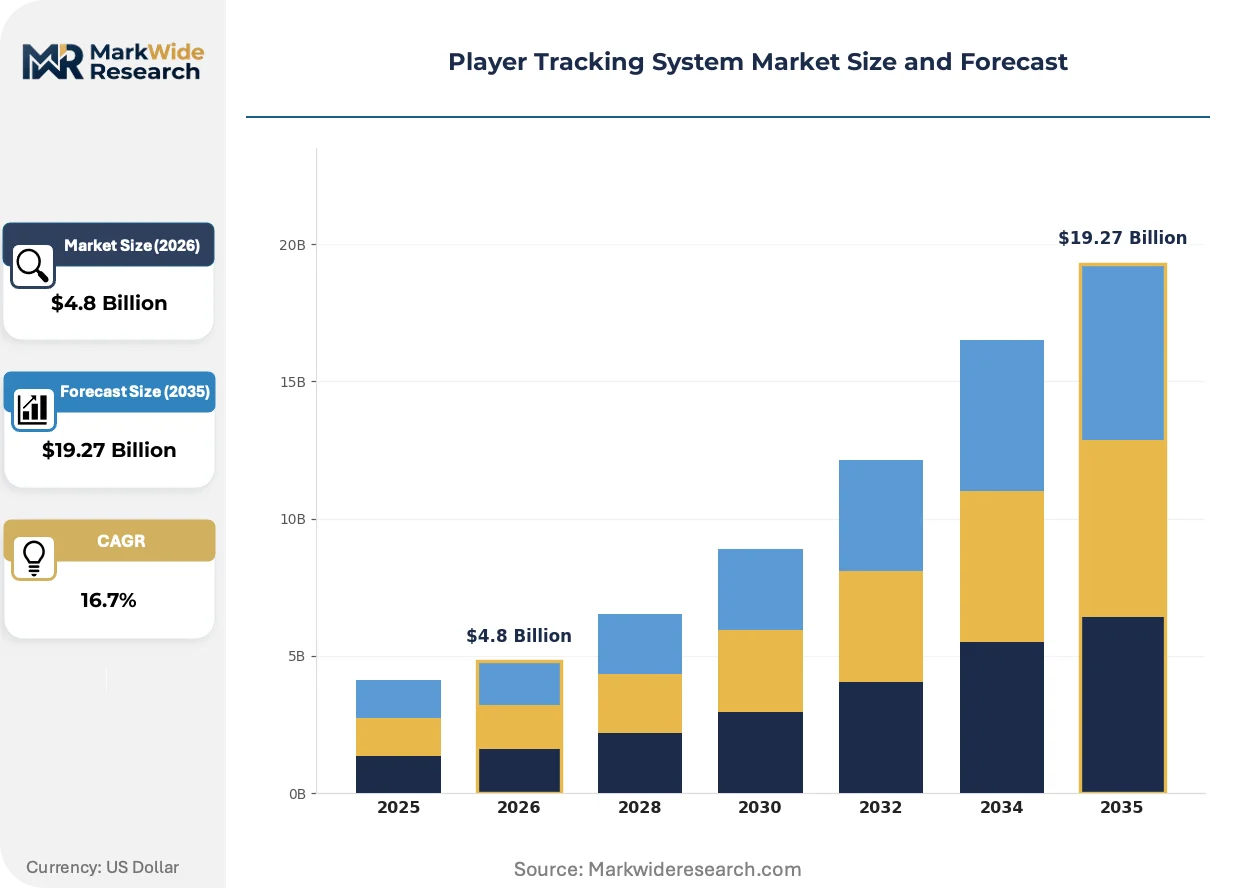
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, RFID, Optical, Inertial Sensors Application: Competitive Sports, Fitness Training, Injury Prevention, Fan Engagement End User: Professional Teams, Academies, Sports Organizations, Coaches Deployment: On-Premise, Cloud-Based, Hybrid, Standalone |
| Companies Covered | Zebra Technologies, Catapult Group International, STATS Perform, ChyronHego, STATSports Group, KINEXON, JOHAN Sports, Second Spectrum, Xampion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Player Tracking System Market Strategic Shifts
Real-time analytics is virtualizing how coaching staffs consume athlete performance data, compressing the interval between on-field action and tactical adjustment. Three developments are reshaping vendor competitive positioning.
Ultra-wideband positioning is virtualizing spatial tracking in GPS-denied environments. KINEXON's sensor modules achieve centimeter-level precision for basketball and ice hockey applications where satellite signals fail. NCAA basketball programs and NHL franchises are adopting these systems at accelerating pace, enabling tactical analysis previously impossible in indoor arenas.
The EU AI Act is imposing algorithmic transparency obligations on automated performance scoring systems deployed in European football leagues. Vendors must now document decision pathways for load ratings and injury risk classifications. German Bundesliga clubs, operating the most sophisticated tracking infrastructure, face immediate compliance pressure to retrofit existing analytics platforms with explainable AI architectures.
Subscription access models are displacing perpetual license sales among mid-tier academies seeking elite-level analytics without capital expenditure. Cloud-based deployment allows smaller football clubs in Spain and Italy to access biomechanical analysis tools previously restricted to top-division budgets. This procurement pattern shift concentrates vendor attention on recurring revenue optimization and customer success functions rather than upfront hardware margins.
Player Tracking System Market Segmentation
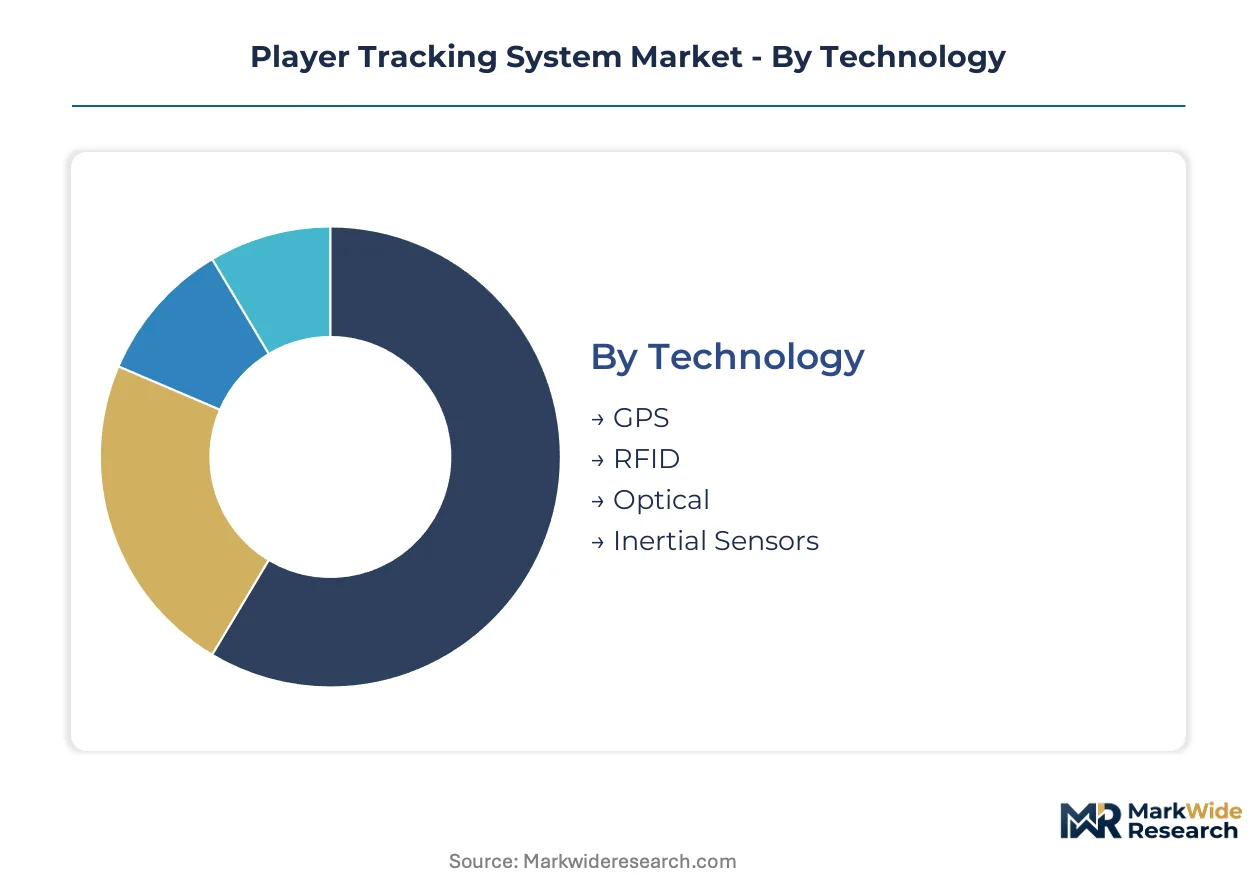
Player tracking technology fragments across positioning methodologies, use-case intensity, and procurement sophistication. Each segmentation dimension reveals distinct margin structures and adoption velocity that shape vendor resource allocation.
Technology:
Use-case spectrum spans satellite-dependent outdoor deployments to centimeter-precise indoor radio-frequency architectures.
- GPS:Satellite-reliant positioning samples at 10 Hz for outdoor team sports velocity requirements. Bundesliga clubs in Germany deploy GPS wearables at the densest per-capita rates globally, establishing operational templates for second-division replication.
- Optical:Computer-vision systems process arena-mounted camera arrays for broadcast-grade positional data without athlete-worn hardware. Indoor basketball venues and television production workflows concentrate demand here, driven by GPS signal failure in roofed stadiums.
- RFID:Radio-frequency identification leverages stadium infrastructure for redundant player positioning in broadcast overlays. Zebra Technologies dominates these contracts through manufacturing scale in Mexico's Guadalajara electronics corridor.
- Inertial Sensors:Accelerometer-gyroscope combinations capture limb kinematics and impact forces for load management analytics.
Established volume favors GPS; emerging adoption favors optical tracking for broadcast convergence.
Application:
Functional intensity ranges from elite competitive diagnostics to consumer-facing entertainment augmentation.
- Competitive Sports:Real-time tactical positioning and physiological monitoring serve professional coaching staffs seeking objective performance diagnostics. FIFA's Quality Programme for Electronic Performance and Tracking Systems compresses certification timelines for on-field wearable hardware in this segment.
- Injury Prevention:Predictive load monitoring tools command premium pricing through direct salary cap efficiency linkage. NCAA training time restrictions in the United States create concentrated demand for maximizing performance within mandated practice limits.
- Fitness Training:Amateur and semi-professional athletes access biomechanical feedback through simplified wearable interfaces.
- Fan Engagement:Augmented reality overlays transform raw tracking feeds into broadcast viewer experiences, requiring technical reconciliation with legacy television production workflows.
Revenue concentration sits with injury prevention; steepest expansion trajectory belongs to fan engagement as broadcast rights holders invest in differentiated viewer experiences.
End User:
Procurement sophistication stratifies across capital availability and technical staffing depth.
- Professional Teams:Bundesliga football clubs and NHL franchises operate dedicated performance departments with in-house biomechanists. Melbourne-based R&D clusters compete for scarce human movement scientists capable of translating kinematic data into actionable protocols.
- Academies:Mid-tier development programs bypass capital expenditure barriers through cloud-based subscription access to elite-level analytics platforms.
- Sports Organizations:Governing bodies mandate hardware certification standards and data governance frameworks across competitive tiers.
- Coaches:Individual practitioners seek portable, interpretation-light tools for immediate tactical feedback.
Professional teams anchor current revenue; academies represent the fastest-climbing adoption curve through procurement pattern shifts toward recurring service models.
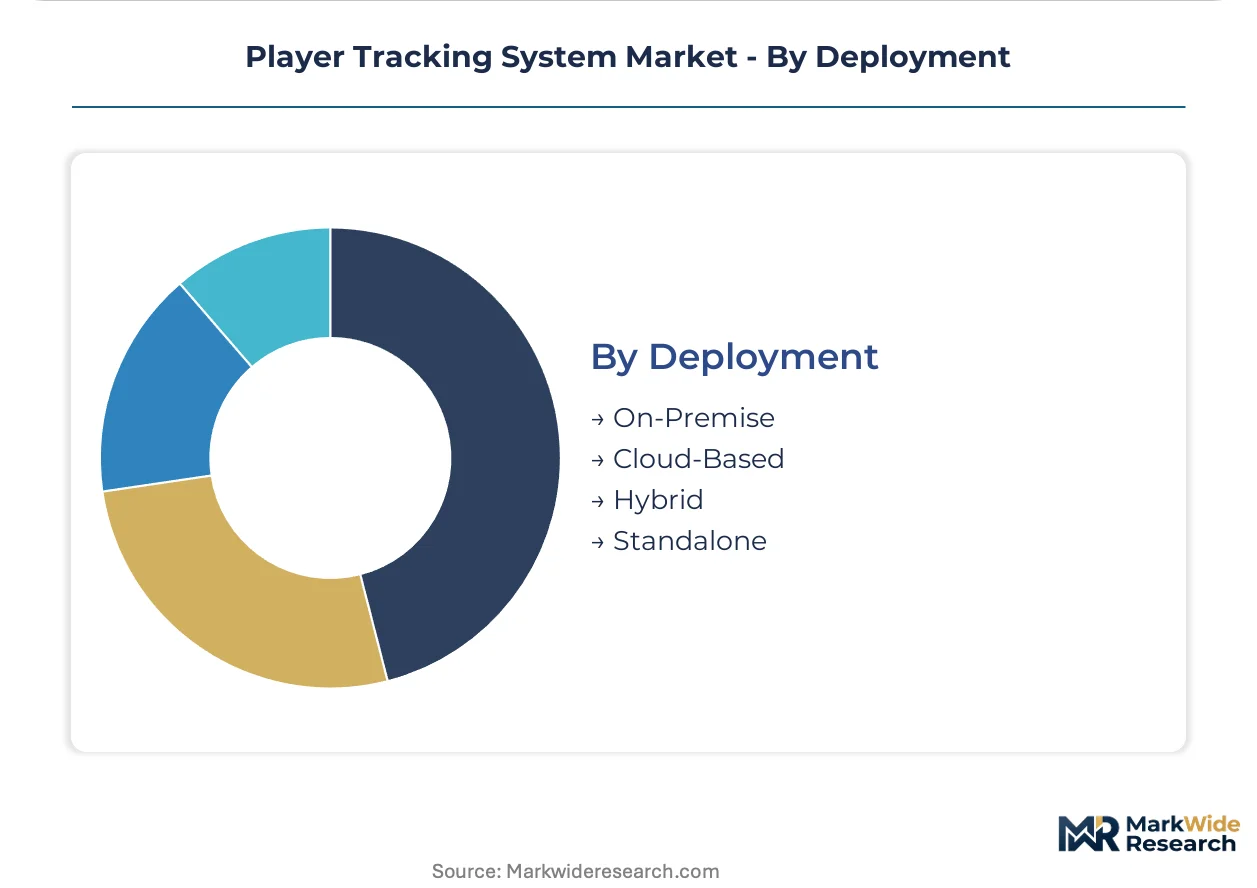
Deployment:
Infrastructure commitment varies from captive server installations to fully outsourced analytics consumption.
- Cloud-Based:Software-as-a-service delivery allows smaller football clubs in Spain and Italy to access tools previously restricted to top-division budgets. Subscription economics concentrate vendor attention on customer success functions rather than upfront hardware margins.
- Hybrid:Edge-computing architectures process sensitive biometric data locally while pushing anonymized aggregates to central analytics platforms. EU AI Act algorithmic transparency obligations apply differentially across these data flows.
- On-Premise:Dedicated server installations serve organizations with stringent data sovereignty requirements or unreliable connectivity.
- Standalone:Portable systems operate without network dependency for training ground or remote venue deployment.
Hybrid architectures capture security-conscious adopters; cloud-based deployment gains share fastest among cost-constrained mid-market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FIFA's Quality Programme anchors the dominant geography. German Bundesliga clubs operate the densest per-capita tracking infrastructure worldwide. This regulatory-certification nexus shapes deployment patterns across competitive tiers.
Germany
Bundesliga clubs maintain the highest wearable sensor deployment rates per athlete globally, establishing operational templates for second-division and academy adoption. The EU AI Act imposes algorithmic transparency obligations on automated performance scoring systems deployed in German football leagues. Berlin-Brandenburg hosts biomechanics R&D clusters competing for specialized human movement scientists.
United States
NCAA training time restrictions create concentrated demand for load management analytics that maximize performance within mandated practice windows. The NFL's Player Health and Safety protocols shape hardware certification requirements and data governance standards across collegiate and professional tiers. Mexico's Guadalajara electronics corridor anchors North American production capacity for precision positioning hardware.
Australia
Catapult Group International sustains wearable device assembly in Australian facilities while driving R&D intensity through Melbourne-based biomechanics labs. The country's national sports regulator mandates data governance frameworks for athlete monitoring technologies. Victoria's Melbourne metropolitan area concentrates talent competition for kinematic data interpretation specialists.
Spain
Mid-tier football academies in Spain bypass capital expenditure barriers through cloud-based subscription access to elite-level analytics platforms. The country's national data protection authority enforces biometric privacy requirements constraining real-time physiological data collection modalities. Catalonia's Barcelona metropolitan area hosts broadcast production workflows integrating tracking feeds with augmented reality overlays.
Japan
METI funding programs accelerate precision sensor development for professional baseball and sumo applications where tactical positioning analysis commands premium pricing. The country's national broadcasting regulator shapes technical interoperability standards for television production workflow integration. Tokyo's Kanto region concentrates demand from Nippon Professional Baseball franchises seeking objective performance diagnostics.
Player Tracking System Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct competitive tiers: precision-positioning specialists, stadium-infrastructure incumbents, and wearable-device pure-plays. Strategic archetypes include ultra-wideband precision vendors, RFID manufacturing scale players, and cloud-native analytics platforms. M&A activity targets biomechanist talent acquisition; geographic expansion focuses on NCAA and Bundesliga adjacencies.
Within the precision-positioning tier, KINEXON and Zebra Technologies occupy distinct positions. KINEXON represents the ultra-wideband specialist archetype competing on centimeter-level accuracy for GPS-denied environments. Zebra Technologies exemplifies manufacturing scale advantage through stadium infrastructure contracts. Catapult Group International anchors the wearable-device pure-play segment with integrated hardware-software offerings.
| Leading Market Players |
|---|
| Zebra Technologies |
| Catapult Group International |
| STATS Perform |
| ChyronHego |
| STATSports Group |
| KINEXON |
| JOHAN Sports |
| Second Spectrum |
| Xampion |
| Others |
Value Chain & Pricing Dynamics
Guadalajara's electronics corridor anchors North American production capacity for precision positioning hardware, with manufacturing scale translating directly into pricing power for stadium infrastructure contracts. Zebra Technologies leverages this geographic concentration to dominate RFID-based player tracking deployments, while cost compression in wearable sensor modules intensifies competition among pure-play vendors.
Pricing Analysis
Geographic price spreads separate Bundesliga deployments from mid-tier academy subscriptions by a factor of three to five, reflecting infrastructure depth versus SaaS access. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier under FIFA's Quality Programme and data processing latency guarantees. Pricing pressure stems from cloud-native entrants undercutting perpetual license models with recurring revenue alternatives. Professional football clubs exhibit lowest price sensitivity due to salary cap efficiency linkages, while Spanish and Italian academies drive hardest bargain negotiations.
Supply Chain Analysis
Export control regimes on precision semiconductors constrain ultra-wideband module flows from East Asian foundries, creating input bottlenecks for centimeter-level indoor positioning hardware. Manufacturing concentrates in Taiwan, South Korea, and China's Yangtze River Delta for specialized radio-frequency components. Supply chains draw from Australian biomechanics talent pools and Mexican assembly corridors for finished device integration. Single-source vulnerability in UWB chip fabrication exposes margins to geopolitical disruption. Distribution runs through direct vendor relationships with professional sports franchises and cloud platform aggregators serving academy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The player tracking system market is recovering from pandemic-induced capital expenditure freezes, with Bundesliga infrastructure renewal and NCAA compliance spending driving the cyclical upturn.
For Market Incumbents: Harden certification护城河 under FIFA's Quality Programme by accelerating EPTS validation timelines before regulatory compression tightens further. Deepen backward integration into sensor module fabrication to offset East Asian foundry concentration risk. Prioritize Melbourne-based biomechanist retention through captive R&D employment structures. For New Entrants and Emerging Players: Build out cloud-native analytics platforms targeting Spanish and Italian mid-tier academies bypassing capital expenditure barriers through subscription procurement. NCAA basketball programs represent the most penetrable white-space segment given ultra-wideband adoption acceleration in GPS-denied environments. Lead with load management ROI quantification to displace incumbent perpetual license vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wearable-device pure-plays with integrated hardware-software architectures over stadium infrastructure incumbents facing broadcast workflow disruption. Long-term viability hinges on algorithmic explainability compliance under EU AI Act mandates. Acquisition targets should demonstrate biomechanist talent density and Bundesliga reference contracts. Watch FIFA EPTS certification backlog duration as inflection indicator for hardware vendor revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FIFA EPTS Certification Acceleration | Compressed validation timelines unlock revenue recognition for new sensor form factors in Bundesliga deployments. |
| Cloud Platform Integration | SaaS delivery models displace perpetual licenses among Spanish and Italian academy segments seeking elite analytics access. |
| Biomechanist Talent Acquisition | Melbourne-based R&D clusters compete for scarce human movement scientists capable of translating kinematic data into coaching protocols. |
| Ultra-Wideband Module Development | Centimeter-level precision enables basketball and ice hockey tracking where GPS signals fail in roofed venues. |
| EU AI Act Compliance Architecture | Explainable AI retrofitting addresses algorithmic transparency obligations for automated load rating systems in European leagues. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with professional football performance directors, NCAA athletic compliance officers, broadcast technology integrators, and wearable device procurement leads. Secondary validation drew from FIFA Quality Programme certification databases, Bundesliga club financial disclosures, EU AI Act regulatory filings, and cloud platform subscription metrics. Bottom-up segment sizing triangulated against top-down market envelope checks across technology, application, and deployment dimensions.
Calibration against historical adoption curves in adjacent sports technology markets anchored the analytical framework across the projection horizon. Segmentation modeling spanned positioning methodology, competitive tier intensity, procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating Bundesliga infrastructure density as leading indicator and NCAA training restriction compliance as lagging validation. Industry-specific inputs included FIFA EPTS certification pipeline velocity and ultra-wideband module cost trajectories.
Stress conditions across semiconductor supply disruption, biometric privacy legislative acceleration, and broadcast rights holder consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud migration pace and regulatory compliance cost absorption. Material shifts in FIFA certification timeline compression or EU AI Act enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Fantasy Sports Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
India Fantasy Sports Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Global Player Tracking Market