
 Europe Sports Analytics Market | 2026-2036
Europe Sports Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sports Analytics Market Foresight
Capital-intensity divergence between wearable-hardware producers and pure-software analytics platforms is bifurcating competitive dynamics across the European landscape. Catapult Group International Ltd anchors its position through integrated athlete-monitoring hardware that captures biomechanical load data in real time. SAP SE leverages cloud-native architectures to serve multi-sport federations with centralized data lakes. Sportradar AG competes on proprietary data partnerships with wagering operators and rights holders.
Europe sports analytics encompasses the systematic capture, processing, and interpretation of athletic performance and commercial data through sensor networks, computer vision pipelines, and statistical modeling engines, typically operating at sub-second latency for in-game decision support. The discipline serves professional organizations seeking competitive advantage through quantified training loads, tactical pattern recognition, and revenue optimization across ticketing and broadcast segments. Performance Analysis commands established spending from football and rugby academies seeking granular biomechanical feedback on player conditioning regimes. Cloud-Based deployment is gaining traction among mid-tier clubs that lack capital for on-premises server farms but require elastic compute for match-day analytics spikes. Fan Engagement solutions are attracting fresh investment as leagues in Italy and France pursue direct-to-consumer subscription models that depend on personalized content recommendation engines.
The EU AI Act imposes risk-classification requirements on automated decision systems used for player recruitment and injury prediction, compelling vendors to document algorithmic transparency and human oversight protocols. GDPR constraints on biometric data collection limit how wearable Technology providers store and transfer physiological metrics across national borders within the European Economic Area. Stakeholders must monitor evolving conformity assessment timelines under the AI Act's implementation roadmap while calibrating product architectures for interoperability with emerging federation-level data standards.
Market Dynamics
The EU AI Act's risk-classification framework is forcing vendors to reengineer predictive injury algorithms and recruitment tools, bifurcating the vendor landscape between compliant enterprise platforms and constrained point solutions.
Growth Catalysts
- Cloud-native architectures:Mid-tier football clubs in Spain and Italy are abandoning on-premises infrastructure for elastic compute resources that scale during match-day analytics spikes.
- GDPR-compliant data lakes:Federations across Germany and England are consolidating athlete biometric data under centralized governance models that satisfy cross-border transfer requirements.
- Broadcast-rights holder investment:Rights holders in the United Kingdom are funding analytics infrastructure to power personalized fan engagement and direct-to-consumer subscription platforms.
Market Restraints
- Biometric data storage costs:GDPR-mandated encryption and localization requirements inflate operational expenditures for wearable technology providers transferring physiological metrics across EEA borders.
- Algorithmic transparency mandates:The EU AI Act's documentation requirements for high-risk automated decision systems extend product development cycles for injury prediction and player valuation models.
- Sensor hardware commoditization:Price compression in GPS and accelerometer components erodes margins for hardware-centric vendors dependent on unit sales rather than software subscriptions.
Strategic Opportunities
- French league digitization:Ligue 1 clubs lag German and English counterparts in analytics penetration, creating whitespace for cloud-based performance analysis deployments.
- Computer vision convergence:Integration of optical tracking with wearable biomechanical data is enabling new tactical pattern recognition products for rugby and football academies.
- CSRD-aligned ESG reporting:The EU Corporate Sustainability Reporting Directive creates demand for analytics platforms that quantify athlete welfare metrics and environmental footprint of sporting operations.
Industry Challenges
- Interoperability fragmentation:Proprietary data formats from competing wearable hardware vendors complicate integration with federation-level standardization initiatives.
- Specialized talent scarcity:Shortages of sports scientists fluent in both biomechanical load interpretation and machine learning pipeline engineering constrain platform development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sports Analytics Market |
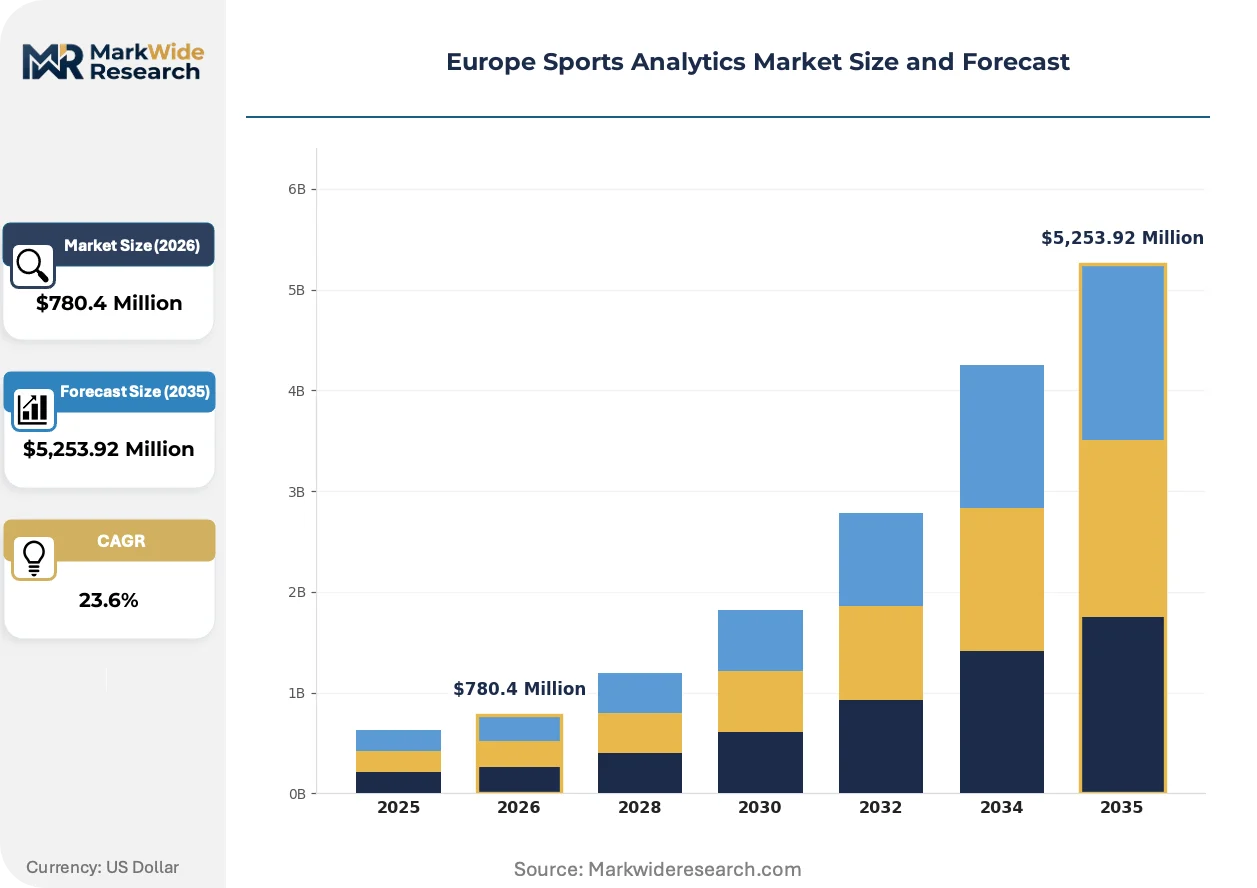
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $5,253.92 Million |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance Analysis, Fan Engagement, Video Analysis, Wearable Technology Application: Team Management, Player Performance, Event Analytics, Audience Insights End User: Professional Teams, Coaches, Sports Organizations, Event Managers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Catapult Group International Ltd, Stats Perform, SAP SE, International Business Machines Corp, Oracle Corporation, Genius Sports Ltd, deltatre, TruMedia Networks, Sportradar AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sports Analytics Market Shifts & Advancements
Computer vision pipelines and federated data architectures are displacing siloed tracking systems, while regulatory pressure on algorithmic accountability accelerates vendor consolidation.
Edge-computing video analytics is supplanting centralized server processing for real-time tactical recognition. Bundesliga and Premier League clubs are deploying pitch-side inference units that reduce latency from 800 milliseconds to under 100 milliseconds. This compression is enabling live substitution recommendations and dynamic formation adjustments during active play.
The EU AI Act's conformity assessment timelines are compressing vendor roadmaps for automated recruitment tools. High-risk classification of player valuation algorithms mandates human-in-the-loop protocols and bias auditing documentation. German football academies are prioritizing vendors with pre-certified transparency frameworks to avoid procurement delays.
Subscription-based analytics procurement is displacing perpetual license arrangements among mid-tier clubs. Italian Serie A teams are negotiating outcome-tied contracts where platform fees scale with measurable performance improvements or broadcast engagement metrics. This shift concentrates vendor risk and demands more robust implementation support capabilities.
Europe Sports Analytics Market Segmentation
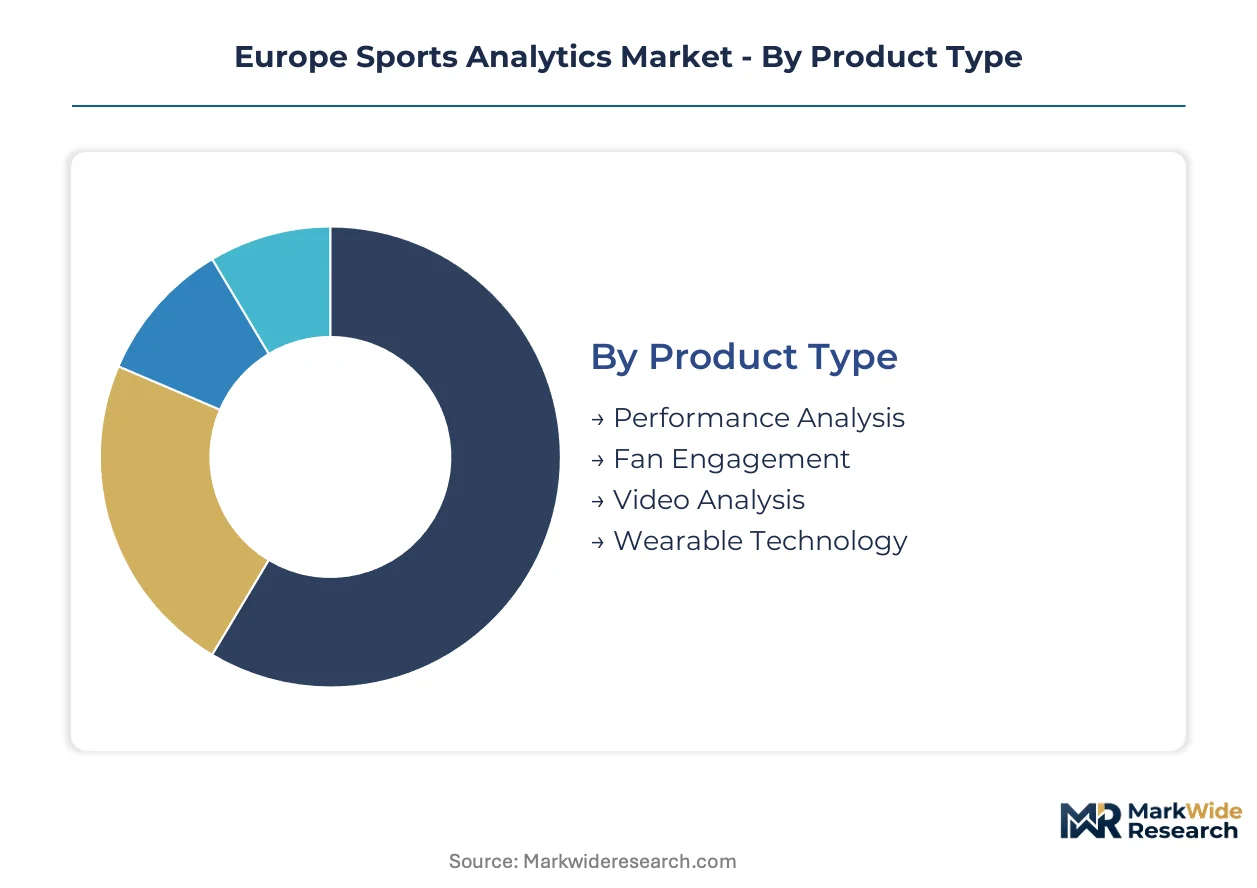
Segmentation in European sports analytics reveals how regulatory pressure and infrastructure maturity fragment purchasing behavior across federations. Clubs in Germany and England prioritize compliance-heavy biometric systems while Spanish and Italian organizations favor elastic cloud deployments that sidestep capital constraints.
Product Type:
Wearable Technology faces acute substitution pressure from computer vision pipelines that extract biomechanical data without physical sensors, forcing hardware vendors to defend through real-time telemetry integration.
- Performance Analysis:Systems aggregate tactical pattern recognition with quantified training loads to optimize player conditioning regimes. German football academies and English rugby clubs concentrate procurement here, driven by federation mandates for granular biomechanical feedback on athlete welfare metrics.
- Fan Engagement:Platforms power personalized content recommendation engines and direct-to-consumer subscription models. Broadcast-rights holders in the United Kingdom and league operators in Italy fund these deployments to capture disintermediated revenue streams from cord-cutting audiences.
- Video Analysis:Optical tracking systems capture tactical formations without wearable hardware attachment.
- Wearable Technology:GPS and accelerometer units transmit physiological metrics under GDPR-constrained data architectures.
Performance Analysis retains volume leadership; Fan Engagement holds the steepest expansion curve.
Application:
Cost tier stratification separates enterprise-grade team management suites from point solutions targeting individual performance optimization.
- Team Management:Unified dashboards consolidate roster decisions, tactical planning, and medical protocols across departmental silos. Bundesliga and Premier League clubs drive adoption, compelled by CSRD-aligned reporting requirements that demand auditable athlete welfare documentation.
- Player Performance:Individual athlete monitoring isolates biomechanical load thresholds and injury risk indicators. Spanish La Liga academies and French Ligue 1 training centers concentrate investment here, constrained by EU AI Act documentation mandates for predictive algorithms.
- Event Analytics:Real-time processing of match data for broadcast augmentation and wagering integrity.
- Audience Insights:Behavioral segmentation of viewership patterns across streaming and stadium touchpoints.
Team Management commands the premium pricing tier; Player Performance scales fastest among mid-market clubs.
End User:
Customer type fragmentation pits capital-rich professional organizations against resource-constrained coaches seeking portable analytics tools.
- Professional Teams:Full-stack deployments spanning performance, medical, and commercial operations. English football clubs and German handball franchises anchor procurement, navigating GDPR cross-border transfer rules for multinational player rosters.
- Coaches:Mobile-first applications delivering tactical visualization without IT infrastructure dependency. Independent operators in Italy and Spain favor these solutions, limited by federation interoperability standards that complicate data portability.
- Sports Organizations:Federation-level standardization initiatives and centralized data lake governance.
- Event Managers:Temporary infrastructure for single-match or tournament analytics requirements.
Professional Teams absorb the majority of platform expenditure; Coaches represent the most price-elastic demand segment.
Deployment:
Supply concentration in cloud infrastructure providers is compressing margins for hybrid architectures that blend on-premises control with elastic scaling.
- Cloud-Based:Elastic compute resources scale processing capacity during match-day analytics spikes without capital-intensive server farms. Mid-tier Italian Serie A and Spanish Segunda División clubs concentrate adoption here, driven by subscription procurement models that displace perpetual licenses.
- Edge Computing:Pitch-side inference units reduce tactical recognition latency from centralized processing delays. Bundesliga clubs and Premier League training grounds deploy these systems, compelled by live substitution recommendations requiring sub-100-millisecond response times.
- On-Premises:Dedicated hardware installations for organizations with stringent data sovereignty requirements.
- Hybrid:Partitioned workloads separating sensitive biometric storage from scalable analytics processing.
Cloud-Based deployment captures the broadest addressable base; Edge Computing climbs the fastest as latency requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's sports analytics trade flows reflect a net importer position in wearable hardware and a net exporter position in cloud-native software platforms. Cross-border data transfers under GDPR constrain physical device shipments while licensing revenues from analytics engines flow toward German and English federation headquarters.
Germany
Bundesliga clubs drive demand for edge-computing pitch-side inference units that compress tactical recognition latency. The EU AI Act's conformity assessment mandates from ECHA and national regulators compel vendors to pre-certify transparency frameworks for automated recruitment tools. Munich and Dortmund industrial clusters host training grounds deploying sub-100-millisecond response systems for live substitution recommendations.
United Kingdom
Premier League broadcast-rights holders fund analytics infrastructure to power direct-to-consumer subscription platforms and personalized fan engagement engines. GDPR constraints from the Information Commissioner's Office limit biometric data storage architectures for multinational player rosters. London and Manchester concentrate procurement of unified team management dashboards that consolidate roster decisions across departmental silos.
Spain
La Liga academies concentrate investment in individual player performance monitoring for biomechanical load threshold analysis. Spanish data protection authority guidelines intersect with EU AI Act documentation mandates for predictive injury algorithms. Barcelona and Madrid training centers negotiate outcome-tied contracts where platform fees scale with measurable performance improvements.
Italy
Serie A mid-tier clubs favor cloud-based deployments that displace capital-intensive on-premises server farms through subscription procurement models. CSRD-aligned ESG reporting requirements from EU regulators create demand for platforms quantifying athlete welfare metrics. Milan and Turin industrial zones lag German counterparts in analytics penetration, creating whitespace for elastic compute resource providers.
France
Ligue 1 organizations pursue digitization investments to close the analytics penetration gap with Bundesliga and Premier League counterparts. CNIL enforcement of biometric data localization requirements inflates operational expenditures for wearable technology providers transferring physiological metrics. Paris and Lyon training centers prioritize mobile-first tactical visualization tools that minimize IT infrastructure dependency.
Europe Sports Analytics Market Competitive Landscape
Concentration sits with integrated hardware-software platforms and cloud-native federation suites. The vendor landscape bifurcates between compliant enterprise architectures and constrained point solutions navigating EU AI Act risk classifications. Three archetypes dominate: wearable-telemetry specialists capturing real-time biomechanical load data, cloud infrastructure providers serving multi-sport federations through centralized data lakes, and wagering-data integrators monetizing proprietary partnerships with rights holders. Competitive moves center on M&A activity consolidating sensor hardware capabilities and strategic partnerships aligning vendor roadmaps with federation-level standardization initiatives.
Within the integrated hardware tier, Catapult Group International Ltd and Sportradar AG exemplify contrasting approaches to athlete data monetization. SAP SE occupies a position among cloud-native architecture providers serving multi-sport governance bodies. These three entities represent the strategic spectrum from physical sensor deployment through federated data governance to commercial data partnerships.
| Leading Market Players |
|---|
| Catapult Group International Ltd |
| Stats Perform |
| SAP SE |
| International Business Machines Corp |
| Oracle Corporation |
| Genius Sports Ltd |
| deltatre |
| TruMedia Networks |
| Sportradar AG |
| Others |
Supply & Pricing Matrix
Sensor-hardware scale economies in GPS and accelerometer production compress unit costs for wearable-telemetry vendors while elevating price floors for cloud-native software platforms that lack manufacturing leverage. Bundesliga and Premier League procurement concentration amplifies buyer power, forcing tiered pricing concessions from vendors dependent on elite club reference accounts.
Pricing Analysis
Professional football clubs anchor subscription-based pricing structures across performance analytics platforms, with three-tier pricing stratifying across premium, standard, and economy levels based on data volume entitlements and federation certification status. Price differentiation rests on GDPR compliance tier and edge-computing latency guarantees, with German and English buyers commanding steepest discounts through multi-year federation-wide contracts. Cost compression in wearable hardware components intensifies pricing pressure on sensor-centric vendors, while pure-software providers retain margin resilience. Mid-tier Italian and Spanish clubs exhibit highest price sensitivity, constrained by capital scarcity and outcome-tied procurement models.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for edge-computing inference units deployed in pitch-side tactical recognition systems. Germany and China concentrate optical sensor assembly for computer vision pipelines, while Ireland and the Netherlands host GDPR-compliant data lake infrastructure serving federated governance requirements. Raw material dependencies span silicon wafers, lithium-ion cells for portable telemetry devices, and specialized glass for stadium camera arrays. Single-source vulnerability concentrates in EU AI Act certification bodies, where ECHA conformity assessment bottlenecks delay vendor product launches. Distribution runs through federation-licensed systems integrators that bundle hardware deployment with regulatory compliance consulting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is accelerating as Bundesliga and Premier League procurement committees consolidate vendor shortlists around pre-certified transparency frameworks, compressing margins for non-compliant point solutions.
For Market Incumbents: Fortify competitive moats through backward integration into wearable sensor manufacturing and pre-certification of algorithmic transparency documentation under EU AI Act high-risk classification protocols. Catapult Group International Ltd and SAP SE demonstrate defensive positioning through federation-level data lake partnerships that embed switching costs. Edge-computing latency guarantees below 100 milliseconds represent the priority capability investment for retaining elite club accounts against computer vision substitution threats. For New Entrants and Emerging Players: EU AI Act fast-track certification for injury prediction algorithms creates entry pathways into French Ligue 1 and Italian Serie A mid-tier clubs underserved by incumbent sales coverage. White-space concentrates in mobile-first tactical visualization tools for independent coaches lacking IT infrastructure, and in CSRD-aligned ESG reporting modules quantifying athlete welfare metrics for German federation compliance. Go-to-market leverage rests on outcome-tied pricing models that align vendor compensation with measurable broadcast engagement or performance improvement metrics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform providers serving multi-sport federations through centralized data lake architectures, with subscription renewal rates exceeding hardware-dependent peers. Long-term viability across the projection horizon favors vendors with pre-certified EU AI Act compliance and established GDPR cross-border transfer protocols. Acquisition targets should demonstrate federation interoperability standards alignment and elastic compute infrastructure partnerships. The signal to watch is ECHA conformity assessment timeline compression, which will accelerate vendor consolidation toward compliant enterprise platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | ECHA transparency framework documentation accelerates procurement cycles for German and English federation contracts. |
| Edge-Computing Infrastructure Deployment | Pitch-side inference units below 100-millisecond latency enable live substitution recommendations for Bundesliga clubs. |
| Federation Data Lake Partnership | Centralized GDPR-compliant governance models satisfy cross-border biometric transfer requirements for multinational rosters. |
| Computer Vision Platform Integration | Optical tracking convergence with wearable data creates tactical pattern recognition products for rugby and football academies. |
| Outcome-Tied Pricing Model Launch | Performance-scaled contracts align vendor risk with measurable engagement metrics for Italian and Spanish mid-tier adoption. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sports technology procurement officers, federation data governance leads, and wearable hardware engineering directors; and secondary validation through ECHA regulatory filings, GDPR enforcement decisions from national data protection authorities, and federation standardization initiative documentation. Bottom-up triangulation aggregated vendor revenue disclosures and club-level deployment counts, while top-down validation cross-referenced broadcast-rights holder infrastructure investment disclosures. Primary fieldwork spanned German Bundesliga clubs, English Premier League training grounds, and Spanish La Liga academies to capture deployment pattern variance across compliance maturity tiers.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning deployment architecture, end-user scale tier, and federation regulatory cluster. CAGRs derived from elastic adoption curve modeling of cloud-native platform penetration among capital-constrained mid-tier clubs, cross-referenced with hardware shipment volumes from sensor vendors. Industry-specific inputs incorporated EU AI Act implementation timeline scenarios and CSRD-aligned ESG reporting mandate effective dates. Volume projections weighted German and English federation procurement concentration against whitespace opportunity in French and Italian market development.
Underlying assumptions cover GDPR enforcement consistency and ECHA certification capacity, with deviation risk concentrated in EU AI Act risk-classification redefinitions and biometric data localization requirement expansions. Recalibration cycles align with material shifts in federation standardization initiatives and broadcast-rights holder direct-to-consumer platform investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
Fantasy Sports Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
India Fantasy Sports Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Daily Fantasy Sports Market