
 Wearable Inertial Sensors Market | 2026-2036
Wearable Inertial Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Inertial Sensors Market Analytics
Software-defined calibration and remote firmware update services is shifting how sensor vendors monetize hardware deployments. Bosch Sensortec GmbH leverages its MEMS foundry scale to dominate consumer-grade accelerometer supply. STMicroelectronics anchors high-volume production through integrated manufacturing in European and Asian facilities. Analog Devices differentiates on precision gyroscope architectures for aerospace-grade wearable applications.
Wearable inertial sensors integrate microelectromechanical systems measuring linear acceleration, angular velocity, and magnetic heading with typical noise densities below 0.01 degrees per second per root hertz, serving motion capture and dead-reckoning navigation in portable electronics. Inertial measurement units command the highest unit values by fusing multi-axis data streams for clinical gait analysis and military helmet tracking. MEMS technology leads unit shipments through semiconductor-compatible batch fabrication, while optical gyroscope variants occupy premium tiers where drift tolerance below one degree per hour justifies cost.
FDA clearance pathways for Class II diagnostic wearables shape product development timelines for health-monitoring applications in the United States. The EU Medical Device Regulation and ISO 13485 quality management standards govern market access for clinical-grade inertial sensors distributed in Europe. Stakeholders must weigh regulatory jurisdiction against reimbursement velocity when selecting initial launch markets for new wearable sensor form factors.
Market Dynamics
Software-defined calibration protocols are compressing hardware refresh cycles as sensor vendors pivot toward recurring firmware revenue streams anchored by remote update infrastructure.
Growth Catalysts
- EU Medical Device Regulation:Clinical validation mandates for health-monitoring wearables are elevating entry barriers that favor established suppliers with ISO 13485-certified quality systems.
- Biomechanical feedback integration:Sports teams and rehabilitation clinics are embedding inertial measurement units into athlete-worn garments for real-time motion capture and injury prevention protocols.
- Precision electronics manufacturing:Japan's manufacturing belt is concentrating high-volume MEMS fabrication capacity that feeds consumer and industrial sensor demand simultaneously.
Market Restraints
- MEMS foundry concentration:Bosch Sensortec's dominance in consumer-grade accelerometer supply creates single-source vulnerability for mid-tier wearable manufacturers.
- Optical gyroscope cost structure:Premium-tier drift tolerance below one degree per hour requires non-semiconductor fabrication processes that resist scale economies.
- FDA clearance timelines:Class II diagnostic wearable pathways extend product development cycles by 18-36 months versus consumer wellness devices.
Strategic Opportunities
- Clinical gait analysis:Inertial measurement units fusing multi-axis data streams command premium unit values in European rehabilitation networks seeking objective mobility metrics.
- Aerospace-grade precision:Analog Devices' gyroscope architectures are penetrating military helmet tracking applications where magnetic interference disqualifies standard MEMS alternatives.
- Germany's industrial corridor:Factory automation and exoskeleton developers are sourcing calibrated inertial sensors for worker safety monitoring and ergonomic optimization.
Industry Challenges
- Calibration talent scarcity:Firmware engineers capable of implementing noise-density optimization below 0.01 degrees per second per root hertz command salaries that strain mid-cap sensor houses.
- Dead-reckoning integration:Portable electronics manufacturers face complexity unifying inertial data with GPS dropout compensation in battery-constrained form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Inertial Sensors Market |
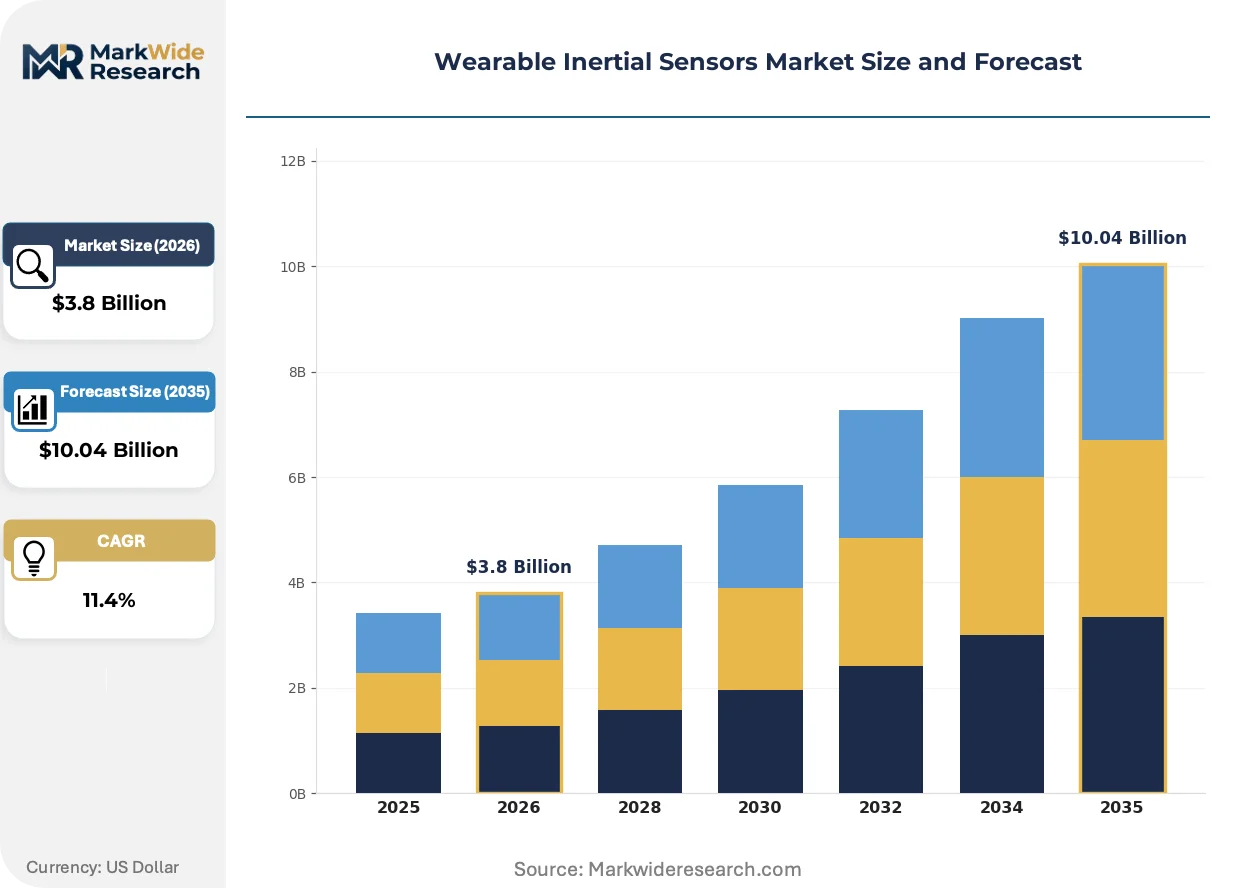
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Magnetometers, Inertial Measurement Units Technology: MEMS, Optical, Capacitive, Piezoelectric End User: Fitness Enthusiasts, Healthcare, Military, Sports Application: Health Monitoring, Motion Tracking, Navigation, Gaming |
| Companies Covered | STMicroelectronics, Analog Devices, Bosch Sensortec GmbH, Texas Instruments, Xsens (Movella Inc.), InvenSense (TDK Corporation), NXP Semiconductors, TE Connectivity, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Inertial Sensors Market Evolving Landscape
Sensor fusion architectures are collapsing the boundary between consumer wellness and clinical-grade monitoring, forcing vendors to recalibrate certification strategies and pricing models simultaneously.
Edge-resident sensor fusion is rewriting how motion data gets processed. Inertial measurement units now embed onboard Kalman filtering that eliminates host-processor dependency for real-time orientation tracking. Wearable manufacturers in Germany and Japan are adopting these system-in-package designs to reduce bill-of-materials complexity. The shift is compressing value capture toward semiconductor vendors while eroding margins for downstream firmware integrators.
REACH substance restrictions and RoHS recast directives are tightening material compliance for European-distributed wearables. Battery housings and solder joints face enhanced scrutiny for restricted substance thresholds that affect MEMS packaging reliability. Sensor vendors with integrated European manufacturing footprints are absorbing compliance costs internally while Asian contract manufacturers pass through certification fees.
Hospital procurement committees are consolidating vendor relationships around single-source suppliers capable of spanning wellness, diagnostic, and research applications. Integrated delivery networks in the United States are demanding unified data formats across inertial sensor deployments that span patient monitoring, staff safety, and asset tracking. This concentration is privileging vendors with FDA-cleared portfolios over point-solution specialists.
Wearable Inertial Sensors Market Segmentation
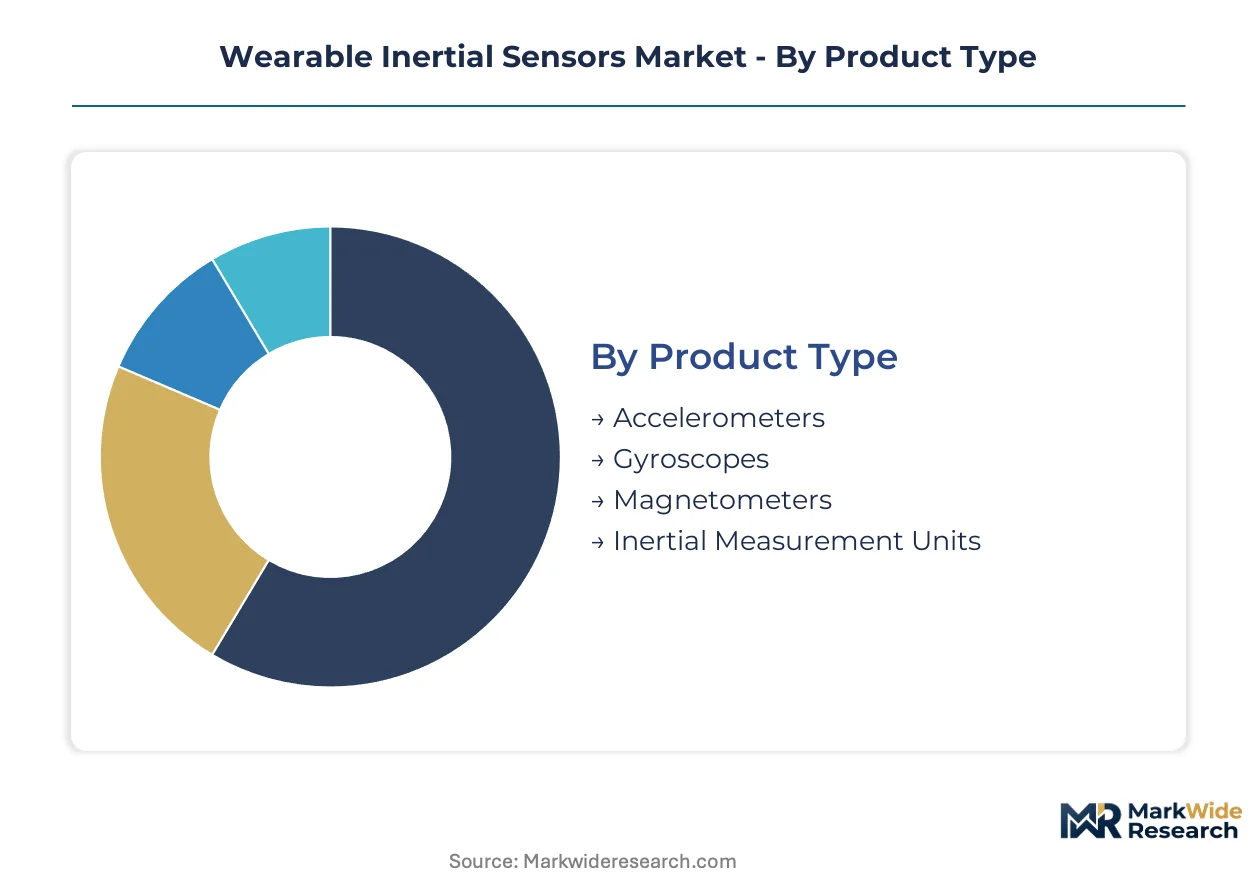
Segmentation in wearable inertial sensors reveals divergent buyer priorities across certification tiers, fabrication methods, and use-case precision requirements. Understanding these fault lines enables vendors to align R&D spend with segments commanding premium pricing versus those competing on semiconductor scale.
Product Type:
Buyers in this category separate by whether they need discrete axis measurement or fused multi-axis data streams for their specific motion-capture application.
- Accelerometers:MEMS-based devices measuring linear acceleration dominate unit economics through batch semiconductor fabrication. Consumer wellness bands and smartphone stabilization systems in Japan's precision manufacturing belt absorb the highest shipment volumes, though price compression limits margin expansion.
- Inertial Measurement Units:These fuse accelerometer, gyroscope, and magnetometer outputs through onboard sensor fusion algorithms for six-to-nine degrees of freedom tracking. European rehabilitation clinics and German industrial exoskeleton developers pay substantial premiums for calibrated IMUs delivering clinical-grade gait metrics.
- Gyroscopes:Angular velocity sensors with noise densities below 0.01 degrees per second per root hertz serve aerospace helmet tracking and high-end gaming controllers.
- Magnetometers:Magnetic heading reference sensors compensate for gyroscope drift in dead-reckoning navigation applications.
Volume sits with accelerometers; growth tilts toward inertial measurement units.
Technology:
Technology selection hinges on the tradeoff between semiconductor-compatible batch economics and drift tolerance thresholds that justify non-standard fabrication.
- MEMS:Microelectromechanical systems leverage silicon wafer processing for sub-dollar unit costs at million-piece scale. Bosch Sensortec's foundry dominance feeds consumer-grade demand across Germany's industrial corridor and Japan's electronics manufacturing belt.
- Optical:Ring laser and fiber-optic gyroscopes achieve drift below one degree per hour through precision optical cavity fabrication. Military helmet tracking programs and aerospace applications in the United States absorb limited production runs despite five-figure unit pricing.
- Capacitive:Electrostatic force-rebalance architectures offer intermediate precision for industrial motion-capture systems.
- Piezoelectric:Crystal-based vibration sensing serves niche high-shock environments where MEMS fragility disqualifies standard approaches.
MEMS commands absolute volume; optical claims the steepest expansion trajectory as defense budgets prioritize magnetic-immune precision.
End User:
End-user segmentation tracks regulatory burden divergence, from unregulated consumer wellness through FDA-cleared diagnostic applications.
- Healthcare:Clinical-grade inertial sensors face EU Medical Device Regulation validation requirements and FDA Class II clearance pathways. German rehabilitation networks and United States integrated delivery networks consolidate procurement around ISO 13485-certified suppliers capable of spanning patient monitoring and staff safety.
- Military:Helmet-mounted tracking systems demand ITAR-compliant supply chains and drift tolerance below one degree per hour. Analog Devices' precision gyroscope architectures penetrate this segment where standard MEMS fail under magnetic interference.
- Sports:Professional teams embed IMUs into athlete-worn garments for real-time biomechanical feedback and injury prevention protocols.
- Fitness Enthusiasts:Consumer wellness bands and running watches absorb commodity accelerometers with minimal calibration requirements.
Healthcare delivers the highest average selling prices; sports applications are climbing fastest as professional leagues mandate wearable analytics.
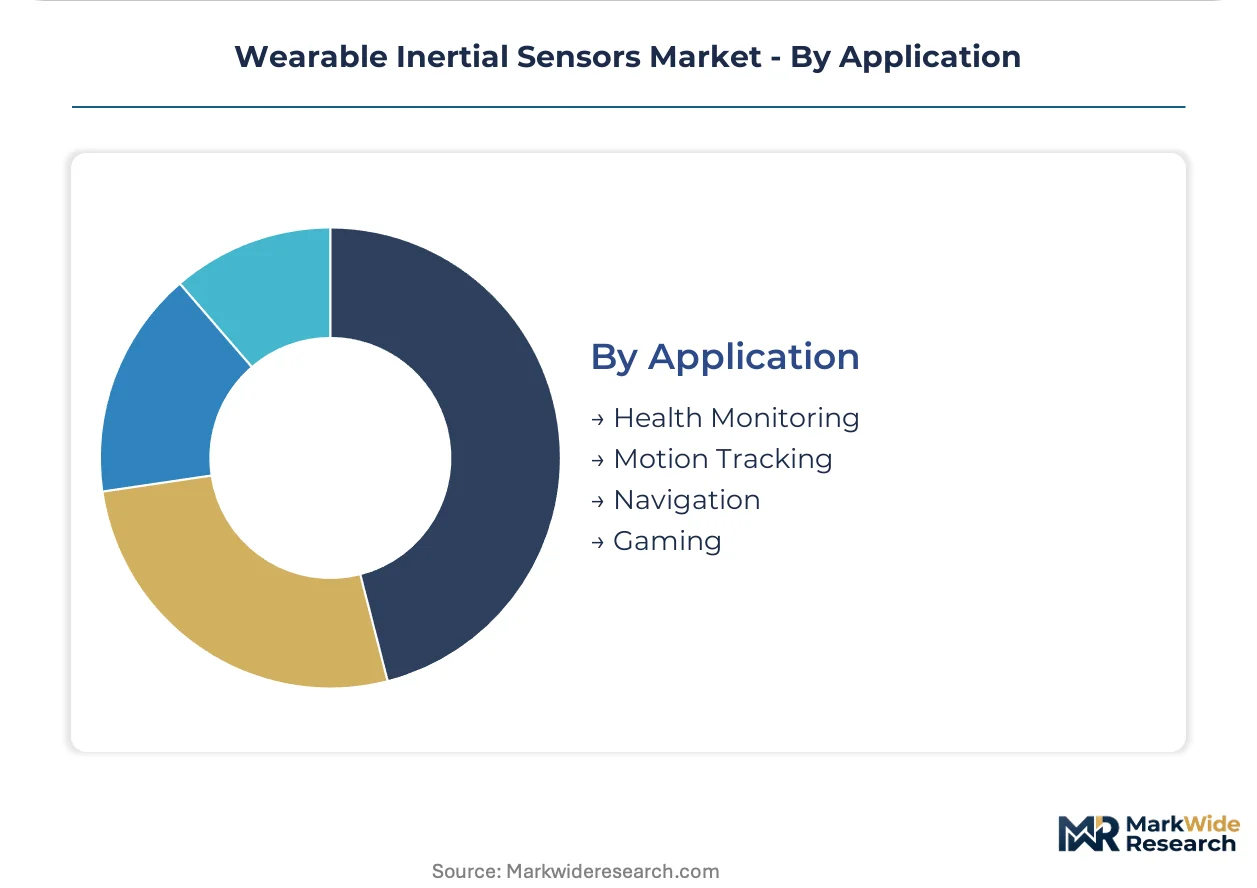
Application:
Application segmentation reflects the collision between consumer wellness expectations and clinical-grade diagnostic requirements.
- Health Monitoring:Continuous gait analysis and fall detection algorithms process inertial data through FDA-cleared or EU MDR-validated pathways. Hospital procurement committees in the United States favor vendors offering unified data formats across patient monitoring, staff safety, and asset tracking deployments.
- Motion Tracking:Real-time orientation estimation serves animation production, sports biomechanics, and industrial ergonomics. Edge-resident Kalman filtering in system-in-package designs reduces host-processor dependency for German factory automation integrators.
- Navigation:GPS dropout compensation in portable electronics fuses inertial dead-reckoning with satellite fixes.
- Gaming:Controller motion sensing and virtual reality head tracking absorb high-volume MEMS with relaxed drift specifications.
Health monitoring captures premium pricing; motion tracking applications are expanding most quickly as edge AI reduces integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial sensor corridor around Munich and Stuttgart anchors European demand for calibrated inertial measurement units. Japan's precision electronics manufacturing belt feeds high-volume MEMS fabrication for consumer and industrial applications simultaneously.
United States
FDA clearance pathways for Class II diagnostic wearables shape product development timelines for health-monitoring applications. The agency's 510(k) and De Novo review processes extend commercialization cycles by 18-36 months versus consumer wellness devices. Hospital procurement committees in Boston and the San Francisco Bay Area consolidate vendor relationships around single-source suppliers capable of spanning patient monitoring, staff safety, and asset tracking.
Germany
Factory automation and exoskeleton developers in Baden-Württemberg source calibrated inertial sensors for worker safety monitoring and ergonomic optimization. The EU Medical Device Regulation tightens clinical validation requirements for health-monitoring wearables distributed throughout the single market. Stuttgart's automotive and industrial robotics cluster absorbs precision gyroscopes for motion-capture systems in manufacturing lines.
Japan
METI's industrial digitization initiatives accelerate MEMS sensor deployment across precision manufacturing and healthcare sectors. The country's national pharmaceutical regulator, PMDA, governs market access for clinical-grade inertial sensors used in rehabilitation and gait analysis. Kyushu's semiconductor fabrication facilities concentrate high-volume production capacity that feeds consumer electronics and automotive sensor demand.
China
NMPA medical device registration requirements create parallel pathways for domestic and imported wearable diagnostic sensors. The MIIT's industrial internet policies promote sensor fusion architectures in factory automation and smart manufacturing. Shenzhen's electronics manufacturing ecosystem produces consumer-grade accelerometers at scale while absorbing imported precision components for higher-tier applications.
South Korea
MFDS medical device approval processes govern clinical-grade wearable sensor market entry for rehabilitation and health-monitoring applications. The Seoul Capital Area's consumer electronics manufacturers integrate MEMS inertial units into smartphones, wearables, and gaming peripherals. Daegu-Gyeongbuk's automotive component suppliers source motion sensors for vehicle stability control and advanced driver assistance systems.
Wearable Inertial Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the wearable inertial sensor value chain. Foundry operators with captive MEMS fabrication capacity face off against fabless semiconductor houses specializing in sensor fusion algorithms and calibration software. Three strategic archetypes dominate: integrated device manufacturers controlling wafer-to-package production, precision sensor specialists serving aerospace and military tiers, and platform vendors bundling hardware with recurring firmware services. Competitive moves center on backward integration into MEMS foundry capacity and strategic partnerships with wearable OEMs for co-development of system-in-package designs.
Within the integrated manufacturing tier, STMicroelectronics and Bosch Sensortec GmbH exemplify scale-driven positions anchored by European foundry footprints. Analog Devices occupies a distinct precision-tier position serving applications where drift tolerance and magnetic immunity justify premium positioning. These three entities represent the structural poles around which mid-cap specialists and regional fabricators organize their competitive strategies.
| Leading Market Players |
|---|
| STMicroelectronics |
| Analog Devices |
| Bosch Sensortec GmbH |
| Texas Instruments |
| Xsens (Movella Inc.) |
| InvenSense (TDK Corporation) |
| NXP Semiconductors |
| TE Connectivity |
| Honeywell International |
| Others |
Value Network & Pricing Analysis
Firmware engineers capable of noise-density optimization below 0.01 degrees per second per root hertz cluster in Germany's industrial sensor corridor and Japan's precision electronics belt, creating labor-cost differentials that widen pricing spreads between clinical-grade and consumer-tier inertial sensors.
Pricing Analysis
Value-based pricing anchored to clinical outcome metrics dominates EU and US healthcare procurement, where rehabilitation networks pay premiums for calibrated gait analysis validated under EU Medical Device Regulation and FDA Class II pathways. Price differentiation separates ISO 13485-certified diagnostic tiers from consumer wellness bands through certification investment and magnetic-immunity specifications. Cost compression in commodity accelerometers intensifies as Bosch Sensortec's MEMS foundry scale feeds high-volume smartphone and fitness wearable demand. Sports team buyers exhibit lowest price sensitivity, prioritizing real-time biomechanical feedback over per-unit costs.
Supply Chain Analysis
Freight cost volatility from Asian component hubs to European assembly sites elevates landed costs for calibrated inertial measurement units requiring temperature-controlled transit. Supply concentrates in Japan's Kyushu semiconductor belt for MEMS wafer fabrication, Germany's Stuttgart corridor for precision gyroscope packaging, and China's Shenzhen ecosystem for consumer-grade module integration. Raw material dependencies include silicon wafers, rare-earth magnetic materials for magnetometers, and specialized ceramic substrates for high-temperature stability. Single-source vulnerability around Bosch Sensortec's consumer accelerometer dominance creates procurement risk for mid-tier wearable OEMs. Distribution runs through direct hospital procurement committees in the United States and specialized industrial sensor distributors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a technology-transition inflection where edge-resident sensor fusion with onboard Kalman filtering displaces host-processor-dependent architectures, compressing value capture toward semiconductor vendors and eroding margins for downstream firmware integrators.
For Market Incumbents: Deepen captive MEMS foundry capacity in European and Asian facilities to defend against fabless competitors specializing in calibration software. Secure ISO 13485 certification breadth spanning wellness, diagnostic, and research applications to meet hospital procurement committee demands for unified vendor relationships. Counter edge-AI displacement threat by bundling hardware with recurring firmware update services.
For New Entrants and Emerging Players: Direct-to-clinic digital channels bypass entrenched distributor relationships in European rehabilitation networks seeking objective mobility metrics. Target Germany's industrial exoskeleton developers and factory automation integrators with system-in-package designs reducing bill-of-materials complexity. Penetrate sports analytics white space through IMU-embedded athlete garment partnerships with professional leagues mandating wearable biomechanical feedback.
For Investors and Strategic Acquirers: Re-rating potential sits with precision sensor specialists serving aerospace and military tiers given defense budget prioritization of magnetic-immune drift tolerance below one degree per hour. Long-term viability favors acquisition targets with ITAR-compliant supply chains and integrated European manufacturing footprints absorbing REACH and RoHS compliance costs internally. Watch for inflection in hospital procurement consolidation around single-source suppliers capable of spanning patient monitoring, staff safety, and asset tracking deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | STMicroelectronics and Bosch Sensortec anchor scale-driven positions through European wafer-to-package production control. |
| Sensor Fusion Algorithm Development | Onboard Kalman filtering eliminates host-processor dependency for German factory automation integrators. |
| EU Medical Device Regulation Certification Investment | ISO 13485 quality systems elevate entry barriers favoring established suppliers in European rehabilitation networks. |
| Strategic Partnership with Wearable OEMs | Co-development of system-in-package designs reduces bill-of-materials complexity for Japan's precision electronics manufacturers. |
| Remote Firmware Update Infrastructure Deployment | Software-defined calibration protocols pivot sensor vendors toward recurring revenue streams anchored by update services. |
Research Methodology
SEC filings, EU Medical Device Regulation submission databases, and hospital procurement contract records formed the secondary backbone, cross-referenced with primary interviews involving MEMS foundry operations directors, biomedical engineers at German rehabilitation clinics, and FDA regulatory affairs specialists managing Class II diagnostic wearable pathways. Bottom-up shipment estimates by product type and technology tier were reconciled with top-down market size assessments derived from semiconductor industry trade data and customs records for inertial sensor component flows.
Bottom-up modeling segmented volume and value across accelerometer, inertial measurement unit, gyroscope, and magnetometer categories, further disaggregated by MEMS versus optical fabrication technology and healthcare versus military versus sports end-use applications. CAGRs were derived from regression analysis of historical shipment trends and forward projection of edge-AI adoption rates in portable electronics. Industry-specific forecast inputs included PMDA medical device approval timelines for Japan's rehabilitation sector and METI industrial digitization initiative spending patterns.
The model holds under stable regulatory clearance timelines and continued defense budget prioritization of precision navigation; deviation in FDA 510(k) review duration or export control tightening on ITAR-compliant components would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Breathing Wear Market