
 Stress Tracking Devices Market | 2026-2036
Stress Tracking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Tracking Devices Market Analytics
Graphene-enhanced flexible electrodes are rebalancing sensor economics in wearable stress monitors by cutting production costs while improving signal fidelity. WHOOP leverages proprietary heart rate variability algorithms to sustain premium positioning in athletic and corporate segments. Apple Inc. anchors mainstream adoption through tight integration with its health ecosystem and retail scale. Garmin Ltd. dominates outdoor and aviation stress-monitoring niches with purpose-built hardware durability.
Stress tracking devices are electronic systems that capture physiological indicators—primarily heart rate variability, electrodermal activity, and sleep architecture—to quantify autonomic nervous system load and cognitive strain. These systems typically employ photoplethysmography sensors sampling at 100-512 Hz alongside accelerometers, transmitting encrypted data to cloud analytics platforms for pattern recognition and intervention alerting. Wearable devices lead current revenue pools due to continuous monitoring capability and consumer familiarity, while smartphone apps represent the fastest-expanding segment as software-only deployment slashes hardware barriers for employers and insurers. Corporate wellness programs command disproportionate margin attention because annual contracts bundle device provisioning with analytics dashboards and coaching services.
FDA clearance requirements for medical-grade stress monitors and HIPAA data-handling rules constrain market entry in the United States, compelling vendors to invest in clinical validation and cybersecurity infrastructure. The EU AI Act and GDPR impose additional algorithmic transparency and consent-management burdens on vendors serving European employers. Stakeholders must weigh regulatory compliance costs against the pricing power that certified, privacy-assured platforms command in risk-sensitive buyer segments.
Market Dynamics
Corporate wellness programs are restructuring demand architecture for stress tracking devices by bundling biometric hardware with analytics platforms and coaching services, forcing vendors to pivot from consumer retail toward annual enterprise contracts with embedded data services.
Growth Catalysts
- FDA 510(k) clearance pathways:Medical-grade certification for heart rate variability monitors opens reimbursement channels through employer-sponsored health plans in the United States.
- Graphene electrode manufacturing:Flexible sensor production costs are declining while signal fidelity improves, enabling thinner form factors in wrist-worn devices.
- Enterprise mental health mandates:Post-pandemic duty-of-care obligations are compelling Fortune 500 employers to quantify workforce cognitive strain through continuous physiological monitoring.
Market Restraints
- Photoplethysmography sensor supply concentration:High-precision optical components rely on a limited base of Asian contract manufacturers, creating vulnerability to semiconductor allocation disruptions.
- HIPAA compliance infrastructure costs:End-to-end encryption, audit logging, and business associate agreements impose fixed overhead that excludes sub-scale software vendors from enterprise procurement.
- Smartphone camera HRV apps:Software-only alternatives using existing device sensors threaten dedicated hardware adoption among price-sensitive consumer segments.
Strategic Opportunities
- EU AI Act algorithmic transparency requirements:Early compliance with explainable stress-scoring models creates differentiation for vendors targeting European corporate buyers.
- Insurer wellness incentive programs:Life and health underwriters are piloting premium discounts tied to verified stress management data, opening B2B2C distribution.
- Photoplethysmography-electrodermal fusion:Multi-modal sensor convergence enables anxiety-specific detection beyond generic autonomic load measurement.
Industry Challenges
- Clinical validation timelines:FDA 510(k) submissions for novel HRV algorithms require 12-18 month prospective studies, delaying product launches against faster-moving software competitors.
- Interoperability with legacy HR systems:Enterprise wellness platforms demand API integration with established payroll, benefits administration, and EHR infrastructure, stretching engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Tracking Devices Market |
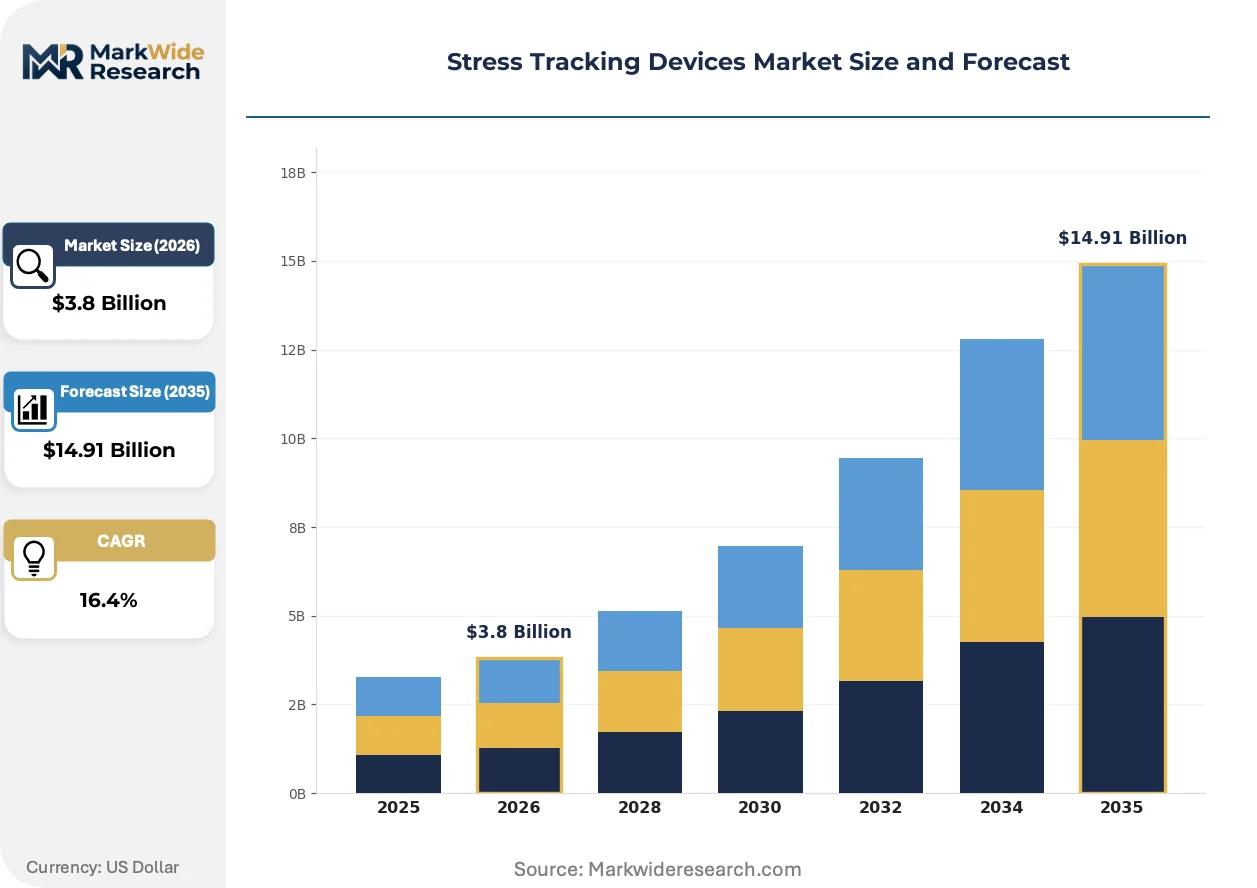
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smartphone Apps, Desktop Applications, Hybrid Solutions End User: Consumers, Corporate Wellness Programs, Healthcare Providers, Insurance Companies Technology: Biometric Sensors, Heart Rate Monitors, Sleep Trackers, Mobile Analytics Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Medical Supply Distributors |
| Companies Covered | Oura Health Oy, WHOOP, Apple Inc., Empatica, NeuroSky, Samsung Electronics, Garmin Ltd., Biostrap, Google LLC (Fitbit), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Tracking Devices Market Evolving Landscape
Sensor miniaturization and edge computing are collapsing the boundary between medical-grade precision and consumer convenience, while regulatory frameworks on both sides of the Atlantic are hardening data governance requirements that favor established vendors with compliance infrastructure.
Photoplethysmography sampling architectures are consolidating around 512 Hz acquisition rates with motion-artifact rejection algorithms, enabling clinical-grade heart rate variability extraction from wrist-worn form factors. Hospital systems and self-insured employers are adopting these devices for remote patient monitoring and workforce wellness programs. This technical convergence is consolidating competitive advantage around vendors with proprietary signal processing IP and FDA-cleared algorithms.
The EU AI Act's risk classification system for biometric emotion recognition is mandating algorithmic impact assessments and human oversight protocols for stress-scoring systems deployed in workplace settings. Vendors serving European corporate clients must document training data provenance and model performance across demographic subgroups. Stress tracking platforms with opaque machine-learning pipelines face exclusion from procurement shortlists in Germany, France, and the Netherlands.
Employer purchasing committees are unbundling device provisioning from analytics and coaching services, forcing hardware vendors to compete on unit economics while specialist platforms capture recurring software revenue. This disintermediation is compressing margins for integrated solution providers and elevating pure-play analytics vendors with superior dashboard customization. The United States exhibits the most pronounced unbundling, where benefits consultants increasingly specify multi-vendor architectures.
Stress Tracking Devices Market Segmentation
Device upgrade cycles and replacement patterns vary sharply across stress tracking modalities. Understanding these rhythms helps vendors align inventory planning with enterprise procurement calendars and consumer refresh behavior.
Product Type:
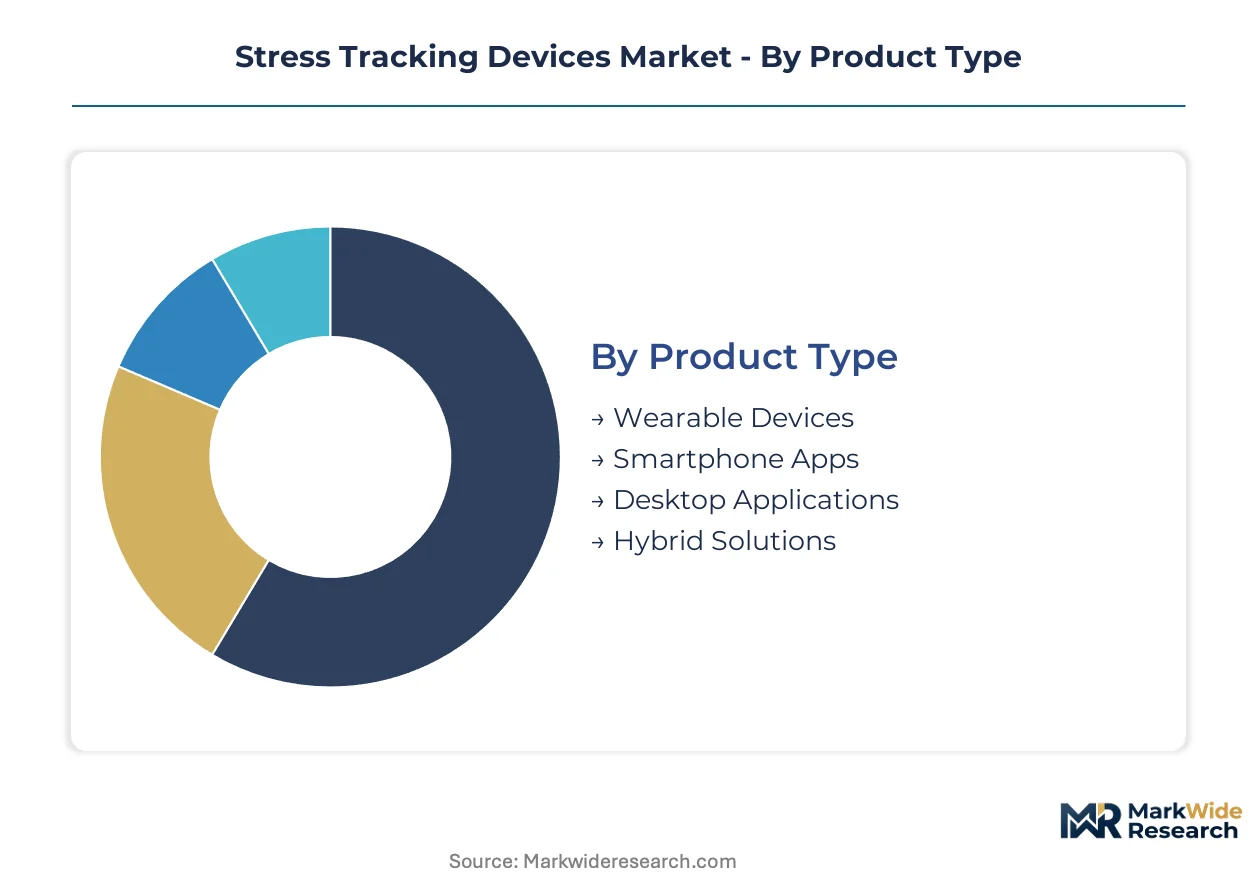
Wearable hardware commands the shortest replacement cycle as battery degradation and sensor obsolescence drive 18-24 month refresh rates among enterprise buyers.
- Wearable Devices:Wrist-worn and patch-form systems integrate photoplethysmography sensors sampling at 100-512 Hz with accelerometry for continuous autonomic monitoring. Corporate wellness programs in the United States concentrate procurement here, compelled by post-pandemic duty-of-care mandates for workforce cognitive strain quantification.
- Smartphone Apps:Software-only deployments leverage existing device cameras and accelerometers for heart rate variability estimation, eliminating hardware provisioning overhead. Insurance companies piloting wellness incentive programs favor this modality for rapid member onboarding without logistical complexity.
- Desktop Applications:Stationary systems with external peripherals target clinical and research settings requiring medical-grade precision.
- Hybrid Solutions:Multi-device ecosystems combine wearable sensors with cloud analytics platforms and coaching service layers.
Wearable Devices sits at the top of the volume ranking, with Smartphone Apps climbing the fastest.
End User:
Customer type determines pricing tolerance and contract structure, with enterprise buyers demanding multi-year service bundles while consumers favor transactional purchases.
- Consumers:Individual purchasers prioritize form factor aesthetics and ecosystem integration over clinical validation. United States retail channels concentrate volume here, though price sensitivity limits attachment of premium analytics subscriptions.
- Corporate Wellness Programs:Fortune 500 employers bundle biometric hardware with dashboards and coaching services under annual contracts. HIPAA compliance infrastructure requirements exclude sub-scale vendors from procurement shortlists.
- Healthcare Providers:Hospital systems adopt FDA-cleared devices for remote patient monitoring and stress-related condition management.
- Insurance Companies:Life and health underwriters pilot premium discount programs tied to verified stress management data, opening B2B2C distribution pathways.
Corporate Wellness Programs anchor revenue concentration, with Insurance Companies gaining share fastest as underwriting models integrate biometric verification.
Technology:
Component sourcing geography and regulatory clearance requirements fragment competitive positioning across sensing modalities.
- Biometric Sensors:Graphene-enhanced flexible electrodes are cutting production costs while improving signal fidelity in next-generation form factors. Asian contract manufacturers concentrate supply of high-precision optical components, creating vulnerability to semiconductor allocation disruptions.
- Heart Rate Monitors:Photoplethysmography architectures are consolidating around 512 Hz acquisition with motion-artifact rejection algorithms. FDA 510(k) clearance pathways for novel HRV algorithms require 12-18 month prospective studies, delaying product launches.
- Sleep Trackers:Multi-modal systems combining accelerometry with peripheral temperature and blood oxygen sensing address recovery quantification.
- Mobile Analytics:Edge computing pipelines enable real-time stress scoring without cloud dependency, reducing latency for intervention alerting.
Biometric Sensors dominate component value capture, with Mobile Analytics expanding most quickly as edge AI capabilities mature.
Distribution Channel:
Channel selection shapes margin structure and customer acquisition economics, with direct relationships commanding premium pricing but requiring compliance infrastructure investment.
- Online Retail:E-commerce platforms enable rapid consumer scaling with minimal geographic constraint. United States benefits consultants increasingly specify multi-vendor architectures through digital procurement portals, compressing margins for integrated solution providers.
- Specialty Stores:Focused retail environments allow hands-on device demonstration and personalized fitting services.
- Direct Sales:Enterprise account teams negotiate annual contracts with embedded data services and API integration requirements for legacy HR system compatibility.
- Medical Supply Distributors:Established healthcare logistics networks provide regulatory compliance documentation and clinical training support.
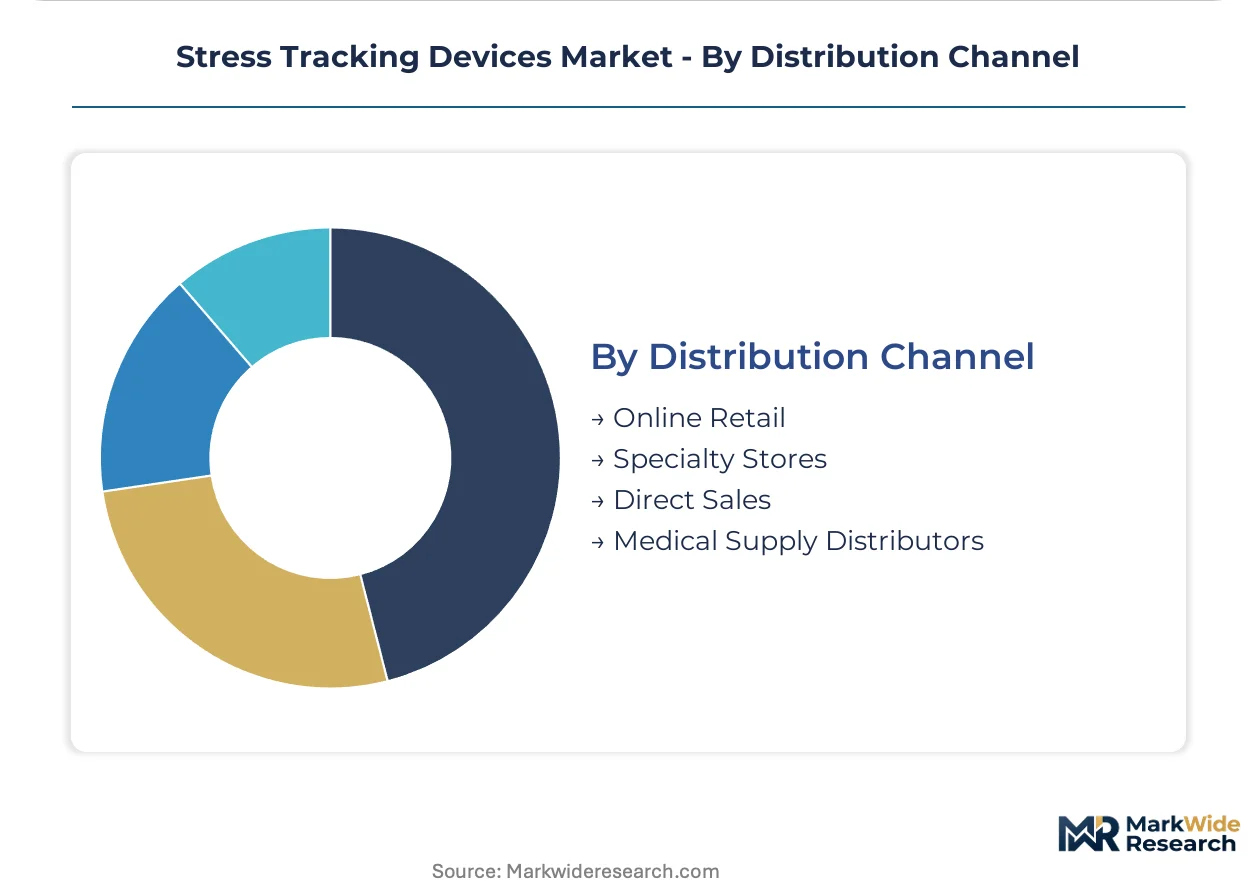
Online Retail leads volume throughput, with Direct Sales capturing the steepest expansion trajectory as enterprise unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of wearable technology developers anchors North American innovation in stress monitoring hardware and algorithm development. Corporate wellness procurement concentrates procurement power among Fortune 500 headquarters clusters. Regulatory divergence between FDA clearance pathways and EU AI Act compliance is fragmenting vendor geographic strategies.
United States
Fortune 500 employers in New York and Chicago metropolitan areas drive enterprise contract volume for biometric monitoring bundles. FDA 510(k) clearance requirements for medical-grade heart rate variability monitors create certification bottlenecks that favor established vendors with clinical validation infrastructure. Boston's medical device corridor hosts specialist firms developing photoplethysmography-electrodermal fusion sensors for anxiety-specific detection.
Germany
Industrial employers in Baden-Württemberg and Bavaria pilot stress tracking programs for manufacturing workforce cognitive strain quantification. EU AI Act algorithmic transparency mandates require documented training data provenance and human oversight protocols for workplace biometric systems. Munich's precision engineering cluster supplies graphene-enhanced flexible electrode components to wearable manufacturers.
United Kingdom
London-based financial services firms deploy continuous monitoring for trader stress management under duty-of-care obligations. GDPR consent-management requirements impose additional engineering burdens on vendors serving British corporate clients. Cambridge's sensor technology hub advances edge computing pipelines for real-time stress scoring without cloud dependency.
Japan
Metropolitan Tokyo employers integrate stress tracking into corporate health insurance schemes administered through keiretsu networks. METI guidelines on workplace digital health tools shape procurement specifications for biometric monitoring platforms. Osaka's electronics manufacturing district produces high-precision optical components for photoplethysmography sensors.
South Korea
Seoul Capital Area technology conglomerates deploy stress monitoring across R&D workforce populations. MFDS medical device regulations create parallel certification tracks for clinical-grade versus wellness-grade stress tracking systems. Suwon's semiconductor cluster supplies motion-artifact rejection algorithm chipsets to regional wearable vendors.
Stress Tracking Devices Market Competitive Landscape
Global majors compete with regional champions across algorithm sophistication and enterprise sales infrastructure dimensions. The vendor base stratifies into three tiers: integrated hardware-software platforms commanding premium enterprise pricing, specialist sensor component suppliers, and software-only analytics vendors capturing recurring revenue from unbundled service layers. Dominant competitive moves include portfolio diversification into adjacent biometric monitoring categories and strategic partnerships with benefits consultants to secure procurement specification influence.
Within the integrated platform tier, Apple Inc. and Garmin Ltd. exemplify divergent positioning strategies that anchor competitive archetypes. WHOOP occupies a position emphasizing proprietary heart rate variability algorithms for athletic and corporate segments. Samsung Electronics represents scale-driven manufacturing integration from component through finished device. Empatica and NeuroSky sit within the specialist medical-grade certification segment where FDA clearance creates defensible positioning against consumer-oriented competitors.
| Leading Market Players |
|---|
| Oura Health Oy |
| WHOOP |
| Apple Inc. |
| Empatica |
| NeuroSky |
| Samsung Electronics |
| Garmin Ltd. |
| Biostrap |
| Google LLC (Fitbit) |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up enterprise wellness platforms anchor pricing discipline through multi-year contract lock-in, while their concentrated procurement power squeezes component suppliers in Taiwan and South Korea. This ownership pattern tightens margin capture at the analytics layer, forcing hardware vendors to absorb photoplethysmography sensor cost volatility or cede enterprise accounts to bundled competitors.
Pricing Analysis
Input-cost pass-through from graphene electrode and optical sensor suppliers is compressing margins for wrist-worn device manufacturers serving price-sensitive consumer segments. Pricing stratifies across FDA-cleared medical tiers, HIPAA-compliant enterprise bundles, and unvalidated wellness-grade hardware, with certification level commanding the steepest premium. Pricing pressure stems from smartphone camera HRV apps eliminating hardware provisioning costs for insurance pilot programs. Corporate wellness buyers exhibit the lowest price sensitivity due to duty-of-care mandate compliance requirements, while individual consumers in United States retail channels drive transactional volume at thinner margins.
Supply Chain Analysis
Single-source vulnerability sits with Asian contract manufacturers concentrated in Taiwan, South Korea, and Japan for high-precision photoplethysmography optical components. Raw material dependencies center on graphene substrates for flexible electrodes, indium gallium arsenide photodetectors, and motion-artifact rejection algorithm chipsets. Supply chain risk hinges on semiconductor allocation disruptions rippling from foundry capacity constraints. Distribution runs through direct sales teams for enterprise accounts, online retail portals for consumer volume, and medical supply distributors for hospital system procurement requiring regulatory documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between United States FDA clearance timelines and European Union AI Act compliance burdens, with the latter imposing heavier algorithmic transparency engineering costs that disadvantage software-only entrants.
For Market Incumbents: Cement enterprise contract renewal rates by embedding proprietary HRV algorithm IP into multi-year service bundles that resist unbundling pressure from benefits consultants. Deepen backward integration into graphene-enhanced electrode production to offset Asian component supplier concentration. Fortify HIPAA compliance infrastructure as a competitive moat against sub-scale software vendors seeking enterprise procurement access.
For New Entrants and Emerging Players: Begin with insurer wellness incentive programs as the most penetrable entry point, leveraging software-only deployment to bypass hardware certification timelines and capital requirements. Target B2B2C distribution through life and health underwriters piloting premium discount verification models. Lead with smartphone camera HRV apps to establish member onboarding scale before expanding into dedicated biometric hardware.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialist sensor component suppliers facing margin compression from integrated platform bundling. Long-term viability centers on vendors with FDA-cleared algorithms and EU AI Act-compliant explainable stress-scoring models. Watch for inflection signals in Fortune 500 employer unbundling behavior, where multi-vendor architecture specifications indicate pure-play analytics vendor elevation over integrated hardware-software providers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Medical-grade certification unlocks employer-sponsored health plan reimbursement channels in United States. |
| EU AI Act Compliance Investment | Algorithmic transparency documentation creates procurement differentiation for European corporate buyers. |
| Photoplethysmography-Electrodermal Fusion | Multi-modal sensor convergence enables anxiety-specific detection beyond generic autonomic load measurement. |
| Enterprise API Integration | Legacy HR system compatibility secures annual contract renewals with Fortune 500 benefits administrators. |
| Insurer B2B2C Partnership | Wellness incentive program integration opens premium discount verification revenue without hardware logistics. |
Research Methodology
Multiple input streams — executive interviews with wearable device manufacturers, regulatory affairs specialists at FDA-cleared firms, and corporate benefits administrators — were reconciled against secondary validation from FDA 510(k) filings, EU AI Act implementation guidance, and hospital procurement database extracts. Bottom-up triangulation across device shipment estimates and top-down reconciliation against enterprise wellness contract values anchored volume and value outputs.
Data-stream reconciliation employed segmentation modeling across product type, end user archetype, sensing technology modality, and distribution channel, with growth trajectories derived from cohort-based adoption curves and replacement cycle analysis. Forecast inputs incorporated graphene electrode cost decline trajectories, HIPAA compliance infrastructure scaling patterns, and photoplethysmography sampling architecture consolidation around 512 Hz acquisition standards.
Several conditions sit outside the modeled scope, including geopolitical disruption to Asian semiconductor foundry operations, abrupt shifts in FDA digital health enforcement posture, and unforeseen algorithmic bias litigation affecting workplace biometric deployment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market