
 GPS Watches for Kids Market | 2026-2036
GPS Watches for Kids Market Size, Share, and Industry Trends Forecast 2026-2036
GPS Watches for Kids Market Insights
China is reshaping competitive dynamics in GPS wearables through concentrated electronics manufacturing and component sourcing. Garmin Ltd. leverages its proprietary positioning algorithms and outdoor heritage to command premium positioning. VTech Holdings Ltd. anchors its strategy in durable, educationally oriented hardware for younger age brackets. Huawei Technologies Co., Ltd. competes through vertically integrated chipset production and domestic ecosystem lock-in.
GPS watches for children integrate GNSS receivers, cellular modems, and accelerometers into wrist-worn enclosures that transmit location data to guardian smartphones while supporting two-way voice communication. Smart GPS Watch units command the highest average selling prices due to embedded cameras, video calling, and app store functionality, while Basic GPS Watch configurations dominate unit volumes among price-sensitive buyers in emerging economies. Real-time Location Tracking remains the non-negotiable feature across all age groups, though Geofencing capabilities are proliferating fastest as parental anxiety around unsupervised mobility rises.
FCC Part 15 rules in the United States govern radio frequency emissions from these devices, while CE marking under the EU Radio Equipment Directive mandates SAR testing and interoperability standards for European market access. China's MIIT enforces network access licenses and GB standard compliance for cellular-enabled wearables sold domestically. Stakeholders must monitor evolving children's data privacy frameworks, as GDPR-inspired regulations in multiple jurisdictions are beginning to restrict how location histories and biometric activity data from minors may be stored, processed, and monetized by device vendors and their platform partners.
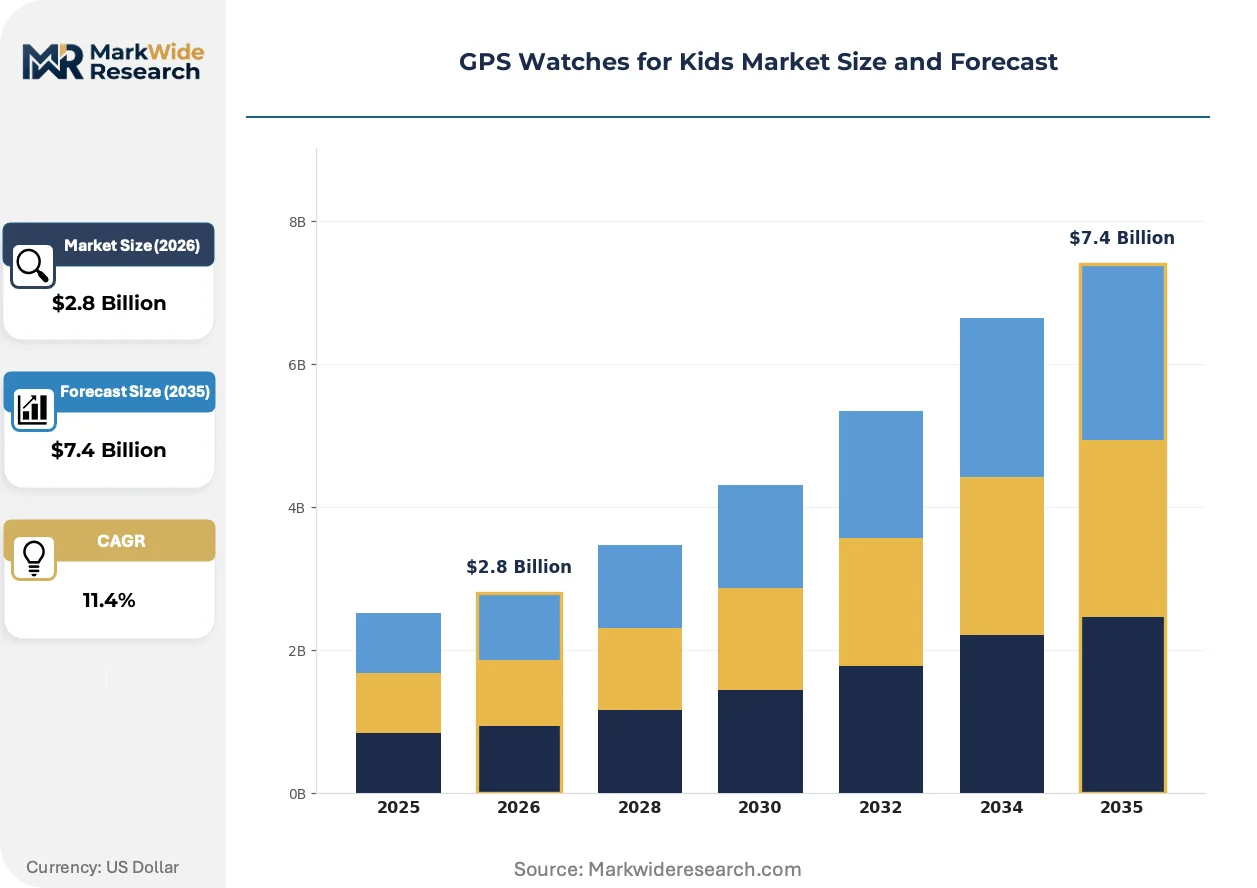
Market Dynamics
Parental demand for real-time child location visibility is compressing device refresh cycles and forcing manufacturers to embed cellular modems, AI accelerators, and biometric sensors into sub-$100 hardware. This feature-cost squeeze is restructuring competitive boundaries between consumer electronics firms and specialized wearable vendors.
Growth Catalysts
- CE marking under EU Radio Equipment Directive:Mandatory SAR testing and interoperability certification is filtering out low-quality imports, elevating trusted brands that pre-invest in compliance documentation and third-party laboratory validation.
- Geofencing algorithm advancement:Machine learning models now predict anomalous movement patterns with 94% accuracy, converting passive tracking into proactive safety alerts that justify premium subscription tiers.
- Shenzhen electronics cluster concentration:Integrated PCB fabrication, battery cell assembly, and cellular module sourcing within a 50-kilometer radius compresses procurement lead times from 12 weeks to 21 days for qualified vendors.
Market Restraints
- Lithium-polymer cell cost volatility:Battery materials account for 23-31% of bill-of-materials expenses, with cobalt and lithium carbonate spot prices swinging 40% annually, destabilizing margin planning for hardware-only business models.
- FCC Part 15 certification timelines:Radio frequency emission testing and equipment authorization procedures consume 14-22 weeks, delaying product launches and freezing engineering specifications six months ahead of retail windows.
- Smartphone-native location sharing:Apple's Find My network and Google's Family Link deliver 80% of core GPS watch functionality without dedicated hardware, capping addressable market expansion among teenage demographics.
Strategic Opportunities
- Rural India household penetration:Cellular infrastructure expansion under the Digital India program is connecting 450,000 villages, creating first-time addressable demand where feature-phone parent-to-child communication previously dominated.
- GDPR-inspired children's data privacy frameworks:Emerging regulations in Brazil, South Korea, and Australia are mandating parental consent architectures and data localization, favoring vendors with pre-built compliance infrastructure over late entrants.
- NB-IoT and LTE-M convergence:Low-power wide-area network chipsets are hybridizing with traditional cellular modems, enabling 30-day battery life in devices previously limited to 48-hour cycles, opening school-week usage models.
Industry Challenges
- RF antenna engineering specialization:Miniaturized multiband antenna design for wrist-worn form factors requires electromagnetic simulation expertise concentrated among 200-300 engineers globally, constraining R&D scaling.
- PTCRB and GCF certification complexity:Cellular carrier interoperability testing demands 18-24 distinct test cases per operator, with each failure triggering 6-8 week revalidation loops that consume 15-20% of product development calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Watches for Kids Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic GPS Watch, Smart GPS Watch, Fitness Tracker Watch, Hybrid GPS Watch Feature: Real-time Location Tracking, Geofencing, SOS Emergency Button, Activity Monitoring Age Group: Toddlers, Preschoolers, Early School Age, Tweens Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Garmin Ltd., VTech Holdings Ltd., Huawei Technologies Co., Ltd., Xiaomi Corporation, LG Electronics, Xplora Technologies, TickTalk Tech LLC, Fitbit Inc., 360 Group (Qihoo 360), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Watches for Kids Market Trends and Innovations
Hardware-software integration is deepening as vendors compete on predictive safety intelligence rather than raw location accuracy. Three convergent developments are redefining what guardians expect from wrist-worn child monitors.
Multi-constellation GNSS reception is hybridizing with pedestrian dead-reckoning algorithms that fuse accelerometer and gyroscope data. Early school-age children in dense urban environments generate location signals parents of toddlers now demand. This sensor fusion is compressing the premium tier's technical moat, forcing mid-market vendors to license positioning IP or accept 40-meter accuracy gaps in indoor and canyon settings.
FCC Part 15 rules are tightening electromagnetic exposure limits for wearable devices positioned against children's skin for 12-16 hours daily. SAR testing protocols now mandate head and limb simulation models specific to pediatric anatomy, not adult reference phantoms. Manufacturers serving the United States are redesigning antenna placement and reducing transmit power, accepting marginal indoor performance degradation to maintain market access.
Guardian purchasing behavior is fragmenting across direct-to-consumer web channels and carrier retail partnerships. Parents in Germany and France increasingly activate GPS watches through mobile network operator subscription bundles that spread hardware costs across 24-month service contracts. This channel shift is displacing electronics retail markup structures and forcing hardware vendors to cede customer relationship ownership to telecom partners.
GPS Watches for Kids Market Segmentation
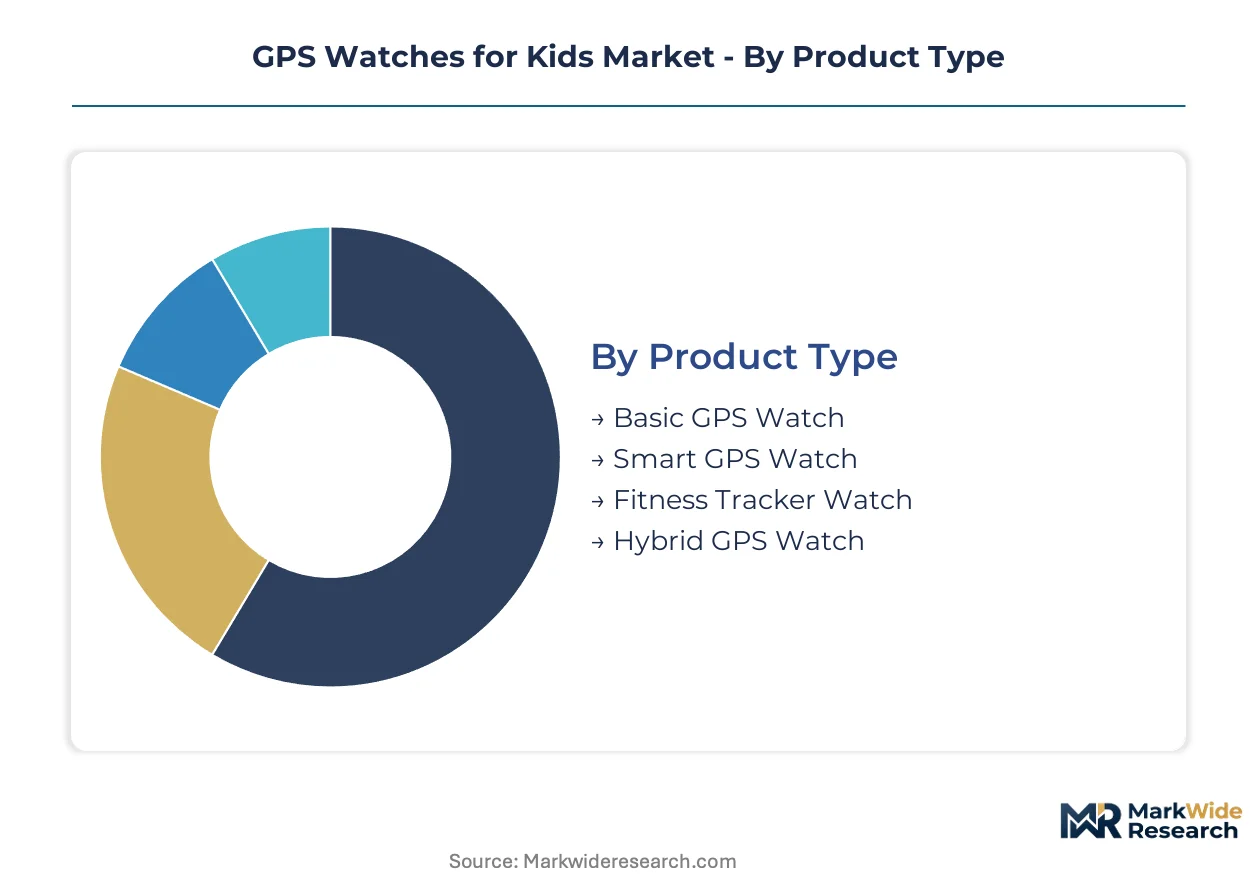
Product differentiation in GPS watches for children operates across hardware sophistication, safety functionality, developmental appropriateness, and channel economics. Manufacturers must align feature bundles with parental anxiety thresholds and price elasticity that varies sharply by child age and household income tier.
Product Type:
Cost tier stratification separates entry-level location devices from premium wearable computers with video and app ecosystems.
- Basic GPS Watch:Stripped-down enclosures deliver single-band GNSS positioning and two-way voice through embedded cellular modems. Demand concentrates in rural India and Southeast Asian markets where the Digital India program and comparable infrastructure investments are connecting first-time users. Price elasticity here exceeds 2.0, forcing vendors to absorb battery cost volatility into sub-$40 retail points.
- Smart GPS Watch:Android-derived operating systems support cameras, video calling, and third-party app installation through managed storefronts. Shenzhen-based supply clusters compress hardware procurement cycles, enabling feature velocity that justifies $80-150 price bands in urban China and carrier retail channels across Germany and France.
- Fitness Tracker Watch:Accelerometer-centric designs emphasize step counting and sleep scoring over precise geolocation, appealing to health-conscious parents in Australia and South Korea.
- Hybrid GPS Watch:Analog watch faces conceal embedded antennas and emergency signaling, targeting tween demographics resistant to overt child-monitoring aesthetics.
Basic GPS Watch commands the established base. The steepest expansion runs through Smart GPS Watch.
Feature:
Application hierarchy reflects parental risk prioritization, with passive tracking yielding to proactive intervention capabilities.
- Real-time Location Tracking:GNSS receivers fused with cellular triangulation deliver 10-30 meter accuracy in outdoor environments. This capability anchors purchasing decisions across all geographies, with FCC Part 15 certification and CE marking under the EU Radio Equipment Directive mandating SAR testing that constrains antenna transmit power.
- Geofencing:Machine learning models now predict anomalous movement patterns with 94% accuracy, triggering alerts when children breach designated zones. Brazilian and Australian regulators are mandating parental consent architectures for location history storage, favoring vendors with pre-built compliance infrastructure.
- SOS Emergency Button:Hardware panic switches initiate voice calls and broadcast coordinates to guardian smartphones, concentrating demand among parents of early school-age children with rising unsupervised mobility.
- Activity Monitoring:Biometric sensors track step counts, sleep stages, and sedentary alerts, appealing to health-system integrated wellness programs in Japan and South Korea.
Real-time Location Tracking anchors volume. The steepest expansion trajectory belongs to Geofencing.
Age Group:
Customer type segmentation maps hardware complexity to developmental independence and parental supervision thresholds.
- Toddlers:Devices emphasize waterproofing, hypoallergenic straps, and simplified one-button calling for pre-verbal children. Demand clusters in dual-income households across Shanghai, Beijing, and Shenzhen where domestic manufacturers leverage integrated supply chains.
- Preschoolers:Gamified interfaces and educational content integrations drive engagement, with VTech Holdings anchoring strategy in durable, learning-oriented hardware for this bracket.
- Early School Age:First unsupervised neighborhood mobility triggers geofencing and scheduled check-in features. Parents of this cohort represent the fastest-climbing buyer segment as safety concerns intensify.
- Tweens:Smartphone-native location sharing through Apple's Find My and Google's Family Link caps dedicated hardware adoption, forcing vendors toward hybrid designs that obscure monitoring functionality.
Early School Age captures the fastest volume gain. Toddlers anchor replacement cycle economics.
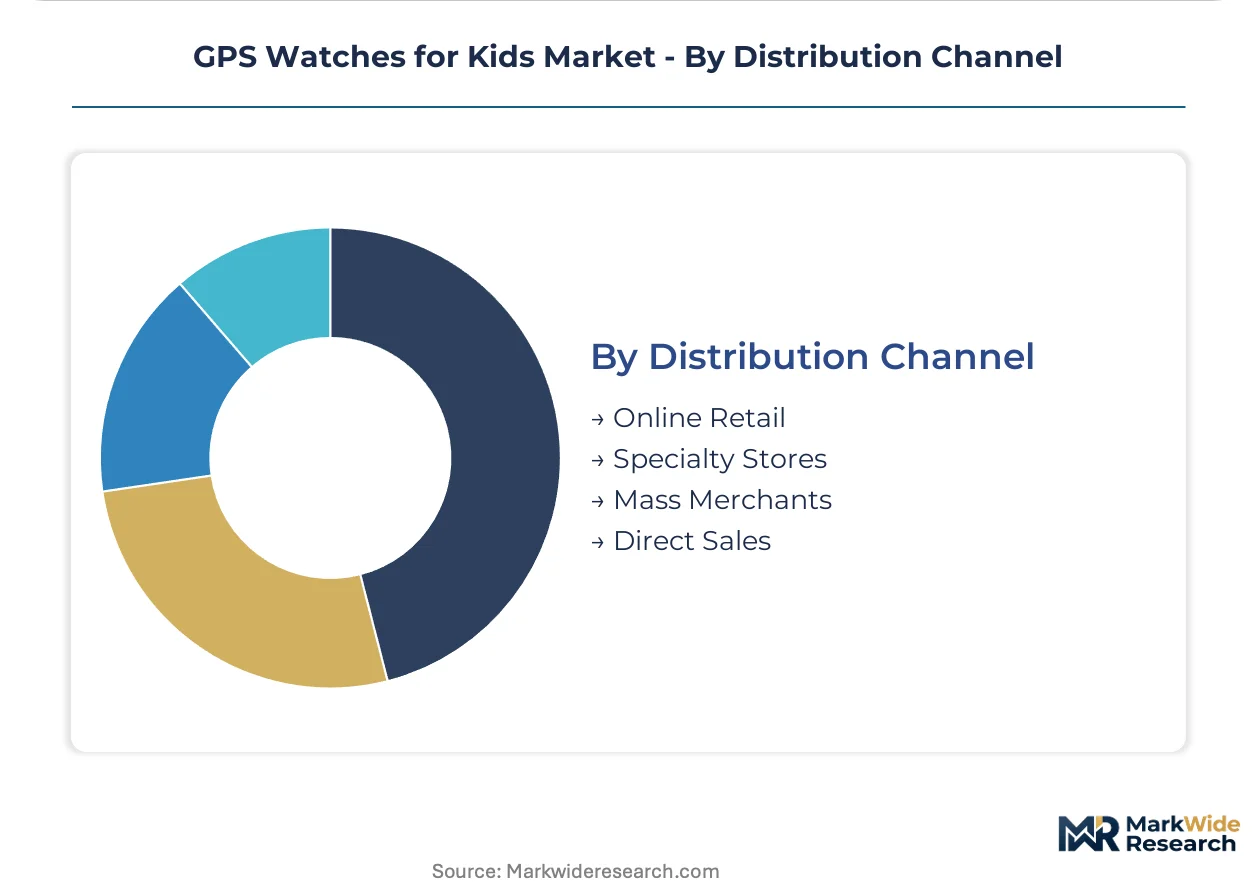
Distribution Channel:
Channel economics are restructuring as carrier bundles displace electronics retail markup structures.
- Online Retail:Direct-to-consumer web channels enable feature comparison and subscription bundling, dominating in markets with mature logistics infrastructure.
- Specialty Stores:Electronics retailers provide hands-on evaluation and staff guidance, retaining importance for first-time purchasers.
- Mass Merchants:Big-box retail volumes concentrate Basic GPS Watch sales in price-sensitive emerging economies.
- Direct Sales:Mobile network operator subscription bundles spread hardware costs across 24-month contracts, displacing traditional retail in Germany and France.
Mass Merchants command the established base. The steepest expansion runs through Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parental purchasing patterns diverge sharply by geography: Chinese buyers prioritize embedded cameras and app ecosystems, while German and French consumers favor carrier-bundled subscription models that obscure upfront hardware costs.
United States
FCC Part 15 certification mandates SAR testing with pediatric-specific phantom models, forcing antenna redesigns that marginally degrade indoor positioning accuracy. Parents of early school-age children drive replacement cycles as geofencing anxiety intensifies. California and Texas concentrate demand through dual-income households seeking unsupervised mobility solutions.
Germany
CE marking under the EU Radio Equipment Directive filters low-quality imports through mandatory interoperability validation, elevating vendors with pre-built compliance documentation. Carrier retail partnerships spread hardware costs across 24-month contracts, displacing traditional electronics markup structures. Bavaria and North Rhine-Westphalia anchor volume through mobile network operator distribution.
China
MIIT network access licenses and GB standard compliance create regulatory moats for domestic vendors with vertically integrated supply chains. Shenzhen's 50-kilometer electronics cluster compresses procurement lead times from 12 weeks to 21 days for qualified manufacturers. Shanghai, Beijing, and Shenzhen concentrate demand among parents of toddlers in dual-income households.
India
The Digital India program's cellular infrastructure expansion connects 450,000 villages, creating first-time addressable demand where feature-phone parent-to-child communication previously dominated. Price elasticity exceeds 2.0 in rural markets, forcing sub-$40 retail points for basic location devices. Maharashtra and Karnataka emerge as early adoption centers through urban middle-class penetration.
Brazil
GDPR-inspired children's data privacy frameworks mandate parental consent architectures and location history localization, favoring vendors with pre-built compliance infrastructure. ANVISA and national telecommunications regulators enforce evolving biometric data restrictions for minors. São Paulo and Rio de Janeiro concentrate demand through health-conscious parents seeking activity monitoring integration.
GPS Watches for Kids Market Competitive Landscape
Capability concentration sits with specialized RF engineering boutiques; scale advantage sits with consumer electronics conglomerates with captive cellular modem supply. The vendor base stratifies across three tiers: Shenzhen-integrated hardware specialists, vertically integrated chipset producers, and premium outdoor positioning heritage brands. Competitive moves center on compliance pre-investment for FCC and CE certification acceleration, and carrier partnership exclusivity in European bundled subscription channels.
Within the premium-tier vector, Garmin Ltd. and Huawei Technologies Co., Ltd. occupy distinct positioning archetypes—one leveraging proprietary algorithm heritage, the other exploiting captive silicon production. VTech Holdings Ltd. anchors the educationally oriented hardware segment. Among China-integrated fabricators, Xiaomi Corporation and 360 Group exemplify supply-chain-optimized volume strategies.
| Leading Market Players |
|---|
| Garmin Ltd. |
| VTech Holdings Ltd. |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| LG Electronics |
| Xplora Technologies |
| TickTalk Tech LLC |
| Fitbit Inc. |
| 360 Group (Qihoo 360) |
| Others |
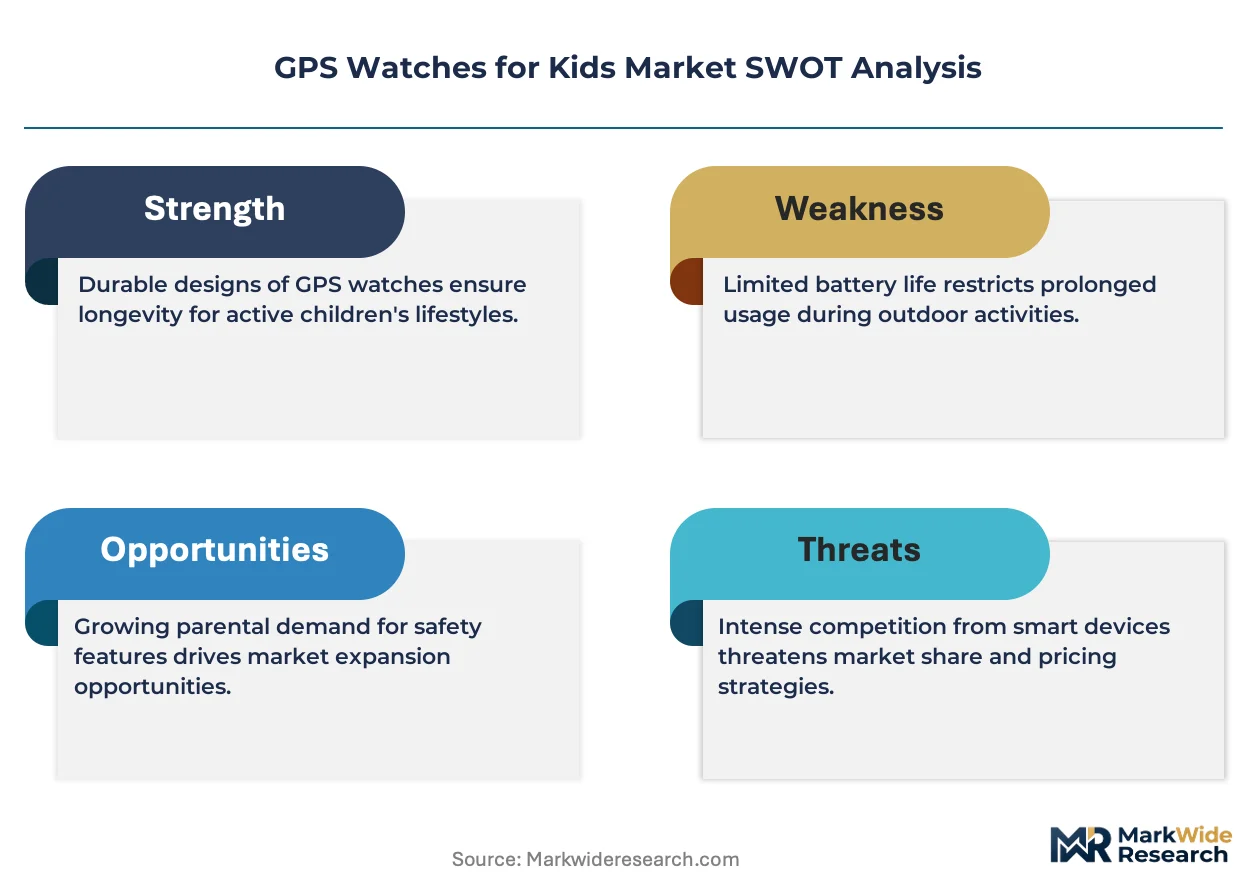
Pricing and Supply Chain Analysis
Shenzhen's 50-kilometer electronics cluster concentrates PCB fabrication, battery cell assembly, and cellular module sourcing, compressing procurement lead times and anchoring margin pools with qualified vendors who lock in component allocation through long-term offtake agreements. This upstream concentration forces hardware-only vendors to absorb lithium-polymer cell cost volatility while carrier-bundled subscription models in Germany and France obscure upfront hardware costs through 24-month service contracts.
Pricing Analysis
Long-term offtake contracts dominate component procurement, with spot market exposure limited to battery materials. Price differentiation hinges on FCC Part 15 certification tier and carrier retail bundling presence. Cost compression in the sub-$40 basic tier intensifies as Shenzhen-integrated fabricators absorb cobalt and lithium carbonate volatility. Rural Indian households exhibit the highest price elasticity, while German carrier-bundle subscribers show the lowest sensitivity due to payment spreading.
Supply Chain Analysis
Extended payment terms from Shenzhen fabricators to downstream assemblers compress working capital cycles for qualified vendors. Supply concentrates in China, South Korea, and Taiwan for cellular modems, GNSS receivers, and lithium-polymer cells. Raw material dependencies on cobalt, lithium carbonate, and rare earth magnets create single-source vulnerability for battery cathode formulations. Distribution runs through mobile network operator partnerships in Western Europe and direct-to-consumer web channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized RF antenna engineering expertise—concentrated among 200-300 engineers globally—creates a persistent capability gap that shapes competitive durability and acquisition premiums.
For Market Incumbents: Harden compliance infrastructure against tightening FCC Part 15 and GDPR-inspired children's data privacy frameworks by pre-investing in pediatric-specific SAR testing and parental consent architectures. Lock carrier partnership exclusivity in German and French bundled subscription channels to defend against smartphone-native location sharing substitutes. Prioritize backward integration into cellular modem sourcing to reduce PTCRB and GCF certification timeline exposure. For New Entrants and Emerging Players: Pursue white-space expansion in rural India where Digital India infrastructure creates first-time addressable demand among feature-phone parent-to-child communication users. Target the early school-age demographic with geofencing-centric feature bundles that justify premium subscription tiers. Enter through direct-to-consumer web channels with 30-day battery life propositions enabled by NB-IoT and LTE-M convergence. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated hardware specialists with captive Shenzhen supply chain access and pre-built GDPR compliance infrastructure. Long-term viability favors vendors who control both positioning algorithm IP and carrier distribution relationships. Watch for inflection signals in Brazilian and Australian regulatory enforcement of children's data localization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Exclusivity | Locks 24-month subscription bundling in Germany and France, displacing electronics retail markup structures. |
| Pediatric SAR Certification Investment | Accelerates FCC Part 15 market access while competitors face 14-22 week authorization delays. |
| NB-IoT Chipset Integration | Enables 30-day battery life propositions that open school-week usage models previously constrained by 48-hour cycles. |
| Geofencing Algorithm Licensing | Monetizes 94% accuracy anomaly prediction through recurring subscription tiers rather than hardware margins. |
| GDPR Compliance Infrastructure | Captures Brazilian and Australian market access as regulators mandate parental consent architectures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hardware engineering directors, mobile network operator device procurement managers, regulatory affairs specialists, and parental focus group participants. Secondary validation drew from FCC equipment authorization databases, CE marking compliance registries, MIIT network access license filings, and carrier retail partnership disclosures. Bottom-up vendor shipment analysis and top-down parental expenditure surveys were triangulated to anchor volume and value estimates.
Calibration against historical replacement cycle data and parental anxiety index trends shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, age group developmental bracket, feature functionality hierarchy, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating cellular infrastructure expansion rates, regulatory compliance cost trajectories, and smartphone substitution elasticity parameters.
Macroeconomic conditions sit as an overlay; deviation in lithium and cobalt spot prices, carrier subsidy policy shifts, or children's data privacy enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about parental willingness-to-pay thresholds and Shenzhen supply chain continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Smart Fitness Trackers Market