
 Smart Fitness Market | 2026-2036
Smart Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fitness Market Outlook
China's manufacturing corridor for MEMS sensors and lithium-polymer batteries is rewriting cost structures for wearable producers worldwide. Peloton sustains brand loyalty through proprietary content ecosystems that lock in subscription revenue. Garmin dominates aviation-grade GPS adaptation for multisport watches with altimeter and pulse oximeter integration. Apple controls silicon design through custom S-series chips that optimize power draw for all-day health monitoring.
Smart fitness encompasses sensor-embedded hardware and software platforms that capture physiological metrics—heart rate variability, blood oxygen saturation, VO2 max estimates, and sleep architecture—then transmit encrypted data via Bluetooth Low Energy or Wi-Fi to cloud analytics engines for personalized coaching feedback. Wearable Devices and Connected Equipment command the deepest margin pools due to hardware replacement cycles and premium pricing tiers, while Fitness Apps face commoditization pressure from free alternatives despite lower customer acquisition costs. Corporate Wellness Programs represent the fastest-growing end-user channel as self-insured employers seek quantifiable ROI on preventive health expenditures.
FDA clearance pathways for software-as-a-medical-device constrain heart rhythm algorithms marketed for diagnostic purposes, while GDPR and the EU AI Act mandate explicit consent frameworks for biometric data processing across European deployments. The Federal Trade Commission monitors subscription billing practices and cancellation friction in direct-to-consumer fitness apps under Section 5 unfairness standards. Stakeholders must track evolving regulatory divergence between health-adjacent wellness claims and regulated medical device classifications as enforcement priorities shift.
Market Dynamics
The Smart Fitness Market is being fundamentally restructured by the collision of biometric data commoditization with escalating regulatory scrutiny over algorithmic health claims. Hardware margins compress as sensor costs plummet while software platforms face escalating compliance burdens for cross-border data flows.
Growth Catalysts
- EU AI Act compliance mandates:Biometric data processing frameworks are forcing platform operators to invest in consent architecture, creating competitive moats for compliant incumbents against undercapitalized entrants.
- Corporate wellness procurement:Self-insured employers in the United States are consolidating vendor relationships around platforms that demonstrate quantifiable preventive health ROI through integrated claims data.
- MEMS sensor cost curves:China's manufacturing corridor for motion and optical sensors is enabling sub-$50 wearable hardware with clinical-grade accuracy, democratizing access across price-sensitive demographics.
Market Restraints
- Lithium-polymer supply concentration:Battery cell production clusters in East Asia create single-source vulnerability for wearable manufacturers facing geopolitical trade friction.
- FDA software-as-medical-device pathways:Heart rhythm algorithm submissions for diagnostic claims face monthsland timelines that freeze feature deployment for cardiovascular monitoring apps.
- Free fitness app substitution:Ad-supported alternatives with basic tracking capabilities erode subscription pricing power for premium coaching platforms.
Strategic Opportunities
- India's preventive health infrastructure:The country's national digital health mission creates data interoperability standards that lower platform onboarding costs for biometric-integrated wellness services.
- Generative AI coaching convergence:Large language models paired with real-time biometrics enable hyper-personalized workout programming that differentiates against static content libraries.
- Pharmacy retail channel expansion:CVS and Walgreens storefront networks in the United States are adding connected fitness hardware to chronic disease management sections, reaching Medicare-eligible demographics.
Industry Challenges
- Biometric data science talent scarcity:Signal processing engineers with cardiovascular physiology domain expertise command compensation premiums that strain R&D budgets outside Silicon Valley and Boston clusters.
- GDPR-EU AI Act dual compliance:European deployments require reconciling divergent consent mechanisms across health-adjacent wellness claims and regulated algorithmic outputs.
- Legacy EHR integration complexity:Hospital system procurement committees demand HL7 FHIR interoperability that smaller fitness platforms lack engineering resources to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fitness Market |
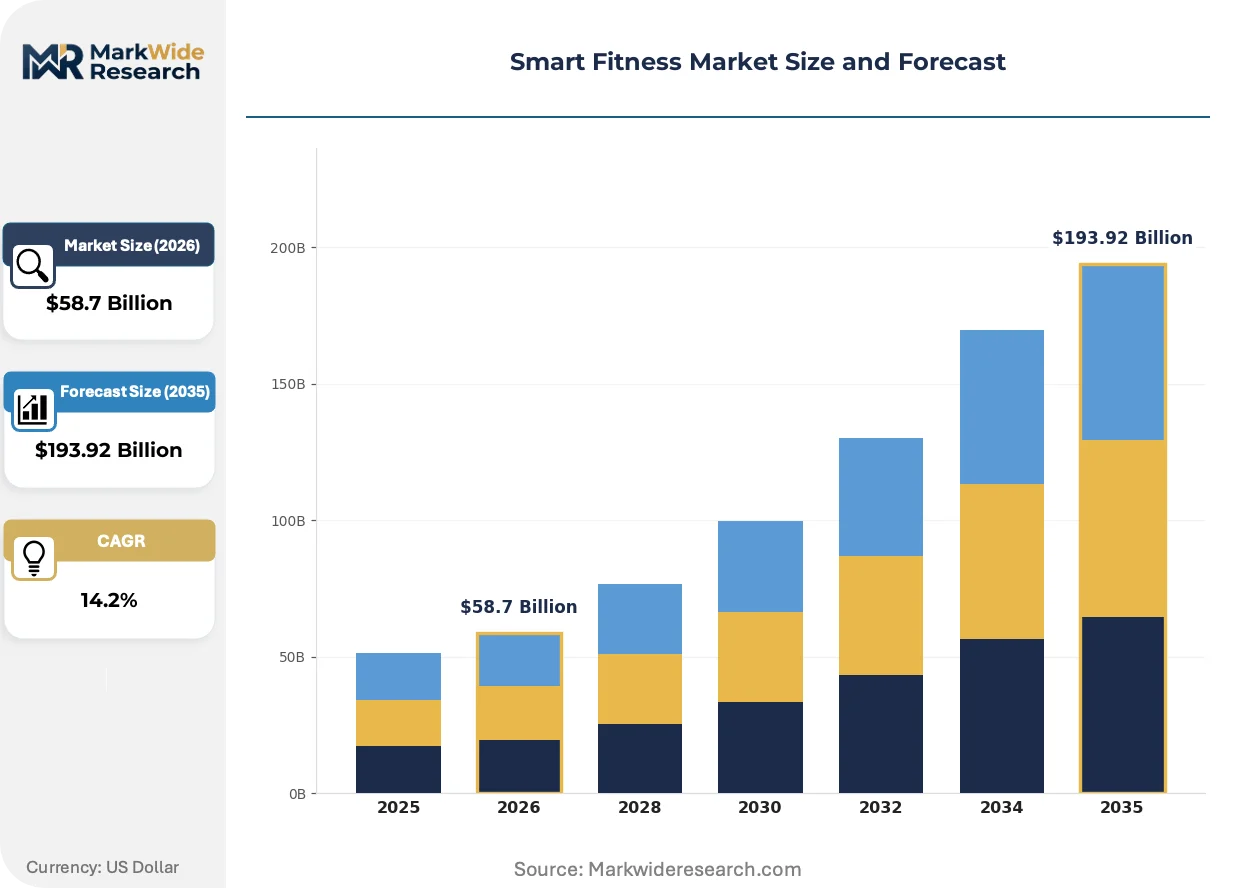
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $193.92 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Apparel, Fitness Apps, Connected Equipment End User: Gyms, Individual Consumers, Health Clubs, Corporate Wellness Programs Technology: Bluetooth, Wi-Fi, NFC, Cloud Computing Application: Personal Training, Group Classes, Health Monitoring, Performance Tracking |
| Companies Covered | WHOOP, Peloton, Garmin, Strava, Noom, Fitbit, Oura, iFIT, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fitness Market Strategic Shifts
Photoplethysmography signal processing is collapsing the boundary between consumer wellness and clinical monitoring, forcing regulatory recalibration across multiple jurisdictions simultaneously.
Multi-wavelength optical sensors embedded in wrist-worn devices now capture blood pressure trend estimates and atrial fibrillation signatures previously requiring cuff-based or patch monitors. Medicare Advantage plans in the United States are piloting reimbursement for remote patient monitoring feeds sourced from consumer wearables. This capability convergence is collapsing the distinction between fitness accessories and regulated medical devices, exposing manufacturers to FDA enforcement discretion.
The EU AI Act's risk classification framework for biometric identification systems is forcing platform operators to rearchitect cloud inference pipelines. High-risk algorithmic health assessments must now maintain human-in-the-loop review capabilities and algorithmic impact documentation. German and French deployments face additional CNIL and BfDI interpretations of GDPR Article 9 special category data that exceed baseline European requirements.
Employer-sponsored wellness procurement is consolidating around outcome-contingent contracts that tie vendor payments to measured biometric improvements. Self-insured corporations in the United States are replacing per-employee-per-month subscriptions with value-based arrangements indexed to claims cost reduction. This purchasing transformation is most visible among Fortune 500 manufacturers with unionized workforces where preventive health investments carry measurable workers compensation liability implications.
Smart Fitness Market Segmentation
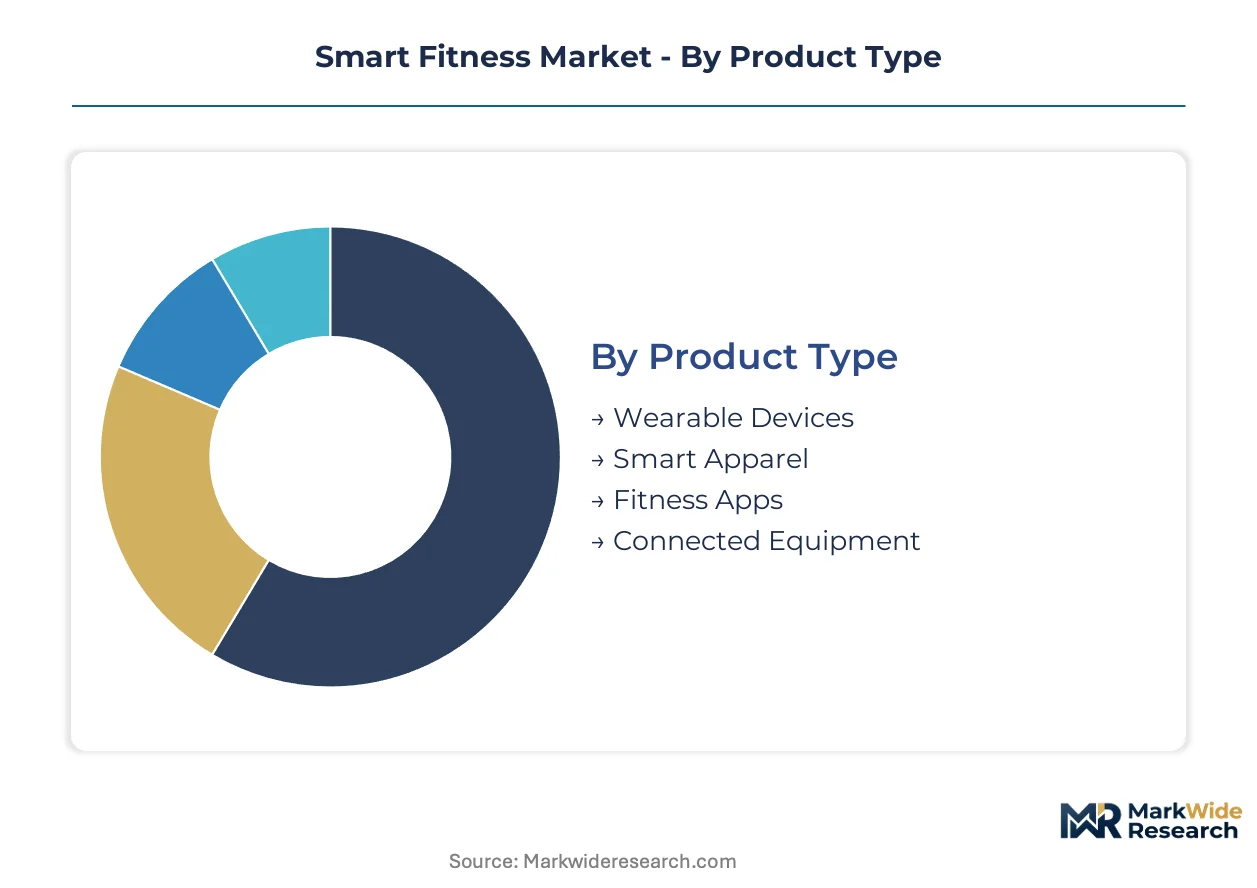
Segmentation in smart fitness reveals how hardware replacement cycles, software monetization friction, and B2B procurement consolidation create divergent margin profiles across product and customer dimensions. Understanding these fault lines exposes where capital efficiency concentrates and where compliance burdens erode returns.
Product Type:
Mature hardware categories with established supply chains dominate revenue concentration, while emerging software layers face commoditization pressure from free alternatives.
- Wearable Devices:Sensor-embedded wristbands and watches integrating photoplethysmography, accelerometry, and GPS modules for continuous biometric capture. Demand concentrates among self-insured employers in the United States seeking quantifiable preventive health ROI through integrated claims data, though lithium-polymer supply concentration in East Asia creates single-source vulnerability.
- Connected Equipment:Internet-enabled treadmills, stationary bikes, and strength training rigs with embedded screens streaming proprietary content ecosystems. Peloton sustains brand loyalty through subscription lock-in, while hardware margins compress as China's MEMS sensor manufacturing corridor enables sub-$50 competitive entrants.
- Smart Apparel:Textile-integrated conductive fibers and stretch sensors measuring muscle activation and posture biomechanics.
- Fitness Apps:Software platforms delivering workout programming, nutrition tracking, and social features via smartphone interfaces.
Wearable Devices retains volume leadership; Corporate Wellness Programs as end users drive Connected Equipment's steepest expansion curve.
End User:
Customer type determines pricing power, with institutional procurement consolidating around outcome-contingent contracts while individual subscriptions face cancellation friction scrutiny.
- Corporate Wellness Programs:Employer-sponsored platforms where self-insured corporations tie vendor payments to measured biometric improvements and claims cost reduction. Fortune 500 manufacturers with unionized workforces index investments to workers compensation liability implications, creating the fastest-growing channel in the United States.
- Individual Consumers:Direct-to-customer subscribers purchasing hardware and software through retail and e-commerce channels. The Federal Trade Commission monitors billing practices and cancellation friction under Section 5 unfairness standards, constraining pricing experimentation.
- Gyms:Multi-location fitness operators deploying connected equipment fleets for member retention and competitive differentiation.
- Health Clubs:Premium facilities integrating biometric monitoring into personalized coaching services for high-net-worth demographics.
Individual Consumers retains volume leadership; Corporate Wellness Programs holds the steepest expansion trajectory.
Technology:
Connectivity infrastructure spans mature short-range protocols and emerging cloud architectures, with compliance requirements diverging across biometric data processing jurisdictions.
- Cloud Computing:Centralized analytics engines processing encrypted physiological data for personalized coaching feedback and algorithmic health assessments. The EU AI Act mandates human-in-the-loop review capabilities and algorithmic impact documentation for high-risk biometric identification systems, forcing rearchitecture of inference pipelines.
- Bluetooth:Low-energy wireless protocol dominating wearable-to-smartphone data transmission with minimal power draw optimized through Apple's custom S-series silicon design.
- Wi-Fi:Higher-bandwidth connectivity enabling real-time video streaming and firmware updates for connected equipment.
- NFC:Near-field communication facilitating tap-to-pair device onboarding and gym access control integrations.
Bluetooth retains volume leadership; Cloud Computing gains share fastest as generative AI coaching convergence demands scalable inference infrastructure.
Application:
Use case differentiation tracks the boundary between wellness-adjacent claims and regulated medical device classifications, with FDA enforcement discretion escalating compliance investment.
- Health Monitoring:Continuous tracking of heart rate variability, blood oxygen saturation, and atrial fibrillation signatures previously requiring clinical-grade equipment. Medicare Advantage plans in the United States pilot reimbursement for remote patient monitoring feeds sourced from consumer wearables, collapsing distinctions between fitness accessories and regulated devices.
- Personal Training:Algorithmic workout programming adapted to real-time biometric feedback and recovery metrics.
- Group Classes:Synchronized multiplayer experiences with leaderboards and instructor-led content delivery.
- Performance Tracking:VO2 max estimates, lactate threshold modeling, and sleep architecture analysis for athletic optimization.
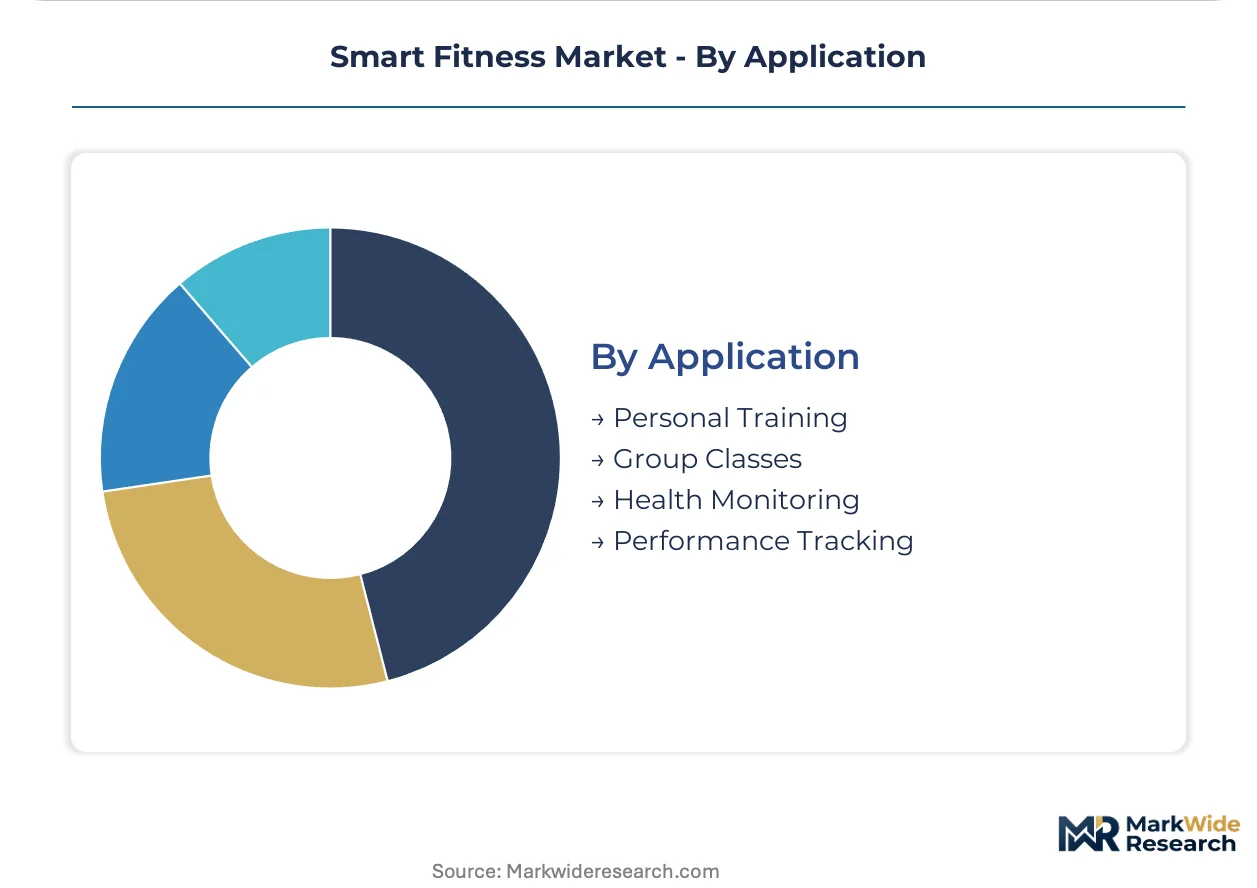
Personal Training retains volume leadership; Health Monitoring climbs the fastest as photoplethysmography signal processing forces regulatory recalibration across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for software-as-medical-device constrain cardiovascular algorithm deployment in the United States, while GDPR and the EU AI Act reshape biometric data processing across European deployments. Demand concentrates where employer-sponsored wellness budgets and direct-to-consumer subscription models drive hardware and software uptake.
United States
Self-insured employers consolidate vendor relationships around platforms demonstrating quantifiable preventive health ROI through integrated claims data. The Federal Trade Commission monitors subscription billing practices and cancellation friction under Section 5 unfairness standards. Fortune 500 manufacturers with unionized workforces in the Midwest index wellness investments to workers compensation liability implications.
Germany
Corporate procurement teams demand outcome-contingent contracts tying vendor payments to measured biometric improvements. The BfDI interprets GDPR Article 9 special category data requirements beyond baseline European standards for biometric processing. Munich and Berlin host engineering clusters developing HL7 FHIR interoperability solutions for hospital system integration.
China
MEMS sensor and lithium-polymer battery manufacturing corridors in Shenzhen and Dongguan rewrite cost structures for wearable producers worldwide. MIIT standards govern wireless transmission protocols for health monitoring devices. The Yangtze River Delta concentration enables sub-$50 wearable hardware with clinical-grade accuracy for price-sensitive demographics.
India
The national digital health mission creates data interoperability standards lowering platform onboarding costs for biometric-integrated wellness services. CDSCO regulatory frameworks distinguish between wellness-adjacent claims and regulated medical device classifications. Bengaluru and Hyderabad clusters supply signal processing engineers with cardiovascular physiology domain expertise.
United Kingdom
Medicare Advantage reimbursement pilots for remote patient monitoring feeds sourced from consumer wearables drive hardware adoption among Medicare-eligible demographics. The Medicines and Healthcare products Regulatory Agency calibrates enforcement discretion between fitness accessories and regulated devices. London fintech corridors integrate biometric data into insurance underwriting models.
Smart Fitness Market Competitive Environment
Capability concentration sits with integrated hardware-software platforms; scale advantage sits with consumer electronics conglomerates with captive silicon design. The market structures around three tiers: premium ecosystem operators with proprietary content lock-in, component specialists with aviation-grade sensor adaptation, and vertically integrated technology giants with custom chip architectures. Strategic moves center on M&A for biometric data science talent and geographic expansion into pharmacy retail channels for chronic disease management placement.
Within the premium ecosystem tier, Peloton and iFIT exemplify content-locked subscription models that sustain brand loyalty through proprietary programming libraries. Garmin occupies a position among precision sensor specialists, representing aviation-grade GPS adaptation for multisport applications. Apple anchors the integrated technology tier, exemplifying custom silicon design that optimizes power draw for continuous health monitoring.
| Leading Market Players |
|---|
| WHOOP |
| Peloton |
| Garmin |
| Strava |
| Noom |
| Fitbit |
| Oura |
| iFIT |
| Apple |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shenzhen lithium-polymer cell manufacturing is compressing supplier margins and enabling aggressive hardware pricing from wearable brands while simultaneously constraining R&D investment cycles across the ecosystem.
Pricing Analysis
Geographic price spreads between US corporate wellness procurement and Indian direct-to-consumer channels exceed three-to-one for comparable sensor hardware. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) certification and EU AI Act compliance emerging as the dominant price differentiation drivers. Cost compression in the economy tier is intensifying because MEMS sensor commoditization from China's manufacturing corridor erodes hardware margins. Self-insured employers in the United States demonstrate the lowest price sensitivity, while price-sensitive demographics in emerging markets drive volume through sub-$50 wearable adoption.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Luxshare, and Goertek for final assembly of wrist-worn devices, while BYD and CATL dominate lithium-polymer cell supply. Component sourcing draws from China's MEMS sensor corridor, South Korea's OLED display foundries, and Taiwan's semiconductor packaging facilities. Single-source vulnerability in East Asian battery cell production creates exposure to geopolitical trade friction. Distribution runs through pharmacy retail networks for chronic disease management placement and direct-to-consumer e-commerce channels for hardware subscription bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI coaching convergence paired with EU AI Act biometric compliance mandates is creating a high-growth disruption window where algorithmic differentiation and regulatory architecture determine competitive survival.
For Market Incumbents: Harden cloud inference pipelines against EU AI Act high-risk classification requirements by embedding human-in-the-loop review capabilities and algorithmic impact documentation. Deepen backward integration into custom silicon design to optimize power draw for continuous health monitoring and defend against Apple's S-series chip advantage. Consolidate biometric data science talent in Boston and Bengaluru engineering clusters before compensation premiums escalate further. For New Entrants and Emerging Players: Establish a beachhead in India's national digital health mission infrastructure where data interoperability standards lower platform onboarding costs for biometric-integrated wellness services. Target pharmacy retail channel expansion through CVS and Walgreens storefront networks for Medicare-eligible demographic reach. Pursue white-label partnerships with self-insured employers seeking outcome-contingent contracts rather than competing head-to-head against Peloton's content-locked subscription ecosystem. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud computing infrastructure deployments as generative AI coaching demands scalable inference capabilities. Long-term viability favors platforms with integrated hardware-software stacks and proprietary biometric algorithms rather than pure-play fitness apps facing free substitution. Monitor FDA software-as-medical-device clearance timelines for heart rhythm diagnostic features as the critical inflection signal separating wellness-adjacent claims from regulated medical device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture | Human-in-the-loop review capabilities create competitive moats against undercapitalized entrants in European deployments. |
| Generative AI Coaching Integration | Large language models paired with real-time biometrics enable hyper-personalized workout programming against static content libraries. |
| Pharmacy Retail Channel Expansion | CVS and Walgreens storefront networks reach Medicare-eligible demographics for chronic disease management hardware placement. |
| Custom Silicon Design Investment | In-house S-series chip architectures optimize power draw for all-day health monitoring and extend hardware replacement cycles. |
| Outcome-Contingent Contract Structuring | Self-insured employers tie vendor payments to measured biometric improvements and quantifiable claims cost reduction. |
Study Parameters
Initial hypotheses were tested against primary input from connected fitness platform executives, biomedical engineers with cardiovascular signal processing expertise, corporate wellness procurement directors at Fortune 500 manufacturers, and pharmacy retail category managers, then refined through secondary validation against FDA 510(k) filings, EU AI Act regulatory texts, SEC 10-K hardware revenue disclosures, and Medicare Advantage remote patient monitoring pilot documentation. Bottom-up sensor shipment modeling and top-down corporate wellness expenditure estimates were triangulated to cross-validate market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, end user, technology, and application dimensions plus a biometric data processing risk classification layer. CAGRs were derived from installed base growth rates and replacement cycle compression. Forecast inputs incorporated MEMS sensor cost curve trajectories and lithium-polymer supply concentration risk assessments.
Sensitivities concentrate around FDA enforcement discretion for heart rhythm diagnostic algorithms and GDPR-EU AI Act dual compliance implementation timelines. Forecasts reflect assumptions regarding employer wellness budget continuity and photoplethysmography signal processing accuracy improvements. Quarterly review of FDA software-as-medical-device submission backlogs and EU member state AI Act enforcement priorities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Gym Equipment
UK Gym Accessories Market
Smart Gym Equipment
Smart Gym Equipment Market
Smart Gym Equipment
Smart Treadmill Market
Smart Gym Equipment
Indoor Smart Bikes Market
Smart Gym Equipment
South Korea Gym Accessories Market
Smart Gym Equipment
Gym Accessories Market
Smart Gym Equipment
Smart Sports Equipment Market
Smart Gym Equipment
Gym Mats Market
Smart Gym Equipment
Aqua Gym Equipment Market
Smart Gym Equipment
Singapore Gym Accessories Market
Smart Gym Equipment
Connected Gym Equipment Market
Smart Gym Equipment
Argentina Gym Accessories Market
Smart Gym Equipment
Gymnastic Bench Market
Smart Gym Equipment
Australia Gym Accessories Market
Smart Gym Equipment
Home Gym Equipment Market
Smart Gym Equipment
Smart Fitness Wear Market