
 Smart Wearable Equipment Market | 2026-2036
Smart Wearable Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wearable Equipment Market Insights
Silicon anode chemistry is consolidating as the dominant battery architecture for premium smartwatches, replacing traditional graphite cells to extend device runtime between charges. Apple Inc. leverages vertical integration across chip design and health sensor fabrication to sustain margin capture. Samsung Electronics Co., Ltd. anchors its position through in-house display manufacturing and diversified foundry partnerships. Garmin Ltd. specializes in GPS-dominant outdoor and aviation segments where ruggedization commands pricing power.
Smart wearable equipment denotes body-worn electronic devices integrating microprocessors, biometric sensors, wireless transceivers, and rechargeable power cells within ergonomic housings typically weighing under 100 grams, designed to capture physiological data and transmit telemetry to paired hosts. These systems serve continuous health surveillance, athletic performance quantification, and clinical remote diagnostics without restricting user mobility. Smart watches occupy the largest revenue pool as multipurpose endpoints, while wearable health monitors represent the fastest-expanding category as FDA-cleared devices penetrate chronic disease management workflows. Fitness tracking applications retain the broadest installed base though sleep analysis functions are differentiating premium tier offerings.
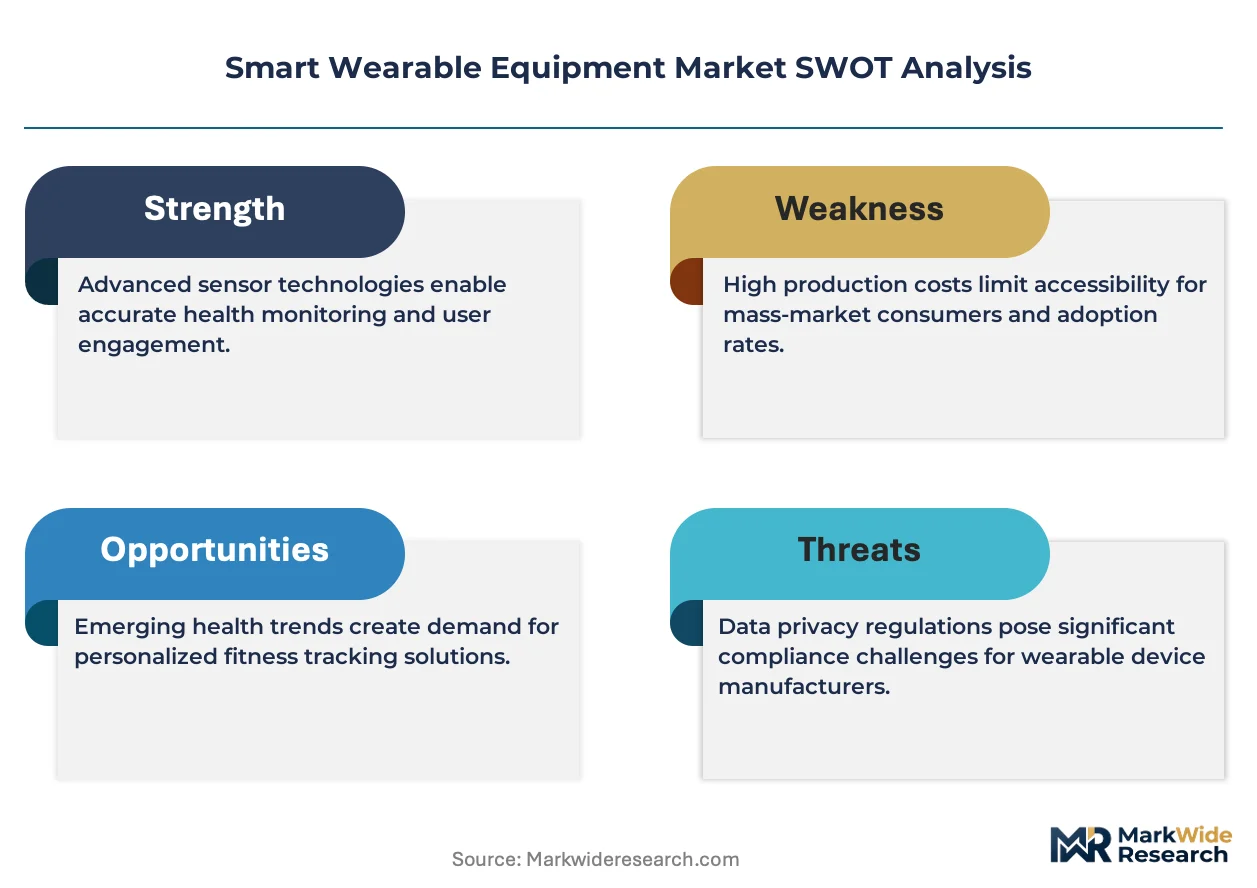
FDA software-as-a-medical-device oversight and HIPAA data handling requirements constrain market entry for unvalidated health claim devices in the United States, while the EU MDR and GDPR impose parallel conformity and privacy burdens across European distribution. CE marking under the Radio Equipment Directive governs electromagnetic compatibility and spectrum use for all wireless wearables sold in Europe. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payor decisions will determine which sensor categories achieve clinical-scale deployment.
Market Dynamics
Silicon anode battery chemistry is compressing recharge cycles and extending runtime, forcing incumbents to redesign power management subsystems or cede premium positioning to vertically integrated competitors controlling cell fabrication.
Growth Catalysts
- FDA software-as-a-medical-device guidance:The 2021 policy framework clarifies classification pathways for algorithm-driven diagnostics, accelerating commercialization timelines for continuous glucose monitoring and arrhythmia detection wearables.
- German reimbursement expansion:Statutory health insurers now cover remote patient monitoring for chronic heart failure, creating immediate volume pull for prescription-grade wearable ECG devices.
- Solid-state battery pilot lines:Samsung SDI and Toyota's manufacturing partnerships are scaling silicon-anode production, resolving the energy density bottleneck that constrained always-on health sensing.
Market Restraints
- Lithium supply concentration:Over 60% of global lithium chemical processing sits within China's Sichuan and Qinghai provinces, exposing battery cost structures to export licensing volatility.
- GDPR Article 9 health data restrictions:The EU's special category processing requirements impose legal engineering costs that deter mid-tier hardware vendors from European distribution.
- Skin-interfacing sensor longevity:Electrochemical glucose sensors require 14-day replacement cycles, creating recurring cost burdens that limit Medicare reimbursement appeal.
Strategic Opportunities
- India's PLI scheme for wearable electronics:Production-linked incentives covering 4-6% of incremental sales value are attracting EMS partners to Gujarat and Tamil Nadu manufacturing clusters.
- Continuous blood pressure monitoring:Optical plethysmography algorithms from Stanford and MIT spinouts are achieving cuffless accuracy, opening hypertension management to wrist-worn form factors.
- Telehealth platform bundling:Teladoc and Amwell are white-labeling FDA-cleared devices for employer contracts, shifting distribution through benefits administrators rather than retail.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for skin-contact materials extends 18-24 months, delaying product launches behind semiconductor refresh cycles.
- RF front-end integration complexity:Concurrent support for 5G NR, UWB precise positioning, and legacy Bluetooth Low Energy requires multi-protocol stack engineering scarce outside Qualcomm and MediaTek.
- Health claim substantiation costs:FDA 510(k) clearance for novel biomarkers demands clinical trials exceeding $10 million, concentrating innovation among capitalized platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wearable Equipment Market |
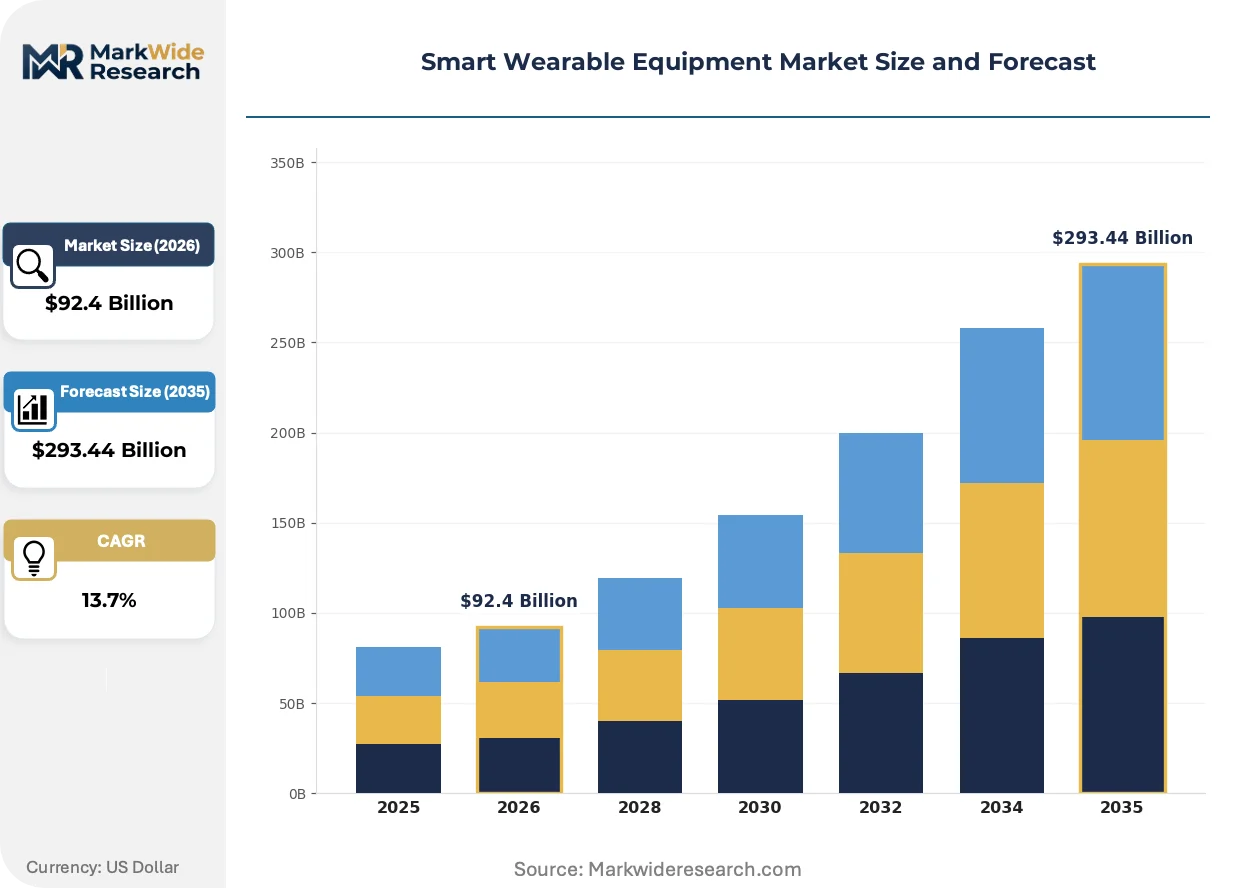
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $293.44 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Watches, Fitness Trackers, Smart Glasses, Wearable Health Monitors Technology: Bluetooth, NFC, Wi-Fi, GPS End User: Healthcare Providers, Fitness Enthusiasts, Athletes, Corporate Professionals Application: Health Monitoring, Fitness Tracking, Sleep Analysis, Remote Patient Monitoring |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Garmin Ltd., Xiaomi Corporation, Huawei Technologies Co., Ltd., Alphabet Inc., Fossil Group Inc., Sony Corporation, Imagine Marketing Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wearable Equipment Market Trends and Innovations
Computational biomarker extraction and ambient sensing architectures are displacing discrete health peripherals, consolidating multiple diagnostic functions into single wrist-worn endpoints.
Silicon-anode lithium-ion cells are electrifying power budget allocations across premium smartwatch lines. Apple and Samsung manufacturing partners have qualified solid-electrolyte interphase coatings that suppress volume expansion during cycling. Healthcare providers prescribing remote monitoring now specify 72-hour minimum runtime as a procurement threshold, compressing graphite-based designs to mid-tier positioning.
The EU Medical Device Regulation's Class IIa reclassification of software-driven diagnostic wearables is fragmenting conformity assessment routes. Notified body capacity constraints in Germany and the Netherlands extend CE marking timelines 8-14 months beyond the MDR's 2017 transition schedule. Manufacturers are responding by front-loading clinical evidence generation for predicate device equivalence, prioritizing blood oxygen and atrial fibrillation detection algorithms.
Employer-sponsored wellness programs are unbundling fitness tracking from medical-grade monitoring, creating parallel procurement channels. Large self-insured employers in the United States now contract directly with Omada and Livongo for diabetes prevention hardware, bypassing retail distribution. This bifurcation concentrates consumer-grade volume through Amazon and Best Buy while channeling clinical-grade shipments through specialty distributors servicing health systems.
Smart Wearable Equipment Market Segmentation
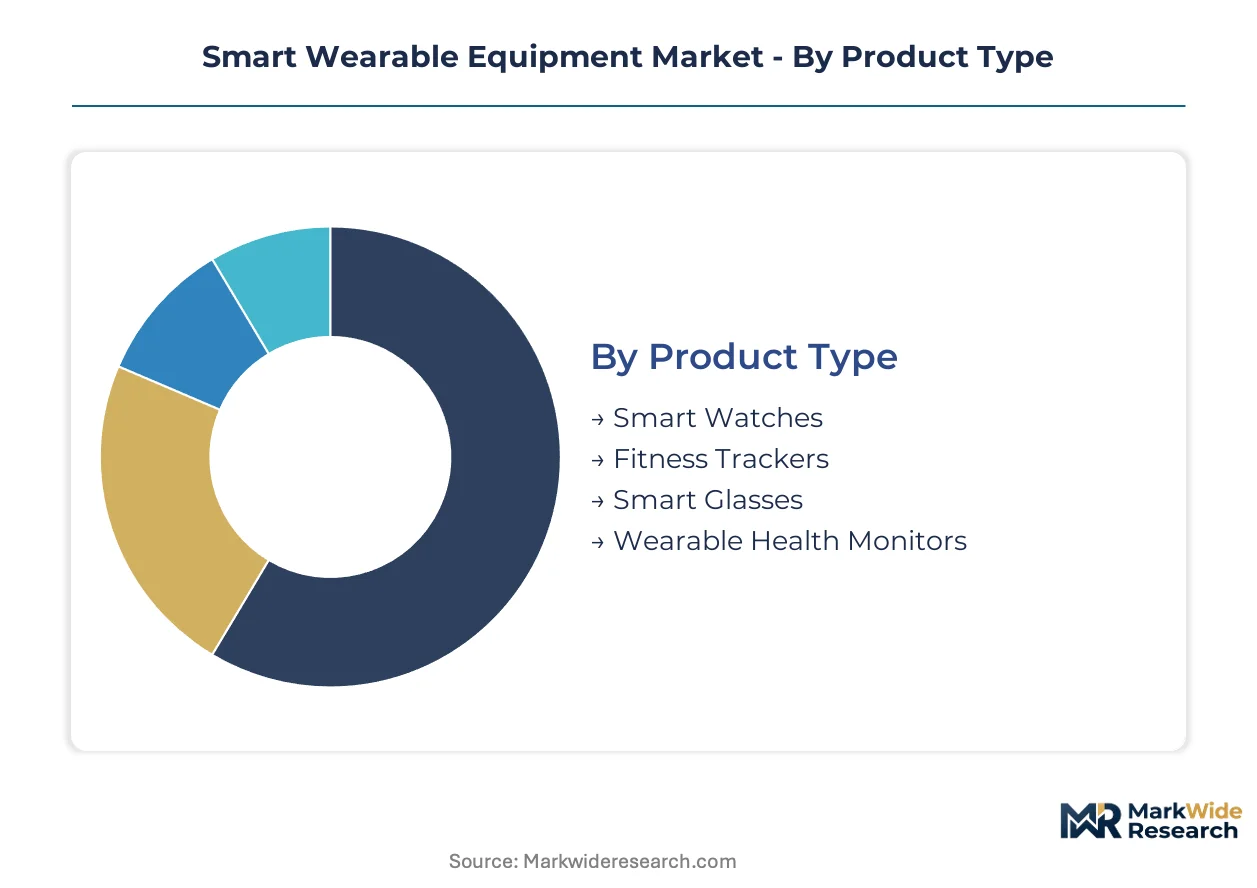
Smart wearable equipment segments fragment across device form factors, connectivity protocols, user profiles, and clinical use cases. Each dimension carries distinct margin structures, certification requirements, and channel economics that reshape competitive positioning. Understanding these boundaries clarifies where silicon-anode battery investments and FDA clearance spending concentrate.
Product Type:
Standardized mass-market designs compete against prescription-grade hardware requiring biocompatibility certification and clinical validation workflows.
- Smart Watches:Multipurpose wrist-worn endpoints integrating AMOLED displays, multi-sensor arrays, and app ecosystems. Demand concentrates among corporate professionals in the United States and Germany where employer wellness subsidies offset premium pricing. FDA-cleared ECG and blood oxygen variants command 3-4x hardware margins over consumer-tier equivalents.
- Wearable Health Monitors:Dedicated clinical devices with continuous glucose monitoring, arrhythmia detection, or blood pressure tracking. Prescription workflows in Germany and reimbursement expansion for chronic heart failure drive fastest category expansion. CE marking under EU MDR Class IIa extends development timelines 8-14 months.
- Fitness Trackers:Simplified motion-sensing bands prioritizing step counting and calorie estimation. Volume concentrates through Amazon and Best Buy retail channels targeting fitness enthusiasts with sub-$100 price points.
- Smart Glasses:Optical see-through displays with embedded cameras and spatial computing capabilities. Enterprise maintenance and logistics applications in the United States pilot adoption ahead of consumer scaling.
Leading the category by volume: Smart Watches. Growing fastest: Wearable Health Monitors.
Technology:
Connectivity architecture determines power budget allocation, antenna integration complexity, and interoperability with hospital IT systems.
- Bluetooth:Low-energy protocol dominating short-range pairing with smartphones and clinical gateways. Ubiquitous across all price tiers with minimal RF engineering requirements.
- GPS:Multi-constellation satellite positioning enabling outdoor activity tracking without tethered phones. Garmin and dedicated sports wearable vendors anchor demand among athletes requiring meter-level accuracy in remote terrain.
- Wi-Fi:Direct cloud synchronization bypassing phone intermediaries for remote patient monitoring uploads. Healthcare provider procurement specifications increasingly mandate standalone connectivity for elderly patient populations.
- NFC:Near-field payment and access control integration. Corporate professional adoption in Germany and the United States drives contactless transit and building entry use cases.
Bluetooth anchors installed base. GPS-enabled devices gain share fastest among premium outdoor segments.
End User:
Procurement authority separates institutional buyers with clinical validation requirements from individual purchasers prioritizing aesthetics and app ecosystems.
- Healthcare Providers:Hospitals, clinics, and accountable care organizations prescribing FDA-cleared devices for remote patient monitoring. German statutory insurer reimbursement creates immediate volume pull for prescription-grade wearable ECG hardware.
- Fitness Enthusiasts:Self-directed consumers tracking activity metrics without clinical oversight. Amazon and direct-to-consumer channels dominate with minimal regulatory friction.
- Athletes:Performance-optimized users demanding GPS precision, ruggedized housings, and extended battery runtime. Specialized retailers and team procurement contracts concentrate volume.
- Corporate Professionals:Employer-subsidized wellness program participants. United States self-insured employers contract directly with telehealth platforms, bypassing retail distribution for medical-grade hardware.
Healthcare providers drive highest average selling prices. Corporate wellness programs expand fastest as benefits administrators consolidate purchasing.
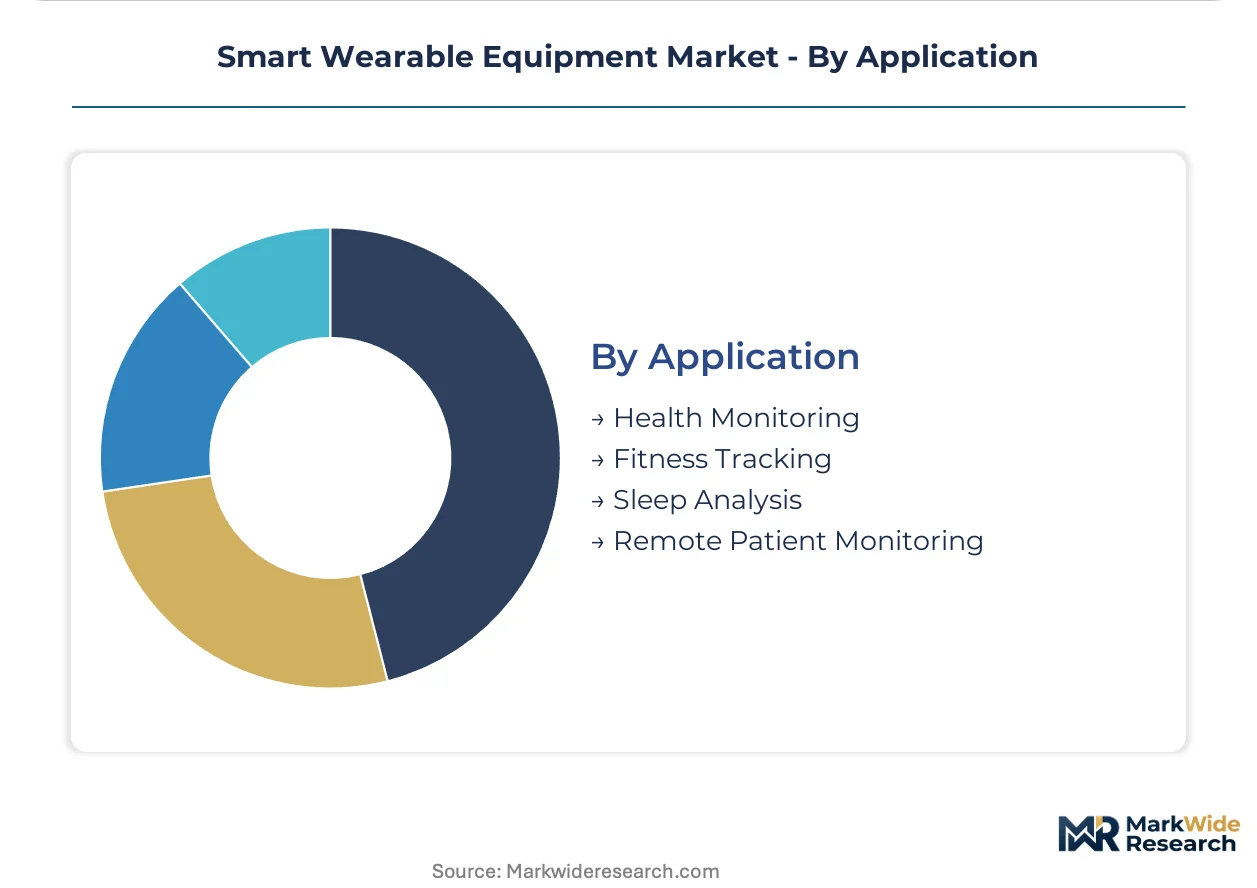
Application:
Clinical-grade functionality commands pricing premiums over lifestyle tracking, with reimbursement eligibility determining addressable market scale.
- Health Monitoring:Continuous vital sign surveillance including heart rate variability, blood oxygen saturation, and skin temperature. FDA software-as-a-medical-device guidance accelerates commercialization for algorithm-driven diagnostics in the United States.
- Remote Patient Monitoring:Telemetric data transmission to clinical dashboards for chronic disease management. Medicare reimbursement codes and German statutory coverage create sustainable revenue streams distinct from consumer hardware cycles.
- Fitness Tracking:Activity quantification spanning steps, distance, and caloric expenditure. Broadest installed base though commoditization pressures margins.
- Sleep Analysis:Polysomnography-proxy metrics including REM detection and respiratory disturbance indices. Premium tier differentiation focus as optical sensor accuracy improves.
Fitness tracking holds largest installed base. Remote patient monitoring climbs fastest as reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement and consumer electronics retail concentrate demand in three major economies, with reimbursement policy divergence creating distinct commercialization pathways across regulatory jurisdictions.
United States
Employer wellness subsidies and Medicare remote patient monitoring reimbursement drive institutional procurement of FDA-cleared devices. The FDA's 2021 software-as-a-medical-device guidance accelerates commercialization timelines for algorithm-driven diagnostics. Boston and San Francisco Bay Area clusters host telehealth platform partnerships that bypass retail distribution for clinical-grade hardware.
Germany
Statutory health insurer coverage for chronic heart failure remote monitoring creates immediate volume pull for prescription-grade wearable ECG hardware. EU MDR Class IIa reclassification and GDPR Article 9 health data restrictions extend conformity timelines and legal engineering costs. Munich and Stuttgart industrial corridors concentrate EMS partnerships serving European distribution.
China
Domestic consumer electronics retail and enterprise wellness programs absorb volume from local OEMs and global brands alike. NMPA medical device registration and MIIT radio equipment certification govern market entry for health claim devices. Shenzhen and Dongguan manufacturing clusters integrate silicon-anode battery pilot lines from Samsung SDI partnerships.
India
Production-linked incentives under the PLI scheme for wearable electronics attract EMS partners to Gujarat and Tamil Nadu manufacturing clusters. BIS certification and CDSCO medical device rules constrain unvalidated health claim devices. Bangalore and Hyderabad technology corridors host algorithm development for cuffless blood pressure monitoring spinouts.
Japan
Aging demographics and METI promotion of digital health drive institutional adoption of remote patient monitoring devices. PMDA medical device approval and JIS standards for electromagnetic compatibility govern product registration. Tokyo and Osaka metropolitan areas concentrate telehealth platform bundling with employer insurance contracts.
Smart Wearable Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration in chip design and sensor fabrication determining margin capture at the premium tier. The vendor base concentrates around three strategic archetypes: integrated consumer technology platforms controlling silicon and health sensor supply chains; specialized GPS and outdoor equipment vendors commanding ruggedization pricing power; and diversified electronics conglomerates leveraging display manufacturing and foundry partnerships. Competitive moves center on silicon-anode battery qualification for runtime extension and FDA 510(k) clearance accumulation for clinical-grade biomarker claims.
Among integrated consumer technology platforms, Apple Inc. and Samsung Electronics Co., Ltd. exemplify the vertically integrated archetype through captive chip design and health sensor fabrication capabilities. Garmin Ltd. occupies a distinct position within specialized outdoor and aviation segments where GPS precision and ruggedized housings sustain pricing premiums outside consumer electronics commoditization pressures.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Garmin Ltd. |
| Xiaomi Corporation |
| Huawei Technologies Co., Ltd. |
| Alphabet Inc. |
| Fossil Group Inc. |
| Sony Corporation |
| Imagine Marketing Limited |
| Others |
Pricing and Supply Chain Analysis
Healthcare provider procurement concentration in the United States and Germany anchors contract-based pricing for FDA-cleared and CE-marked devices, while consumer retail channels absorb volume-driven compression in fitness trackers and unverified health claim wearables.
Pricing Analysis
Volume concentrates in sub-$100 fitness bands through Amazon and Best Buy retail, while prescription-grade wearable ECG and continuous glucose monitoring devices command hardware margins amplified by Medicare and German statutory reimbursement eligibility. Pricing stratifies across FDA 510(k)-cleared clinical tiers, CE-marked diagnostic tiers, and unvalidated consumer wellness tiers, with certification grade as the dominant price differentiation driver. Cost compression in consumer wellness hardware intensifies because Chinese OEMs flood direct-to-consumer channels with sensor-laden devices lacking clinical validation. Fitness enthusiasts exhibit highest price sensitivity, whereas hospital purchasing committees and corporate benefits administrators demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Lithium chemical processing rests on Chinese Sichuan and Qinghai province concentration, with over 60% of global capacity feeding battery cell fabrication for wearable power systems. Silicon-anode precursor materials and solid-electrolyte interphase coatings draw from South Korean Samsung SDI pilot partnerships and Japanese specialty chemical producers, while AMOLED display modules hinge on Samsung Display and BOE Technology manufacturing clusters. Single-source vulnerability in lithium hydroxide refining exposes cost structures to export licensing volatility from China's Ministry of Commerce. Distribution runs through EMS partners in Shenzhen and Dongguan for global brand OEMs, with regional fulfillment centers in Rotterdam and Memphis serving European and North American healthcare procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-anode battery cell capacity constraints among qualified suppliers prop pricing power for premium smartwatch vendors controlling qualified manufacturing partnerships, compressing margin recovery timelines for second-tier hardware brands.
For Market Incumbents: Cement FDA 510(k) clearance accumulation for novel biomarkers like cuffless blood pressure and continuous glucose monitoring, defending against algorithm-driven diagnostics from Stanford and MIT spinouts. Prioritize backward integration into health sensor fabrication to capture margin erosion from discrete component vendors, while locking multi-year silicon-anode supply agreements with Samsung SDI and Toyota manufacturing partnerships to preempt cell allocation shortages. For New Entrants and Emerging Players: Direct-to-employer telehealth platform bundling offers the most penetrable channel architecture, bypassing retail commoditization through white-label contracts with Teladoc and Amwell for diabetes prevention hardware. Target India's PLI scheme manufacturing clusters in Gujarat and Tamil Nadu to exploit 4-6% production-linked incentives and BIS certification pathways, then leverage cost-advantaged production for Southeast Asian consumer wellness expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized GPS and outdoor equipment vendors with ruggedization IP and aviation segment pricing power in Germany and the United States, where Garmin anchors defensible positioning. Watch FDA software-as-a-medical-device guidance expansion and EU MDR notified body capacity constraints as inflection indicators determining which algorithm categories achieve clinical-scale deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Accumulation | Algorithm-driven diagnostics from Apple and Samsung secure Medicare reimbursement eligibility for remote patient monitoring. |
| Silicon-Anode Battery Partnership | Samsung SDI and Toyota manufacturing alliances resolve energy density bottlenecks constraining always-on health sensing. |
| Telehealth Platform Bundling | White-label contracts with Teladoc shift distribution through benefits administrators rather than retail channels. |
| EU MDR Class IIa CE Marking | Notified body capacity constraints in Germany and Netherlands extend conformity timelines for blood oxygen algorithms. |
| India PLI Scheme Manufacturing Entry | EMS partners in Gujarat and Tamil Nadu exploit production-linked incentives covering 4-6% of incremental sales value. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts manager surveys underwrites the qualitative findings on procurement specification evolution. Primary fieldwork with FDA regulatory affairs specialists, CE marking technical file consultants, and silicon-anode battery R&D directors combined with secondary validation from FDA 510(k) filings, EMA MDR transition dashboards, and CMS Medicare reimbursement code updates. Bottom-up demand modeling across device form factors and top-down macroeconomic anchoring triangulate volume estimates.
Comparable-period anchoring to 2026 baseline valuations and 2035 projection endpoints structured the CAGR derivation across the analysis window. Segmentation dimensions modeled include device form factor, connectivity protocol architecture, end-user procurement authority, and clinical application tier with reimbursement eligibility. CAGRs reflect demand elasticity coefficients derived from German statutory coverage expansion and United States Medicare remote patient monitoring code activation, cross-referenced against lithium supply concentration risk premiums.
The model holds under sustained silicon-anode qualification timelines and stable FDA software-as-a-medical-device guidance interpretation; deviation in Chinese lithium export licensing regimes or EU MDR notified body bankruptcy would shift capacity allocation and commercialization timelines. Forecasts embed assumptions on reimbursement code expansion velocity and solid-state battery manufacturing yield curves. A small set of named triggers—NMPA medical device registration acceleration, India PLI scheme incentive revision, and METI digital health promotion budget allocation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Global Weight Management Devices Market