
 North America Wearable Sensors Market | 2026-2036
North America Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wearable Sensors Market Foresight
Healthcare providers is bifurcating demand away from pure consumer fitness buyers as reimbursement codes for remote physiologic monitoring expand across Medicare Advantage plans. Texas Instruments Incorporated leverages its analog front-end expertise to dominate clinical-grade photoplethysmography modules. STMicroelectronics anchors MEMS inertial sensing for fall-detection wearables through foundry partnerships in Arizona and Texas. Apple Inc. competes by extending its electrocardiogram and blood oxygen stack from consumer wellness into employer-sponsored preventive health contracts.
North America wearable sensors are microelectromechanical and optoelectronic transducers, typically fabricated on silicon or flexible polymer substrates with feature resolutions below one micron, that convert biomechanical, biochemical, or environmental stimuli into electrical signals for real-time health and activity quantification. Their primary commercial purpose spans preventive diagnostics, athletic performance optimization, and chronic disease management through continuous, non-invasive data capture. Medical wearables command premium margin pools owing to FDA validation requirements and clinical trial overhead, while fitness trackers face commoditization pressure as Bluetooth-enabled units from Asian contract manufacturers flood Amazon and direct-to-consumer channels. Health monitoring applications absorb the largest share of semiconductor content per device, with multi-parameter arrays combining accelerometry, optical heart rate, and galvanic skin response now standard in employer wellness programs.
FDA 510(k) premarket notification and the FCC's Part 15 rules for unlicensed radio transmission jointly determine product architecture, with dual-submission timelines often extending development cycles by eight to fourteen months for connectivity-integrated medical wearables. Health Canada and PMRA maintain aligned but separate device licensing requirements that fragment North American go-to-market strategy for Toronto and Vancouver headquartered startups. Stakeholders must monitor CMS reimbursement rulemaking for continuous glucose monitoring adjuncts and pulse oximetry, as coverage determinations will dictate whether hospital-at-home programs sustain sensor procurement volumes or retreat to conventional bedside monitoring.
Market Dynamics
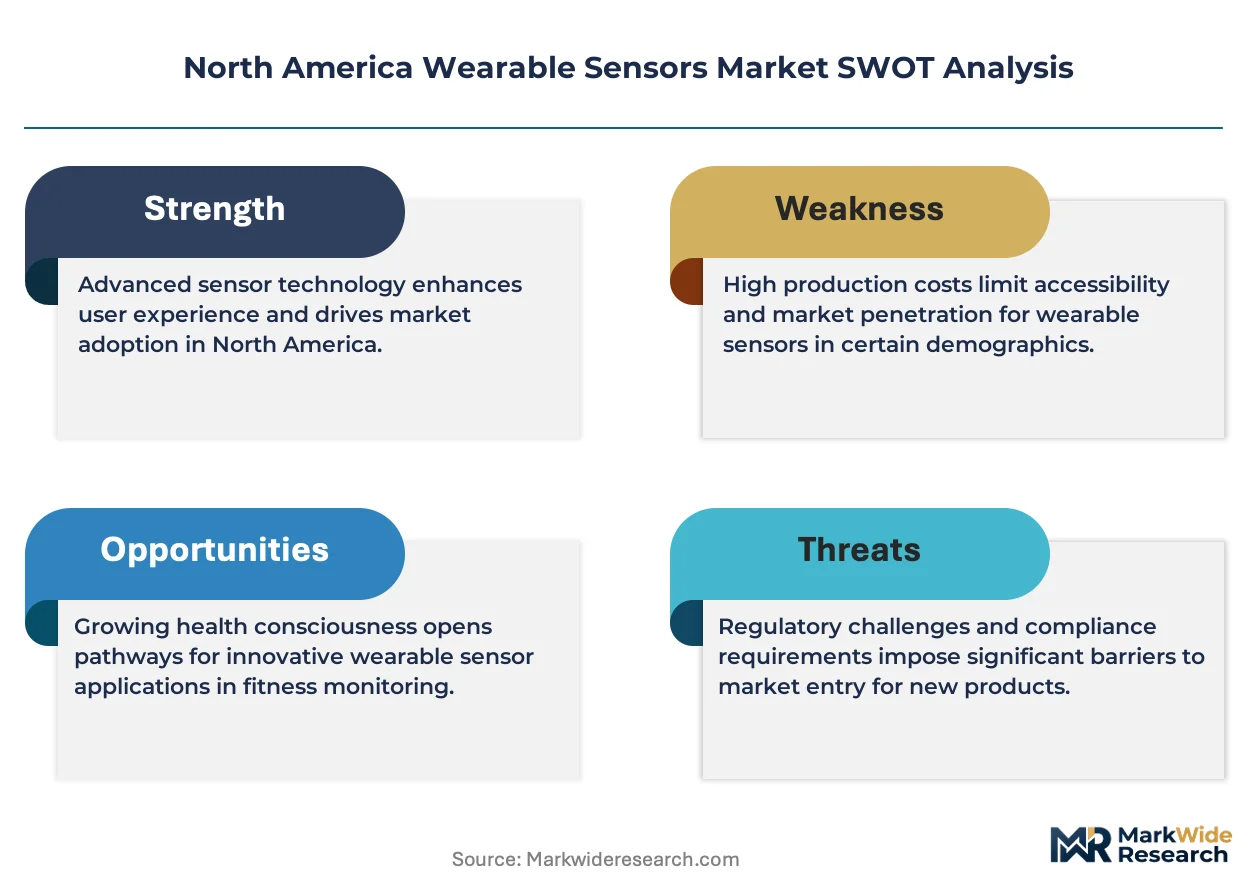
Reimbursement pathway fragmentation between CMS Medicare Advantage plans and commercial payers is bifurcating procurement channels, forcing sensor vendors to maintain dual regulatory stacks for clinical-grade and wellness-tier devices.
Growth Catalysts
- Remote Physiologic Monitoring Codes:CMS expansion of CPT 99453-99458 reimbursement categories for pulse oximetry and accelerometry data is pulling hospital-at-home programs toward continuous monitoring contracts.
- Silicon Valley Cluster Density:Stanford Health Care and UCSF Medical Center proximity to semiconductor foundries in San Jose accelerates FDA pre-submission feedback loops for photoplethysmography startups.
- Flexible Polymer Substrates:Microfabrication advances enabling sub-micron feature resolution on polyimide bases are expanding conformal sensor placement for wound monitoring and hydration tracking.
Market Restraints
- Dual-Submission Timelines:FDA 510(k) premarket notification paired with FCC Part 15 unlicensed radio certification extends development cycles by eight to fourteen months for connectivity-integrated medical wearables.
- Foundry Concentration:Arizona and Texas MEMS fabrication capacity constraints create bottlenecks for inertial sensing modules used in fall-detection algorithms.
- Asian Contract Manufacturer Flooding:Bluetooth-enabled fitness trackers from Shenzhen and Dongguan assembly plants are compressing margins in direct-to-consumer channels through Amazon marketplace saturation.
Strategic Opportunities
- Canadian Licensing Alignment:Health Canada and PMRA device licensing requirements, though separate from FDA pathways, offer faster review timelines for Toronto and Vancouver headquartered startups targeting North American expansion.
- Employer Preventive Health Contracts:Apple electrocardiogram and blood oxygen stack extensions into corporate wellness programs are creating new B2B procurement channels beyond retail consumer sales.
- Galvanic Skin Response Arrays:Multi-parameter sensor fusion combining accelerometry, optical heart rate, and electrodermal activity is penetrating stress-management applications in financial services and aviation sectors.
Industry Challenges
- Clinical Validation Talent Scarcity:Biostatisticians with FDA Q-Submission experience command premium compensation, stretching burn rates for Series B sensor startups preparing pivotal trials.
- Legacy Hospital IT Integration:Epic and Cerner electronic health record compatibility requirements force middleware development that delays pilot deployments by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wearable Sensors Market |
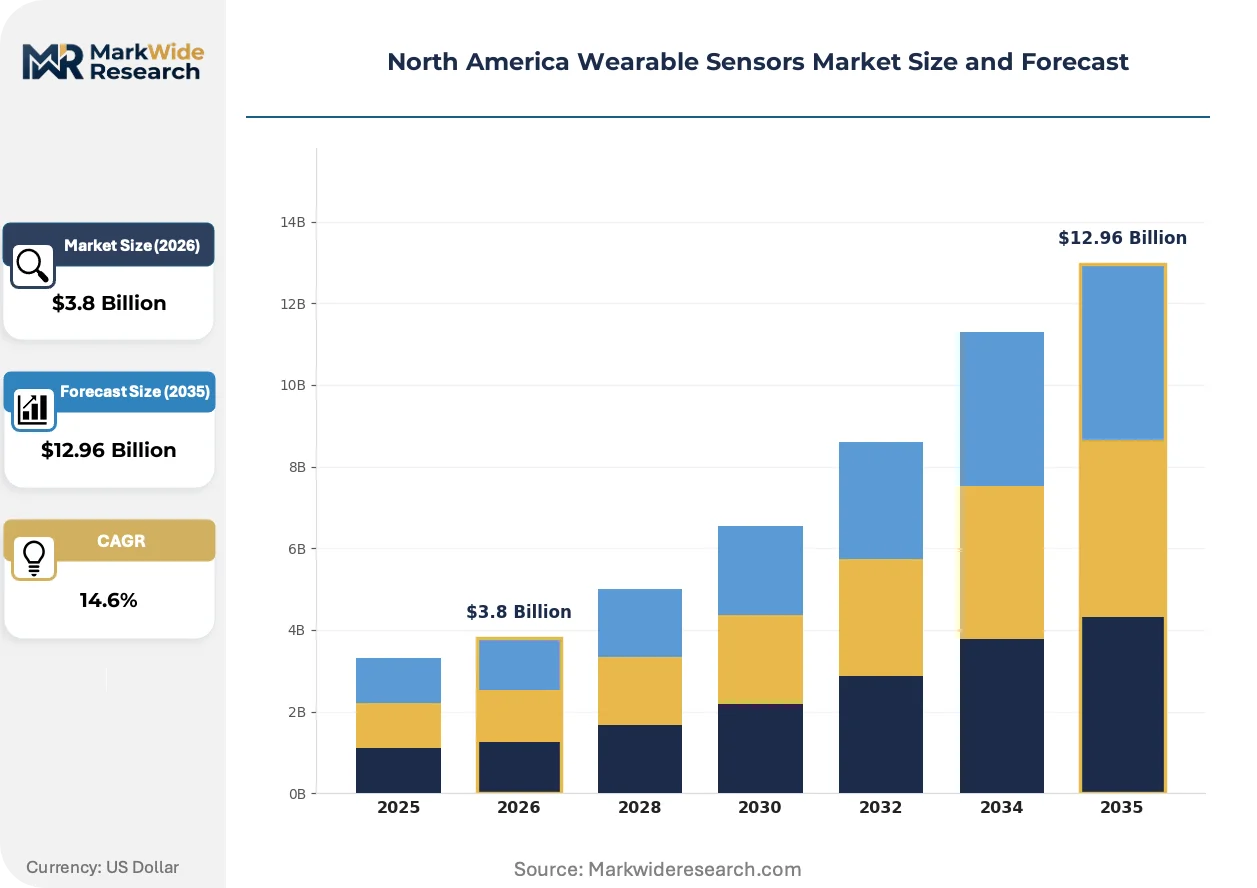
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, Medical Wearables, Head-mounted Devices End User: Consumers, Healthcare Providers, Sports Teams, Fitness Enthusiasts Technology: Bluetooth, NFC, Wi-Fi, Zigbee Application: Health Monitoring, Fitness Tracking, Medical Diagnostics, Personal Safety |
| Companies Covered | Texas Instruments Incorporated, STMicroelectronics, Apple Inc., NXP Semiconductors NV, Infineon Technologies AG, Fitbit Inc., Analog Devices Inc., TE Connectivity Ltd, Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wearable Sensors Market Shifts & Advancements
Photoplethysmography module miniaturization and algorithmic noise reduction are compressing form factors while expanding clinical-grade signal fidelity. These shifts are reshaping competitive differentiation from hardware specifications to software-validated biomarker extraction.
Optical heart rate sensors with multi-wavelength LED arrays are displacing single-channel green-light photoplethysmography in employer wellness programs. Human resources departments at Fortune 500 manufacturers are specifying these modules for fatigue-monitoring applications in warehouse and logistics operations. The structural consequence is a margin compression for basic fitness trackers while premium multi-parameter devices capture procurement budgets.
FDA breakthrough device designation pathways for continuous glucose monitoring adjuncts are accelerating premarket review timelines for metabolic sensor startups. This regulatory tailwind is concentrating venture deployment in Boston's Route 128 corridor near Joslin Diabetes Center and Massachusetts General Hospital research affiliates. Sensor vendors are responding by co-locating clinical affairs teams within walking distance of FDA's White Oak campus for face-to-face Q-Submission meetings.
Hospital procurement committees are unbundling after-sales calibration and algorithm update services from initial device purchases. This behavioral shift is disrupting traditional capital-equipment leasing models that bundled five-year maintenance contracts. The unbundling is most visible in Texas Medical Center and Cleveland Clinic health system RFPs, where sensor vendors must now price software subscriptions separately from hardware amortization schedules.
North America Wearable Sensors Market Segmentation
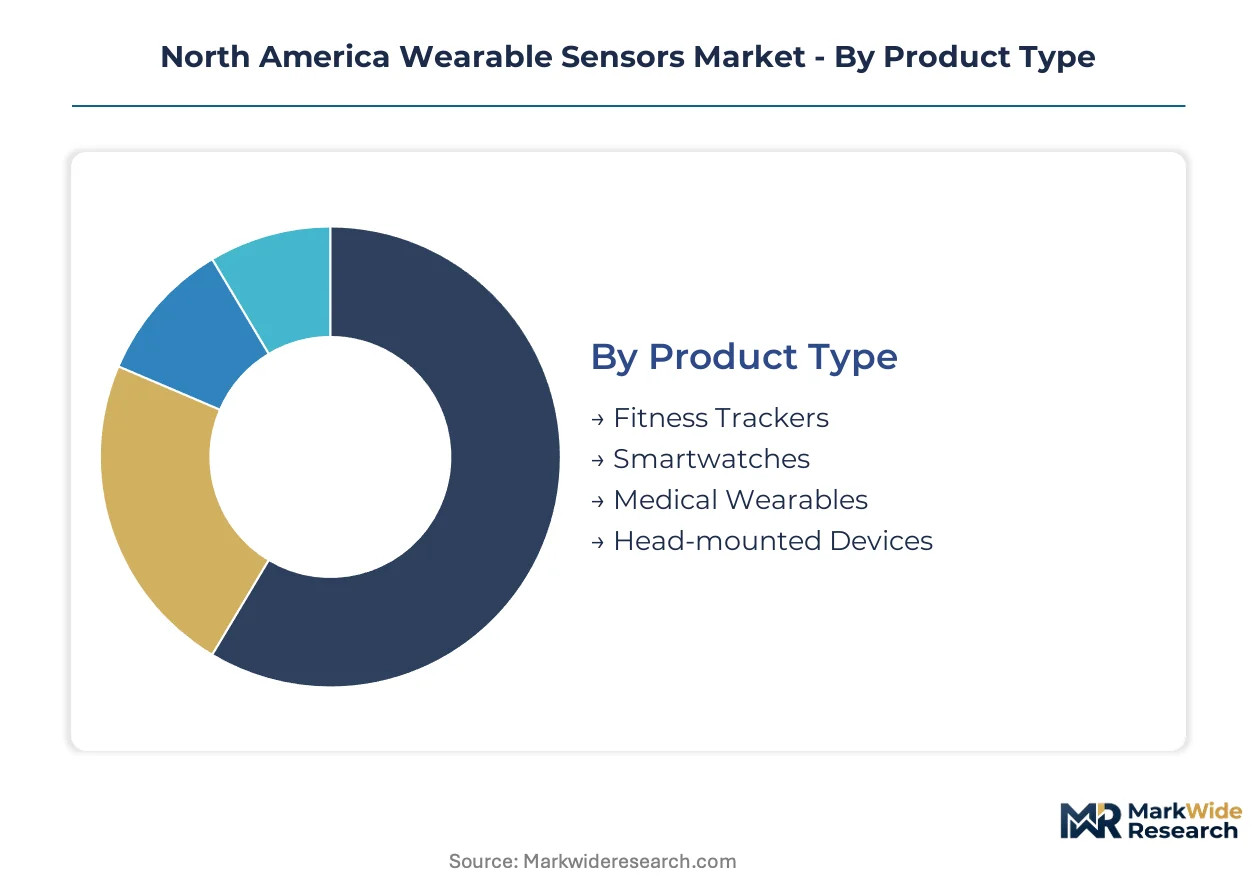
Wearable sensor procurement channels diverge sharply between direct-to-consumer retail and institutional contracting, with reimbursement eligibility determining which segments flow through hospital supply chains versus employer wellness programs or Amazon marketplace listings.
Product Type:
Fitness trackers and smartwatches dominate direct-to-consumer e-commerce channels, while medical wearables concentrate in hospital-at-home procurement committees and Medicare Advantage reimbursement pathways.
- Fitness Trackers:Basic accelerometry and optical heart rate modules fabricated on rigid PCB substrates. Demand concentrates in California's Silicon Valley consumer electronics retail and Amazon direct-to-consumer channels, where Shenzhen contract manufacturers compress margins through Bluetooth-enabled unit flooding.
- Smartwatches:Multi-parameter arrays combining photoplethysmography, inertial MEMS, and galvanic skin response on flexible polymer substrates. Texas Medical Center and Cleveland Clinic health systems are unbundling after-sales calibration services from initial hardware purchases for these devices.
- Medical Wearables:FDA 510(k)-cleared devices with clinical-grade signal fidelity requirements.
- Head-mounted Devices:Optoelectronic transducers for fatigue monitoring in logistics and aviation applications.
By volume, fitness trackers lead. By growth pace, medical wearables are expanding most quickly as CMS reimbursement codes for remote physiologic monitoring pull procurement toward continuous monitoring contracts.
End User:
Cost tier stratification separates premium clinical-grade deployments from commoditized consumer wellness purchases, with biostatistician talent scarcity stretching burn rates for Series B startups targeting healthcare provider segments.
- Healthcare Providers:Hospital-at-home programs and Medicare Advantage plans requiring FDA-validated devices with Epic and Cerner electronic health record compatibility. Stanford Health Care and UCSF Medical Center proximity to San Jose foundries accelerates pre-submission feedback loops.
- Consumers:Direct-to-consumer purchasers through Amazon marketplace and retail electronics channels, where Asian contract manufacturer saturation compresses pricing power for basic fitness trackers.
- Sports Teams:Professional and collegiate athletic programs specifying multi-wavelength LED arrays for fatigue monitoring.
- Fitness Enthusiasts:Individual purchasers of Bluetooth-enabled wellness devices through direct-to-consumer channels.
By revenue concentration, healthcare providers dominate. By volume scale, consumers absorb the largest unit shipments.
Technology:
Application requirements determine connectivity selection, with medical diagnostics mandating FCC Part 15 compliance timelines that extend development cycles by eight to fourteen months.
- Bluetooth:Dominant protocol for fitness trackers and consumer smartwatches, with FCC Part 15 unlicensed radio certification requirements.
- Wi-Fi:Higher bandwidth connectivity for hospital-at-home programs requiring continuous data streaming to Epic and Cerner electronic health record systems.
- NFC:Short-range pairing and payment integration in employer-sponsored wellness programs.
- Zigbee:Low-power mesh networking for multi-device sensor arrays in clinical environments.
By deployment breadth, Bluetooth leads. By clinical adoption velocity, Wi-Fi is gaining share fastest as hospital procurement committees prioritize electronic health record integration.
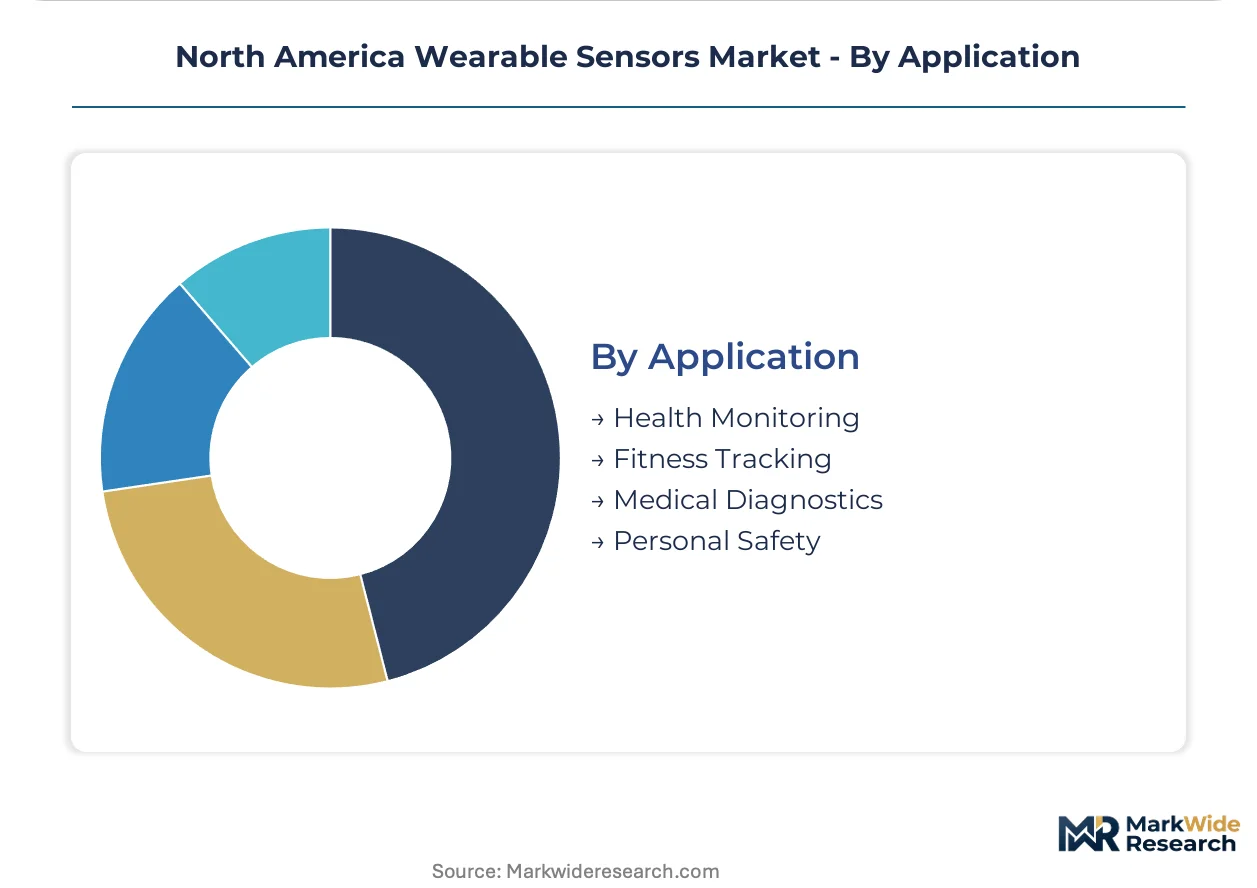
Application:
Margin tier differentiation separates premium medical diagnostics—with FDA validation overhead and clinical trial requirements—from commoditized fitness tracking facing Shenzhen assembly plant competition.
- Health Monitoring:Continuous accelerometry, optical heart rate, and galvanic skin response arrays in employer wellness programs. Fortune 500 manufacturers specify multi-wavelength LED modules for warehouse fatigue monitoring.
- Medical Diagnostics:FDA 510(k)-cleared photoplethysmography and continuous glucose monitoring adjuncts. Boston's Route 128 corridor concentrates venture deployment near Joslin Diabetes Center and Massachusetts General Hospital research affiliates.
- Fitness Tracking:Basic activity quantification through consumer-grade accelerometry.
- Personal Safety:Fall-detection algorithms leveraging STMicroelectronics MEMS inertial sensing modules.
By semiconductor content per device, health monitoring leads. By regulatory tailwind, medical diagnostics shows the steepest expansion trajectory as FDA breakthrough device designations accelerate premarket review timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-5 corridor and cross-border freight rail networks linking Vancouver to San Diego underwrite North America's sensor manufacturing density, while the NAFTA successor USMCA governs semiconductor component flows across the three member economies.
United States
Medicare Advantage remote physiologic monitoring expansion and employer wellness program procurement are pulling demand toward clinical-grade devices. FDA 510(k) premarket notification paired with FCC Part 15 radio certification extends development timelines for connectivity-integrated wearables. Silicon Valley's Stanford Health Care proximity to San Jose foundries accelerates pre-submission feedback loops for photoplethysmography startups.
Canada
Toronto and Vancouver headquartered startups target faster Health Canada and PMRA device licensing review timelines for North American expansion. The country's national medical device regulator maintains aligned but separate requirements from FDA pathways, fragmenting go-to-market strategy. Ontario's corridor concentrates clinical affairs talent near research hospitals deploying hospital-at-home programs.
Mexico
Assembly operations in Baja California and Chihuahua support US-bound fitness tracker production under USMCA rules of origin for semiconductor components. The country's federal economic secretariat promotes electronics manufacturing through shelter programs near the border. Guadalajara's tech cluster attracts sensor module integration facilities serving direct-to-consumer channels.
North America Wearable Sensors Market Competitive Landscape
Listed leaders compete with private specialists across reimbursement eligibility tiers, with publicly traded analog semiconductor giants dominating clinical-grade photoplethysmography while private wellness-focused hardware vendors fight margin compression in consumer channels. The vendor base stratifies into FDA-validated medical device suppliers, consumer electronics platforms extending into employer contracts, and Asian contract manufacturer-dependent fitness tracker brands. Three archetypes prevail: analog front-end specialists, MEMS fabrication anchor tenants, and integrated health platform operators. M&A activity concentrates on algorithm startups with FDA Q-Submission experience, while capacity expansion targets Arizona and Texas MEMS foundry partnerships.
Among analog front-end specialists, Texas Instruments Incorporated and Analog Devices Inc. exemplify the clinical-grade signal chain archetype, with their corporate structures reflecting decades of precision semiconductor manufacturing heritage. STMicroelectronics occupies a position within the MEMS fabrication tier, leveraging foundry partnerships to anchor inertial sensing supply for fall-detection applications. Apple Inc. represents the integrated platform operator archetype, extending electrocardiogram and blood oxygen capabilities from consumer wellness into corporate procurement channels.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| STMicroelectronics |
| Apple Inc. |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| Fitbit Inc. |
| Analog Devices Inc. |
| TE Connectivity Ltd |
| Garmin Ltd. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with Arizona and Texas MEMS foundries lock in semiconductor wafer access while anchoring unit cost visibility for photoplethysmography module vendors. These contracts insulate clinical-grade sensor manufacturers from spot-market silicon price swings while committing buyers to minimum volume thresholds that shape procurement flexibility.
Pricing Analysis
Volume-discount tiering separates hospital-at-home procurement committees placing thousand-unit orders from Amazon marketplace consumers purchasing single fitness trackers. FDA 510(k) certification grade and after-sales calibration bundling drive price differentiation between clinical and wellness tiers. Cost compression in consumer Bluetooth-enabled units intensifies because Shenzhen contract manufacturers flood direct-to-consumer channels. Employer wellness programs show least price sensitivity, prioritating multi-parameter arrays with Epic and Cerner compatibility over per-unit cost.
Supply Chain Analysis
Inventory buffers for MEMS inertial sensing modules stretch lead times when Arizona and Texas foundry capacity tightens during hospital-at-home program expansions. Silicon wafer fabrication draws from Taiwan, South Korea, and domestic U.S. facilities, while polyimide flexible substrate production feeds from Japanese and German chemical suppliers. Single-source vulnerability concentrates in analog front-end chip supply where Texas Instruments and Analog Devices anchor clinical-grade signal chains. Distribution runs through hospital procurement committees for medical wearables and Amazon fulfillment centers for consumer fitness trackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware unbundling from software subscriptions creates a service-attach opportunity as Texas Medical Center and Cleveland Clinic procurement committees separately price algorithm updates and calibration services. This recurring-revenue layer expands faster than device amortization schedules.
For Market Incumbents: Secure FDA Q-Submission talent pools in Boston's Route 128 corridor to defend against emerging photoplethysmography startups accelerating premarket review timelines. Anchor MEMS foundry partnerships in Arizona and Texas through capacity reservation clauses that block competitor access during hospital-at-home procurement surges.
For New Entrants and Emerging Players: Lead with galvanic skin response arrays targeting stress-management applications in financial services and aviation sectors where reimbursement requirements are absent. Canadian Health Canada and PMRA pathways offer faster licensing timelines for Toronto and Vancouver headquartered ventures before FDA dual-submission complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward algorithm startups with FDA Q-Submission experience and biostatistician teams capable of navigating 510(k) premarket notification pathways. Long-term viability hinges on software-validated biomarker extraction capabilities rather than hardware module fabrication. Watch CMS reimbursement rulemaking for continuous glucose monitoring adjuncts as the inflection signal determining whether hospital-at-home sensor procurement volumes sustain or retreat.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for metabolic sensor startups near Joslin Diabetes Center. |
| Hospital System Partnership | Epic and Cerner EHR compatibility requirements force six-to-nine month middleware development cycles. |
| Software Companion Development | Unbundled algorithm subscriptions capture recurring revenue separate from hardware amortization. |
| Reimbursement Strategy | CMS CPT 99453-99458 code expansion pulls procurement toward continuous monitoring contracts. |
| CE Marking Pathway | Canadian Health Canada alignment offers faster review timelines for North American expansion. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers and hospital purchasing committees anchors the qualitative findings against secondary validation from FDA 510(k) filings and CMS reimbursement databases. Conversations with GPO contracts managers, clinical affairs directors at sensor startups, and semiconductor foundry operations heads combined with SEC 10-K disclosures from analog front-end suppliers and trade data from USMCA semiconductor component flows. Bottom-up unit shipment estimates triangulate against top-down Medicare Advantage remote monitoring expenditure projections.
Sensitivity analysis across the projection horizon tests demand elasticity for clinical-grade versus wellness-tier devices under varying CMS coverage determination scenarios. Segmentation dimensions modeled include product type, end user archetype, connectivity technology, and application purpose alongside reimbursement eligibility tiers. CAGRs derive from installed base growth rates and replacement cycle assumptions calibrated against hospital procurement database trends. Forecast inputs incorporate MEMS foundry capacity utilization rates and FDA premarket review timeline distributions.
Forecasts assume regulatory continuity in FDA 510(k) and FCC Part 15 regimes; material policy shifts would require re-modeling submission timeline impacts on product launch schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market