
 Smart Sports Bracelet Market | 2026-2036
Smart Sports Bracelet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sports Bracelet Market Insights
Asian component suppliers are rebalancing capacity toward advanced biometric sensors and low-power Bluetooth SoCs. Apple leverages vertical integration across silicon, software, and health services to sustain premium positioning. Garmin anchors its competitive stance through specialized GPS and multi-sport analytics for endurance athletes. Xiaomi Corporation competes on manufacturing scale and ecosystem pricing across emerging markets.
A smart sports bracelet is a wrist-worn electronic device integrating accelerometers, photoplethysmography sensors, and wireless transceivers to capture physiological and kinematic data during physical activity, with primary purpose of quantifying athletic performance, recovery metrics, and longitudinal health trends for consumers and institutional buyers. The fitness tracker segment leads volume shipments due to accessible price points and streamlined feature sets, while health monitor configurations command margin concentration through clinical-grade sensor arrays and regulatory clearance requirements. GPS-enabled units represent the fastest-growing technology integration as outdoor activity tracking becomes standard across athlete and casual user categories.
FCC certification governs radio frequency emissions for US market entry, while CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility and health safety standards for European distribution. China's MIIT enforces GB standards for wireless transmission and SAMR oversees product quality certification, collectively raising compliance costs but filtering substandard entrants. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications that could reclassify certain heart rate and blood oxygen features.
Market Dynamics
Professional sports teams and collegiate athletic programs are expanding procurement of biometric monitoring wearables, creating institutional demand that reshapes product specifications toward clinical-grade accuracy and durability standards.
Growth Catalysts
- GDPR-aligned health data frameworks:The EU's data protection mandates are accelerating enterprise adoption of compliant wearables by professional sports organizations seeking liability protection.
- Photoplethysmography sensor miniaturization:Advanced optical heart rate monitoring enables continuous SpO2 tracking without fingertip contact, expanding use cases into sleep medicine and altitude training.
- China manufacturing scale:Domestic OEMs leverage Shenzhen component ecosystems and MIIT certification pathways to compress production cycles and dominate emerging market volume.
Market Restraints
- GB standards compliance costs:China's MIIT wireless transmission certifications and SAMR quality oversight impose multi-month approval timelines that filter substandard entrants but raise working capital requirements.
- Lithium-polymer cell volatility:Battery raw material price swings and concentrated cathode supply from specific geographies squeeze margin predictability for mid-tier manufacturers.
- Optical sensor accuracy ceilings:Skin tone variation and motion artifact interference limit heart rate precision during high-intensity interval training, constraining clinical credibility.
Strategic Opportunities
- FDA software-as-medical-device pathways:Evolving guidance on heart rate and blood oxygen feature classifications creates first-mover advantage for cleared clinical-grade configurations.
- Low-power Bluetooth SoC convergence:Nordic Semiconductor and Dialog platforms enable week-long battery life in sub-40mm form factors, opening pediatric and elderly monitoring segments.
- Direct-to-athlete subscription models:Bypassing retail channel markups through team and league bulk purchasing agreements captures recurring revenue from institutional buyers.
Industry Challenges
- FCC Part 15 certification timelines:Radio frequency emission testing for US market entry requires specialized test labs and 8-16 week documentation cycles that delay product launches.
- Biometric algorithm validation:Demonstrating clinical equivalence against predicate devices demands expensive third-party studies and statistical power calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sports Bracelet Market |
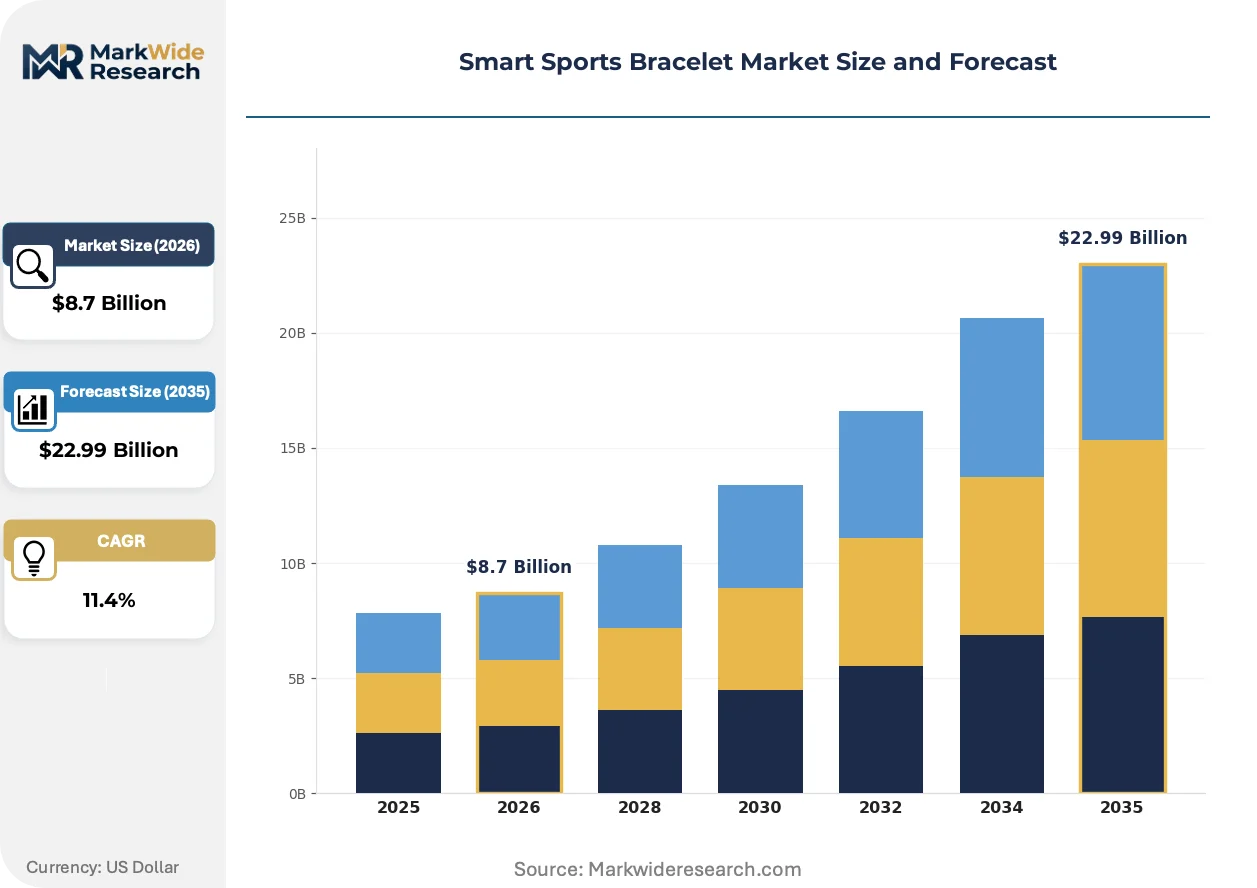
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracker, Smartwatch, Health Monitor, Activity Band Technology: Bluetooth, Wi-Fi, NFC, GPS End User: Athletes, Fitness Enthusiasts, Casual Users, Health-Conscious Individuals Feature: Heart Rate Monitoring, Sleep Tracking, GPS Functionality, Activity Recognition |
| Companies Covered | Apple, Samsung Electronics, Garmin, Fitbit, Alphabet, Huawei Technologies, Xiaomi Corporation, Zepp Health Corporation, Polar Electro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sports Bracelet Market Trends and Innovations
Multi-sport analytics platforms are compressing the feature gap between consumer fitness bands and dedicated GPS watches, forcing vendors to differentiate through proprietary health algorithms rather than hardware specifications alone.
Photoplethysmography is converging with accelerometer-based motion classification to enable real-time workout intensity adjustment without user input. Marathon training programs and CrossFit affiliates are adopting these auto-calibrating systems to reduce coaching labor. This sensor fusion is compressing the addressable market for standalone chest-strap heart rate monitors.
The EU AI Act's risk classification framework for biometric identification systems is reshaping product development roadmaps. Manufacturers must document algorithmic decision-making processes for features like stress scoring and recovery recommendations. Health monitor configurations with explicit clinical claims face heightened conformity assessment requirements under MDR Article II.
Institutional procurement through athletic departments and corporate wellness programs is displacing individual consumer purchases as the primary volume driver. Universities negotiate multi-year fleet deployments with centralized data dashboards. This channel shift concentrates buyer power and demands API interoperability with existing athlete management systems, visible most acutely in NCAA Division I programs and English Premier League academies.
Smart Sports Bracelet Market Segmentation
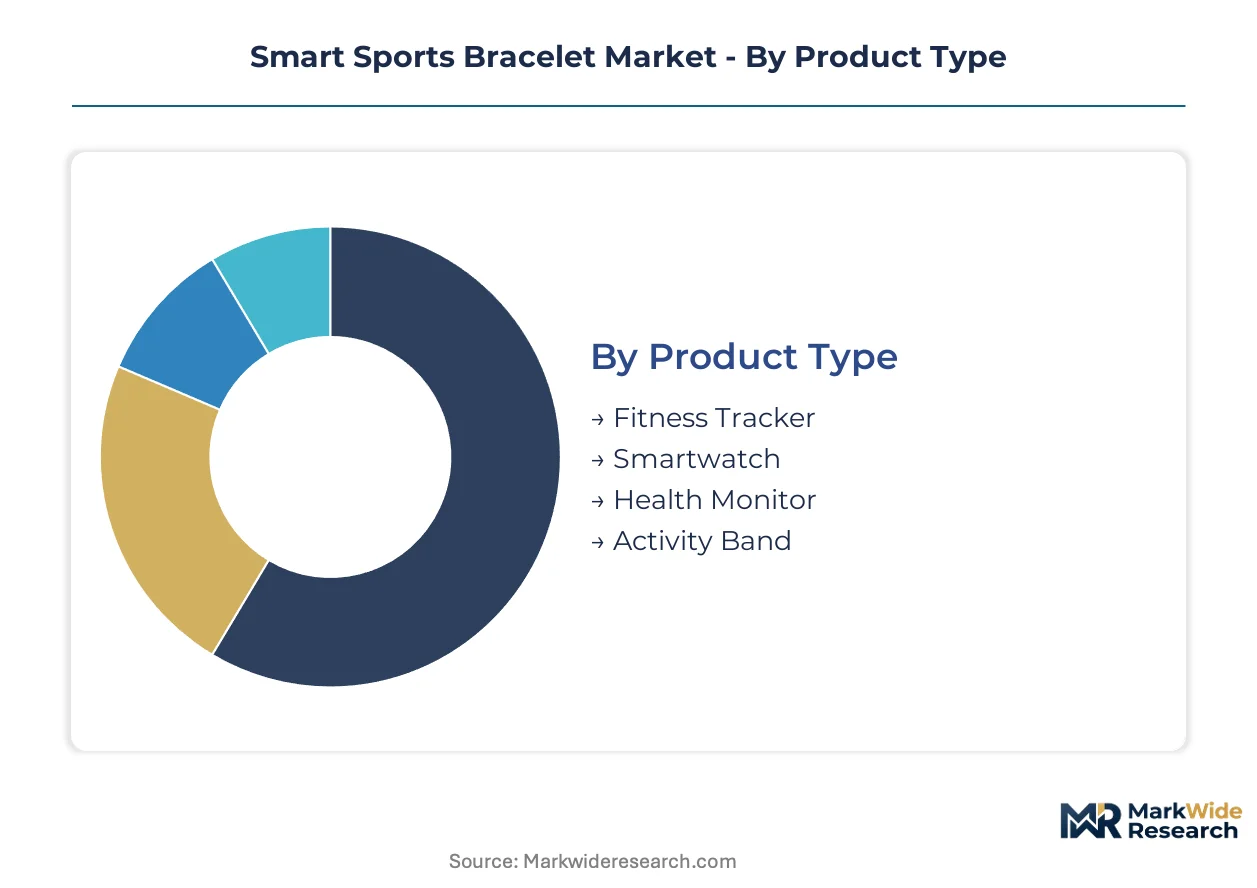
Segmentation in smart sports bracelets reveals how hardware specifications, connectivity protocols, and user profiles create divergent margin structures. Manufacturers must align sensor arrays and certification pathways with distinct procurement channels.
Product Type:
Form factor and sensor density define the technology axis across wrist-worn categories.
- Fitness Tracker:Streamlined accelerometer and basic photoplethysmography configurations dominate volume shipments through retail channels. Procurement concentrates in emerging markets where Xiaomi and domestic Chinese OEMs leverage Shenzhen manufacturing scale to compress price points below fifty dollars.
- Health Monitor:Clinical-grade sensor arrays with regulatory clearance requirements command margin concentration through institutional procurement. NCAA Division I athletic programs and English Premier League academies deploy these for longitudinal athlete monitoring, demanding API interoperability with existing management systems.
- Smartwatch:Full-featured platforms integrating cellular connectivity and third-party application ecosystems target premium consumer segments with extended replacement cycles.
- Activity Band:Minimalist form factors prioritize battery longevity and water resistance for swimming and sleep tracking use cases.
Mature deployment sits with Fitness Tracker. Newer deployment is concentrated in Health Monitor.
Technology:
Connectivity protocol selection determines power budgets, data throughput, and geographic certification requirements.
- GPS:Multi-constellation positioning modules from u-blox and MediaTek enable outdoor activity tracking without smartphone tethering. Demand climbs fastest in North American and European markets where trail running and cycling applications drive feature expectations.
- Bluetooth:Low-power SoC platforms from Nordic Semiconductor and Dialog enable week-long battery life in compact form factors. Pediatric and elderly monitoring segments adopt these configurations for continuous wear compliance.
- Wi-Fi:Direct cloud synchronization bypasses smartphone intermediaries for institutional fleet management scenarios.
- NFC:Contactless payment and access control integration targets corporate wellness program deployments with centralized provisioning.
Mature deployment sits with Bluetooth. Newer deployment is concentrated in GPS.
End User:
User sophistication and data utilization intensity separate consumer from institutional procurement channels.
- Athletes:Professional and collegiate competitors demand clinical-grade accuracy for load management and injury prevention protocols. Biometric data feeds directly into coaching workflows through centralized dashboards.
- Fitness Enthusiasts:Quantified-self practitioners drive subscription revenue for advanced analytics platforms and training program integrations.
- Casual Users:Step counting and basic notification features dominate this price-sensitive segment with high churn and low attachment rates.
- Health-Conscious Individuals:Preventive monitoring applications including sleep medicine and stress scoring attract older demographics with chronic condition management needs.
Mature deployment sits with Casual Users. Newer deployment is concentrated in Athletes.
Feature:
Sensor fusion capabilities determine competitive differentiation as hardware commoditizes.
- Heart Rate Monitoring:Photoplethysmography miniaturization enables continuous SpO2 tracking without fingertip contact. Skin tone variation and motion artifact interference during high-intensity interval training constrain clinical credibility and algorithm validation costs.
- GPS Functionality:Multi-band positioning with Galileo and BeiDou support expands addressable use cases into backcountry navigation and geofenced safety applications for endurance events.
- Sleep Tracking:Accelerometer-derived sleep staging combined with heart rate variability metrics targets wellness program differentiation.
- Activity Recognition:Machine learning classification of motion patterns enables automatic workout logging without user input, reducing coaching labor in CrossFit and marathon training contexts.
Mature deployment sits with Heart Rate Monitoring. Newer deployment is concentrated in GPS Functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's component ecosystem anchors manufacturing capacity for photoplethysmography sensors and low-power Bluetooth SoCs that feed assembly lines worldwide. Raw material concentration in China's Pearl River Delta compresses production cycles for domestic OEMs targeting emerging market volume.
United States
NCAA Division I athletic programs and professional sports franchises drive institutional procurement of clinical-grade wearables with API interoperability requirements. FDA software-as-medical-device guidance shapes product roadmaps for heart rate and blood oxygen features. Greater Boston's medtech cluster hosts validation laboratories conducting third-party equivalence studies for algorithm clearance.
Germany
Endurance athletes and corporate wellness programs demand multi-sport analytics with Galileo GPS integration and extended battery specifications. EU AI Act risk classification mandates documentation for stress-scoring algorithms under biometric identification rules. Baden-Württemberg's precision engineering corridor supplies u-blox positioning modules for outdoor activity tracking.
China
Domestic OEMs leverage MIIT certification pathways and SAMR quality oversight to compress approval timelines for GB standards compliance. Shenzhen's manufacturing scale dominates fitness tracker volume shipments through ecosystem pricing strategies. Beijing-Tianjin-Hebei corridor concentrates health monitor development targeting collegiate athletic program exports.
Japan
Aging demographics and preventive monitoring applications expand demand for sleep staging and heart rate variability metrics in compact form factors. METI standards coordination aligns Bluetooth SoC certification with domestic radio equipment regulations. Kansai region's electronics fabricators specialize in accelerometer miniaturization for elderly continuous-wear compliance.
South Korea
Corporate wellness deployments and direct-to-athlete subscription models concentrate procurement through chaebol-affiliated health platforms. MFDS medical device classification guidance influences regulatory strategy for clinical-grade sensor arrays. Seoul Capital Area's semiconductor foundries produce Nordic-compatible low-power transceivers for week-long battery configurations.
Smart Sports Bracelet Market Competitive Landscape
Global majors compete with regional champions across certification pathways and distribution channels, producing a tiered structure where vertical integration separates premium positioning from scale-driven volume plays. The vendor base clusters around three strategic archetypes: silicon-to-services integrators, specialized GPS analytics providers, and ecosystem-priced manufacturers. Consolidation pressure manifests through strategic partnerships for algorithm licensing and geographic expansion into institutional procurement channels.
Within the premium-tier vector, Apple exemplifies silicon-to-services vertical integration through captive sensor design and health platform control. Garmin occupies a position among specialized endurance analytics providers, while Xiaomi Corporation represents ecosystem-priced manufacturing scale. These three anchors illustrate how competitive positioning diverges across certification grade, feature density, and channel strategy.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Garmin |
| Fitbit |
| Alphabet |
| Huawei Technologies |
| Xiaomi Corporation |
| Zepp Health Corporation |
| Polar Electro |
| Others |
Pricing and Supply Chain Analysis
Institutional buyers in collegiate athletic programs and corporate wellness fleets command volume-based contract structures that compress unit economics for mid-tier manufacturers while rewarding certified health monitor configurations with premium positioning. Shenzhen's component ecosystem feeds this procurement concentration through ecosystem pricing strategies that stratify across certification grade tiers.
Pricing Analysis
Warranty and algorithm update bundling separates premium health monitor configurations from unbundled fitness tracker tiers where after-sales service remains minimal. Three-tier pricing structure across premium, standard, and economy levels tracks FDA clearance status, MIIT certification pathways, and enterprise API integration depth. Cost compression in the fitness tracker tier intensifies because Xiaomi and domestic Chinese OEMs leverage manufacturing scale to compress price points below fifty dollars. Casual users exhibit highest price sensitivity while NCAA Division I programs and English Premier League academies demonstrate lowest sensitivity due to centralized procurement budgets.
Supply Chain Analysis
Photoplethysmography sensor supply rests on Taiwanese optical component specialists and Japanese precision optics fabricators, with Nordic Semiconductor and Dialog anchoring low-power Bluetooth SoC production. Lithium-polymer cell supply draws from South Korean cathode material producers and Chinese electrolyte formulators, creating concentrated dependency on Pearl River Delta assembly integration. Single-source vulnerability in advanced biometric sensor arrays exposes manufacturers to allocation risk during capacity crunches. Distribution runs through direct-to-athlete subscription channels and retail electronics chains, with institutional fleet procurement bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
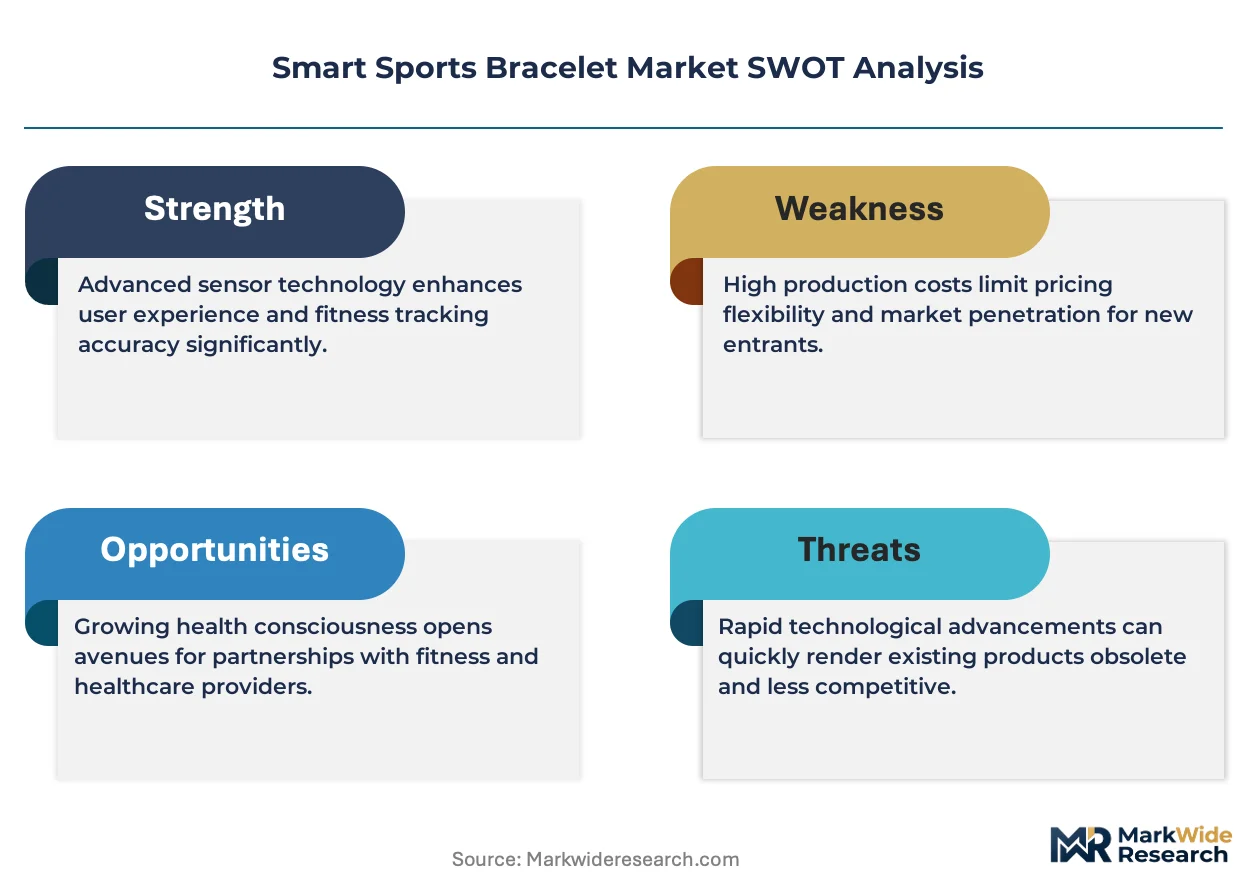
The smart sports bracelet market has become a vertical-integration race where captive silicon design and proprietary health algorithm development separate premium positioning from commodity volume plays. Players are pursuing upstream control over photoplethysmography sensor arrays to defend margin concentration.
For Market Incumbents: Deepen backward integration into optical sensor design and health platform infrastructure to defend against ecosystem-priced manufacturers eroding fitness tracker margins. Prioritize FDA software-as-medical-device clearance investment to capture institutional procurement concentration in collegiate athletic programs. Fortify API interoperability with existing athlete management systems to lock in multi-year fleet deployments. For New Entrants and Emerging Players: Direct-to-athlete digital subscription routes offer lowest customer acquisition cost entry into the health-conscious elderly segment where pediatric and geriatric monitoring applications remain underpenetrated. Target sleep medicine and stress scoring configurations for preventive monitoring demand in aging demographics. Pursue white-label manufacturing partnerships with Shenzhen OEMs to compress production cycles before establishing proprietary certification pathways. For Investors and Strategic Acquirers: The window for entry favors algorithm-specialist firms with validated biometric equivalence studies against predicate devices. Long-term viability hinges on regulatory clearance moats and institutional channel relationships rather than consumer brand recognition. Watch FDA guidance evolution on heart rate and blood oxygen feature classifications as the inflection indicator for clinical-grade configuration valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Regulatory clearance unlocks institutional procurement from NCAA Division I programs and professional sports franchises. |
| Photoplethysmography Sensor Backward Integration | In-house optical component production reduces dependency on Taiwanese and Japanese specialty suppliers. |
| API Interoperability Partnership | Integration with athlete management systems secures multi-year fleet deployment contracts. |
| Low-Power Bluetooth SoC Platform Migration | Nordic Semiconductor and Dialog platforms enable week-long battery life for pediatric and elderly segments. |
| Direct-to-Athlete Subscription Launch | Bypassing retail channel markups captures recurring revenue from team and league bulk purchasing agreements. |
Research Methodology
Multi-period observation of MIIT certification timelines, FDA guidance evolution, and institutional procurement patterns anchored the trend analysis, supplemented by interviews with wearable device engineering directors, collegiate athletic program procurement officers, and health platform product managers. Primary fieldwork combined with secondary validation against FCC filing databases, EU MDR conformity assessment records, and SAMR quality oversight disclosures. Bottom-up shipment estimates by product type and technology tier triangulated against top-down market value reconstruction across the analysis window.
Segment-weighting approaches distributed value concentration across fitness tracker, health monitor, smartwatch, and activity band configurations while modeling technology adoption curves for GPS, Bluetooth, Wi-Fi, and NFC connectivity protocols. CAGRs derived from logistic diffusion curves fitted to historical penetration data and institutional buyer survey responses. Forecast inputs incorporated photoplethysmography sensor miniaturization trajectories and low-power Bluetooth SoC platform development roadmaps throughout the projection horizon.
The model holds under stable regulatory classification of heart rate and blood oxygen features; deviation in FDA software-as-medical-device reclassification or EU AI Act biometric identification enforcement would shift volume toward cleared clinical-grade configurations. Forecasts reflect documented assumptions regarding Shenzhen manufacturing scale sustainability and lithium-polymer cell supply continuity. A small set of named triggers—regulatory reclassification, component allocation crunches, and institutional procurement budget cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Wearable Motion Sensors Market